
 Vietnam Retail Market | 2026-2036
Vietnam Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Retail Market Outlook
Young retail talent fluent in digital merchandising and data analytics is bifurcating the competitive landscape between legacy operators and agile newcomers. Circle K leverages its convenience store density to anchor urban foot traffic in Hanoi and Ho Chi Minh City. Bach Hoa Xanh sustains aggressive provincial expansion through vertically owned distribution centers. Central Retail Vietnam competes by dominating mall-based formats and premium grocery positioning.
Vietnam retail encompasses the sale of finished consumer goods through physical and digital channels, spanning product categories from perishables to durables, with inventory turnover and shelf-life management as critical operational parameters. The sector serves household consumption, tourism procurement, and B2B resale across a population of roughly one hundred million. Grocery and convenience store formats capture the deepest margin pools due to repeat purchase frequency and private-label penetration. Electronics and apparel segments lead online growth velocity, driven by platform-native Gen Z and millennial buyers. Traditional markets retain volume leadership in rural provinces but face structural displacement from organized modern trade.
Vietnam's Ministry of Industry and Trade enforces e-commerce licensing and foreign investment caps in retail, while the Competition and Consumer Protection Authority monitors anti-competitive conduct among dominant chains. BIS-aligned product safety standards and local food hygiene regulations shape import and domestic sourcing requirements for grocery operators. Stakeholders must monitor regulatory enforcement intensity around data localization and cross-border platform taxation as these rules will determine capital allocation between pure-play digital and hybrid omnichannel models.
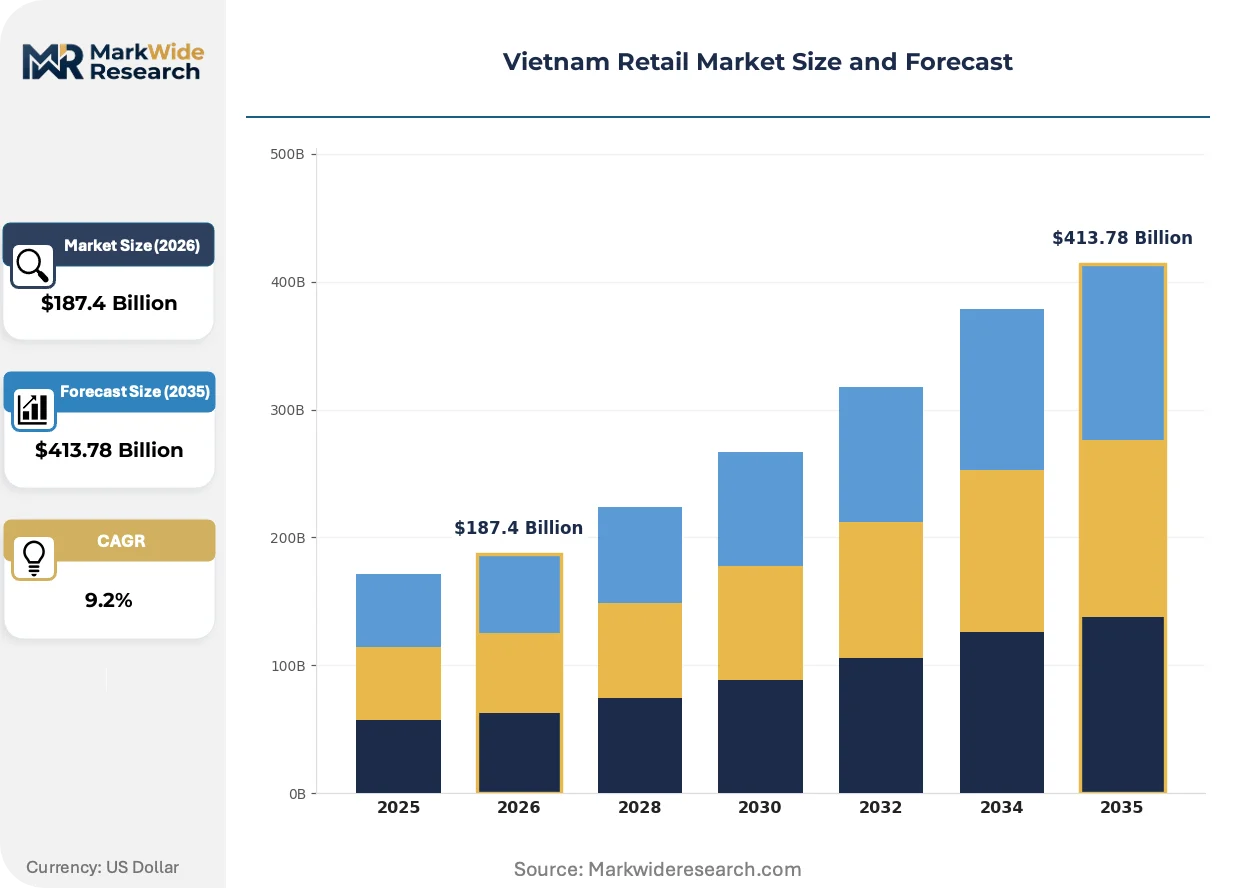
Market Dynamics
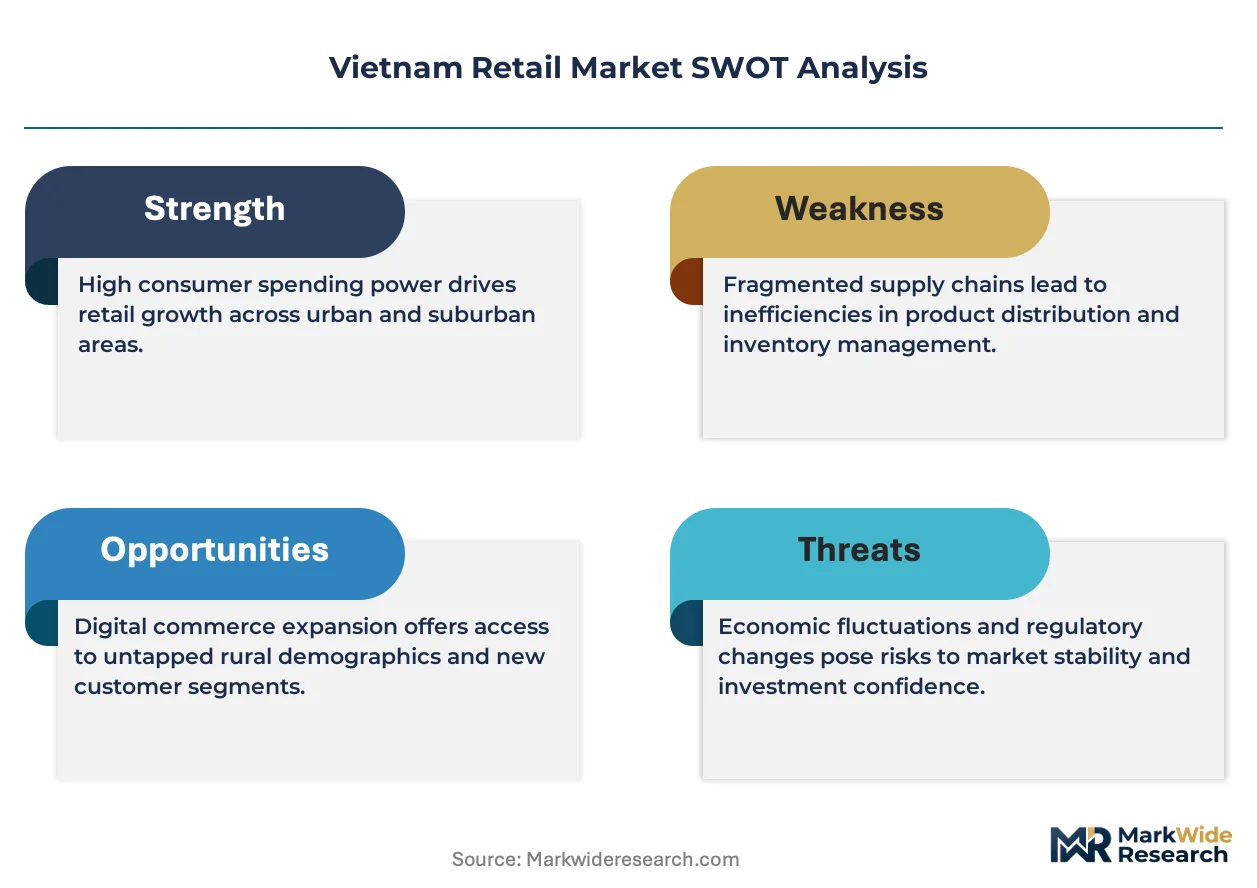
The Vietnam retail sector is restructuring around last-mile logistics density as foreign and domestic operators race to secure urban real estate and provincial distribution nodes before regulatory caps on store expansion tighten.
Growth Catalysts
- Revised Competition Law enforcement:Vietnam's Competition and Consumer Protection Authority is accelerating clearance timelines for multi-format retail investments, reducing entry friction for organized modern trade operators.
- Provincial income convergence:Household consumption clusters in secondary cities like Da Nang, Can Tho, and Hai Phong are reaching inflection points for convenience store penetration.
- QR-code payment infrastructure:Real-time settlement networks from domestic fintech platforms are collapsing cash-handling costs for small-format grocery operators.
Market Restraints
- Prime commercial rent inflation:District 1 and District 3 in Ho Chi Minh City, plus Hoan Kiem and Dong Da in Hanoi, are seeing lease renewal premiums that compress net operating margins for convenience chains.
- Fresh produce supply fragmentation:Mekong Delta sourcing networks remain dominated by unconsolidated agricultural cooperatives, creating quality inconsistency and spoilage risk for grocery private-label programs.
- Cross-border e-commerce taxation uncertainty:Vietnam's Ministry of Finance has signaled pending duties on platform-facilitated imports, creating inventory planning paralysis for hybrid omnichannel retailers.
Strategic Opportunities
- Central Highlands underpenetration:Gia Lai and Dak Lak provinces host growing urban populations with minimal modern trade presence, offering first-mover positioning for provincial distribution center investments.
- Regulatory sandbox for drone delivery:Vietnam's Ministry of Transport is piloting beyond-visual-line-of-sight permits for last-mile logistics, potentially unlocking rural grocery replenishment at cost points below road-based fleets.
- Livestream-commerce integration:Convergence of short-video platforms with embedded checkout is creating native demand generation channels that bypass traditional search-based e-commerce economics.
Industry Challenges
- Cold-chain engineering talent scarcity:Vietnam's technical universities produce insufficient refrigeration systems specialists for the aggressive expansion of fresh-format grocery networks into tropical climates.
- Legacy POS integration friction:Traditional market vendors transitioning to organized trade face data migration complexity when connecting inventory management systems to national retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Retail Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $413.78 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Grocery, Home Goods Customer Type: Millennials, Gen Z, Families, Seniors Distribution Channel: Online, Supermarkets, Convenience Stores, Traditional Markets Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Circle K, Aeon Maxvalu, WinMart+, Big C Supercenter, MegaMarket, Bach Hoa Xanh, GS25, Central Retail Vietnam, Co.op Food, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Retail Market Strategic Shifts
Retail technology deployment in Vietnam is splitting between capital-intensive automation at the fulfillment layer and lightweight digital tools at the storefront, creating divergent investment profiles across operator scale tiers.
AI-powered demand forecasting is bifurcating inventory performance between early adopters and legacy operators. Bach Hoa Xanh and Circle K Vietnam have deployed machine learning models for perishable shrink reduction, while traditional market wholesalers still rely on manual reorder triggers. This capability gap is compressing margin structures for operators without real-time sales velocity data.
Vietnam's revised e-commerce regulatory framework is mandating data localization for cross-border platforms and tightening foreign investment notification thresholds. The Ministry of Industry and Trade is enforcing licensing requirements for marketplace operators with annual transaction volumes above specified thresholds. Domestic grocery chains with captive app ecosystems are accelerating first-party data strategies to preempt compliance disruption.
Urban Vietnamese consumers are consolidating weekly shopping trips into fewer, larger-format visits while supplementing with micro-fulfillment for immediate needs. Convenience stores in Ho Chi Minh City and Hanoi are repositioning as pickup nodes for online grocery orders rather than pure impulse-purchase destinations. This behavioral pivot is most visible among dual-income households in Thu Duc City and Tay Ho District, where time scarcity overrides price sensitivity for staple replenishment.
Vietnam Retail Market Segmentation
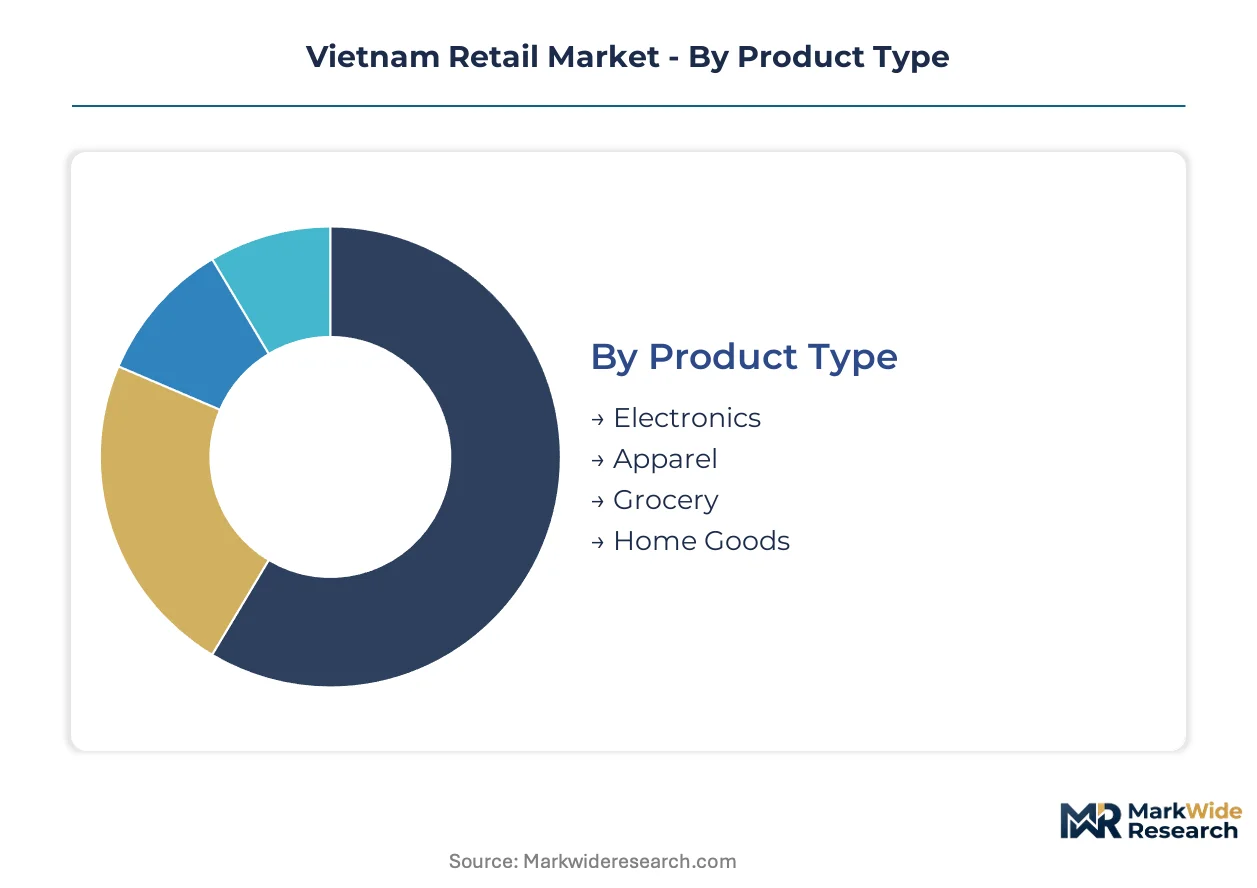
Vietnam's retail segmentation reflects a market bifurcated between urban modern trade expansion and persistent traditional channel dominance. Understanding these divides enables operators to align format investments with actual consumption patterns rather than assumed modernization trajectories.
Product Type:
Grocery anchors domestic volume, while electronics and apparel concentrate in export-adjacent urban corridors with higher disposable income penetration.
- Grocery:Perishables and packaged staples dominate transaction frequency, with fresh produce commanding the highest inventory velocity. Demand clusters in Ho Chi Minh City and Hanoi's dense urban districts where dual-income households prioritize convenience over price for daily replenishment.
- Electronics:Smartphones and small appliances lead category value, driven by platform-native Gen Z buyers seeking specification transparency. Urban millennials in Thu Duc City and Tay Ho District drive replacement cycles through embedded-finance checkout options.
- Apparel:Fast fashion and sportswear segments respond to social commerce discovery mechanics, with livestream commerce collapsing traditional seasonal buying patterns.
- Home Goods:Furniture and kitchenware purchases concentrate around life-event triggers, with online penetration lagging other categories due to tactile evaluation requirements.
Grocery commands the established base. The steepest expansion runs through electronics.
Customer Type:
Generational divides in digital fluency are reshaping channel preference faster than income stratification alone would predict.
- Gen Z:Platform-native buyers born after 1997, exhibiting lowest loyalty to any single retail format and highest responsiveness to influencer-curated discovery. Short-video commerce in Ho Chi Minh City captures their discretionary spending before traditional brand awareness forms.
- Millennials:Dual-income households aged 28-43 consolidating weekly shopping into fewer, larger-format trips while supplementing via convenience store pickup nodes. Time scarcity in Hanoi's Dong Da District overrides price sensitivity for staple categories.
- Families:Multi-generational purchasing units balancing bulk value with quality assurance for infant and elderly nutrition. Provincial cities like Can Tho and Da Nang show rising modern trade penetration as household structures urbanize.
- Seniors:Traditional market loyalty persists strongest in this cohort, though QR-code payment adoption in Hanoi and Ho Chi Minh City is collapsing prior digital exclusion barriers.
Millennials anchor current revenue concentration. Gen Z is gaining share fastest among discretionary categories.
Distribution Channel:
Channel economics diverge sharply between capital-intensive last-mile networks and low-fixed-cost traditional infrastructure.
- Convenience Stores:Small-format urban outlets repositioning as micro-fulfillment nodes for online grocery pickup. Prime location scarcity in District 1 and Hoan Kiem is inflating lease premiums and compressing operator margins.
- Online:Platform-facilitated commerce spanning marketplace aggregators and captive retailer apps. Cross-border taxation uncertainty from Vietnam's Ministry of Finance is creating inventory planning paralysis for hybrid operators.
- Supermarkets:Large-format destinations for consolidated weekly shopping trips, with private-label penetration deepest in grocery categories. Provincial expansion into Gia Lai and Dak Lak offers first-mover positioning.
- Traditional Markets:Unconsolidated vendor networks retaining volume leadership in rural provinces, facing structural displacement as modern trade logistics networks deepen.
Traditional markets retain the volume base. Convenience stores are climbing the fastest as urban pickup infrastructure scales.
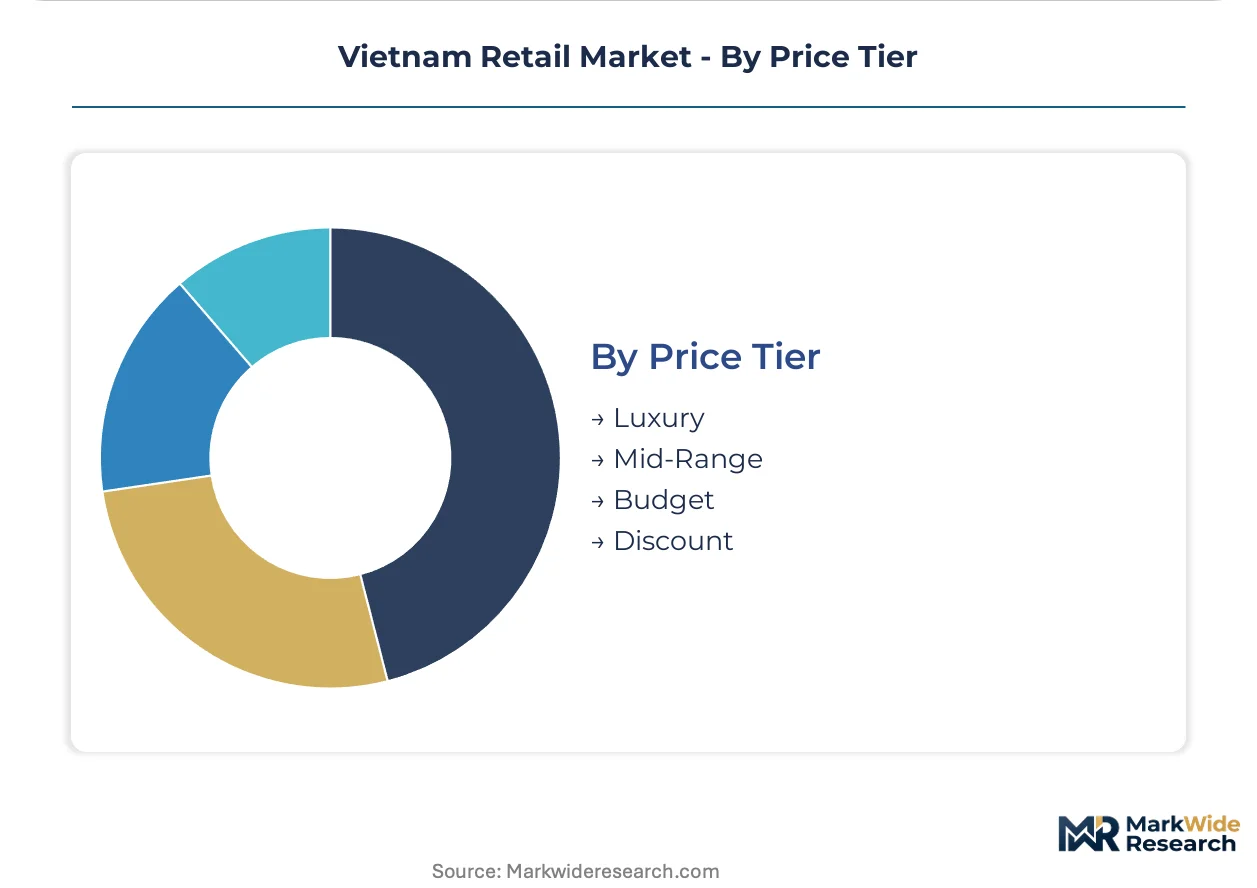
Price Tier:
Pricing stratification aligns with distribution channel density rather than pure income segmentation.
- Budget:Value-focused positioning targeting price-sensitive households in secondary cities and rural provinces. Traditional market vendors and discount chains compete on staple commodity pricing with minimal service overlay.
- Mid-Range:Largest addressable segment spanning organized modern trade and emerging private-label penetration. Bach Hoa Xanh and comparable chains dominate this tier through vertically owned distribution center cost control.
- Luxury:Premium positioning concentrated in mall-based formats and flagship districts, with Central Retail Vietnam competing through experiential retail and exclusive brand partnerships.
- Discount:Hard-discounter models with limited SKU count and extreme cost discipline, expanding most aggressively in peri-urban corridors where land costs permit larger footprint economics.
Mid-Range captures the established revenue base. Discount is expanding most quickly as provincial income convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Industry and Trade anchors retail governance through e-commerce licensing frameworks and foreign investment notification thresholds. The Competition and Consumer Protection Authority monitors clearance timelines for multi-format retail investments across the country's urban corridors.
Ho Chi Minh City
Dual-income households in Thu Duc City and District 7 drive convenience store penetration for immediate replenishment needs. The city's Department of Industry and Trade enforces food hygiene regulations for modern trade operators expanding fresh-format grocery networks. District 1 and District 3 host the densest concentration of international convenience chains competing for prime commercial real estate.
Hanoi
Young urban professionals in Tay Ho District and Dong Da District consolidate weekly shopping into fewer, larger-format trips supplemented by micro-fulfillment. The municipal People's Committee coordinates with national regulators on QR-code payment infrastructure deployment across traditional market vendors. Hoan Kiem District anchors luxury mall-based formats while suburban districts see aggressive discount chain expansion.
Da Nang
Household consumption clusters in this secondary city have reached inflection points for organized modern trade penetration. The Da Nang Department of Planning and Investment facilitates provincial distribution center investments through streamlined foreign enterprise registration. The city bridges northern and southern logistics networks, attracting regional fulfillment hub positioning.
Can Tho
Multi-generational purchasing units in this Mekong Delta hub balance bulk value with quality assurance for fresh produce procurement. The Can Tho People's Committee administers agricultural cooperative coordination programs affecting grocery private-label sourcing networks. Urbanizing household structures in Ninh Kieu District drive modern trade displacement of traditional market volume.
Hai Phong
Industrial zone workers and port-adjacent populations create concentrated demand for mid-range grocery positioning. The Hai Phong Economic Zone Authority offers investment incentives for cold-chain infrastructure supporting fresh-format retail expansion. Le Chan District and Hong Bang District host emerging convenience store density competing with traditional market legacy vendors.
Vietnam Retail Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Vietnam's retail sector. The market structures around three tiers: international convenience chains with dense urban footprints, domestic grocery operators with vertically owned distribution networks, and hybrid omnichannel retailers building captive app ecosystems. Two dominant competitive moves define current positioning: aggressive provincial expansion through distribution center investments, and livestream-commerce integration bypassing traditional search-based e-commerce economics.
Within the international convenience tier, Circle K and GS25 anchor urban foot traffic capture through small-format density in Hanoi and Ho Chi Minh City. Among domestic grocery specialists, Bach Hoa Xanh exemplifies cost leadership through provincial distribution center vertical integration. Central Retail Vietnam occupies a position bridging mall-based premium formats with experiential retail positioning. These three players represent the archetype spectrum from foreign convenience density to domestic supply chain control to hybrid premium positioning.
| Leading Market Players |
|---|
| Circle K |
| Aeon Maxvalu |
| WinMart+ |
| Big C Supercenter |
| MegaMarket |
| Bach Hoa Xanh |
| GS25 |
| Central Retail Vietnam |
| Co.op Food |
| Others |
Value Chain & Pricing Dynamics
Vietnam's Ministry of Industry and Trade e-commerce licensing framework gates both supplier qualification and price differentiation simultaneously, as operators without compliant data localization infrastructure face exclusion from mid-range and premium tier positioning while budget players absorb compliance costs through margin compression.
Pricing Analysis
Lease renewal premiums in Ho Chi Minh City's District 1 and Hanoi's Hoan Kiem District diverge sharply from provincial corridors, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on location density and private-label penetration depth, with urban convenience chains commanding brand premiums over traditional market vendors. Cost compression in the budget tier intensifies because unconsolidated Mekong Delta sourcing networks force quality inconsistency discounts. Traditional market vendors exhibit highest price sensitivity, while dual-income households in Thu Duc City show least sensitivity for time-convenience tradeoffs.
Supply Chain Analysis
Inventory strategy across Vietnam retail favors strategic stockpiling for perishables through vertically owned distribution centers, contrasting with just-in-time approaches for packaged staples. Geographic supply concentration draws from China for electronics components, Thailand for processed food inputs, and domestic Mekong Delta agricultural cooperatives for fresh produce. Raw material dependencies center on imported refrigeration equipment, cross-border packaging materials, and unconsolidated vegetable and seafood sourcing. Single-source vulnerability runs through cold-chain engineering talent scarcity for tropical climate operations. Distribution runs through provincial hub-and-spoke networks anchored by Bach Hoa Xanh and comparable domestic operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam retail incumbents face substitution defense imperatives as livestream-commerce platforms disintermediate traditional search-based e-commerce economics and capture Gen Z discretionary spending before brand loyalty forms.
For Market Incumbents: Compound format density in provincial corridors before regulatory caps on store expansion tighten, securing Gia Lai and Dak Lak distribution center positioning ahead of competitor land-banking. Deepen backward integration into Mekong Delta agricultural cooperatives to reduce fresh produce quality inconsistency and spoilage risk. Channel control through captive app ecosystems preempts data localization compliance disruption from cross-border platform taxation uncertainty. For New Entrants and Emerging Players: Differentiate on drone delivery infrastructure by securing beyond-visual-line-of-sight permits from Vietnam's Ministry of Transport for Central Highlands rural replenishment at cost points below road-based fleets. Target the underpenetrated Central Highlands provinces where urban populations grow with minimal modern trade presence. Go-to-market angle: livestream-commerce integration with embedded checkout bypassing traditional search-based platform economics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-chain infrastructure as tropical climate expansion demands refrigeration systems specialization that Vietnam's technical universities cannot supply. Long-term viability favors operators with captive distribution center networks and first-party data strategies. Acquisition target archetype: domestic grocery chains with provincial hub positioning and compliant data localization infrastructure. Signal to watch: clearance timeline acceleration from the Competition and Consumer Protection Authority for multi-format retail investments.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Distribution Center Expansion | Captures Gia Lai and Dak Lak first-mover positioning before competitor land-banking accelerates. |
| Livestream-Commerce Platform Integration | Bypasses traditional search-based e-commerce economics by converging short-video discovery with embedded checkout. |
| Cold-Chain Infrastructure Investment | Addresses engineering talent scarcity for tropical climate fresh-format grocery network expansion. |
| Captive App Ecosystem Development | Preempts data localization compliance disruption from Ministry of Industry and Trade enforcement. |
| Backward Integration into Agricultural Cooperatives | Reduces Mekong Delta sourcing fragmentation and quality inconsistency for private-label programs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with retail operations directors, category buyers at domestic chains, convenience store franchise managers, and provincial distribution center planners; and secondary validation against customs records, Nielsen retail audit data, Ministry of Industry and Trade e-commerce licensing disclosures, and Competition and Consumer Protection Authority clearance filings. Bottom-up store count and transaction velocity estimates triangulated against top-down household consumption expenditure patterns.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, customer generation, distribution channel format, and price tier positioning. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and provincial income convergence patterns. Industry-specific forecast inputs incorporated QR-code payment infrastructure deployment rates and livestream-commerce platform transaction volume growth.
The analysis sits within stated boundaries; outcomes outside sustained provincial income convergence or stable cross-border e-commerce taxation policy would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cold-chain engineering talent pipeline expansion. Revision becomes warranted when Competition and Consumer Protection Authority clearance timelines or Ministry of Finance cross-border platform duty signals cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
In Store Signage Market
Retailing
Home Shopping Market
Retailing
Philippines Retail Industry Market
Retailing
Consumer Shopping Cart Market
Retailing
Retail Vending Machine Market
Retailing
Out Store Signage Market
Retailing
Australia Retail Bags Market
Retailing
Department Stores Market
Retailing
European Discount Retail Market
Retailing
North America Retail Vending Machine Market
Retailing
Floor Displays Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Retail Signage Market
Retailing
Subscription Box Market
Retailing
Consumer Products and Retail Market
Retailing
Thailand Retail Market