
 Home Shopping Market | 2026-2036
Home Shopping Market Size, Share, and Industry Trends Forecast 2026-2036
Home Shopping Market Intelligence
Aftermarket service revenue from installation and assembly support is reconfiguring margin pools away from pure product transactions in the home shopping sector. Amazon leverages its logistics infrastructure to control same-day delivery expectations across metropolitan zones. IKEA anchors its competitive position through in-house production of flat-pack systems that reduce last-mile costs. Walmart sustains volume leadership by dominating grocery-integrated basket expansion in suburban markets.
Home shopping encompasses the retail distribution of consumer goods through remote ordering mechanisms, including broadcast television, internet-based storefronts, printed catalogs, and mobile software applications, with order fulfillment executed via parcel carriers, digital download, or retail location collection. The primary commercial purpose centers on eliminating geographic and temporal constraints between product discovery and purchase completion, thereby expanding addressable consumer bases beyond physical store catchment areas. Electronics and home goods product categories capture disproportionate margin contribution due to higher average selling prices and attachment revenue from protection plans. Online and mobile app sales channels represent the fastest-expanding demand vectors as smartphone penetration and one-click payment infrastructure mature across consumer demographics.
The US Federal Trade Commission enforces advertising substantiation standards that govern product claims made through televised and digital home shopping formats, while the EU Digital Services Act imposes transparency obligations on algorithmic product recommendations that affect cross-border purchasing flows. China's State Administration for Market Regulation oversees livestream commerce host accountability and refund mechanisms that shape platform operating requirements. Stakeholders must monitor evolving platform liability frameworks as regulators distinguish between marketplace intermediaries and direct retailers in enforcement actions.
Market Dynamics
Livestream commerce infrastructure is compressing purchase cycles from discovery to checkout, eliminating the traditional catalog-to-warehouse lag that defined prior home shopping eras.
Growth Catalysts
- EU Digital Services Act transparency mandates:Algorithmic disclosure requirements are forcing platform operators to document recommendation logic, reducing consumer friction in cross-border transactions and building purchase confidence.
- One-click payment tokenization:Biometric authentication integration across mobile wallets is collapsing checkout abandonment rates among smartphone-native demographics.
- China's tier-one city density:Social commerce penetration in Beijing, Shanghai, and Shenzhen has created reference markets where livestream conversion benchmarks now shape global platform feature roadmaps.
Market Restraints
- Last-mile labor cost inflation:Parcel carrier wage pressures in Germany and the United Kingdom are eroding margin structures for bulky home goods categories that resist automation.
- GDPR compliance architecture:Data localization and consent management tooling imposes fixed operational overhead that disadvantages smaller marketplace entrants against scaled incumbents.
- Return logistics density:High apparel and electronics return rates in the United States require dedicated reverse supply chain capacity that consumes warehouse square footage.
Strategic Opportunities
- India's tier-two and tier-three urbanization:Vernacular-language livestream hosts are unlocking first-time e-commerce adoption in cities like Jaipur, Lucknow, and Indore where English-dominant platforms historically underperformed.
- Extended producer responsibility frameworks:France's AGEC law and similar EU packaging mandates are creating competitive differentiation for platforms that pre-integrate take-back and recycling logistics.
- Augmented reality furniture placement:Spatial computing integration between mobile cameras and 3D product models is collapsing the imagination gap that historically suppressed online furniture conversion.
Industry Challenges
- Livestream host talent scarcity:Platforms in Brazil and Mexico report acute shortages of bilingual hosts capable of sustaining engagement across Portuguese and Spanish audiences simultaneously.
- Cross-border VAT complexity:The EU's One-Stop-Shop mechanism and divergent national digital services tax regimes create reconciliation overhead that delays settlement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Shopping Market |
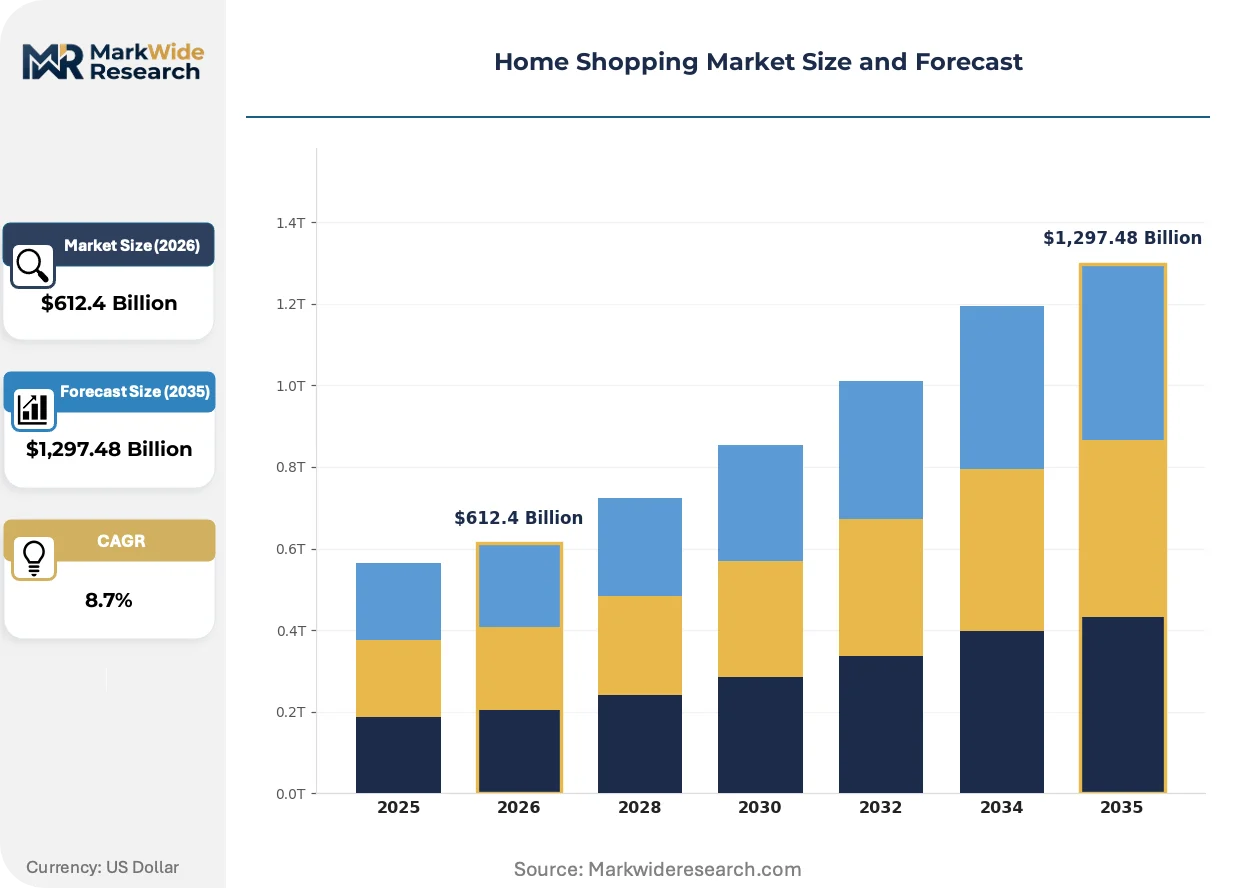
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Apparel, Home Goods, Beauty Products Sales Channel: Television, Online, Catalogs, Mobile Apps Customer Type: Retail Consumers, Wholesale Buyers, Business Clients, Resellers Delivery Method: Standard Shipping, Expedited Shipping, In-Store Pickup, Digital Delivery |
| Companies Covered | Home Depot, IKEA, Amazon, Lowe’s, Target, Walmart, Costco, TJX Companies, Wayfair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Shopping Market Strategic Shifts & Innovations
Generative AI is inserting itself between product catalogs and consumer eyeballs, replacing static taxonomy browsing with conversational discovery that rewrites how inventory surfaces to intent.
Visual search technology trained on home décor image corpora is rendering obsolete text-based query interfaces for furniture and appliance categories. Millennial and Gen Z shoppers in South Korea and the United States now initiate purchase journeys through screenshot uploads rather than keyword entry. This behavioral shift is compressing search-to-transaction latency and privileging platforms with proprietary visual embedding databases.
China's State Administration for Market Regulation issued binding accountability rules for livestream commerce hosts in 2023, extending platform liability to individual influencers for product claims. The regulation forces cross-border sellers using Chinese livestream infrastructure to maintain localized legal representation and escrow mechanisms. Electronics and cosmetics categories face the steepest compliance ramps as host liability attaches to safety substantiation.
Subscription-based replenishment models for consumable home goods are displacing one-off promotional buying in the United Kingdom and Germany. Amazon's Subscribe and Save and similar programs capture pantry and cleaning product demand through predictive algorithms that anticipate depletion cycles. This pattern concentrates volume with platforms possessing sufficient purchase history density to forecast household consumption curves accurately.
Home Shopping Market Segmentation
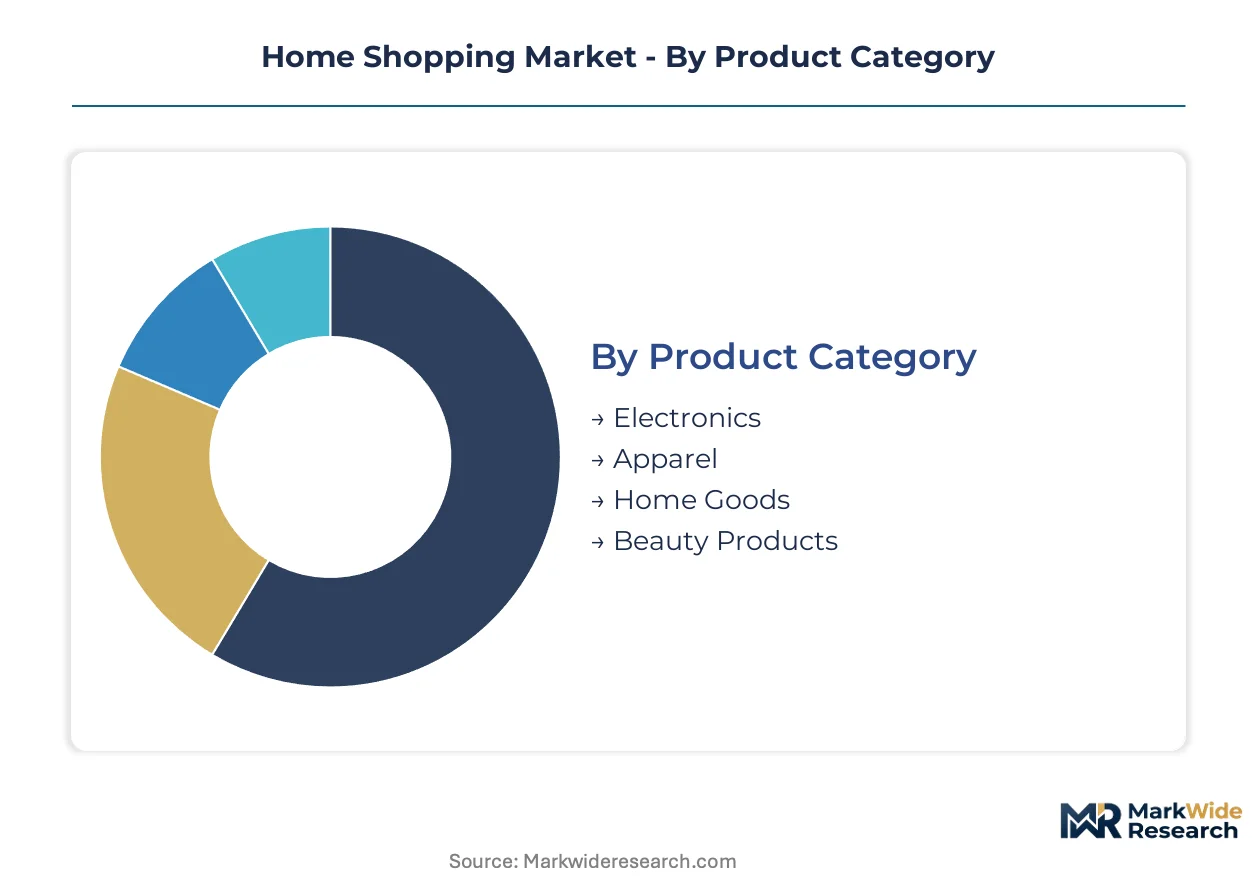
Segmentation in home shopping determines which inventory turns fastest and where capital gets trapped in slow-moving stock. Electronics and apparel rotate through fulfillment centers at radically different velocities than furniture or beauty products.
Product Category:
Electronics compress purchase cycles to hours while home goods stretch inventory exposure across seasons.
- Electronics:Smartphones, laptops, and wearable devices carry high average selling prices with attachment revenue from protection plans. Demand concentrates in China's tier-one cities where livestream hosts demonstrate product functionality in real-time, though return rates for electronics in the United States consume dedicated reverse logistics capacity.
- Apparel:Fashion and accessories categories face the steepest return density in the home shopping sector, particularly for size-dependent items ordered without physical trial. Demand clusters with millennial and Gen Z consumers in South Korea and the United States who initiate searches through screenshot uploads rather than keyword entry.
- Home Goods:Furniture, kitchenware, and décor items resist automation in last-mile delivery due to dimensional weight.
- Beauty Products:Cosmetics and skincare rely on host demonstration and sampling programs to overcome the imagination gap of remote purchasing.
Electronics dominates installed base. Apparel is where expansion concentrates.
Sales Channel:
Channel economics separate high-frequency mobile transactions from appointment-viewing television formats.
- Television:Broadcast home shopping operates on scheduled programming blocks with live host demonstrations and limited-time offers. The US Federal Trade Commission enforces advertising substantiation standards that govern product claims made through this format.
- Online:Web-based storefronts integrate algorithmic recommendations subject to EU Digital Services Act transparency mandates, with conversion benchmarks in Beijing, Shanghai, and Shenzhen shaping global platform feature roadmaps.
- Catalogs:Print-to-order mechanisms retain relevance for demographic segments with lower smartphone penetration.
- Mobile Apps:One-click payment tokenization with biometric authentication is collapsing checkout abandonment rates among smartphone-native demographics.
Television holds legacy revenue share. Mobile apps are climbing the fastest.
Customer Type:
Volume concentration shifts from individual basket expansion to institutional procurement contracts.
- Retail Consumers:Individual households purchasing for personal use drive subscription-based replenishment models for consumable goods in the United Kingdom and Germany.
- Wholesale Buyers:Volume purchasers negotiating tiered pricing structures require dedicated account management infrastructure.
- Business Clients:Corporate procurement of office equipment and furnishings follows contract cycles rather than impulse patterns.
- Resellers:Independent distributors operating through marketplace platforms face China's State Administration for Market Regulation host accountability rules when leveraging livestream infrastructure.
Retail consumers anchor transaction volume. Business clients represent the steepest expansion trajectory.
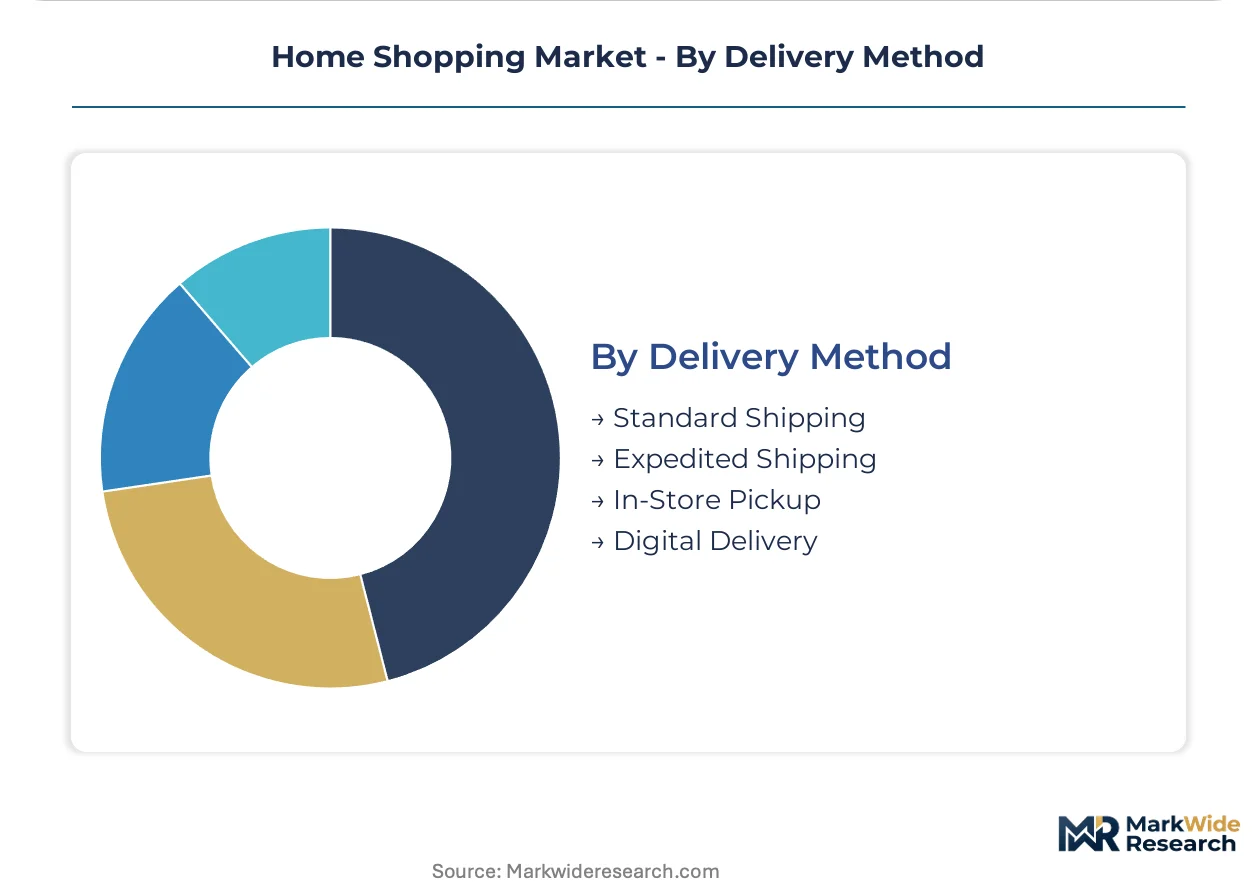
Delivery Method:
Speed tiers separate premium-positioned convenience from cost-optimized fulfillment.
- Standard Shipping:Parcel carrier networks with five-to-seven-day delivery windows capture price-sensitive demand.
- Expedited Shipping:Same-day and next-day delivery expectations in metropolitan zones require logistics infrastructure density that Amazon leverages for competitive positioning.
- In-Store Pickup:Click-and-collect mechanisms reduce last-mile costs while driving ancillary foot traffic.
- Digital Delivery:Software, media, and subscription services eliminate physical fulfillment entirely.
Standard shipping dominates unit economics. Expedited shipping is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics infrastructure density and regulatory frameworks for digital commerce differentiate home shopping penetration across major economies. Platform operators concentrate fulfillment capacity in metropolitan zones where same-day delivery expectations have become table stakes. Consumer protection regimes and data governance standards reshape cross-border selling protocols.
United States
Subscription replenishment models for consumable home goods concentrate volume with platforms possessing dense purchase history data. The FTC enforces advertising substantiation standards governing product claims across televised and digital formats. Greater Boston and the Pacific Northwest host technology clusters developing visual search and augmented reality placement tools for furniture categories.
China
Livestream commerce infrastructure achieves deepest consumer penetration in Beijing, Shanghai, and Shenzhen where social commerce integration sets global conversion benchmarks. SAMR oversees host accountability rules extending platform liability to individual influencers for product claims. The Yangtze River Delta anchors fulfillment network density supporting same-day delivery expectations across tier-one cities.
Germany
GDPR compliance architecture imposes fixed operational overhead on data localization and consent management tooling. The EU Digital Services Act transparency mandates force platform operators to document algorithmic recommendation logic. Parcel carrier wage pressures in metropolitan zones erode margin structures for bulky home goods categories resisting automation.
United Kingdom
Return logistics density for apparel and electronics categories consumes dedicated reverse supply chain capacity and warehouse square footage. Extended producer responsibility frameworks under packaging mandates create competitive differentiation for platforms pre-integrating take-back logistics. London and the Southeast concentrate technology development for predictive replenishment algorithms.
India
Vernacular-language livestream hosts unlock first-time e-commerce adoption in Jaipur, Lucknow, and Indore where English-dominant platforms historically underperformed. BIS standards govern product safety certification requirements for electronics and appliances sold through remote channels. Maharashtra and Karnataka host technology clusters developing mobile-first payment infrastructure with biometric authentication integration.
Home Shopping Market Key Industry Players
Omnichannel retail conglomerates and digital-native marketplaces split the market between physical-integrated fulfillment and algorithmic discovery platforms. The vendor base organizes around three strategic archetypes: logistics-integrated generalists leveraging warehouse density, specialty verticalists commanding category expertise, and hybrid operators bridging broadcast television with mobile commerce. Competitive dynamics center on last-mile speed guarantees and subscription lock-in mechanisms rather than price alone. Capacity expansion into tier-two urban zones and strategic partnerships with livestream talent agencies represent the dominant competitive moves.
Within the logistics-integrated tier, Amazon and Walmart anchor distinct positioning through fulfillment infrastructure scale and grocery-integrated basket expansion respectively. Wayfair exemplifies the specialty verticalist archetype through dedicated home goods taxonomy and spatial computing integration. IKEA occupies a unique position combining in-house flat-pack production with last-mile cost control. These three entities collectively represent the strategic spectrum from pure digital marketplace to captive manufacturing-integrated retail.
| Leading Market Players |
|---|
| Home Depot |
| IKEA |
| Amazon |
| Lowe's |
| Target |
| Walmart |
| Costco |
| TJX Companies |
| Wayfair |
| Others |
Cost & Logistics Intelligence
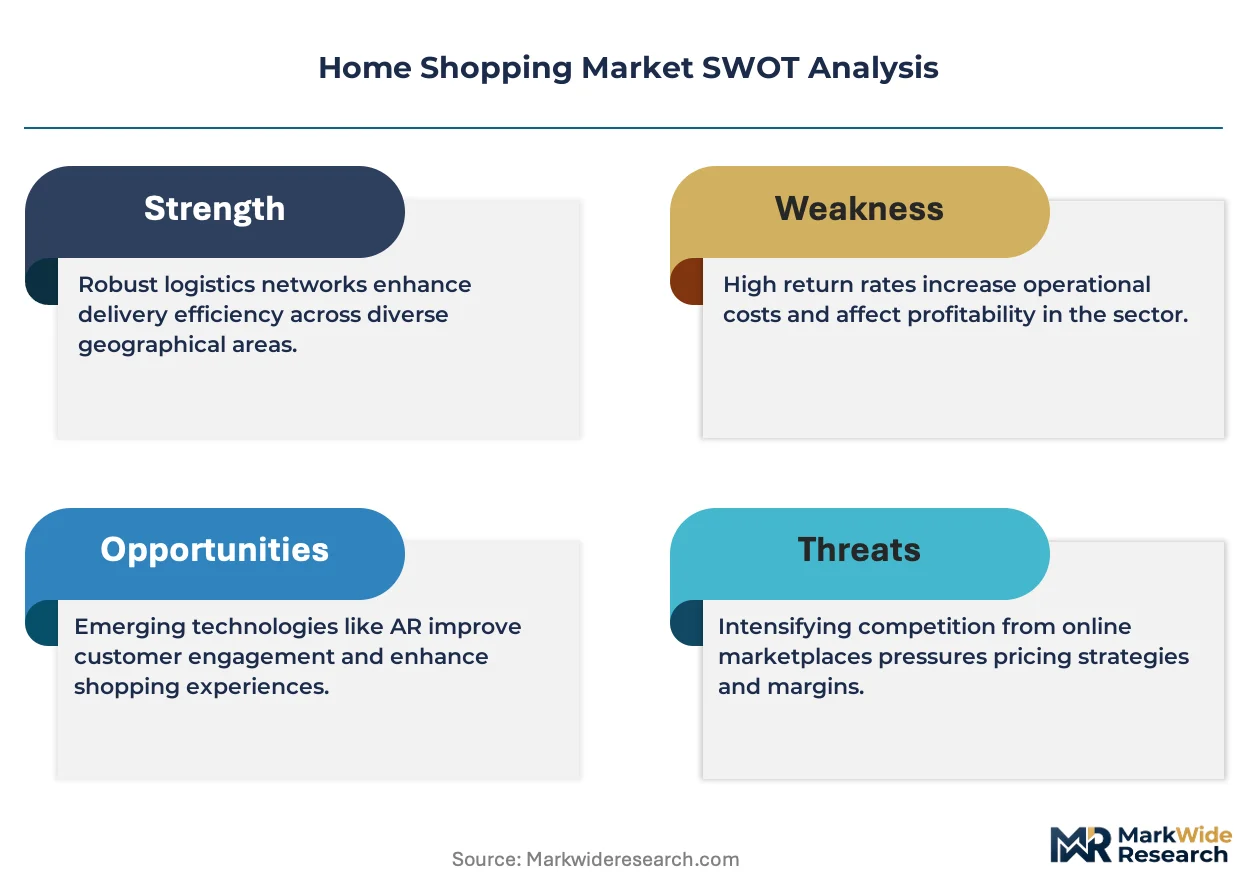
Chinese livestream commerce infrastructure concentration in Beijing, Shanghai, and Shenzhen feeds downstream margin capture into installation, assembly, and protection-plan revenue tiers that now exceed hardware transaction profitability for major platform operators.
Pricing Analysis
After-sales service revenue from installation support and extended protection plans drives lifetime customer value beyond the initial product transaction. Three-tier pricing structure across premium concierge, standard fulfillment, and economy self-service levels segments buyers by delivery speed and support intensity. Price differentiation hinges on geographic delivery density and after-sales bundling depth, with suburban and rural buyers exhibiting highest price sensitivity due to expedited shipping premiums. Cost compression in bulky home goods categories is intensifying because last-mile labor wage pressures in Germany and the United Kingdom resist automation scaling.
Supply Chain Analysis
Upstream flat-pack furniture production and electronics assembly concentrate in China, Vietnam, and Mexico, with component sourcing drawing from Taiwan semiconductors and South Korean display panels. Raw material dependencies include engineered wood composites, lithium-ion cells, and polymer packaging films. Single-source vulnerability persists for specialized livestream commerce logistics providers serving tier-one Chinese cities. Distribution runs through parcel carrier networks integrated with urban micro-fulfillment nodes, though reverse logistics capacity for apparel and electronics returns consumes disproportionate warehouse footprint in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home shopping has reorganized around service-attach revenue, with subscription replenishment and installation support expanding faster than pure merchandise transactions across the United States and European markets.
For Market Incumbents: Pre-empt platform disintermediation by locking in exclusive livestream host talent through multi-year representation contracts and escrow-backed liability frameworks under SAMR rules. Deepen backward integration into last-mile delivery infrastructure in metropolitan zones where same-day expectations have become table stakes. Anchor defensibility through predictive replenishment algorithms trained on dense purchase history data that forecast household consumption curves for consumable categories. For New Entrants and Emerging Players: Build out vernacular-language livestream capabilities targeting India's tier-two and tier-three cities such as Jaipur, Lucknow, and Indore, where English-dominant platforms historically underperformed. Prioritize augmented reality furniture placement tools that collapse the imagination gap suppressing online conversion for dimensional home goods. Partner with regional parcel carriers to bypass incumbent logistics density advantages rather than replicating nationwide fulfillment networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty verticalists commanding dedicated home goods taxonomy and spatial computing integration capabilities. Long-term viability in this market depends on recurring revenue attachment rates and subscription program retention curves rather than transactional growth alone. Monitor livestream commerce host accountability enforcement actions by SAMR and similar regulators as signals of platform liability expansion that could reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Livestream Host Talent Lock-In | Exclusive representation contracts under SAMR liability rules secure conversion-critical influencer relationships against competitor poaching. |
| Predictive Replenishment Algorithm Investment | Machine learning models trained on purchase history density capture consumable demand through anticipatory shipping in UK and German markets. |
| Vernacular Language Platform Localization | Native-language interfaces and hosts unlock first-time e-commerce adoption in India's tier-two urban centers beyond English-dominant incumbents. |
| Reverse Logistics Capacity Expansion | Dedicated returns processing infrastructure addresses apparel and electronics return density consuming warehouse square footage in the United States. |
| Extended Producer Responsibility Pre-Integration | Take-back and recycling logistics alignment with France's AGEC law creates competitive differentiation against compliance-lagged competitors. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with livestream commerce platform executives, logistics operations directors, and regulatory compliance officers; and secondary validation against SAMR enforcement disclosures, EU Digital Services Act transparency filings, and parcel carrier wage datasets. Cross-referencing against customs records for flat-pack furniture imports and Nielsen retail audit data for subscription program penetration enabled bottom-up and top-down triangulation across market sizing estimates.
Forecast inputs spanned product category velocity differentials, channel shift trajectories from television to mobile app, and metropolitan logistics density thresholds across the projection horizon. Segmentation modeling incorporated product category rotation speeds, sales channel conversion benchmarks, customer type procurement cycles, and delivery method cost structures. CAGRs were derived from fitted growth curves applied to installed base expansion and replacement demand patterns, with livestream commerce adoption rates in Chinese tier-one cities serving as reference benchmarks for global platform feature roadmaps.
Stress conditions across parcel carrier labor cost inflation, GDPR compliance architecture overhead, and cross-border VAT reconciliation complexity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smartphone penetration curves and biometric payment authentication rollout timelines. Material shifts in livestream host liability enforcement or extended producer responsibility framework expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Retail Signage Market
Retailing
China Retail Market
Retailing
Department Stores Market
Retailing
Electronics Retailing Market
Retailing
Floor Mat Rental Service Market
Retailing
Furniture Rental Service Market
Retailing
Qatar Retail Market
Retailing
Thailand Retail Market
Retailing
Subscription Box Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Gift Baskets Market
Retailing
Singapore Gifting Market
Retailing
Out Store Signage Market
Retailing
Retail Vending Machine Market
Retailing
United States Hardware Stores Retail Market
Retailing
Philippines Retail Industry Market