
 Retail Signage Market | 2026-2036
Retail Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Signage Market Analytics
The direct-to-retailer channel is narrowing as display manufacturers bypass traditional AV distributors and build proprietary installation networks. Samsung Electronics leverages its vertical semiconductor-to-panel supply chain to control cost positions in high-brightness outdoor units. Daktronics anchors its competitive stance through captive LED module production and sports-venue brand equity that extends into retail applications. Stratacache specializes in software-integrated hardware bundles, differentiating through content management platforms that lock in recurring service relationships.
Retail signage encompasses visual communication systems—ranging from electroluminescent digital displays to printed substrate assemblies—engineered for customer engagement, wayfinding, and promotional messaging in commercial environments. Digital signage units typically employ direct-view LED or LCD panels with brightness ratings exceeding 2,500 nits for window-facing installations, while static formats utilize UV-cured inkjet printing on vinyl or fabric substrates for seasonal campaign flexibility. Vinyl dominates material demand due to its cost scalability for temporary promotional cycles, though acrylic is gaining share in premium illuminated fixtures where optical clarity and weather resistance command margin premiums. Interactive design formats represent the fastest-expanding segment, driven by touch-overlay integration and sensor-based personalization that shifts capital allocation from passive displays toward experiential infrastructure.
The U.S. Department of Energy enforces minimum efficacy standards for illuminated signage under federal appliance regulations, while the EU F-Gas Regulation restricts refrigerant-based cooling in outdoor digital enclosures, pushing thermal design toward passive and liquid-cooled architectures. OSHA workplace safety standards govern installation protocols for overhead-hanging and freestanding units above specified weight thresholds, creating compliance barriers for non-certified contractors. Stakeholders must monitor evolving municipal energy codes and right-to-repair legislation that could mandate modular component access and extend product lifecycle obligations across installed bases.
Market Dynamics
Energy efficiency mandates under the EU Ecodesign Directive and parallel North American frameworks are compressing product lifecycles for static illuminated signage while accelerating capital redeployment toward LED-backlit and direct-view LED systems.
Growth Catalysts
- Quick-service restaurant digital menu expansion:Drive-thru and in-store deployments are pulling demand for high-brightness outdoor-rated displays. Chains prioritize content agility over printed substrate flexibility.
- EU F-Gas Regulation thermal redesign:Restrictions on refrigerant-based cooling in outdoor digital enclosures force passive and liquid-cooled architectures. This expands addressable market for thermal engineering specialists.
- Sun Belt metropolitan construction:New store development and format refreshes across Texas, Florida, and Arizona retail corridors concentrate near-term demand for exterior and interior signage systems.
Market Restraints
- LED driver and semiconductor supply concentration:Taiwan and South Korea foundries control critical backlighting component output. Geopolitical friction or capacity constraints transmit directly to display manufacturer lead times.
- OSHA installation certification barriers:Overhead-hanging and freestanding units above specified weight thresholds require certified contractor protocols. Non-compliant installers face exclusion from commercial projects.
- Printed substrate substitution pressure:Vinyl and fabric static formats face displacement risk where digital unit economics improve. Short-cycle promotional campaigns still favor printed materials.
Strategic Opportunities
- Interactive sensor integration white space:Touch-overlay and camera-based personalization systems enable experiential infrastructure investments. Retailers shift capital from passive displays toward engagement metrics.
- Right-to-repair legislative tailwinds:Proposed modular component access mandates in EU and select US states could extend product lifecycle obligations. Manufacturers with field-service networks capture recurring revenue.
- Acrylic premium fixture penetration:Optical clarity and weather resistance advantages command margin premiums in outdoor illuminated applications. Material substitution from vinyl accelerates in flagship and luxury retail.
Industry Challenges
- AV-integrator skill displacement:Display manufacturers building proprietary installation networks bypass traditional distributor relationships. Technical sales and field engineering talent pools face reconfiguration pressure.
- Content management platform integration complexity:Software-integrated hardware bundles require API compatibility with legacy retail IT infrastructure. Deployment timelines extend where middleware customization proves necessary.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Signage Market |
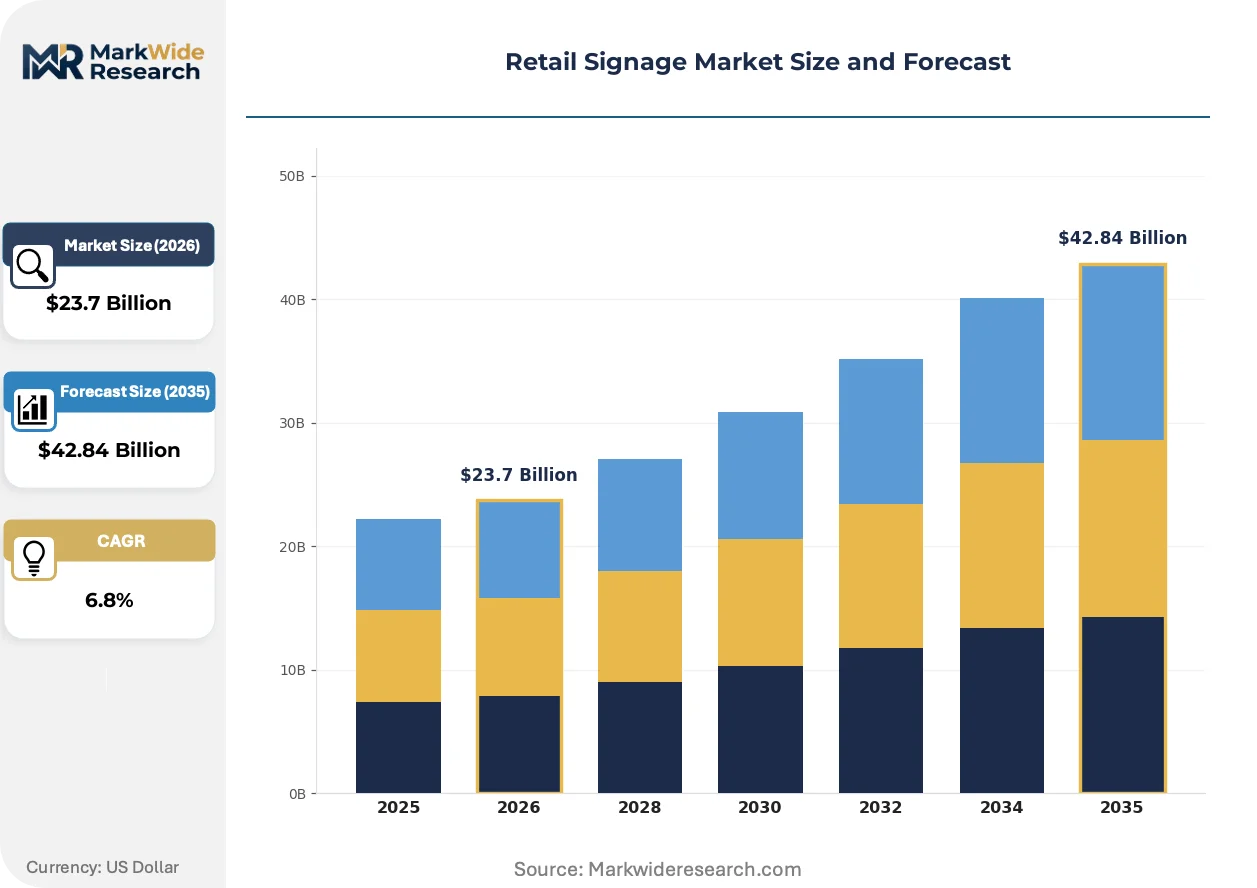
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signage, Banners, Posters, Sign Boards Material: Vinyl, Fabric, Metal, Acrylic Installation Type: Wall-mounted, Freestanding, Hanging, Outdoor Design Format: Interactive, Static, Illuminated, 3D |
| Companies Covered | Sony Corporation, Daktronics, Samsung Electronics, Cisco Systems, Stratacache, LG Display, Panasonic Corporation, Sharp Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Signage Market Evolving Landscape
Display hardware and content management software are fusing into unified service architectures, while thermal design and material selection respond to tightening energy and environmental compliance frameworks.
Direct-view LED is hybridizing with LCD backlighting systems in mid-brightness retail applications. Department stores and grocery chains adopt mixed-format deployments to balance capital efficiency with window-facing visibility requirements. This convergence compresses pure-play LCD market share in the 2,500-5,000 nit range while expanding LED module demand for retrofit upgrades.
REACH substance restrictions and EU Green Deal circularity requirements are forcing substrate and adhesive reformulation in printed signage. UV-cured inkjet operations face supply chain audits for hazardous material content. German and French converters are accelerating water-based and bio-derived ink qualification to maintain CE marking access.
Buyer preference for hardware-as-a-service models is displacing capital purchase cycles in multi-location retail chains. Subscription structures bundle display hardware, content management software, and field maintenance into single operational expenditures. This shift concentrates most visibly in United States quick-service restaurant and convenience store verticals where refresh frequencies exceed five-year depreciation schedules.
Retail Signage Market Segmentation
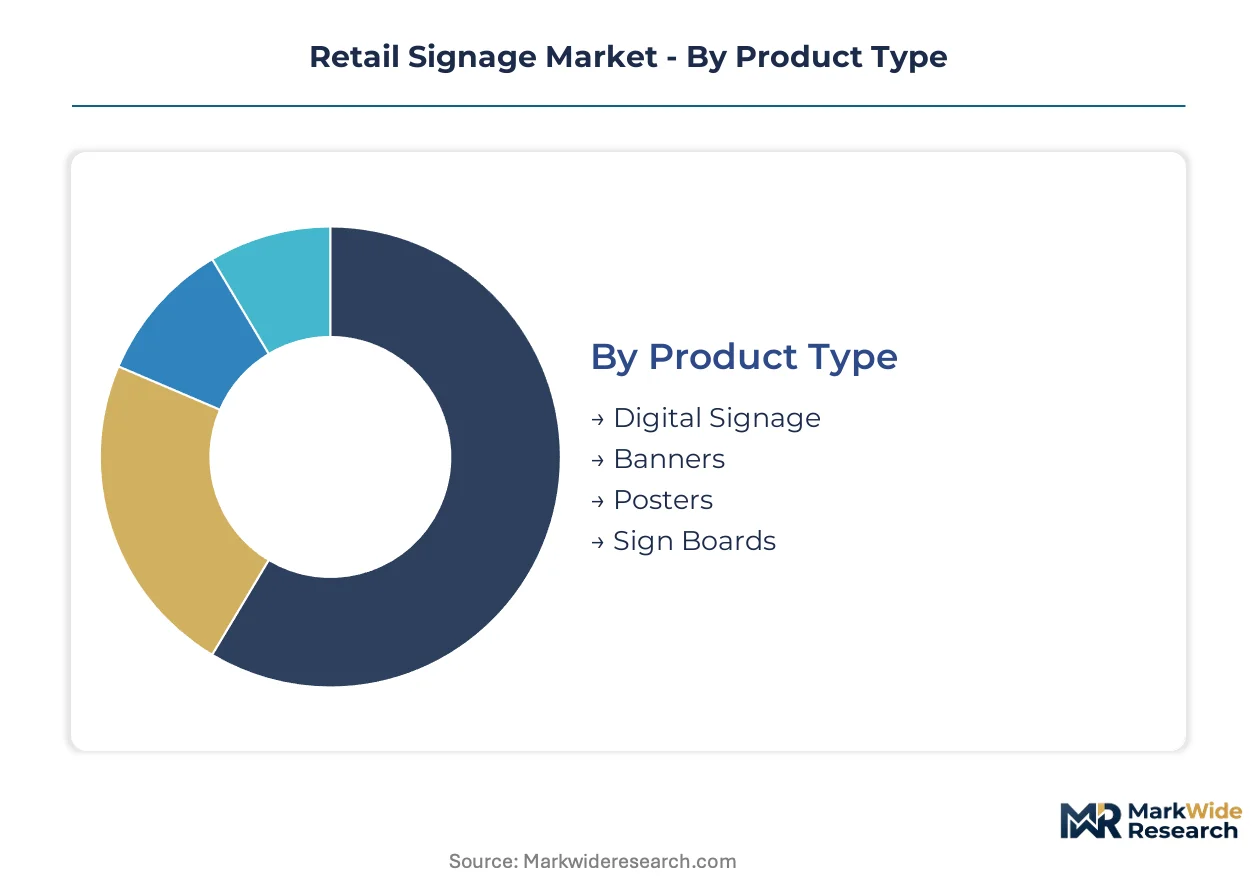
Retail signage segmentation reveals divergent service intensity across product categories. Digital systems demand continuous software support and thermal maintenance, while static formats require minimal post-installation engagement. Material selection and installation geometry further differentiate lifecycle cost structures and replacement cadences.
Product Type:
After-sales-service intensity varies sharply across product categories, with digital platforms requiring ongoing content management and field engineering support that static formats never demand.
- Digital Signage:Direct-view LED and LCD panels with brightness ratings exceeding 2,500 nits for window-facing installations. Quick-service restaurant chains across Texas and Florida are pulling demand for outdoor-rated units with content agility requirements. Thermal management and software updates create recurring service relationships.
- Banners:Flexible printed substrates using UV-cured inkjet or solvent-based production for temporary promotional cycles. Seasonal retail campaigns in Sun Belt metropolitan corridors favor vinyl-based banner economics for 30-90 day display periods. Replacement frequency outpaces digital alternatives.
- Posters:Rigid substrate displays for interior point-of-sale messaging. Backlit poster frames in convenience store verticals balance illumination requirements against capital constraints.
- Sign Boards:Permanent identification systems for storefront and wayfinding applications. Acrylic-faced illuminated boards command premium positioning in luxury retail environments.
By volume, Banners leads. By growth pace, Digital Signage is ahead.
Material:
Cost tier stratification separates commodity substrates from engineered materials with optical and weathering premiums.
- Vinyl:PVC-based flexible substrates dominating temporary promotional applications. Cost scalability for high-volume, short-cycle campaigns protects share against digital displacement in budget-constrained retail verticals.
- Acrylic:Polymethyl methacrylate panels with superior optical clarity and UV resistance. Premium outdoor illuminated fixtures in flagship retail locations command margin premiums that justify material substitution from vinyl.
- Fabric:Polyester and dye-sublimation substrates for tension-frame systems. Lightweight shipping economics benefit multi-location retailers with frequent format refreshes.
- Metal:Aluminum and steel structural elements for permanent exterior installations. OSHA weight-threshold compliance requirements concentrate demand for certified installation protocols.
Vinyl dominates unit shipments. Acrylic captures the steepest expansion trajectory as luxury retail upgrades fixture quality.
Installation Type:
Application geometry determines regulatory exposure and contractor certification requirements.
- Outdoor:Weather-rated enclosures facing EU F-Gas Regulation thermal redesign pressures. Passive and liquid-cooled architectures are displacing refrigerant-based systems in digital deployments across German and French retail corridors.
- Freestanding:Kiosk and pillar structures requiring foundation anchoring and wind-load engineering. Convenience store fuel canopy integrations in Arizona and Texas concentrate near-term demand.
- Wall-mounted:Interior flat-panel and backlit systems with simplified structural requirements. Department store cosmetics and electronics departments favor this geometry for sight-line optimization.
- Hanging:Overhead-suspended units triggering OSHA certification barriers above specified weight thresholds. Non-compliant installers face exclusion from commercial projects in United States jurisdictions.
Wall-mounted systems lead by deployment count. Outdoor installations are expanding most quickly on digital conversion.
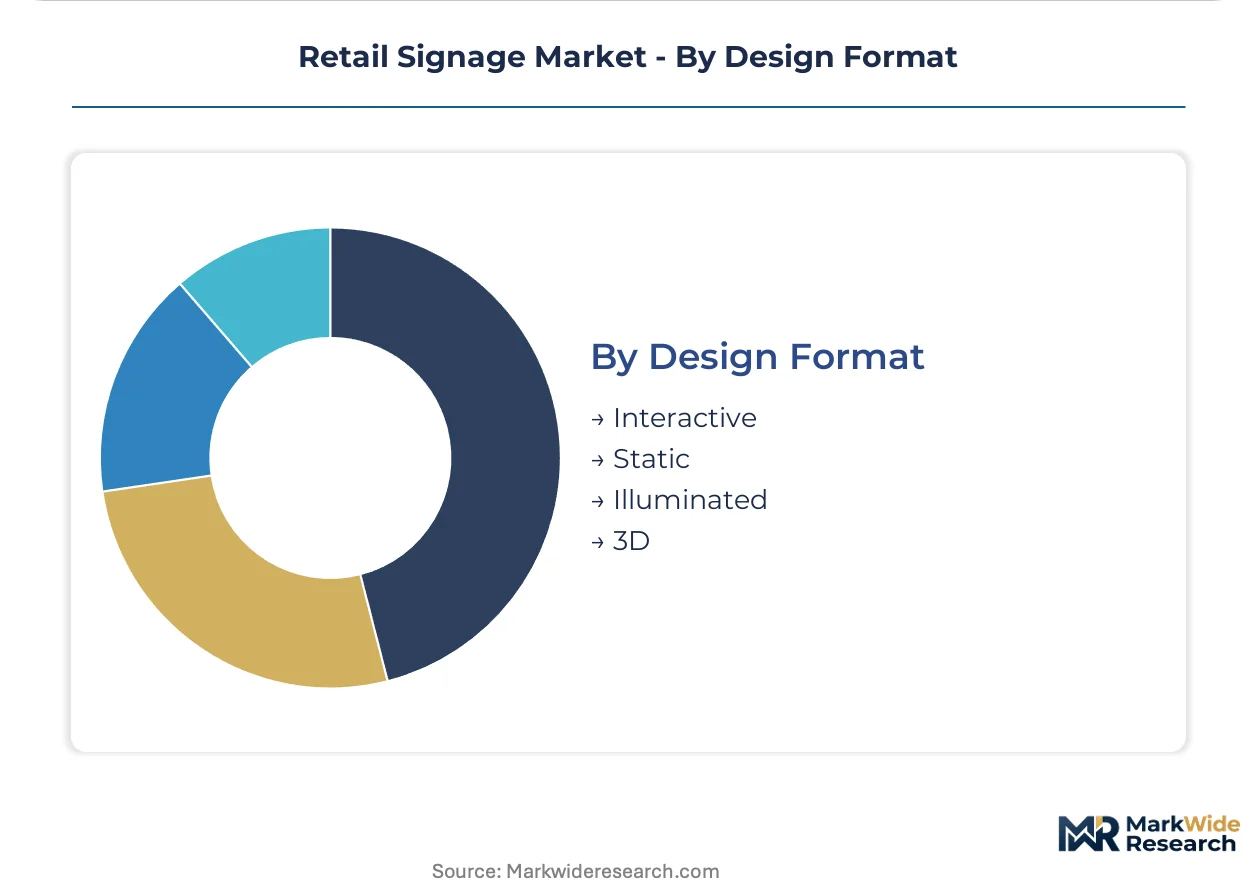
Design Format:
Customer engagement intensity separates passive communication from experiential infrastructure investments.
- Interactive:Touch-overlay and sensor-based personalization systems integrating camera analytics and mobile connectivity. Retailers are shifting capital from passive displays toward engagement metrics and dwell-time optimization.
- Illuminated:LED-backlit and edge-lit systems facing EU Ecodesign Directive efficiency mandates. Energy consumption standards are compressing product lifecycles for legacy fluorescent units.
- Static:Non-illuminated printed and painted substrates with minimal energy footprint. REACH substance restrictions are forcing ink and adhesive reformulation in European supply chains.
- 3D:Dimensional lettering and formed plastic structures for brand identity prominence. Fabrication complexity limits adoption to flagship and anchor tenant locations.
Static formats dominate existing installed base. Interactive systems gain share fastest on experiential retail investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States Sun Belt metros where new construction and format refreshes sustain premium realizations, while European markets compress margins under REACH substance audits and Ecodesign efficiency mandates. Germany and France absorb compliance costs through substrate reformulation and thermal redesign, shifting competitive advantage toward integrated service providers.
United States
Texas, Florida, and Arizona metropolitan corridors drive exterior and interior signage demand through quick-service restaurant expansion and convenience store fuel canopy integrations. OSHA installation certification requirements for overhead-hanging units above weight thresholds exclude non-compliant contractors from commercial projects. Dallas-Fort Worth and Houston retail construction clusters concentrate procurement for high-brightness outdoor-rated displays.
Germany
EU Ecodesign Directive efficiency standards compress product lifecycles for static illuminated signage while accelerating LED-backlit system deployment. REACH substance restrictions force UV-cured inkjet operations toward water-based and bio-derived ink qualification to maintain CE marking access. Frankfurt and Munich retail corridors lead thermal engineering adoption for passive and liquid-cooled outdoor digital enclosures.
China
Domestic LED module production scales to serve retrofit upgrade demand across department store and grocery chain mixed-format deployments. National dual carbon goals pressure energy consumption standards for illuminated fixtures in commercial environments. Yangtze River Delta manufacturing clusters supply direct-view LED components for mid-brightness retail applications balancing capital efficiency with visibility requirements.
Japan
METI efficiency guidelines and JIS standards govern display hardware performance specifications for retail environments. Premium fixture demand concentrates in Tokyo and Osaka flagship locations where acrylic-faced illuminated boards command optical clarity premiums. Touch-overlay integration for experiential infrastructure shifts capital allocation from passive displays toward engagement metrics in cosmetics and electronics departments.
United Kingdom
London and Southeast England retail corridors concentrate hardware-as-a-service model adoption, bundling display hardware, content management software, and field maintenance into operational expenditures. CSRD sustainability reporting requirements extend product lifecycle obligations across installed bases. Midlands and North England distribution networks face reconfiguration pressure as display manufacturers build proprietary installation channels bypassing traditional AV integrators.
Retail Signage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from module and semiconductor supply. Market structure consolidates around vertically integrated electronics conglomerates with captive semiconductor-to-panel supply chains, while mid-scale fabricators fragment across substrate conversion and installation services. Three archetypes dominate: full-stack platform providers bundling hardware-software-service, captive LED module producers controlling thermal and brightness engineering, and regional installation specialists building proprietary field-service networks. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through direct-to-retailer channel bypass.
Among diversified electronics conglomerates, Samsung Electronics and Sony Corporation exemplify full-stack platform positioning through vertical semiconductor-to-display integration. Daktronics occupies a position within the captive production archetype, anchoring competitive stance through in-house LED module manufacturing. Stratacache represents the software-integrated hardware bundle tier, differentiating through content management platforms that lock in recurring service relationships rather than capital purchase cycles.
| Leading Market Players |
|---|
| Sony Corporation |
| Daktronics |
| Samsung Electronics |
| Cisco Systems |
| Stratacache |
| LG Display |
| Panasonic Corporation |
| Sharp Corporation |
| NEC Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese LED module foundries is compressing spot pricing for backlighting components while simultaneously pressuring display manufacturers to absorb inventory risk through take-or-pay arrangements. This utilization dynamic tightens margins for mid-tier fabricators in Southeast Asia who lack captive semiconductor supply, while rewarding vertically integrated conglomerates with cost positions that undercut project-based competitors.
Pricing Analysis
The customization-premium spread between configured-to-order digital signage and standard catalog units now exceeds the hardware cost of entry-level static formats. Subscription-based hardware-as-a-service models dominate quick-service restaurant deployments, bundling content management software and field maintenance into operational expenditures. Price differentiation hinges on brightness certification tiers and thermal engineering complexity, with outdoor-rated units commanding substantial premiums over interior alternatives. Cost compression in vinyl banner substrates is intensifying because Chinese converters are flooding export markets with excess capacity. Budget-constrained convenience store chains exhibit highest price sensitivity, while luxury flagship retailers prioritize optical performance over unit economics.
Supply Chain Analysis
Supplier-financing facilities from Taiwan and South Korea foundries now extend 90-120 day payment terms to qualified display manufacturers, shifting working capital pressure downstream. Critical LED driver ICs and high-brightness diodes draw from Taiwan, South Korea, and China manufacturing clusters. Raw material dependencies include gallium nitride wafers, polymethyl methacrylate resin, and UV-curable ink chemistries. Single-source vulnerability around Taiwan semiconductor output represents the dominant structural risk, with geopolitical friction threatening direct transmission to display manufacturer lead times. Distribution runs through direct-to-retailer channels that bypass traditional AV integrators, concentrating procurement relationships with platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail signage is fundamentally a service-attach opportunity where content management subscriptions and thermal maintenance contracts are expanding faster than hardware replacement cycles. The recurring-revenue layer now captures margin that capital purchase models leave unrealized.
For Market Incumbents: Build proprietary field-service networks as the defensive moat against direct-to-retailer channel bypass. Incumbents should deepen backward integration into LED module production to control thermal engineering costs, while simultaneously locking in multi-year software subscriptions that raise switching costs for quick-service restaurant chains. The threat of hardware-as-a-service displacement from platform specialists demands certification investment in OSHA-compliant installation protocols that exclude non-compliant regional contractors. For New Entrants and Emerging Players: Mid-market grocery chains in the United States Sun Belt represent the most penetrable entry point for digital menu board retrofits, as these buyers prioritize capital efficiency over flagship-grade performance. Interactive sensor integration for convenience store fuel canopy deployments offers a second white-space target with lower incumbent saturation. A software-first go-to-market angle, bundling hardware at cost with content management platform fees, circumvents the capital expenditure approval barriers that stall pure hardware sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators bundling hardware-software-service into unified subscriptions, making these archetypes the preferred acquisition target for long-term viability across the five-to-ten year window. Thermal engineering specialists with passive and liquid-cooled outdoor enclosure expertise command scarcity premiums under EU F-Gas Regulation compliance requirements. The signal to watch is municipal right-to-repair legislation progression, which would extend product lifecycle obligations and favor manufacturers with established field-service infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Modules | Captive production of high-brightness diodes secures thermal engineering control and compresses cost positions. |
| Hardware-as-a-Service Launch | Subscription bundling displaces capital purchase cycles in quick-service restaurant verticals. |
| Content Management Platform Acquisition | Software integration locks in recurring relationships and raises customer switching costs. |
| Proprietary Installation Network Buildout | Direct-to-retailer channels bypass traditional AV integrators and capture service revenue. |
| Passive Thermal System Development | Liquid-cooled architectures satisfy EU F-Gas Regulation while expanding addressable market. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association disclosures to establish grounded market estimates. Primary interviews engaged display manufacturer product managers, quick-service restaurant facilities directors, AV integrator technical sales leads, and municipal code enforcement officers across Texas, Florida, Arizona, Germany, and France. Secondary validation drew from EU Ecodesign Directive implementation reports, OSHA technical guidance documents, and LED component trade flow databases. Bottom-up unit shipment estimates triangulated against top-down spending analyses from retail construction permits and format refresh announcements.
Forecast inputs span product type segmentation across digital, banner, poster, and sign board categories; material tiers from commodity vinyl to engineered acrylic; installation geometry covering outdoor, freestanding, wall-mounted, and hanging configurations; and design format evolution from static through interactive systems. CAGRs were derived from regression analysis against retail construction indices and quick-service restaurant expansion plans. Industry-specific inputs include EU F-Gas Regulation compliance cost modeling and Sun Belt metropolitan development pipeline tracking across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates, semiconductor foundry utilization, or energy efficiency mandate enforcement timelines would shift the trajectory. Forecasts reflect assumptions around regulatory stability and supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Retail Vending Machine Market
Retailing
Australia Retail Bags Market
Retailing
Consumer Products and Retail Market
Retailing
Department Stores Market
Retailing
In Store Signage Market
Retailing
China Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Displays Market
Retailing
Subscription Box Market
Retailing
Gift Baskets Market
Retailing
Vietnam Retail Market
Retailing
Clothing Retail Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
European Discount Retail Market
Retailing
United States Hardware Stores Retail Market
Retailing
Consumer Shopping Cart Market