
 Retail Vending Machine Market | 2026-2036
Retail Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Vending Machine Market Intelligence
The capability gap between developing proprietary smart vending software and sourcing off-the-shelf systems is redrawing the competitive landscape. Fuji Electric Co., Ltd. leverages its electronics expertise to develop advanced, integrated smart machines. In contrast, Royal Vendors, Inc. specializes in durable, traditional machines for specific product categories. Azkoyen Group competes by offering a modular platform adaptable to various payment and management systems.
A retail vending machine is an automated unit that dispenses products after a consumer inserts currency or makes a digital payment. These machines often feature refrigerated coils or conveyor belt systems to handle items ranging from snacks to delicate electronics, providing unattended retail access. While traditional machines still dominate in certain public spaces, the smart machine segment, integrated with mobile payment options, represents the fastest-growing category. Within product types, beverages and snacks maintain the largest share, but personal care items are an expanding niche.
In the United States, FDA regulations govern food safety for dispensed items, while in Europe, CE marking ensures electronic and safety compliance for the machines themselves. Payment Card Industry (PCI) data security standards are critical for operators deploying credit card and mobile payment solutions. Navigating the diverse regional requirements for electrical safety, food handling, and digital payment security is a key strategic consideration for market participants.
Market Dynamics
The central force is the shift from hardware sales to data-driven service models, enabled by IoT connectivity and digital payments. This redefines value from the machine to the retail service it provides.
Growth Catalysts
- Contactless Payments:Integration of NFC and QR code systems accelerates transaction speeds and enhances user convenience, driving sales in high-turnover locations.
- High-Traffic Placements:Demand from airports and hospitals for 24/7 retail access drives network expansion, with deep cultural adoption in markets like Japan.
- Product Diversification:Advanced dispensing and refrigeration enable sales of fresh food and personal care items, expanding the market beyond traditional snacks.
Market Restraints
- High Capital Expenditure:The initial investment for smart machines, including software and payment systems, is a significant financial barrier for smaller operators.
- Regulatory Fragmentation:Operators must navigate disparate rules, including PCI for payments, CE marking in Europe, and FDA food safety regulations in the US.
- Connectivity Dependence:Smart features require reliable internet access, which is a functional limitation in underground transit or remote areas.
Strategic Opportunities
- AI-Powered Analytics:Leveraging AI for dynamic pricing and predictive inventory management can optimize revenue and reduce operational costs.
- Unattended Micro-Markets:Establishing curated retail spaces in offices and residential complexes offers a broader product selection than single machines.
- Emerging Market Expansion:High mobile payment adoption in countries like India creates opportunities for asset-light retail where formal infrastructure is less dense.
Industry Challenges
- Logistical Complexity:Managing route planning, inventory restocking, and maintenance across a dispersed network of machines presents a significant operational hurdle.
- Security Threats:Protecting machines from both physical vandalism and cyberattacks targeting payment systems and operational data is a critical, ongoing challenge.
- System Integration:Ensuring interoperability between machine hardware, various payment gateways, and backend management software remains a persistent technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Vending Machine Market |
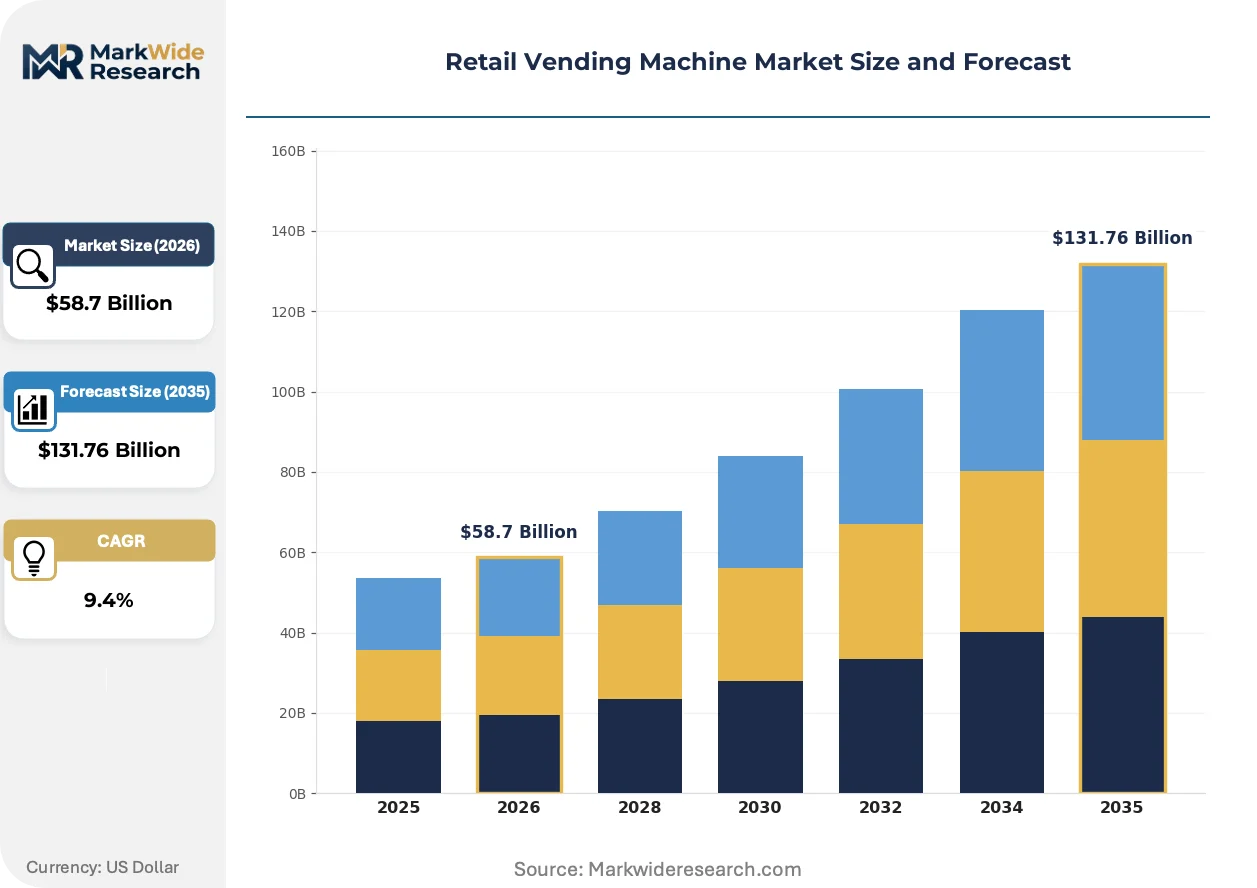
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Electronics, Personal Care Payment Method: Cash, Credit Card, Mobile Payment, Contactless End User: Offices, Schools, Hospitals, Public Spaces Machine Type: Traditional, Smart, Micro Markets, Combo |
| Companies Covered | Fuji Electric Co., Ltd., Crane Merchandising Systems, Azkoyen Group, Sanden Holdings Corp., Royal Vendors, Inc., Seaga Manufacturing, Inc., Jofemar Corporation, N&W Global Vending S.p.A., Westomatic Vending Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Vending Machine Market Strategic Shifts & Innovations
The evolution of retail vending is defined by the transition from simple dispensing to creating interactive, data-rich consumer experiences. This shift prioritizes software-driven services and operational intelligence over mechanical hardware.
Onboard IoT sensors provide real-time data on inventory, temperature, and machine status. Operators of fresh food and high-value product vending are the primary adopters. This capability is miniaturizing the core components for telemetry, allowing older machines to be retrofitted for smart management and reduced spoilage.
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) are creating new compliance demands. These rules push manufacturers toward more energy-efficient refrigeration and electronic systems. Vending operators in the EU now prioritize machines with documented low power consumption to meet regulatory mandates and corporate sustainability goals.
Consumer purchasing is moving from anonymous cash transactions toward loyalty-linked payments via mobile applications. This model disrupts impersonal vending by enabling a direct customer relationship. This trend is most visible in environments like corporate campuses, where users can receive personalized offers and manage account balances.
Retail Vending Machine Market Segmentation
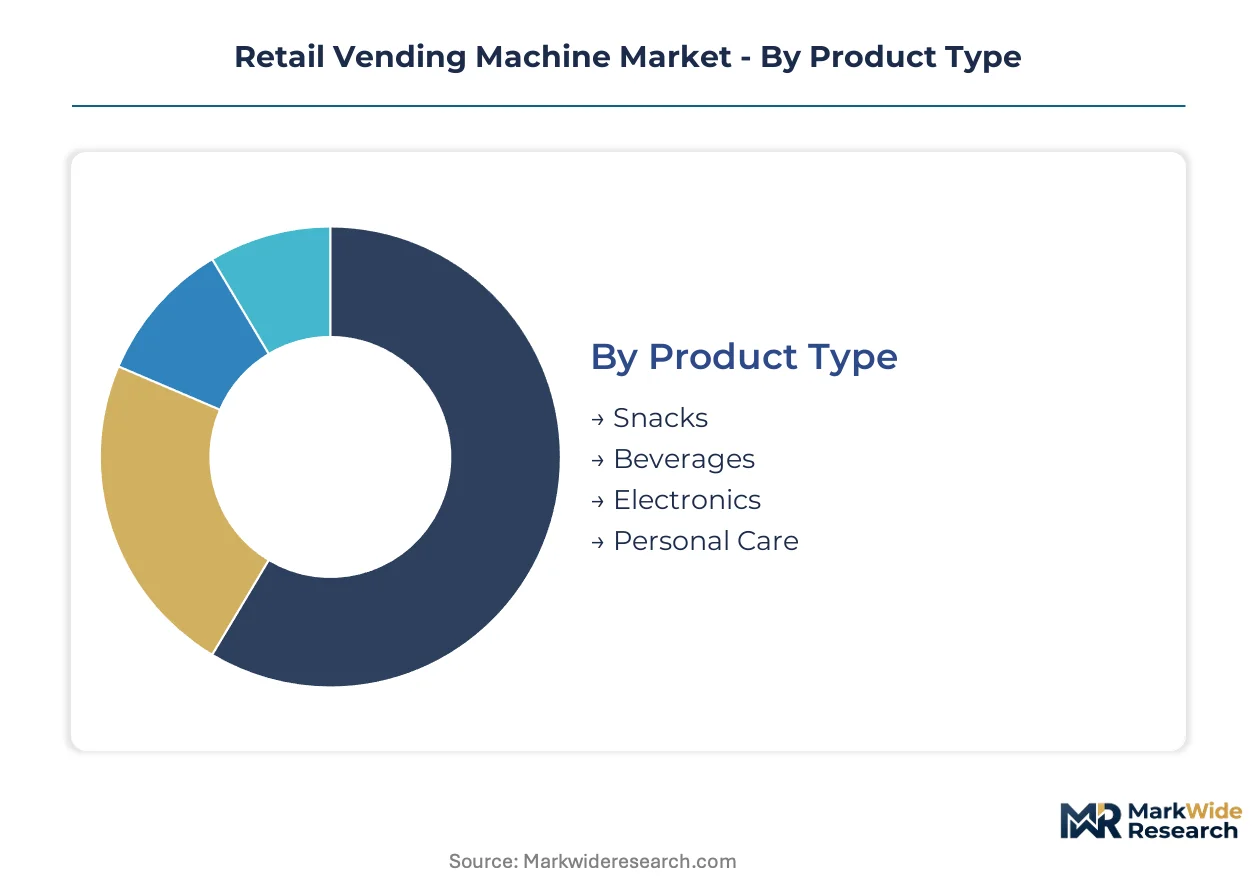
Understanding the Retail Vending Machine market's various segments illuminates distinct operational models and consumer engagement strategies. This granular analysis provides clarity on where demand concentrates and how technological advancements are reshaping traditional retail access. Identifying key segment dynamics allows market participants to tailor offerings and optimize deployment strategies across diverse environments.
Product Type:
Vending machine product types often reflect regional consumption patterns, with some categories experiencing widespread global adoption while others cater to more localized preferences.
- Beverages:These machines dispense a wide array of drinks, from carbonated soft drinks to juices and bottled water. Demand remains consistently high in public spaces and workplaces globally, driven by instant refreshment needs and convenience.
- Snacks:This segment includes confectionery, crisps, and packaged food items, providing quick energy and comfort food options. High-traffic locations like transit hubs and educational institutions across continents sustain robust demand, supported by impulse purchasing.
- Electronics:These machines offer small electronic devices, accessories, and charging solutions. They cater to travelers in airports and tech-savvy consumers in urban centers.
- Personal Care:Dispensing items like toiletries, hygiene products, and over-the-counter medicines. This niche is expanding in hospitality venues and emergency public restrooms.
Beverages holds the largest share; momentum sits with Personal Care.
Payment Method:
The evolution of payment methods in vending machines reflects shifting consumer preferences for speed and security, alongside the integration of digital financial ecosystems.
- Mobile Payment:This category encompasses transactions made via smartphone applications, leveraging technologies like NFC or QR codes. Demand is accelerating in tech-forward markets like Japan and among younger demographics, valuing convenience and integrated loyalty programs.
- Contactless:These systems allow payments by tapping cards or devices without physical contact, including NFC-enabled credit/debit cards. High-turnover locations globally prioritize these solutions for rapid transactions and reduced germ transmission.
- Cash:Traditional currency insertion remains prevalent in many regions, particularly for lower-value transactions and in areas with limited digital payment infrastructure.
- Credit Card:This method allows direct payment using physical credit or debit cards, offering familiarity and wider acceptance in many retail environments.
Mobile Payment is expanding most quickly; Cash still represents a significant transaction volume.
End User:
Vending machine deployment strategies are heavily influenced by the specific needs and traffic patterns of various end-user environments, dictating product mix and service requirements.
- Hospitals:These facilities require 24/7 access to refreshments, snacks, and personal care items for staff, patients, and visitors. Demand for health-conscious options and robust payment systems is high in these critical care settings.
- Public Spaces:Locations such as airports, train stations, and shopping malls experience high foot traffic and diverse consumer needs. These environments drive demand for varied product offerings and resilient, high-capacity machines.
- Offices:Workplace vending solutions provide convenience for employees, often featuring a mix of snacks, beverages, and fresh food options. Corporate campuses increasingly adopt smart machines for integrated services.
- Schools:Educational institutions utilize vending for student and staff refreshments, with a growing emphasis on healthy choices and cashless payment options for minors.
Public Spaces drive substantial volume; Hospitals are demonstrating a steep expansion trajectory.
Machine Type:
The technological sophistication of vending machines varies significantly, from basic mechanical dispensers to advanced, internet-connected retail units.
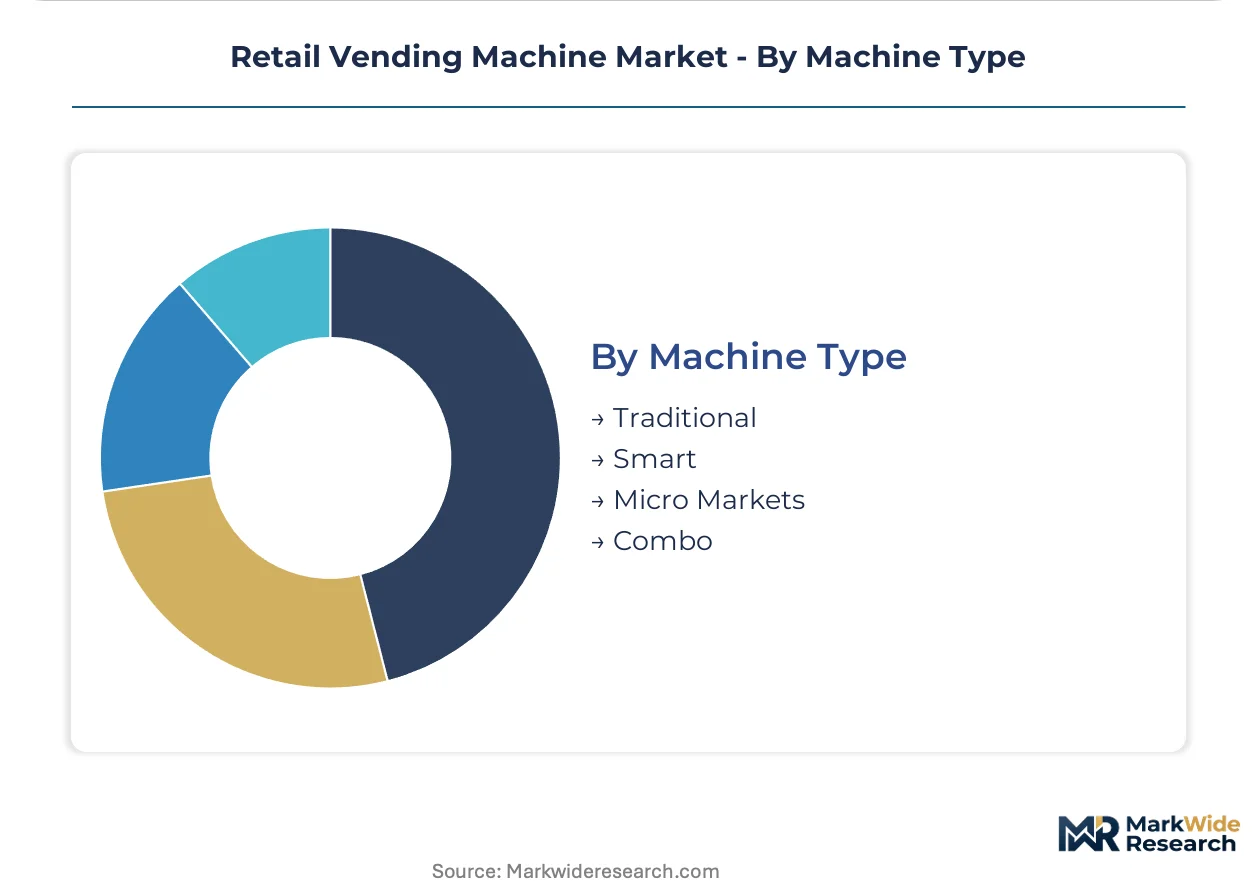
- Smart:These machines integrate IoT connectivity, digital screens, and advanced telemetry for real-time inventory and sales data. Demand for smart machines is concentrated in developed markets like the United States, driven by operational efficiency and data analytics.
- Micro Markets:Unattended self-checkout retail spaces offering a broader product selection than traditional machines, often found in corporate offices or residential complexes. These provide a curated retail experience, enhancing user convenience and product diversity.
- Traditional:These mechanical or electromechanical units dispense products using basic coin or bill acceptors. They maintain prevalence in areas with limited internet infrastructure or lower capital investment capacity.
- Combo:Machines combining multiple product types, such as snacks and beverages, within a single unit. These offer space-saving solutions and diverse offerings in varied locations.
Smart machines are gaining share fastest; Traditional machines still hold a foundational market position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry for retail vending machines is notable between established markets like Japan and emerging economies such as India. Japan's advanced vending culture supports premium pricing for integrated smart machines and diverse product offerings. Conversely, India's market emphasizes cost-effective solutions and high-volume transactions driven by mobile payment adoption.
United States
Demand for smart machines and personal care items drives market expansion across the United States. FDA regulations ensure stringent food safety standards for all dispensed consumables. Tech hubs like Silicon Valley see concentrated deployment of advanced, data-driven vending solutions for employee convenience.
Japan
Japan's deep cultural adoption creates sustained demand for convenience and niche products, from hot meals to fresh produce. METI guidelines encourage energy efficiency and technological innovation in machine design. Major metropolitan areas like Tokyo feature high densities of highly specialized vending units with integrated digital displays.
Germany
European demand for energy-efficient machines and diverse product offerings shapes the German retail vending machine market. CE marking ensures electronic and safety compliance for all machines sold within the European Union. Industrial centers such as Bavaria are adopting smart vending for workplace refreshments and specialized component dispensing.
India
High mobile payment adoption drives demand for asset-light retail solutions in urban and semi-urban areas across India. RBI regulations govern digital payment systems, accelerating secure mobile transaction capabilities. Major cities like Bangalore are experiencing rapid deployment of smart vending machines in public spaces and corporate campuses.
China
Rapid urbanization and a growing middle class fuel demand for convenient, automated retail solutions across China. GB standards dictate product quality and safety for vending machine components and dispensed goods. Manufacturing hubs in the Yangtze River Delta are innovating advanced smart vending technologies for both domestic and export markets.
Retail Vending Machine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the retail vending machine market. The market exhibits a tiered structure, with a few large integrated manufacturers alongside numerous specialized component providers and regional operators. Strategic archetypes include advanced smart machine developers, traditional durable machine specialists, and modular platform providers. Companies pursue portfolio diversification and strategic partnerships to enhance their market reach and technological offerings.
Specialists in integrated smart machines, Fuji Electric Co., Ltd. represents a Japanese electronics giant leveraging deep technological expertise for advanced solutions. Royal Vendors, Inc., a US-based firm, exemplifies a focus on durable, traditional machines for specific product categories, emphasizing reliability and robust design. Azkoyen Group, operating from Europe, occupies a position as a modular platform provider, offering adaptable systems for various payment and management integrations. These companies anchor distinct segments of the market, reflecting varied approaches to product development and market penetration.
| Leading Market Players |
|---|
| Fuji Electric Co., Ltd. |
| Crane Merchandising Systems |
| Azkoyen Group |
| Sanden Holdings Corp. |
| Royal Vendors, Inc. |
| Seaga Manufacturing, Inc. |
| Jofemar Corporation |
| N&W Global Vending S.p.A. |
| Westomatic Vending Services Ltd. |
Cost & Logistics Intelligence
The substitution of traditional mechanical components with advanced IoT sensors and digital displays simultaneously reshapes the supply geography for vending machine manufacturing and influences premium pricing for smart features. This technological evolution drives a shift towards specialized electronics suppliers and value-added service contracts.
Pricing Analysis
Configured-to-order pricing for integrated smart vending solutions commands a premium over standard, off-the-shelf traditional machines. The dominant pricing model remains per-unit transactional for machine sales, complemented by SaaS-tiered subscriptions for software and data analytics services. Customization level and after-sales service contracts are key price differentiation drivers. Smaller operators demonstrate higher price sensitivity compared to large corporate clients seeking advanced unattended retail solutions.
Supply Chain Analysis
Strategic-stockpile preferences for critical electronic components contrast with just-in-time delivery for standard mechanical parts in vending machine manufacturing. Geographic supply concentration for advanced electronics centers on China, Japan, and Taiwan. Key raw material dependencies include specialized microcontrollers, refrigeration units, and high-grade sheet metal. Distribution typically runs through a network of regional distributors and direct sales to large vending operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail vending machine market faces a significant challenge in integrating disparate hardware and software systems, creating a capability scarcity in full-stack smart machine development. This integration complexity limits rapid deployment of advanced features and seamless operational intelligence.
For Market Incumbents: Shield existing market share by accelerating investment in proprietary software platforms and IoT connectivity. Consolidate regional distribution networks to enhance logistical efficiency against emerging asset-light competitors. The threat from agile software-centric new entrants necessitates continuous R&D in AI-powered analytics for predictive maintenance.
For New Entrants and Emerging Players: Differentiate on specialized product offerings, such as fresh food or personal care items, leveraging advanced dispensing technologies. Target underpenetrated segments like residential complexes and remote workplaces with curated micro-market solutions. A strong go-to-market angle involves partnering with mobile payment providers for seamless user experiences and integrated loyalty programs.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-agnostic platform providers capable of integrating diverse hardware. Long-term viability for the next decade centers on scalable software solutions that manage large, dispersed machine networks. A crucial signal to watch is the adoption rate of loyalty-linked mobile payment systems in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Maintenance | Optimizes machine uptime and reduces operational costs for large vending networks. |
| Expand into Unattended Micro-Markets | Captures demand for broader product selections in corporate and residential environments. |
| Integrate Advanced Mobile Payment Systems | Enhances user convenience and drives sales velocity in high-traffic locations like airports. |
| Invest in Energy-Efficient Refrigeration | Ensures compliance with EU CSRD regulations and reduces environmental footprint. |
| Form Strategic Partnerships with Logistics Firms | Streamlines inventory restocking and route optimization across dispersed machine fleets. |
Research Approach
Cross-validation between primary interviews and secondary financial disclosures anchors the qualitative findings and quantitative market sizing. Industry stakeholders interviewed included vending machine operators, component manufacturers, payment system integrators, and retail facility managers. Secondary data sources comprised government regulatory filings, trade association reports, and financial statements of public companies. This approach utilized both bottom-up market sizing and top-down validation to ensure data coherence.
Sensitivity analysis informed the forecast framework, accounting for variables like technological adoption rates and regulatory shifts across the analysis window. Segmentation dimensions modeled included product type, payment method, end-user environment, and machine type, alongside regional market maturity. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key forecast inputs included consumer spending patterns on convenience items and smart technology investment cycles.
Decision-makers should treat outputs as directional under current macroeconomic stability and steady consumer technology adoption; material deviation would warrant model refresh. Forecasts reflect assumptions regarding continued urbanization and regulatory support for unattended retail. Revision becomes warranted when major supply chain disruptions or significant shifts in digital payment infrastructure cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Consumer Products and Retail Market
Retailing
Electronics Retailing Market
Retailing
European Discount Retail Market
Retailing
Home Shopping Market
Retailing
Out-Door Signage Market
Retailing
China Retail Market
Retailing
Out Store Signage Market
Retailing
United States Hardware Stores Retail Market
Retailing
Singapore Gifting Market
Retailing
Retail Display Racks Market
Retailing
Department Stores Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Vietnam Retail Market
Retailing
Floor Displays Market
Retailing
Furniture Rental Service Market
Retailing
Qatar Retail Market