
 Consumer Shopping Cart Market | 2026-2036
Consumer Shopping Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Shopping Cart Market Outlook
The end-use vertical mix is broadening as e-commerce fulfillment centers expand cart procurement alongside traditional brick-and-mortar retailers. Wanzl dominates European manufacturing scale with in-house steel fabrication capabilities. Amazon.com Inc. leverages its captive retail ecosystem to pilot sensor-embedded cart fleets. Guangdong Winleader sustains cost leadership through integrated plastic injection molding operations in southern China.
Consumer shopping carts are wheeled material-handling devices constructed from zinc-plated steel wire, aluminum tubing, or high-density polyethylene, designed to transport merchandise through retail environments with load capacities typically ranging from 100 to 250 kilograms. Their primary commercial purpose centers on reducing shopper fatigue, extending store dwell time, and enabling higher basket sizes per visit. Manual carts still occupy the largest volume share across supermarket applications, though motorized variants for accessibility are capturing margin pools in aging demographics. Plastic trolleys are displacing metal in humid climates and coastal regions where corrosion resistance determines replacement cycles.
The EU's Ecodesign for Sustainable Products Regulation and REACH chemical compliance frameworks constrain material sourcing for carts sold across member states, while the US EPA pushes recycled content thresholds through state-level procurement mandates. China's GB standards for metallic products and SAMR quality certification shape export eligibility for Asian manufacturers. Stakeholders must track evolving durability testing protocols and carbon-border adjustment mechanisms that will reshape supplier qualification criteria and regional cost structures.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is forcing manufacturers to reengineer material compositions and supply chains for recycled steel and aluminum content, reshaping procurement qualification criteria across supermarket chains.
Growth Catalysts
- Smart cart embedded systems:Supermarket chains are deploying scanner-integrated and payment-enabled carts to reduce checkout friction and extend shopper dwell time. This technology pull concentrates in German retail clusters.
- REACH chemical compliance:The European framework creates material sourcing standards that favor established suppliers with certified supply chains, accelerating consolidation among compliant manufacturers.
- Motorized accessibility variants:Aging demographics in Japan and Western Europe are expanding procurement of powered carts, opening margin pools beyond standard manual units.
Market Restraints
- Steel and aluminum input volatility:Zinc-plated wire and aluminum tubing costs fluctuate with energy-intensive smelting economics, compressing fabrication margins for European producers.
- Supply concentration in southern China:Integrated plastic injection molding clusters around Guangdong create dependency risks for polyethylene trolley sourcing.
- Corrosion-driven replacement cycles:Metal cart durability fails in humid coastal climates, shortening asset life and raising total cost of ownership for tropical retailers.
Strategic Opportunities
- E-commerce fulfillment center procurement:Warehouse automation is creating cart demand from logistics operators previously outside traditional retail supply chains.
- Carbon-border adjustment mechanisms:Emerging EU trade instruments will penalize high-carbon imports, creating competitive advantage for regional manufacturers with green steel sourcing.
- Sensor-embedded fleet pilots:Convergence of RFID tracking and weight-sensing technology enables real-time inventory and shopper analytics for data-driven retailers.
Industry Challenges
- Dual certification timelines:Manufacturers must parallel-track GB standard compliance for Chinese exports and REACH documentation for EU market access, extending product launch cycles.
- Legacy fleet integration complexity:Smart cart deployment requires retrofitting store infrastructure for wireless charging and data connectivity, raising implementation friction for established chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Shopping Cart Market |
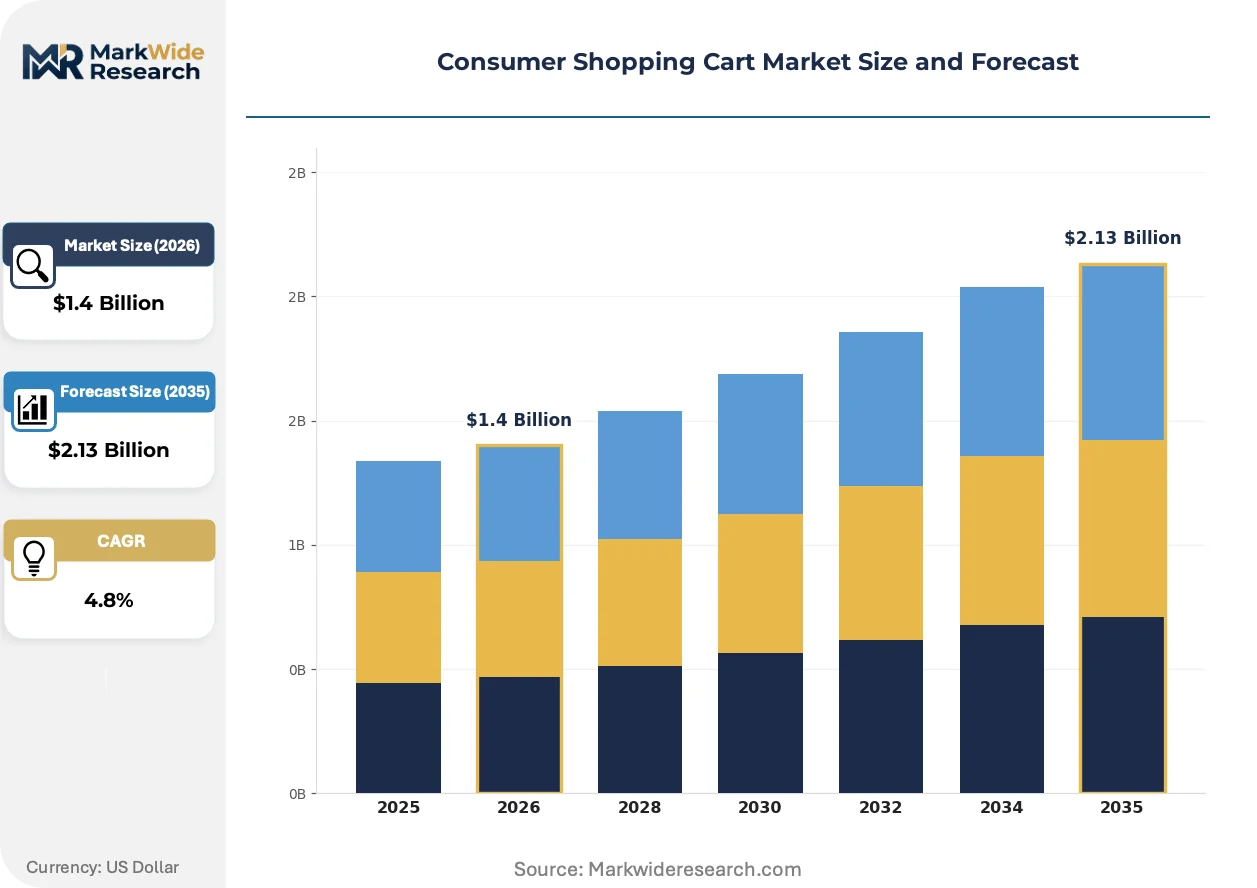
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Carts, Motorized Carts, Folding Carts, Basket Carts, Plastic Trolleys, Metal Trolleys Application: Supermarkets, Department Stores, E-Commerce Fulfillment, Convenience Stores, Specialty Stores, Warehouse Clubs Distribution Channel: Retail Chains, Online Marketplaces, Direct Sales, Wholesale Distributors, Rental Services, Private Label Brands Customer Type: Individual Shoppers, Family Buyers, Senior Citizens, College Students, Corporate Buyers, Institutional Clients |
| Companies Covered | Amazon.com Inc., Caper Inc., Wanzl, Shopic Ltd., Veeve Systems, Unarco, Walmart Inc., Cust2Mate Ltd., Guangdong Winleader, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Shopping Cart Market Strategic Shifts
Active sensor fusion and modular material platforms are compressing the boundary between traditional material-handling equipment and connected retail infrastructure. These developments are redrawing supplier capability requirements.
Embedded scanner-payment systems are unifying checkout functionality with merchandise transport. German supermarket chains are piloting these units at scale. This convergence is compressing the traditional checkout hardware supply chain into cart manufacturing.
REACH substance restrictions and the EU Green Deal are tightening chemical disclosure and recycled content mandates for metallic products. Manufacturers must now document supply chain carbon intensity to maintain market access. Plastic trolley suppliers with closed-loop polyethylene recycling are capturing preference in coastal markets.
Retailers are consolidating procurement through direct manufacturer relationships, bypassing traditional distribution intermediaries. Large supermarket chains now negotiate fleet specifications directly with Wanzl and Asian producers. This pattern concentrates in Germany and is spreading to French and UK retail consolidation.
Consumer Shopping Cart Market Segmentation
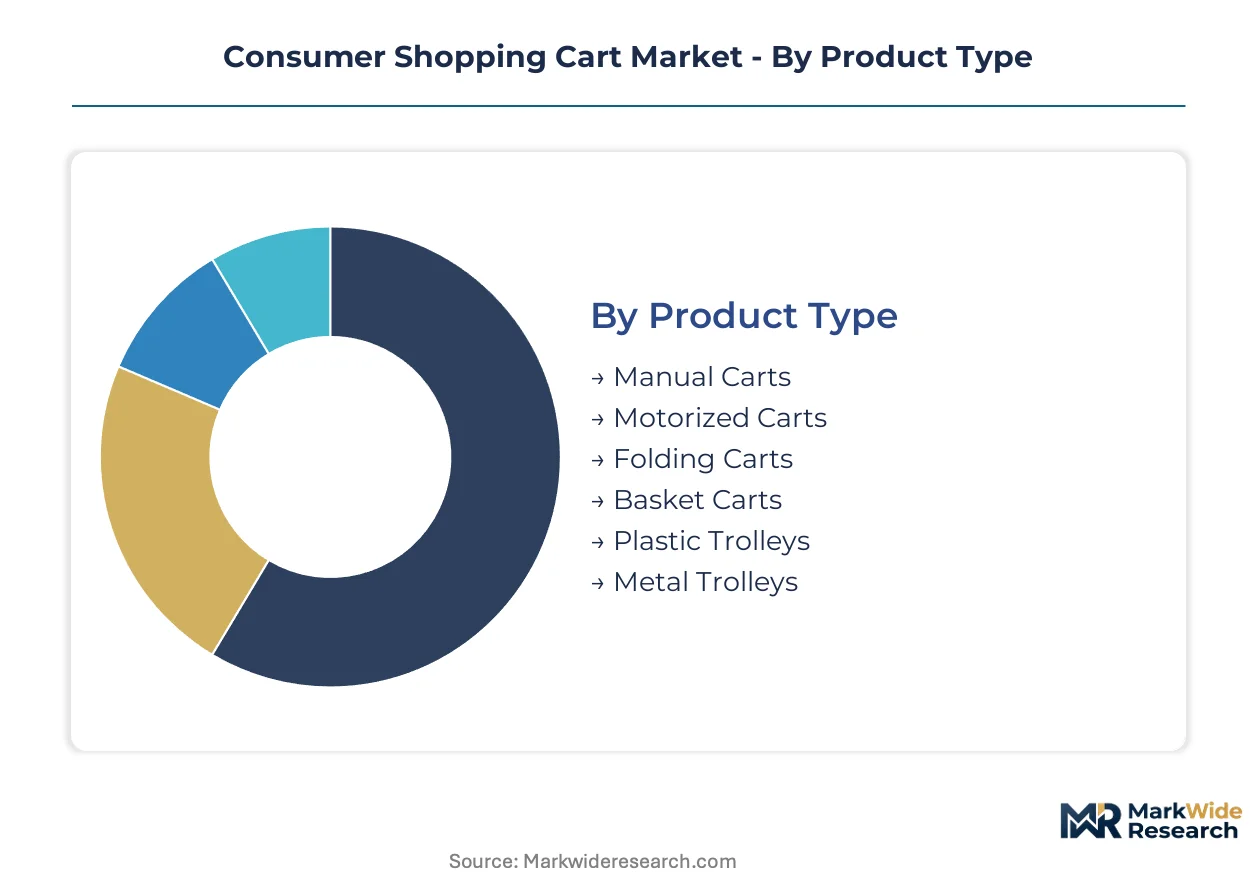
Shopping cart procurement splits across fundamentally different buyer economics. Supermarket chains negotiate fleet specifications directly with manufacturers, while e-commerce operators source through logistics intermediaries with diverging durability requirements.
Product Type:
Material composition and propulsion method separate buyers by climate exposure and labor cost structure.
- Manual Carts:Zinc-plated steel wire construction dominates volume procurement across temperate-zone supermarkets. German retail clusters anchor continental demand for standardized 180-liter wire basket units with polymer child seats.
- Motorized Carts:Battery-assisted propulsion systems with ergonomic throttle controls serve aging demographics in Japan and Western Europe. These units command premium positioning through accessibility compliance mandates in public retail spaces.
- Folding Carts:Collapsible aluminum frames with fabric bag inserts target urban apartment dwellers with storage constraints.
- Basket Carts:Compact two-tier designs with rigid plastic bases concentrate in convenience store formats with narrow aisle geometry.
- Plastic Trolleys:High-density polyethylene shells resist corrosion in coastal Brazil and Southeast Asian humidity zones.
- Metal Trolleys:Tubular aluminum and stainless steel variants persist in warehouse clubs requiring 250-kilogram load ratings.
Volume sits with Manual Carts; growth tilts toward Motorized Carts.
Application:
Foot traffic patterns and basket size economics determine fleet specification intensity.
- Supermarkets:Full-size wire carts with integrated scanner mounts anchor German smart-cart pilot programs. Chains specify modular bases accommodating payment terminal retrofits.
- E-Commerce Fulfillment:Flat-bed trolleys with RFID tracking brackets serve warehouse automation systems. Amazon and regional logistics operators procure specialized units outside traditional retail supply chains.
- Department Stores:Elevator-compatible carts with soft-goods protection rails concentrate in multi-level urban formats.
- Convenience Stores:Compact half-basket designs with single swivel casters navigate tight Tokyo and Seoul convenience formats.
- Specialty Stores:Branded color-matched carts with logo panels support pharmacy and electronics retail identities.
- Warehouse Clubs:Heavy-duty flatbeds with perimeter railings handle bulk packaged goods in Costco and Metro AG formats.
Supermarkets retain procurement volume leadership; E-Commerce Fulfillment climbs the fastest.
Distribution Channel:
Channel selection reflects buyer scale and specification control requirements.
- Retail Chains:Direct manufacturer negotiations bypass distribution intermediaries. French and UK supermarket consolidation accelerates this pattern.
- Direct Sales:Wanzl and Guangdong Winleader maintain captive sales forces for enterprise fleet contracts.
- Online Marketplaces:Alibaba and regional B2B platforms serve smaller independent retailers with standardized specifications.
- Wholesale Distributors:Regional warehousing networks cover replacement parts and smaller fleet orders.
- Rental Services:Short-term fleet provision supports seasonal retail peaks and temporary store formats.
- Private Label Brands:Supermarket-owned specifications manufactured through contract arrangements.
Retail Chains dominate transaction value; Direct Sales expands most quickly.
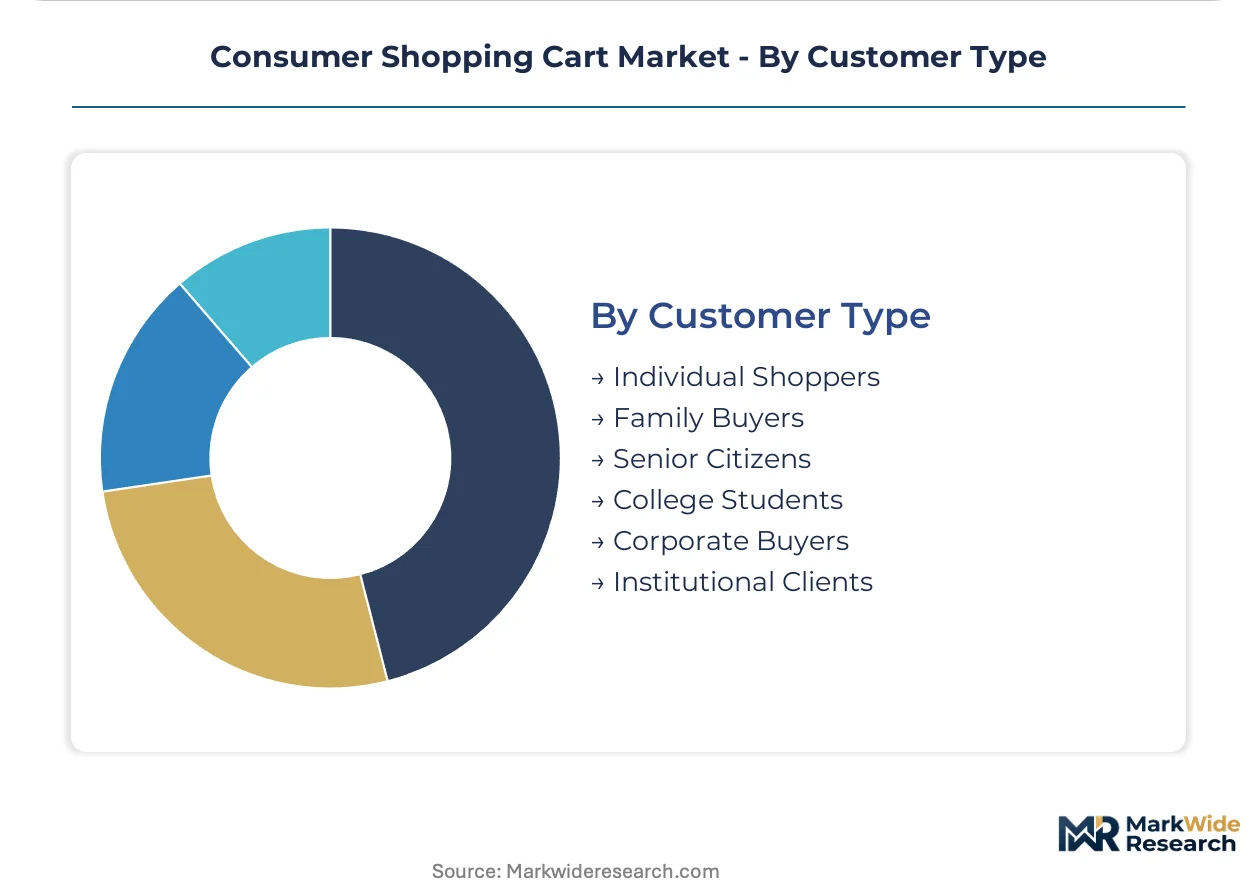
Customer Type:
Demographic and organizational buyer categories shape feature prioritization.
- Corporate Buyers:Procurement departments at supermarket headquarters negotiate multi-year fleet replacement cycles with total-cost-of-ownership modeling.
- Senior Citizens:Individual purchasers of lightweight folding carts for personal transport needs concentrate in Japan and Italy aging demographics.
- Family Buyers:Dual-child-seat configurations with safety harnesses drive feature requests in suburban North American and Australian formats.
- Individual Shoppers:Single-household cart ownership for apartment living and local market visits.
- College Students:Compact folding units for dormitory laundry and grocery transport.
- Institutional Clients:Hospital and airport procurement of specialized transport units with braking systems.
Corporate Buyers command volume; Senior Citizens gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters anchor European production capacity for wire-basket and smart-cart manufacturing, while Chinese injection-molding zones in Guangdong Province supply corrosion-resistant polyethylene units to tropical markets.
Germany
Wanzl anchors continental manufacturing with captive steel-fabrication facilities serving supermarket chains across the EU. The Ecodesign for Sustainable Products Regulation mandates recycled aluminum and steel content thresholds for carts sold in member states. Production concentrates in Leipheim and other Bavarian industrial zones where REACH-compliant supply chains maintain certification documentation.
China
Guangdong Winleader and Pearl River Delta fabricators dominate high-density polyethylene trolley exports for humid Southeast Asian climates. GB standards for metallic products and SAMR quality certification shape export eligibility protocols. Integrated injection-molding clusters in Foshan and Dongguan achieve cost leadership through captive resin sourcing and automated assembly lines.
United States
Amazon pilots sensor-embedded cart fleets through its captive retail ecosystem, while Unarco serves warehouse club procurement with heavy-duty flatbed specifications. State-level EPA recycled-content mandates press manufacturers toward post-consumer steel sourcing. Midwest distribution hubs in Illinois and Ohio coordinate fleet replacement cycles for national supermarket chains.
Japan
METI accessibility guidelines expand procurement of motorized carts with ergonomic throttle controls for aging demographic profiles in Tokyo and Osaka retail formats. JIS standards govern durability testing protocols for public-space deployment. Manufacturing concentrates in the Chubu region around Nagoya, where automotive-tier suppliers apply precision fabrication to battery-assisted propulsion systems.
Brazil
Coastal humidity in Rio de Janeiro and São Paulo accelerates plastic trolley displacement of zinc-plated wire units. ANVISA sanitation protocols for retail equipment influence material selection in food-contact applications. Regional assemblers in Minas Gerais source polyethylene shells from Mercosur trade-zone suppliers to avoid import duty exposure.
Consumer Shopping Cart Market Competitive Environment
Top-tier vendors anchor European steel fabrication and smart-cart technology, while mid-tier Chinese producers compete on polyethylene unit economics. The vendor base separates into three strategic archetypes: integrated metal fabricators with captive galvanizing lines, plastic injection molders with closed-loop recycling, and technology licensors embedding scanner-payment modules. Capacity expansion and direct retail chain contracting represent the dominant competitive moves reshaping procurement relationships.
Among German-based metal fabricators, Wanzl GmbH occupies the premium-tier position exemplifying REACH-compliant supply chain documentation and in-house steel processing. Guangdong Winleader Co., Ltd. represents the scale-driven Chinese archetype with integrated southern China manufacturing. Amazon.com Inc. anchors the technology-licensor segment, piloting sensor-embedded fleets through captive retail infrastructure rather than open market supply.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Caper Inc. |
| Wanzl |
| Shopic Ltd. |
| Veeve Systems |
| Unarco |
| Walmart Inc. |
| Cust2Mate Ltd. |
| Guangdong Winleader |
| Others |
Value Chain & Pricing Dynamics
Family-owned European metal fabricators anchor premium-tier supply, enabling disciplined pricing through captive galvanizing lines and long-tenured supermarket relationships that resist spot-market volatility. This ownership structure concentrates procurement leverage with incumbent producers while compressing margin pools for contract manufacturers without backward integration into steel processing.
Pricing Analysis
Lead-time premiums separate urgent fleet replacements from scheduled procurement cycles, with supermarket chains paying markups for 30-day delivery windows versus standard 90-day production schedules. Three-tier pricing structure across premium smart-cart, standard wire-basket, and economy plastic-trolley levels reflects certification burden and embedded technology content. Cost compression in economy polyethylene units is intensifying because Guangdong injection molders compete on resin sourcing scale. Corporate buyers at German retail headquarters exhibit lowest price sensitivity due to total-cost-of-ownership modeling that weights durability over unit cost.
Supply Chain Analysis
Direct-to-retail-chain channels handle hyperscale fleet procurement, bypassing wholesale distributors for specification control and volume pricing. Manufacturing gravity centers on Germany, China, and the United States, with each hub serving distinct buyer archetypes through differentiated material platforms. Raw material feeds draw from zinc-plated steel wire, high-density polyethylene resin, and aluminum tubing markets subject to energy-intensive smelting economics. Single-source vulnerability concentrates in southern Chinese injection-molding clusters serving corrosion-resistant trolley demand across Southeast Asian humidity zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints at REACH-certified galvanizing facilities prop pricing discipline, creating supply-constrained conditions that favor incumbent metal fabricators with compliant documentation. This bottleneck limits fleet expansion velocity for supermarket chains requiring rapid smart-cart deployment.
For Market Incumbents: Hedge against polyethylene displacement in coastal markets by accelerating closed-loop recycling certification for aluminum trolley lines. Defensive consolidation through captive steel sourcing in Bavarian industrial zones offsets margin pressure from Chinese resin-based competitors. Prioritize smart-cart retrofit modules that extend legacy fleet utility without full replacement cycles.
For New Entrants and Emerging Players: Alibaba B2B platforms offer lowest-friction entry for standardized plastic trolley specifications targeting independent retailers outside consolidated chain procurement. E-commerce fulfillment center procurement represents the most penetrable white-space segment, with logistics operators previously outside traditional retail supply chains. Pursue direct contracting with regional warehouse automation integrators rather than competing for supermarket fleet tenders.
For Investors and Strategic Acquirers: Amazon's sensor-embedded fleet pilot expansion is the leading indicator that smart-cart technology convergence will reshape supplier qualification criteria and valuation multiples. Long-term viability favors manufacturers with dual certification capability for EU REACH and Chinese GB standards. Watch for carbon-border adjustment mechanism implementation signals that would penalize high-carbon import exposure and elevate regional European producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Cart Technology Integration | Embedded scanner-payment modules compress checkout hardware supply chains into cart manufacturing. |
| Recycled Content Certification | EU Ecodesign mandates favor producers with documented green steel and aluminum sourcing. |
| Direct Retail Chain Contracting | Bypassing distribution intermediaries concentrates procurement leverage with Wanzl and Asian producers. |
| E-Commerce Fulfillment Expansion | Amazon and logistics operators create cart demand outside traditional supermarket supply chains. |
| Closed-Loop Plastic Recycling | Polyethylene trolley suppliers with circular resin systems capture preference in coastal humidity markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with supermarket procurement directors, cart manufacturing plant managers, logistics automation engineers, and REACH compliance officers. Secondary validation drew from EU Ecodesign implementation documents, SAMR certification databases, EPA state-level procurement mandates, and steel industry association production statistics. Bottom-up fleet replacement modeling triangulated against top-down retail sector capital expenditure patterns.
Granularity-level framing applied country-specific production capacity estimates, material-type splits across zinc-plated steel and high-density polyethylene, and application segmentation between supermarket and e-commerce fulfillment deployments. CAGRs derived from regression analysis of historical fleet procurement cycles against retail square footage expansion and automation capital deployment trends. Industry-specific inputs included corrosion-driven replacement frequency in tropical climates and smart-cart pilot program adoption velocity in German retail clusters.
The model holds under stable regulatory enforcement timelines for REACH and Ecodesign compliance; deviation in carbon-border adjustment acceleration or Chinese export quota restrictions would shift regional cost structures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Global Food and Non-Food Retail Market
Retailing
Clothing Retail Market
Retailing
Furniture Rental Service Market
Retailing
Singapore Gifting Market
Retailing
Retail Display Racks Market
Retailing
Qatar Retail Market
Retailing
Philippines Retail Industry Market
Retailing
Retail Vending Machine Market
Retailing
Retail Signage Market
Retailing
Electronics Retailing Market
Retailing
Consumer Products and Retail Market
Retailing
Out Store Signage Market
Retailing
China Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Vietnam Retail Market
Retailing
North America Retail Vending Machine Market