
 Philippines Retail Industry Market | 2026-2036
Philippines Retail Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Retail Industry Market Insights
Subscription-based loyalty programs is realigning how retailers monetize repeat purchases. SM Investments Corp. leverages its integrated mall-to-supermarket footprint to sustain customer lock-in across touchpoints. Puregold Price Club Inc. anchors its growth on sari-sari store wholesale supply chains that dominate provincial distribution. Philippine Seven Corp. differentiates through 24-hour convenience density in urban barangays.
The Philippines retail industry encompasses the sale of consumer goods through physical and digital channels, spanning inventory management systems, cold-chain logistics for fresh categories, and point-of-sale technology integration. Its primary purpose is to bridge producers with fragmented household demand across an archipelagic geography. Electronics commands the largest product category spend due to gadget upgrade cycles and remittance-linked purchasing power. Online sales channels represent the fastest-growing structural segment as mobile wallet penetration deepens. Convenience stores remain the most mature format with saturated metro coverage and thin margin pools.
The Department of Trade and Industry shapes retailer compliance through consumer protection and fair trade regulations, while the Bangko Sentral ng Pilipinas governs digital payment rails that enable e-commerce expansion. Local government units enforce business permitting and zoning rules that directly affect store rollout timelines. Stakeholders must monitor how logistics cost differentials between island clusters influence fulfillment economics and format selection.
Market Dynamics
The Department of Trade and Industry's e-commerce roadmap is compressing digital payment adoption timelines across Philippine retail channels, forcing traditional operators to reconfigure fulfillment infrastructure around mobile wallet rails.
Growth Catalysts
- Mobile wallet penetration:GCash and Maya adoption among young Filipino professionals is accelerating online grocery basket sizes. The Bangko Sentral ng Pilipinas' regulatory sandbox for digital banks expands credit access for unbanked consumers.
- Remittance-linked purchasing power:Overseas Filipino Worker inflows sustain electronics upgrade cycles in Metro Manila retail corridors. This demand concentration supports premium format expansion in urban barangays.
- Sari-sari store formalization:The Department of Trade and Industry's micro-enterprise registration programs unlock wholesale credit terms for provincial distributors. Cold-chain logistics investments follow this channel consolidation.
Market Restraints
- Archipelagic logistics costs:Inter-island shipping rate volatility compresses margin pools for fresh category retailers. Fuel price shocks disproportionately affect Visayas and Mindanao fulfillment economics.
- Metro Manila saturation:Convenience store density in urban barangays approaches carrying capacity. Thin same-store sales growth forces format operators into marginal locations with lower foot traffic.
- Digital infrastructure gaps:Last-mile connectivity limitations in provincial clusters constrain real-time inventory visibility. This technical limitation delays omnichannel rollout timelines outside Luzon.
Strategic Opportunities
- Visayas-Mindanao corridor expansion:Underpenetrated secondary cities in Cebu and Davao present whitespace for integrated mall-to-supermarket formats. Logistics cost differentials favor early movers with captive distribution.
- QR code payment convergence:Interoperability between GCash, Maya, and bank-owned wallets is integrating with point-of-sale systems. This technology convergence reduces checkout friction in sari-sari stores.
- Subscription loyalty programs:Tiered membership models monetize repeat purchase behavior across touchpoints. Retailers with integrated physical-digital footprints capture recurring revenue streams.
Industry Challenges
- Cold-chain technician scarcity:Specialized refrigeration maintenance skills are concentrated in Metro Manila. Provincial expansion requires training programs or third-party service contracts.
- Legacy system integration:Sari-sari store wholesale networks operate on informal credit tracking. Digitizing these relationships demands change management without disrupting trust-based arrangements.
- Local government permitting variance:Zoning approval timelines differ across city and municipal jurisdictions. This regulatory fragmentation complicates national rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Retail Industry Market |
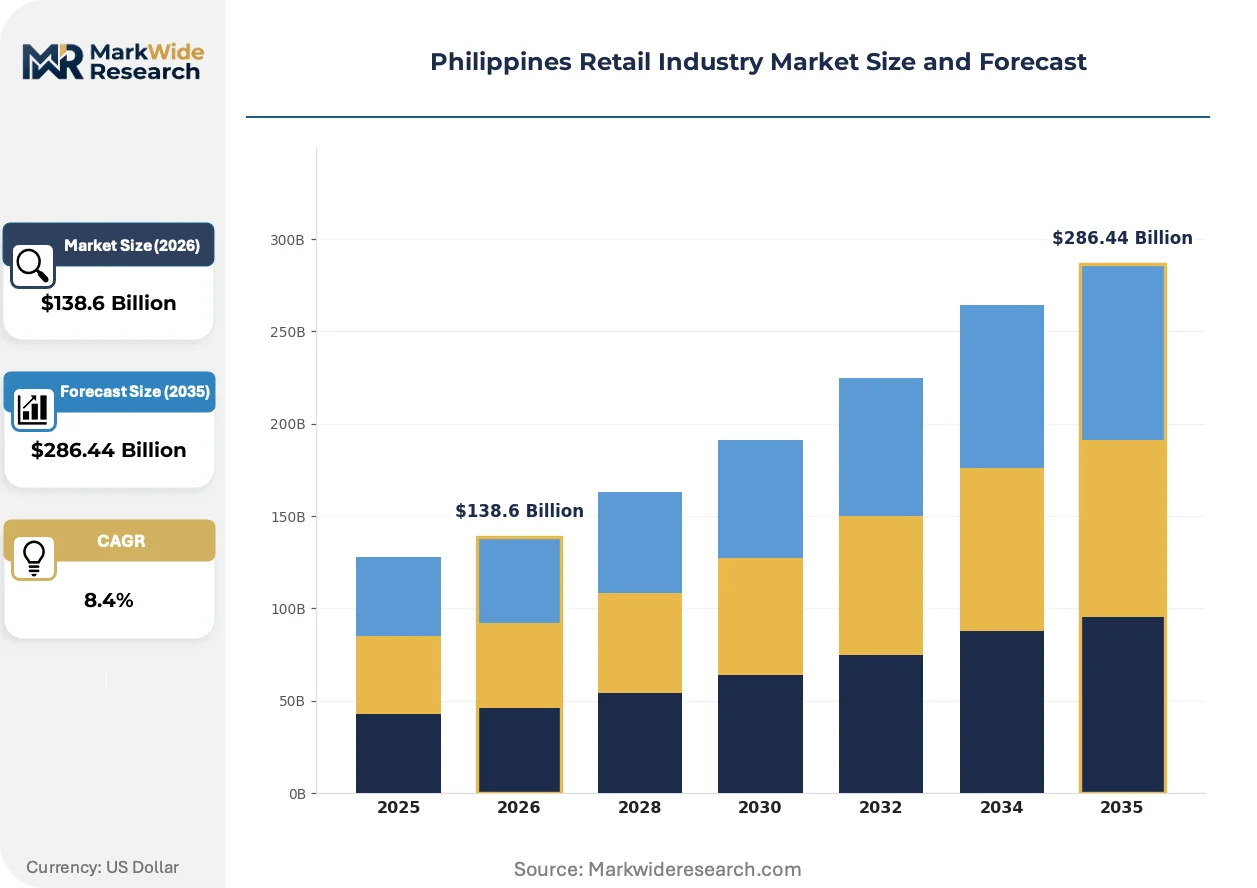
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $286.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Apparel, Electronics, Home Goods, Personal Care Customer Segment: Millennials, Professionals, Families, Students Sales Channel: Online, Supermarkets, Department Stores, Convenience Stores Pricing Strategy: Discount, Premium, Mid-Range, Value |
| Companies Covered | Metro Retail Stores Group Inc., Philippine Seven Corp. (7-Eleven), SM Investments Corp. (SM Retail), AllDay Supermarket, Gaisano Capital Group, Robinsons Retail Holdings Inc, SSI Group Philippines, Alfamart Philippines, Puregold Price Club Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Retail Industry Market Trends and Innovations
Philippine retail is reconfiguring around three simultaneous shifts: payment digitization, logistics network densification, and format hybridization that blurs wholesale and consumer-facing operations.
Artificial intelligence-driven demand forecasting is integrating with legacy inventory management systems in supermarket chains. SM Investments Corp. and Puregold Price Club Inc. are deploying machine learning models to reduce fresh produce spoilage rates. This technology compression is enabling just-in-time replenishment from provincial distribution centers.
The Bangko Sentral ng Pilipinas' National Payment Systems Act is mandating interoperability between e-wallet providers and traditional banking rails. This regulatory framework forces retail payment aggregators to support multiple settlement channels. Convenience store operators are responding by upgrading point-of-sale terminals to accept unified QR codes.
Young Filipino professionals are consolidating grocery purchases into fewer, larger online baskets with scheduled delivery windows. This behavioral shift displaces daily sari-sari store visits in Metro Manila's logistics corridor. Provincial households maintain hybrid patterns, combining weekly supermarket trips with emergency convenience store purchases.
Philippines Retail Industry Market Segmentation

Segmentation in Philippine retail reveals how archipelagic geography fragments demand across distinct customer cohorts and channel preferences. Operators must calibrate format selection and pricing architecture to match these divergent consumption patterns.
Product Category:
Supply concentration in electronics manufacturing shapes category-level margin structures and inventory velocity across Philippine retail networks.
- Electronics:Smartphone and gadget upgrade cycles dominate transaction values, with remittance-linked purchasing power concentrating demand in Metro Manila mall corridors. Cold-chain requirements are minimal, permitting flexible fulfillment from China-direct import channels.
- Apparel:Fast-fashion inventory turns rapidly through integrated mall formats, while formal wear concentrates in department store anchors. Seasonal demand spikes around holiday remittance periods strain provincial distribution capacity.
- Home Goods:Bulky furniture and appliances require dedicated last-mile logistics networks that favor operators with captive trucking fleets.
- Personal Care:High-frequency replenishment drives convenience store penetration in dense urban barangays.
Today's leader: Electronics. Tomorrow's challenger: Personal Care.
Customer Segment:
Cost tier differentiation separates mass-market operators from premium format specialists targeting distinct income brackets.
- Professionals:Time-constrained white-collar workers in Metro Manila and Cebu consolidate purchases into scheduled online grocery deliveries with mobile wallet settlement. Subscription loyalty programs capture recurring revenue from this cohort.
- Millennials:Digital-native consumers blend social commerce discovery with convenience store impulse purchases, driving QR code payment adoption at sari-sari store networks.
- Families:Weekly supermarket stock-up trips dominate household budgeting, with price sensitivity highest in provincial clusters.
- Students:Limited disposable income channels demand toward value-priced formats and discount-driven online flash sales.
Professionals command current spending velocity. Millennials present the steepest expansion trajectory as mobile wallet penetration deepens.
Sales Channel:
Application-based channel selection reflects how Filipino households balance convenience, price transparency, and immediate gratification needs.
- Online:Mobile-first platforms capture grocery basket consolidation among young professionals, with scheduled delivery windows displacing daily convenience store visits in Metro Manila's logistics corridor. Real-time inventory visibility remains constrained outside Luzon.
- Convenience Stores:24-hour density in urban barangays approaches saturation, forcing operators into marginal locations with compressed margins.
- Supermarkets:Weekly family stock-up trips anchor fresh category demand, with cold-chain investments following provincial expansion timelines.
- Department Stores:Mall-anchored formats sustain apparel and electronics discovery shopping, integrated with supermarket footprints for cross-selling.
Convenience stores retain volume leadership. Online channels are gaining share fastest as digital payment infrastructure matures.
Pricing Strategy:
Margin architecture varies sharply across pricing tiers, with operational cost structures determining viable competitive positioning.
- Value:Sari-sari store wholesale networks and discount formats target price-sensitive provincial households, with thin margins offset by inventory velocity.
- Discount:Promotional pricing drives traffic in supermarket weekly circulars, particularly effective for family segment acquisition.
- Mid-Range:Balanced quality-price positioning captures professional and millennial segments seeking brand reliability without premium markup.
- Premium:Remittance-linked purchasing power in Metro Manila supports upscale format expansion, with electronics and apparel commanding highest tier pricing.
Value pricing dominates transaction frequency. Premium positioning offers the most attractive margin expansion pathway.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail investment flows toward sub-regions where local government permitting variance creates compliance cost arbitrage, accelerating format rollout in jurisdictions with streamlined business registration.
Metro Manila
Young Filipino professionals drive online grocery consolidation through scheduled delivery platforms, with mobile wallet settlement displacing daily sari-sari store visits. The Department of Trade and Industry's e-commerce roadmap compresses digital payment timelines across Quezon City and Makati logistics corridors. Convenience store density approaches saturation in urban barangays, forcing operators into marginal locations.
Central Luzon
Provincial household demand for weekly supermarket stock-up trips anchors fresh category growth, with cold-chain investments following distribution center expansion. Local government units in Bulacan and Pampanga enforce streamlined business permitting that accelerates store rollout timelines. Sari-sari store formalization programs unlock wholesale credit terms for regional distributors.
Calabarzon
Integrated mall-to-supermarket formats capture remittance-linked electronics purchasing power concentrated in Cavite and Laguna industrial zones. The Bangko Sentral ng Pilipinas' regulatory sandbox expands credit access for unbanked consumers in secondary cities. Logistics cost differentials favor early movers with captive distribution networks.
Visayas
Underpenetrated secondary cities in Cebu present whitespace for format expansion as inter-island shipping rate volatility compresses margin pools elsewhere. The Department of Trade and Industry's micro-enterprise registration programs channel investment toward provincial clusters. Cold-chain technician scarcity constrains fresh category rollout beyond Metro Cebu.
Mindanao
Davao's emerging logistics corridor attracts wholesale supply chain consolidation targeting sari-sari store networks. Fuel price shocks disproportionately affect fulfillment economics in southern island clusters. Digital infrastructure gaps in provincial municipalities delay real-time inventory visibility for omnichannel operators.
Philippines Retail Industry Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mall operators commanding premium positioning while wholesale distributors dominate provincial penetration. The vendor base concentrates around three strategic archetypes: conglomerate-affiliated retail platforms, convenience store density specialists, and sari-sari store supply chain operators. Competitive moves center on captive distribution investments and loyalty program tiering that monetizes repeat purchase behavior.
Within the conglomerate-affiliated tier, SM Investments Corp. and Robinsons Retail Holdings Inc. anchor integrated physical-digital footprints across Luzon. Philippine Seven Corp. exemplifies the convenience density specialist archetype through 24-hour urban barangay coverage. Puregold Price Club Inc. occupies the wholesale-supply position, formalizing sari-sari store credit relationships through provincial distribution networks.
| Leading Market Players |
|---|
| Metro Retail Stores Group Inc. |
| Philippine Seven Corp. (7-Eleven) |
| SM Investments Corp. (SM Retail) |
| AllDay Supermarket |
| Gaisano Capital Group |
| Robinsons Retail Holdings Inc |
| SSI Group Philippines |
| Alfamart Philippines |
| Puregold Price Club Inc |
| Others |
Pricing and Supply Chain Analysis
Young Filipino professionals consolidating online grocery purchases anchor the market's dominant subscription-loyalty pricing model, with scheduled delivery premiums offsetting last-mile cost volatility across Metro Manila's logistics corridor.
Pricing Analysis
Capacity additions in Central Luzon cold-chain infrastructure are reshaping price floors for fresh categories, compressing margins for operators without captive distribution. Three-tier pricing structure across premium supermarket, standard grocery, and value sari-sari tiers separates SM Investments Corp.'s mall-anchored formats from Puregold's wholesale networks and unbranded provincial stores. Price differentiation rests on cold-chain certification grade and geographic delivery cost to island clusters. Pricing pressure intensifies in convenience store tier due to Metro Manila saturation forcing marginal location entry. Provincial families exhibit highest price sensitivity, while remittance-linked professionals in urban barangays show lowest elasticity.
Supply Chain Analysis
The Department of Trade and Industry's micro-enterprise registration programs are reshaping sourcing requirements, formalizing credit relationships between wholesale distributors and sari-sari store networks. Supply concentration centers on China for electronics direct-import channels, Vietnam for apparel manufacturing, and domestic Luzon for fresh produce aggregation. Raw material dependencies include imported smartphone components, synthetic textile inputs, and temperature-controlled packaging for cold-chain categories. Single-source vulnerability in inter-island shipping routes exposes Visayas-Mindanao operators to fuel price volatility. Distribution runs through captive trucking fleets for integrated mall operators and third-party logistics aggregators for online grocery platforms.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines retail sector compounds steadily as mobile wallet penetration deepens, with GCash and Maya adoption creating durable payment infrastructure for recurring revenue capture.
For Market Incumbents: Deepen captive distribution investments in Visayas-Mindanao corridors before logistics cost differentials close, locking in provincial wholesale relationships through formalized credit terms. Defend against sari-sari store digitization threats by embedding QR code interoperability at point-of-sale terminals before challenger wallets gain merchant share. For New Entrants and Emerging Players: Capture underpenetrated secondary cities in Cebu and Davao through integrated mall-to-supermarket formats, exploiting whitespace left by convenience store saturation in Metro Manila. Target professional households with subscription loyalty programs monetizing scheduled grocery delivery consolidation, using mobile wallet-native onboarding to bypass legacy banking relationships. For Investors and Strategic Acquirers: Conglomerate-affiliated retail platforms are the most active acquirer in this space, consolidating provincial distribution networks to achieve logistics density. Long-term viability hinges on omnichannel integration capability across physical-digital footprints. Monitor Bangko Sentral ng Pilipinas regulatory sandbox expansions for digital bank licensing as inflection signal for credit-access-driven consumption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Reduces fresh produce spoilage rates for supermarket operators competing with sari-sari store velocity. |
| QR Code Payment Interoperability | Integrates GCash, Maya, and bank wallets with point-of-sale systems at sari-sari store networks. |
| Subscription Loyalty Program Launch | Captures recurring revenue from young professionals consolidating online grocery basket sizes. |
| Visayas-Mindanao Distribution Buildout | Exploits logistics cost arbitrage before inter-island shipping rate volatility compresses margins. |
| Sari-Sari Store Formalization Partnership | Unlocks wholesale credit terms through Department of Trade and Industry micro-enterprise registration. |
Research Methodology
Coverage spans Luzon, Visayas, and Mindanao, with primary inputs from each island cluster combined with secondary validation. Primary interviews engaged retail operations executives, provincial distribution managers, mobile wallet platform strategists, and cold-chain logistics specialists. Secondary sources included Bangko Sentral ng Pilipinas payment system reports, Department of Trade and Industry e-commerce roadmap filings, customs import records for electronics categories, and local government unit business permitting databases. Bottom-up store rollout timelines and top-down consumption expenditure patterns were triangulated to anchor projections.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with CAGRs derived from segment-level trajectory aggregation. Segmentation dimensions modeled include product category, customer segment, sales channel, pricing tier, and regional logistics corridor. Industry-specific forecast inputs incorporated mobile wallet transaction velocity trends and inter-island shipping rate indices.
Fuel price shocks, local government permitting delays, and digital infrastructure gaps in provincial municipalities are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Clothing Retail Market
Retailing
Furniture Rental Service Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
United States Hardware Stores Retail Market
Retailing
Consumer Shopping Cart Market
Retailing
Retail Display Racks Market
Retailing
Department Stores Market
Retailing
Global Food and Non-Food Retail Market
Retailing
In Store Signage Market
Retailing
Home Shopping Market
Retailing
Gift Baskets Market
Retailing
Retail Signage Market
Retailing
Qatar Retail Market
Retailing
Out Store Signage Market
Retailing
Floor Mat Rental Service Market
Retailing
Electronics Retailing Market