
 Asia-Pacific Home Furniture Market | 2026-2036
Asia-Pacific Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Home Furniture Market Outlook
GB 18580-2017 compliance for formaldehyde emission limits in wood-based panels is collapsing the supplier base in China's furniture heartland. Shunde Kinwai Furniture Co., Ltd. leverages integrated particleboard milling to sustain cost advantages across Guangdong province. Okamura Corporation anchors premium ergonomic seating through captive R&D centers in Japan. Godrej & Boyce Manufacturing Co. Ltd. dominates India's mass-market residential segment via deep distribution into Mumbai, Bangalore, and Hyderabad.
Asia-Pacific home furniture comprises movable articles designed for residential and commercial interior spaces, typically constructed from engineered wood, solid timber, metal framing, or upholstery composites with load-bearing specifications calibrated for daily use cycles. The category serves dwelling outfitting, workspace configuration, and hospitality environment assembly across varied climatic and cultural contexts. Sofas and chairs capture disproportionate margin pools in the residential channel as consumers prioritize comfort-driven replacement cycles. Metal and plastic material segments gain structural share in office and retail end-use applications where durability requirements override aesthetic preferences. Wood retains premium positioning in cabinets and tables where grain visibility and joinery craftsmanship command price differentiation.
China's SAMR enforces GB standards for volatile organic compound limits while India's BIS mandates ISI certification for furniture safety and structural integrity, creating dual compliance burdens for cross-border suppliers. Japan's METI administers JIS standards that govern office furniture dimensional tolerances and ergonomic benchmarks, shaping product development priorities for Kokuyo Co., Ltd. and Lamex Trading Co., Ltd. Stakeholders must monitor divergence between national certification regimes and assess whether localized testing investments outweigh market access returns in specific country corridors.
Market Dynamics
China's GB 18580-2017 formaldehyde emission standards are compressing engineered wood supplier margins across Guangdong and Zhejiang provinces, forcing material substitutions toward low-emission adhesives and certified timber sourcing. This regulatory pressure cascades through procurement chains, altering competitive positioning between integrated mills and import-dependent assemblers.
Growth Catalysts
- Urban residential construction:India's tier-2 cities including Pune, Ahmedabad, and Kochi are accelerating volume demand for modular storage and seating as mortgage penetration deepens and nuclear family formation rises.
- Hospitality renovation cycles:Indonesia's premium upholstery demand concentrates in Jakarta and Bali as international hotel chains refresh properties ahead of projected visitor recovery.
- GB standards enforcement:China's SAMR is consolidating the supplier base by disqualifying uncertified particleboard mills, creating volume capture opportunities for compliant integrated manufacturers.
Market Restraints
- Input cost volatility:Malaysian rubberwood and Indonesian meranti prices fluctuate with export permit restrictions and shipping lane congestion through the Strait of Malacca.
- Supply concentration risk:Particleboard production clusters in Guangdong's Shunde district, creating single-point vulnerability for downstream furniture assemblers dependent on just-in-time panel delivery.
- Regulatory friction:Cross-border suppliers face dual compliance burdens from China's GB volatile organic compound limits and India's BIS ISI certification requirements for structural integrity testing.
Strategic Opportunities
- Underpenetrated secondary cities:Vietnam's Da Nang and Hai Phong exhibit rising residential completion rates without proportional furniture retail presence, creating first-mover distribution advantages.
- E-commerce channel innovation:Live-streaming commerce platforms in China are collapsing traditional showroom-to-warehouse distribution layers for mass-market seating and storage categories.
- Technology convergence:CNC routing combined with AI-assisted design software enables mass customization of solid timber joinery at previously unattainable production economics.
Industry Challenges
- Skill scarcity in traditional joinery:Master craftsmen capable of hand-finished dovetail construction are aging out of China's Dongyang and Indonesia's Jepara clusters without adequate apprenticeship pipeline replacement.
- Certification timeline compression:Japan's METI JIS office furniture dimensional tolerance testing requires 12-16 week validation cycles that conflict with retail seasonal ordering windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Home Furniture Market |
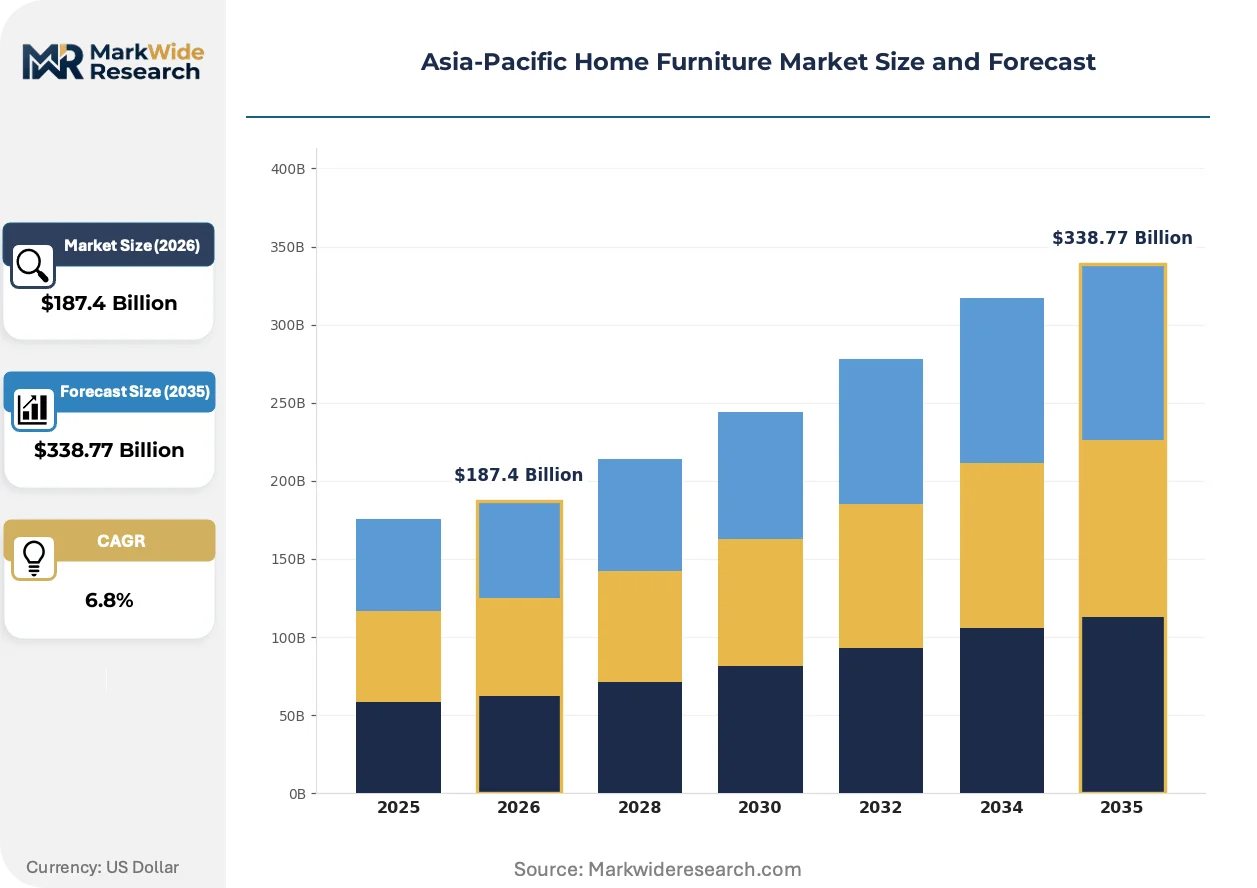
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Fabric, Metal, Plastic End User: Residential, Hospitality, Office, Retail Distribution Channel: Online, Offline, Retailers, Wholesalers |
| Companies Covered | Shunde Kinwai Furniture Co., Ltd., Foshan Sunon Furniture Co., Ltd., Qumei Home Furnishings Group, Okamura Corporation, Kokuyo Co., Ltd., Godrej & Boyce Manufacturing Co. Ltd., Damro Group, Markor Home Furnishings Co., Ltd., Lamex Trading Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Home Furniture Market Strategic Shifts
Material science advances and regulatory stringency are fragmenting production methodologies across the Asia-Pacific furniture base. Manufacturers must now navigate parallel technical pathways rather than unified platform strategies.
Cross-laminated timber (CLT) and mass plywood panel (MPP) systems are bifurcating residential furniture construction from conventional particleboard-dependent methods. Japanese multi-family developers and Australian prefabricated housing contractors specify these engineered wood products for structural furniture integration. The technology is bifurcating the supplier landscape into CLT-capable integrated mills versus legacy particleboard assemblers facing stranded capacity.
China's GB 18580-2017 and subsequent GB/T 39600-2021 formaldehyde emission classifications are mandating E0 and ENF grade panel certification for residential interior use. This regulatory architecture disqualifies approximately one-third of existing particleboard capacity in Guangdong province. Upholstered furniture manufacturers serving export markets are responding by captive integration into certified panel milling or exclusive sourcing agreements with state-owned forestry conglomerates.
Direct-to-consumer configuration platforms are displacing traditional wholesale showroom networks for modular storage systems. Chinese and South Korean buyers increasingly finalize dimensional specifications through augmented reality visualization tools before factory production commitment. This channel shift is most visible in Shanghai and Seoul metropolitan areas where apartment space constraints demand precise fit optimization unavailable through standard SKU retail.
Asia-Pacific Home Furniture Market Segmentation
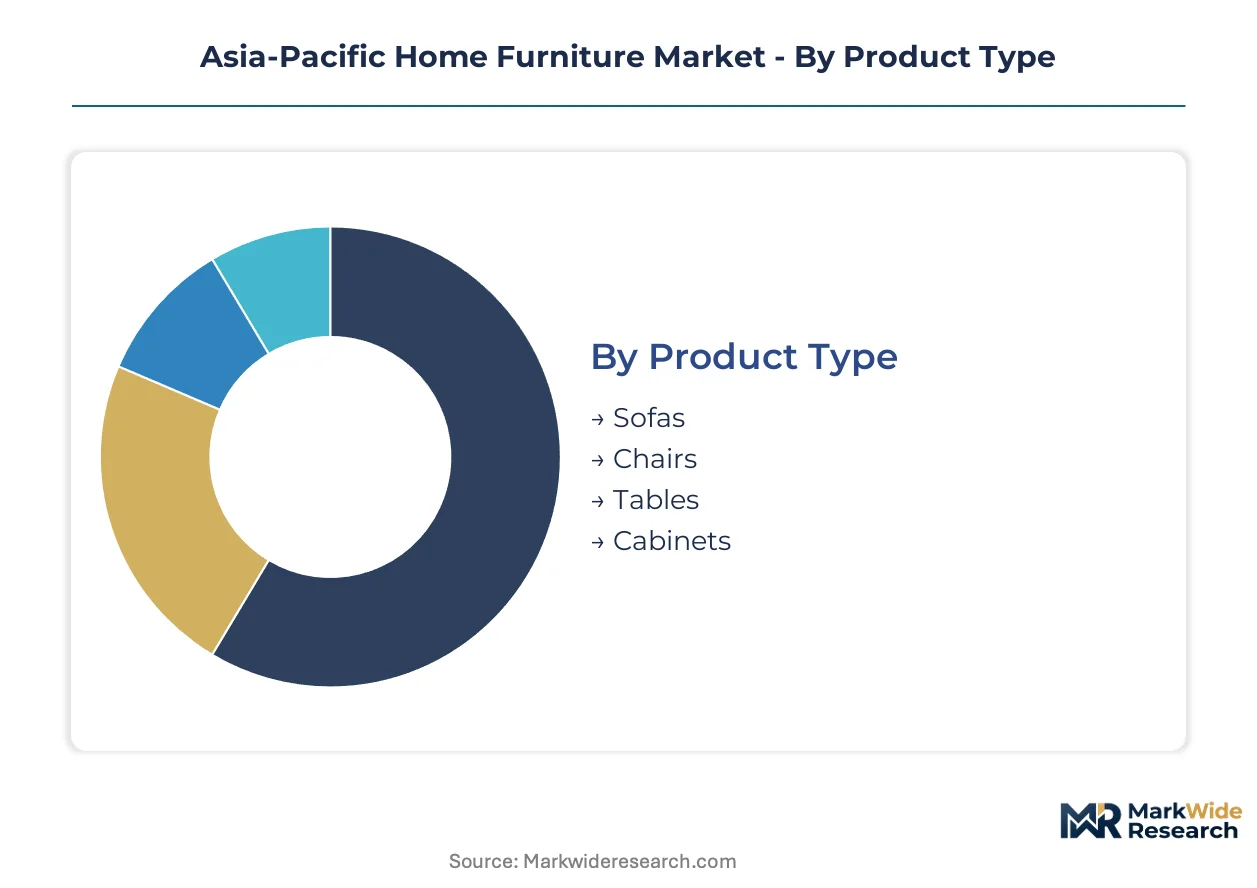
Segmentation reveals how margin pools concentrate across material grades, distribution channels, and end-use specifications in Asia-Pacific home furniture. Understanding these fault lines exposes where procurement power shifts and where certification requirements fragment supplier bases.
Product Type:
Margin capture diverges sharply between comfort-driven replacement categories and structural storage systems with longer depreciation cycles.
- Sofas:Upholstered seating commands premium pricing through foam density specifications and fabric durability ratings. Demand clusters in India's Mumbai and Bangalore residential towers where nuclear family formation accelerates refresh cycles.
- Chairs:Ergonomic task seating carries disproportionate margin in Japan's corporate procurement channels governed by METI JIS dimensional tolerance standards. Volume growth concentrates in China's live-streaming commerce platforms for mass-market dining and accent categories.
- Tables:Dining and occasional tables retain wood grain visibility as the primary price differentiator across Guangdong export clusters.
- Cabinets:Modular storage systems face margin compression from flat-pack logistics optimization and particleboard cost volatility.
The dominant share belongs to Sofas, while Chairs is closing the gap fastest.
Material:
Regulatory enforcement on emissions and supply concentration in tropical hardwoods are restructuring competitive economics across material inputs.
- Wood:Solid timber and engineered panels face divergent fates under China's GB 18580-2017 formaldehyde standards. E0 and ENF grade certification requirements disqualify uncertified Guangdong particleboard mills, compressing supply for downstream assemblers.
- Fabric:Upholstery textiles span performance grades from commercial-grade polyester blends to premium natural fibers. Indonesian hospitality renovation cycles in Jakarta and Bali are concentrating demand for stain-resistant synthetic weaves.
- Metal:Steel and aluminum framing gain structural share in office and retail applications where durability specifications override aesthetic preferences.
- Plastic:Polypropylene and polycarbonate components serve cost-optimized outdoor and children's furniture segments with shorter replacement horizons.
Wood retains volume leadership, though Fabric is expanding most quickly as upholstered seating penetrates India's tier-2 cities.
End User:
Procurement sophistication varies dramatically between specification-driven commercial buyers and price-sensitive residential consumers.
- Residential:Individual household purchases dominate absolute volume across China's urban completion corridors and India's mortgage-deepening markets. Replacement cycles compress as younger cohorts prioritize mobility over heirloom durability.
- Hospitality:International hotel chains in Indonesia and Thailand drive premium upholstery specifications with stringent fire-resistance and wear-testing protocols. Renovation timing concentrates demand in Jakarta and Bali ahead of visitor recovery projections.
- Office:Corporate procurement in Japan and South Korea emphasizes ergonomic certification and modular reconfiguration capabilities.
- Retail:Visual merchandising fixtures prioritize rapid deployment and seasonal refresh over structural longevity.
Residential captures the dominant share, while Hospitality is gaining share fastest as renovation backlogs clear across Southeast Asia.
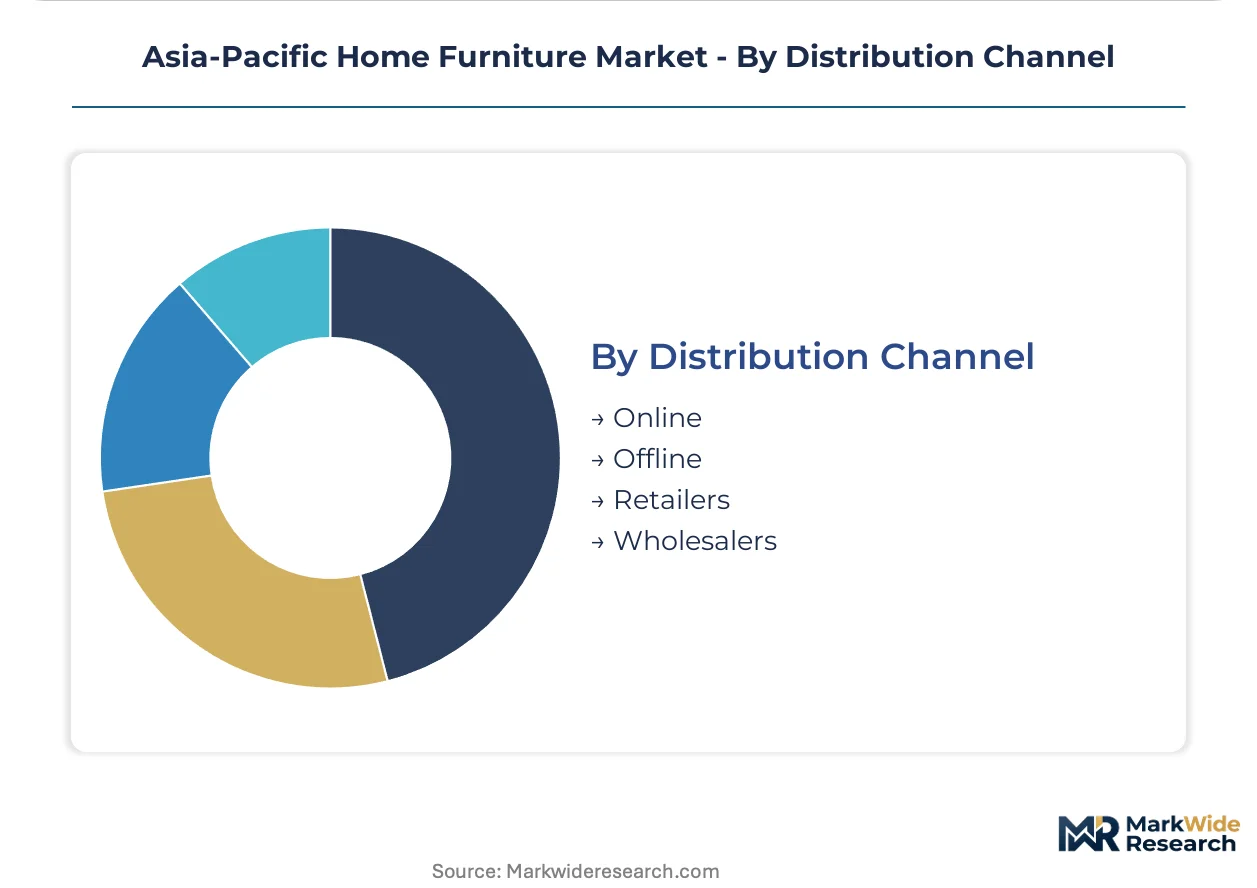
Distribution Channel:
Channel economics are fragmenting as live-streaming commerce collapses traditional showroom-to-warehouse layers in China's mass market.
- Online:Direct-to-consumer platforms enable augmented reality visualization for modular storage fit optimization. Shanghai and Seoul metropolitan buyers finalize dimensional specifications digitally before factory commitment.
- Offline:Physical showrooms retain importance for tactile evaluation of upholstery comfort and wood grain quality in premium segments.
- Retailers:Multi-brand furniture chains in India's Mumbai, Bangalore, and Hyderabad aggregate mass-market demand through deep distribution networks.
- Wholesalers:Project-specification channels serve hospitality and office end-users with volume pricing and customized finishing capabilities.
Offline maintains the dominant share, though Online is climbing the fastest as digital penetration deepens in China's tier-1 cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers dominate procurement across Asia-Pacific, with nuclear family formation in Indian tier-2 cities and space-constrained urban households in Chinese megacities driving divergent demand patterns. Commercial specification buyers in Japan and hospitality chains in Indonesia operate on fundamentally different procurement calendars and certification requirements.
China
Urban completion corridors in Shanghai and Shenzhen sustain volume demand for modular storage optimized through augmented reality configuration tools. SAMR enforcement of GB 18580-2017 and GB/T 39600-2021 formaldehyde standards is disqualifying uncertified particleboard capacity across Guangdong province. Shunde district retains production gravity for compliant integrated mills serving both domestic and export channels.
India
Mortgage penetration in Pune, Ahmedabad, and Kochi accelerates nuclear family formation and associated furniture refresh cycles. BIS mandates ISI certification for structural integrity and safety testing, creating compliance barriers for import-dependent assemblers. Mumbai, Bangalore, and Hyderabad anchor deep distribution networks for mass-market residential segments.
Japan
Corporate procurement channels emphasize ergonomic certification and modular reconfiguration capabilities for office environments. METI-administered JIS standards govern dimensional tolerances and ergonomic benchmarks with 12-16 week validation timelines. Tokyo and Osaka metropolitan areas concentrate specification-driven demand for premium task seating.
Indonesia
International hotel chains in Jakarta and Bali drive premium upholstery demand ahead of projected visitor recovery timelines. Export permit restrictions on meranti and rubberwood create input cost volatility for downstream fabricators. Jepara cluster faces master craftsman attrition without adequate apprenticeship pipeline replacement for hand-finished joinery.
Vietnam
Residential completion rates in Da Nang and Hai Phong outpace proportional furniture retail presence, creating distribution gaps for first-movers. General functional oversight from national trade and standards bodies applies to import compliance without the granular certification architecture seen in neighboring markets. Northern industrial zones near Hai Phong attract assembly investment serving export channels.
Asia-Pacific Home Furniture Market Competitive Environment
Player mix skews toward integrated manufacturers with captive panel milling capabilities and import-dependent assemblers facing margin compression from certification costs. Three archetypes dominate: state-affiliated forestry conglomerates with certified timber access, vertically integrated Guangdong-based producers controlling particleboard supply, and regional specialists in ergonomic or hospitality-grade upholstery. Competitive moves concentrate on backward integration into certified panel production and exclusive sourcing agreements with compliant mills.
Among China-based fabricators, Shunde Kinwai Furniture Co., Ltd. and Foshan Sunon Furniture Co., Ltd. exemplify the integrated mill archetype with Guangdong province positioning. Okamura Corporation occupies a position within the premium ergonomic seating tier, representing Japanese captive R&D center investment. Godrej & Boyce Manufacturing Co. Ltd. anchors Indian mass-market residential distribution through Mumbai, Bangalore, and Hyderabad network depth.
| Leading Market Players |
|---|
| Shunde Kinwai Furniture Co., Ltd. |
| Foshan Sunon Furniture Co., Ltd. |
| Qumei Home Furnishings Group |
| Okamura Corporation |
| Kokuyo Co., Ltd. |
| Godrej & Boyce Manufacturing Co. Ltd. |
| Damro Group |
| Markor Home Furnishings Co., Ltd. |
| Lamex Trading Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
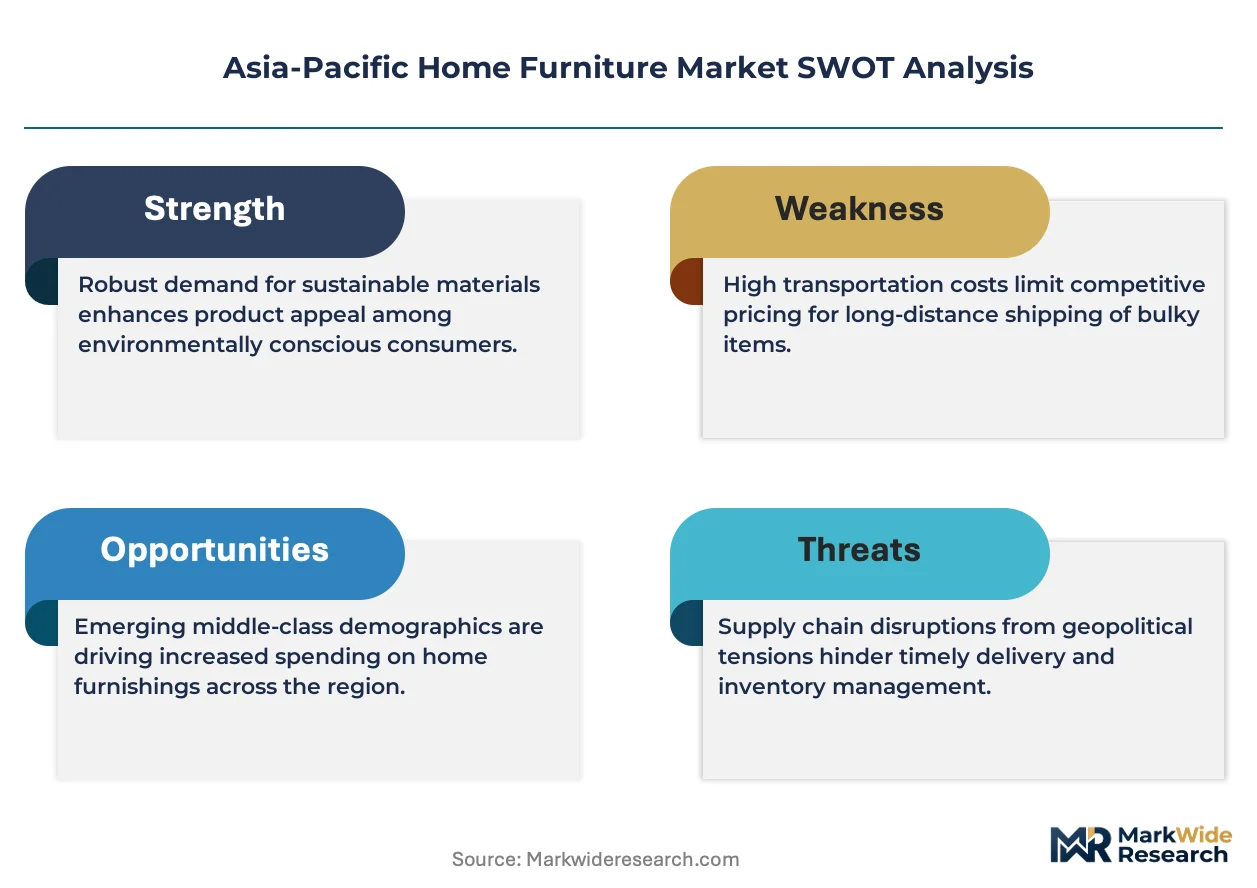
Sixty-day particleboard inventory cycles in Guangdong province concentrate procurement leverage among integrated mills while compressing margins for import-dependent assemblers facing GB 18580-2017 certification costs. This lead-time compression translates directly into pricing power asymmetry between certified integrated producers and downstream fabricators.
Pricing Analysis
Cost-plus contracts indexed to Malaysian rubberwood and Indonesian meranti spot markets dominate raw material procurement for Guangdong-based manufacturers. Price differentiation rests on E0 versus ENF grade panel certification and captive timber milling capabilities. Cost compression in mass-market particleboard seating intensifies because SAMR enforcement is disqualifying uncertified mills. Residential buyers in India's tier-2 cities exhibit highest price sensitivity, while hospitality specifiers in Jakarta and Bali prioritize fire-resistance ratings over unit cost.
Supply Chain Analysis
China, Indonesia, and Vietnam anchor engineered wood panel production and upholstered furniture assembly across the Asia-Pacific basin. Raw material flows draw from Malaysian rubberwood plantations, Indonesian meranti concessions, and imported low-emission adhesive formulations. Single-source vulnerability concentrates in Guangdong's Shunde district where particleboard milling clusters create just-in-time delivery risk. Distribution runs through live-streaming commerce platforms in China's tier-1 cities and deep retail networks in Mumbai, Bangalore, and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around GB standards and BIS certification creates durable barriers against unqualified entrants.
For Market Incumbents: Consolidate certified particleboard capacity in Guangdong's compliant mill base to capture volume from disqualified competitors. Deepen backward integration into low-emission adhesive sourcing to offset input cost volatility from Malaysian export permit restrictions. Defensive positioning against live-streaming commerce disintermediation requires direct-to-consumer platform investment. For New Entrants and Emerging Players: Lead with augmented reality configuration tools targeting space-constrained buyers in Shanghai and Seoul metropolitan corridors. Vietnam's Da Nang and Hai Phong residential completion gaps offer first-mover distribution advantages without proportional retail saturation. Go-to-market execution should emphasize precise fit optimization unavailable through standard SKU retail. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated forestry conglomerates seeking to monetize certified timber access through downstream furniture integration. Long-term viability centers on regulatory compliance infrastructure rather than pure manufacturing scale. Watch for inflection signals in Japan's METI JIS validation timeline compression relative to retail seasonal ordering windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Panel Milling | Captures margin pool from disqualified Guangdong particleboard mills under SAMR enforcement. |
| Exclusive Sourcing Agreements with State Forestry Conglomerates | Locks in E0 and ENF grade timber access ahead of competitor procurement. |
| Direct-to-Consumer AR Configuration Platform Launch | Collapses showroom-to-warehouse layers for modular storage in Shanghai and Seoul. |
| Hospitality-Grade Upholstery Certification Investment | Meets fire-resistance protocols for Jakarta and Bali hotel renovation cycles. |
| Apprenticeship Pipeline Development in Jepara and Dongyang | Addresses master craftsman attrition threatening hand-finished joinery capacity. |
Study Parameters
Initial hypotheses were tested against primary input from furniture manufacturing executives, procurement leads at hospitality chains, retail category managers, and regulatory compliance officers, then refined through secondary validation against SAMR GB standard filings, BIS certification registries, customs trade data, and METI JIS documentation. Bottom-up demand modeling across residential, hospitality, office, and retail end-use segments triangulated with top-down macroeconomic indicators.
Variance decomposition across material grade, distribution channel, and geographic adoption patterns structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization in certified versus uncertified product tiers. Forecast inputs incorporated urban completion rates in Indian tier-2 cities, hospitality renovation backlogs in Southeast Asia, and live-streaming commerce penetration in Chinese metropolitan markets.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement intensity or abrupt Malaysian rubberwood export restrictions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline adherence and apprentice pipeline replenishment. Recalibration cycles align with material shifts in GB standard amendments, BIS testing protocol updates, and METI JIS dimensional tolerance revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United States Luxury Furniture Market
Furniture
RTA Furniture Market
Furniture
North America Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Italy Home Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
North America Smart Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Italy Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
US Sustainable Furniture Market
Furniture
India Luxury Furniture Market