
 Japan Furniture Market | 2026-2036
Japan Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Furniture Market Outlook
Subscription-based furniture leasing and software-driven space planning is repositioning how Japanese consumers acquire and configure home interiors. Nitori Holdings leverages its vertically integrated supply chain to sustain price competitiveness across mass-market segments. Karimoku Furniture anchors the premium solid-wood segment through controlled artisan manufacturing in Aichi Prefecture. Itoki Corporation dominates commercial and institutional channels with ergonomic workplace systems tailored to corporate and government clients.
Japan furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically constructed from engineered wood panels, steel frames, or upholstered composites with functional parameters including load tolerance, dimensional stability, and fire-resistance ratings. The primary purpose spans residential living optimization, commercial workspace configuration, and hospitality environment design. Wood material segments command the highest margin pools due to domestic preference for natural finishes and JIS-certified structural integrity. Residential end users generate the largest volume base, while hospitality applications represent the fastest-growing demand channel as inbound tourism infrastructure expands. Modern and minimalist style categories lead consumer preference, reflecting spatial constraints in dense urban housing.
METI enforces energy-efficiency and circular-economy standards that shape manufacturer material choices and end-of-life obligations for furniture products. JIS standards govern structural safety and chemical emissions, creating compliance barriers for imported goods and protecting domestic producers. PMDA oversight extends to antimicrobial surface claims in healthcare and institutional furniture applications. Stakeholders must monitor evolving sustainability disclosure requirements and supply-chain traceability mandates that will determine competitive access to public-sector and corporate procurement channels.
Market Dynamics
Compact urban housing in Greater Tokyo is compressing furniture dimensions while METI's circular-economy mandates force material transparency throughout supply chains. This structural squeeze between spatial constraints and regulatory compliance defines competitive positioning for domestic manufacturers.
Growth Catalysts
- Subscription leasing models:Urban millennials in Osaka and Fukuoka are bypassing ownership for flexible furniture access. This consumption-pattern shift expands addressable volume beyond traditional purchase cycles.
- METI sustainability disclosure mandates:Public-sector procurement now requires certified wood sourcing documentation. Domestic producers with JIS-compliant supply chains capture institutional contracts previously vulnerable to imports.
- Inbound tourism infrastructure:Hospitality developers in Kyoto and Hokkaido are commissioning custom fixtures at scale. Hotel-grade durability standards are diffusing into residential premium segments.
Market Restraints
- Imported engineered wood dependency:Japanese manufacturers rely on Southeast Asian suppliers for particleboard substrates. Currency volatility and shipping congestion compress margin buffers unpredictably.
- JIS certification timelines:New chemical-emission testing protocols add 4-6 months to product launch schedules. Smaller workshops lack laboratory access to accelerate compliance.
- Steel frame cost pressure:Global ferrous metal markets have elevated input costs for institutional seating and storage systems. Price pass-through remains constrained in mass-market channels.
Strategic Opportunities
- Healthcare furniture antimicrobial claims:PMDA oversight of surface-treatment efficacy creates premium positioning for certified producers. Hospital and eldercare procurement budgets are expanding for infection-control specifications.
- Software-driven space planning:Augmented-reality configuration tools are compressing purchase decision cycles. Retailers deploying these platforms report higher conversion in studio-apartment segments.
- Regional manufacturing clusters:Aichi Prefecture's timber-processing infrastructure supports artisan solid-wood specialization. Proximity to Nagoya port enables efficient export logistics for premium collections.
Industry Challenges
- Craft apprenticeship gaps:Traditional joinery skills are aging out in Gifu and Toyama workshops. Vocational pipelines have not scaled to replace retiring master artisans.
- End-of-life reverse logistics:METI's extended producer responsibility rules require collection networks for discarded items. Retailers lack density-efficient systems outside metropolitan cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Furniture Market |
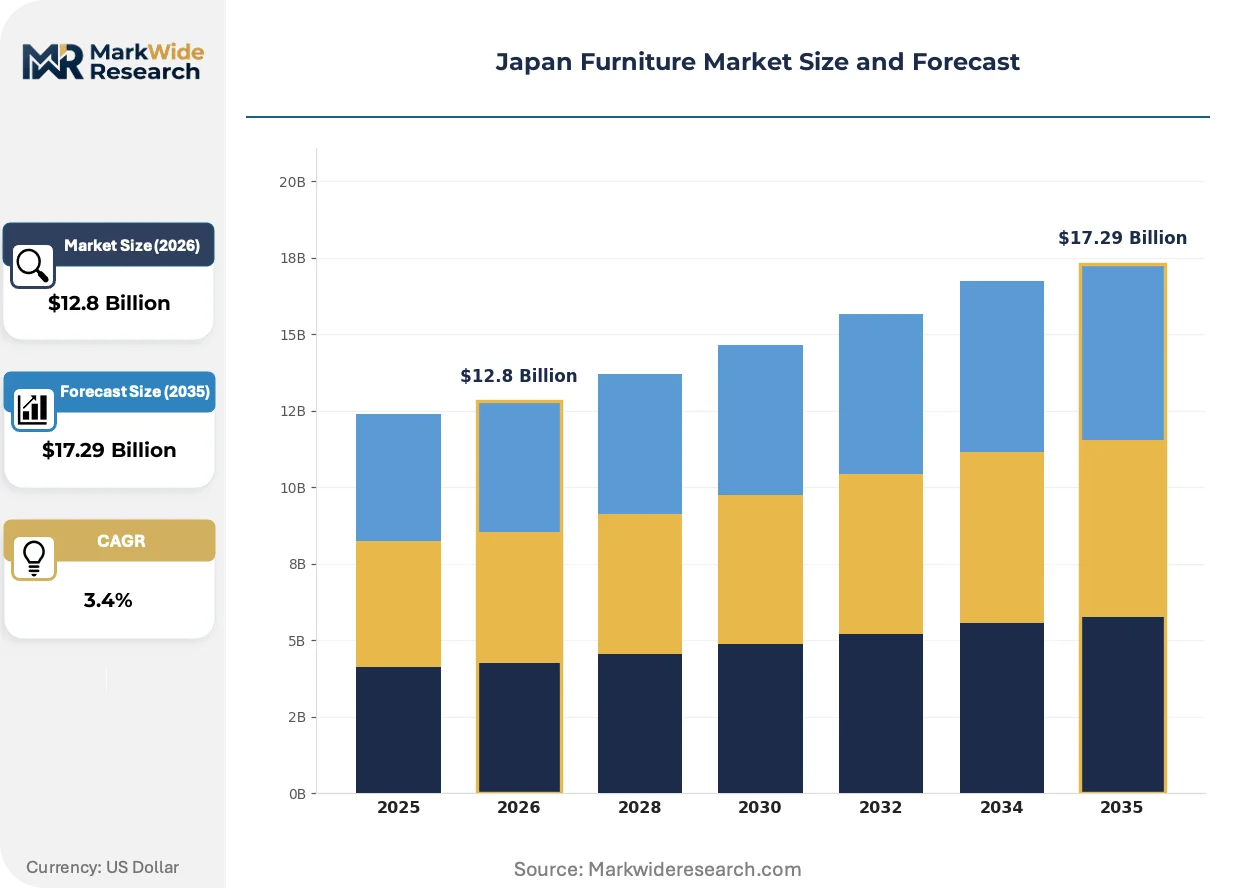
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.29 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Plastic, Fabric Style: Modern, Traditional, Minimalist, Rustic End User: Residential, Commercial, Hospitality, Institutions |
| Companies Covered | Okamura Corporation, Itoki Corporation, Nitori Holdings, Maruni Wood Industry, Karimoku Furniture, IKEA Japan, Kokuyo, Hida Sangyo, Ryohin Keikaku (MUJI), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Furniture Market Strategic Shifts
Digital fabrication and biomaterial research are compressing development cycles while regulatory pressure on chemical emissions accelerates finish-formulation turnover. These forces are reconfiguring how Japanese manufacturers balance craft heritage with production scalability.
Parametric design software is unifying customer measurement data with CNC routing instructions for made-to-order storage systems. Small-batch workshops in Kanagawa Prefecture are adopting these platforms to reduce pattern-making labor. The technology is unifying previously separate design and production functions, collapsing lead times from weeks to days for custom dimensions.
METI's 2024 revision to chemical-substance reporting obligations now captures formaldehyde emissions from adhesives used in composite panels. Manufacturers must submit third-party laboratory documentation for each production batch. Solid-wood specialists with captive forestry operations are marketing natural-finish alternatives to specifiers seeking simplified compliance pathways.
Corporate facility managers are unbundling furniture procurement from interior-design contracts, creating direct vendor relationships for ergonomic workplace systems. This disintermediation compresses margin capture for traditional project intermediaries. Tokyo-headquartered technology firms are piloting this model, with procurement teams negotiating multi-year service agreements inclusive of reconfiguration and refresh cycles.
Japan Furniture Market Segmentation
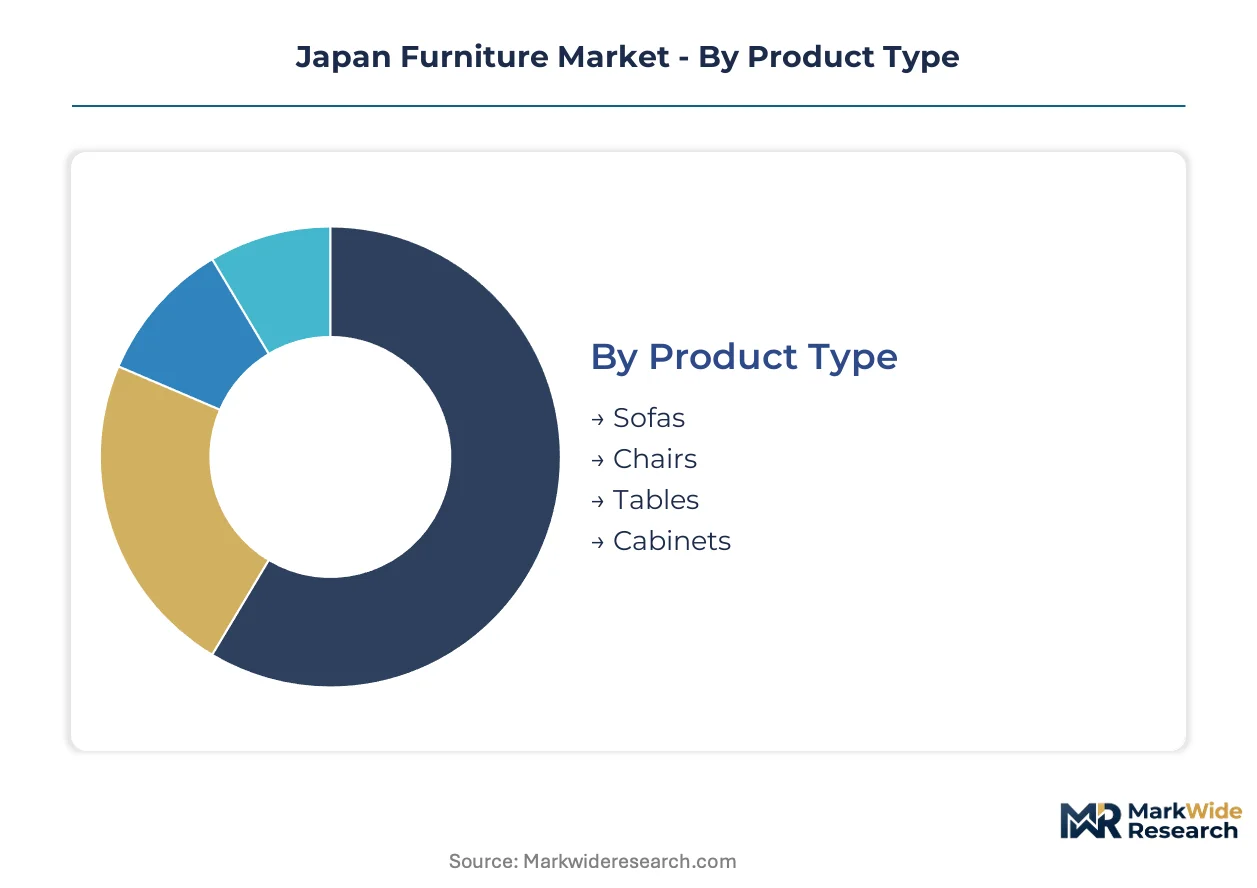
Japanese furniture purchasing splits sharply between spatial constraints in dense urban housing and durability requirements in commercial settings. Segmentation reveals how manufacturers calibrate dimensions, materials, and compliance specifications to match distinct buyer economics across these divergent use cases.
Product Type:
Compact living spaces in Greater Tokyo and Osaka compress buyer priorities toward multifunctional pieces that maximize utility per square meter.
- Sofas:Modular configurations with storage-integrated bases dominate studio-apartment procurement. Convertible sofa-bed mechanisms from domestic suppliers capture premium positioning in Tokyo's 25-35 square meter rental stock.
- Chairs:Ergonomic task seating with JIS-certified structural frames anchor commercial and institutional procurement. Corporate facility managers in Osaka and Nagoya prioritize 8-hour comfort ratings and 10-year durability warranties.
- Tables:Foldable and extendable dining surfaces address variable occupancy in multi-generational households. Kanagawa Prefecture workshops specialize in custom dimensions for narrow urban dining alcoves.
- Cabinets:Vertical storage systems with sliding door mechanisms optimize wall-adjacent placement. METI's formaldehyde emission limits favor solid-wood construction over composite panel alternatives in premium residential segments.
Cabinets lead on scale; chairs lead on momentum.
Material:
Regulatory pressure from METI and JIS certification requirements reshape material selection trade-offs between cost, compliance burden, and consumer preference.
- Wood:Domestic hinoki and sugi species command premium positioning through natural antimicrobial properties and JIS-compliant low-emission finishes. Aichi Prefecture's captive forestry operations supply Karimoku and comparable artisan manufacturers with traceable raw material.
- Metal:Steel frames with powder-coat finishes anchor institutional seating and storage systems. Global ferrous metal price volatility has compressed margin buffers for mass-market producers reliant on imported substrate.
- Plastic:Recycled polymer composites meet METI circular-economy disclosure mandates for public-sector procurement. Injection-molding specialists in Shizuoka Prefecture supply healthcare furniture with PMDA-registered antimicrobial surface treatments.
- Fabric:Performance upholstery with stain-resistant and flame-retardant specifications dominates hospitality applications. Kyoto hotel developers specify domestic textile weavers for custom pattern matching to interior design concepts.
Wood captures the highest margin pools; plastic is expanding most quickly under sustainability procurement mandates.
Style:
Aesthetic preference correlates tightly with housing vintage and buyer age cohort, creating distinct addressable markets within residential channels.
- Modern:Clean lines and neutral palettes align with new-construction condominium specifications. Tokyo developers specify modern collections from Nitori and comparable suppliers for furnished rental inventory.
- Traditional:Joinery techniques from Gifu and Toyama workshops serve ceremonial and heritage-property restoration demand. Master artisan scarcity limits production scale and extends lead times for custom commissions.
- Minimalist:Reduced visual mass and hidden storage integration address psychological preferences in compact spaces. Young professional buyers in Fukuoka and Sapporo prioritize this aesthetic for studio-apartment configurations.
- Rustic:Reclaimed timber and visible grain patterns attract rural second-home and hospitality developers. Hokkaido ski lodge and onsen ryokan projects commission custom rustic fixtures from regional sawmills.
Modern leads on scale; minimalist leads on momentum among urban millennial buyers.
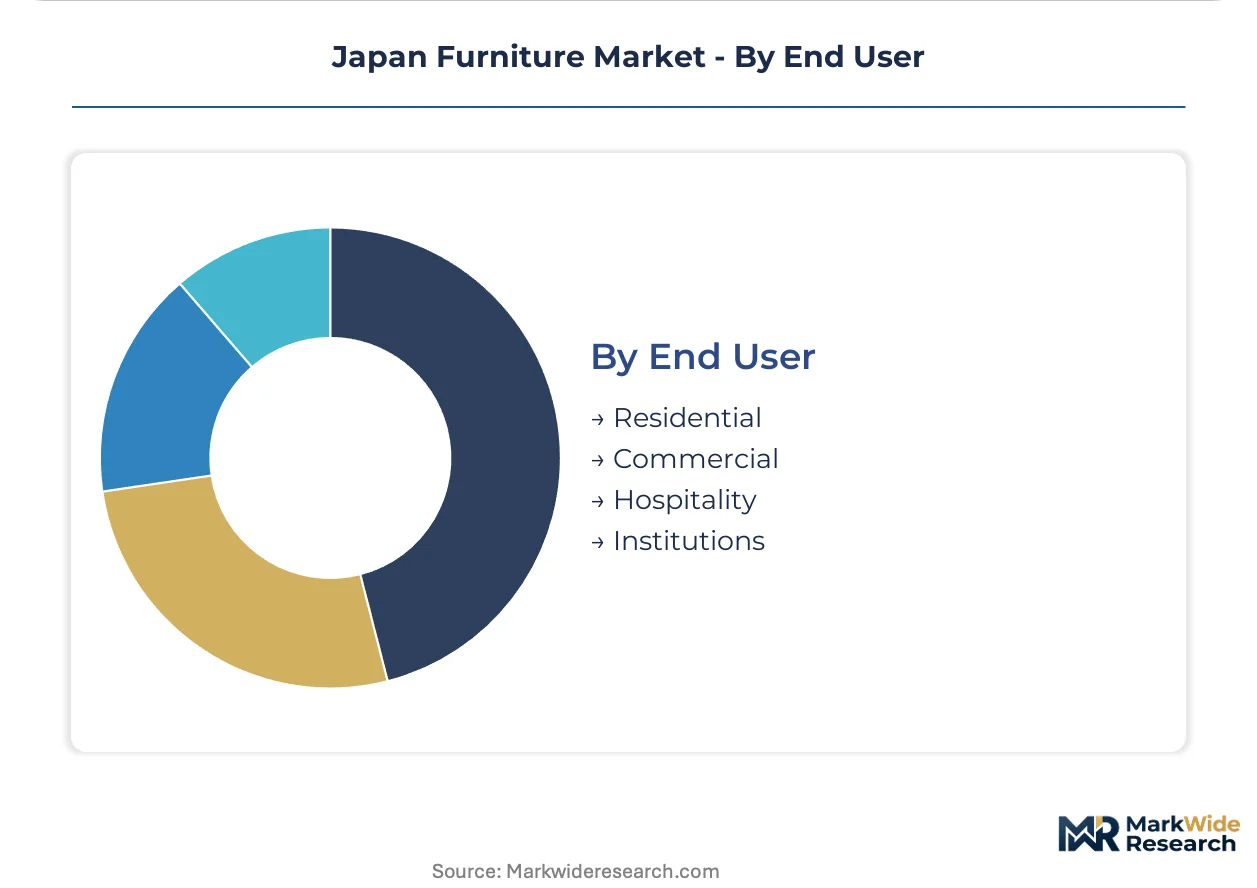
End User:
Procurement authority and decision criteria diverge sharply between individual consumers, corporate facility managers, and institutional purchasing departments.
- Residential:Individual buyers prioritize space efficiency and aesthetic cohesion with existing interiors. Subscription leasing models from Tokyo-based platforms are displacing traditional ownership in Osaka and Fukuoka metro areas.
- Commercial:Corporate facility managers negotiate multi-year service agreements inclusive of reconfiguration and refresh cycles. Technology firms headquartered in Tokyo pilot direct vendor relationships that disintermediate traditional project intermediaries.
- Hospitality:Hotel-grade durability standards are diffusing into residential premium segments as inbound tourism infrastructure expands. Kyoto and Hokkaido developers commission custom fixtures at scale for new property openings.
- Institutions:Healthcare and eldercare procurement budgets are expanding for infection-control specifications. PMDA oversight of antimicrobial surface claims creates premium positioning for certified producers in hospital seating and patient room furniture.
Residential leads on scale; hospitality leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's furniture exports dwarf Japan's domestic production volume, yet Japanese manufacturers command premium positioning through JIS-certified craftsmanship and METI-mandated sustainability compliance that foreign competitors struggle to replicate.
Kanto/Tokyo
Studio-apartment proliferation and corporate headquarters concentration drive demand for space-efficient and ergonomic workplace systems. METI's circular-economy disclosure requirements shape procurement specifications for public-sector contracts. Yokohama and Saitama manufacturing clusters specialize in compact multifunctional storage for metropolitan rental stock.
Kansai/Osaka
Multi-generational households and SME commercial activity sustain mid-market furniture turnover. JIS chemical-emission testing protocols filter out low-cost imports from regional distribution channels. Osaka Prefecture workshops cluster around traditional joinery techniques serving ceremonial and heritage-property restoration demand.
Chubu/Nagoya
Aichi Prefecture's captive forestry operations and timber-processing infrastructure anchor solid-wood specialization for premium residential and hospitality segments. Nagoya port proximity enables efficient export logistics for artisan collections. METI-certified wood sourcing documentation from regional supply chains secures institutional procurement contracts.
Kyushu
Fukuoka's urban millennial demographic adopts subscription-based furniture leasing models that bypass traditional ownership cycles. Regional retailers deploy augmented-reality configuration tools to compress purchase decision cycles for compact apartment segments. Local manufacturing remains limited, with distribution serving as the primary value-add function.
Hokkaido
Inbound tourism infrastructure expansion drives hospitality-grade fixture commissioning for ski lodge and onsen ryokan developments. Sapporo's younger professional buyers prioritize minimalist aesthetics for studio-apartment configurations. Regional sawmills supply reclaimed timber for custom rustic fixtures commissioned by rural second-home developers.
Japan Furniture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated domestic producers commanding institutional channels while import-reliant retailers capture mass-market volume. The vendor base organizes around three strategic archetypes: mass-market retailers with captive supply chains, artisan solid-wood specialists with regional forestry ties, and ergonomic systems providers serving corporate workplace procurement. Competitive positioning hinges on JIS certification speed and METI sustainability documentation depth rather than price alone. M&A activity concentrates on regional timber-processing assets and software-driven space planning platforms.
Within the vertically integrated mass-market tier, Nitori Holdings exemplifies supply chain control that sustains price competitiveness across high-volume segments. Karimoku Furniture occupies a position among Aichi Prefecture's artisan solid-wood specialists leveraging captive forestry operations for traceable raw material. Itoki Corporation anchors the commercial and institutional channel with ergonomic workplace systems tailored to corporate and government procurement specifications.
| Leading Market Players |
|---|
| Okamura Corporation |
| Itoki Corporation |
| Nitori Holdings |
| Maruni Wood Industry |
| Karimoku Furniture |
| IKEA Japan |
| Kokuyo |
| Hida Sangyo |
| Ryohin Keikaku (MUJI) |
| Others |
Value Chain & Pricing Dynamics
Master joiners concentrated in Gifu and Toyama Prefectures command wage premiums that compress margin spreads between artisan solid-wood tiers and mass-market engineered-wood alternatives. Labor-cost differentials between aging craft specialists and automated panel-processing facilities in Kanagawa and Saitama define the pricing architecture across residential segments.
Pricing Analysis
Capacity additions in Southeast Asian particleboard manufacturing are reshaping price floors for Japanese mass-market producers dependent on imported substrates. Three-tier pricing structure across premium solid-wood, certified mid-market, and economy engineered-wood levels stratifies buyer access. Pricing pressure stems from currency volatility in Southeast Asian supply contracts and elevated steel frame input costs. Mass-market residential buyers exhibit highest price sensitivity, while hospitality developers purchasing custom fixtures show lowest sensitivity due to durability specification requirements.
Supply Chain Analysis
Particleboard substrate supply rests on Malaysian and Indonesian forestry operations with Japanese manufacturers holding limited backward integration. Domestic hinoki and sugi sourcing concentrates in Aichi Prefecture captive forestry, while steel frame components draw from Chinese and South Korean ferrous metal processing. Single-source vulnerability in Southeast Asian engineered wood imports exposes margin buffers to shipping congestion and tariff fluctuation. Distribution runs through vertically integrated retail networks in metropolitan cores and regional wholesale channels serving institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where inbound tourism infrastructure and healthcare procurement are shifting specifications toward premium durability grades and certified antimicrobial finishes.
For Market Incumbents: To counter craft apprenticeship attrition in Gifu and Toyama, anchor market position through parametric design software deployment that compresses custom-order lead times and reduces pattern-making labor dependency. Deepen upstream control over Aichi Prefecture timber assets to secure JIS-certified traceability documentation for institutional contract eligibility. For New Entrants and Emerging Players: Subscription-platform routes into Osaka and Fukuoka urban millennial segments offer the most penetrable white-space, bypassing traditional ownership cycles with flexible-access models. Target studio-apartment configuration services through augmented-reality space planning tools that accelerate purchase decisions. Pursue direct vendor relationships with Tokyo-headquartered technology firms piloting disintermediated procurement models. For Investors and Strategic Acquirers: Regional furniture retailers with established metropolitan distribution density are the most active acquirer in this space, consolidating end-of-life reverse logistics capabilities required under METI extended producer responsibility mandates. Acquisition focus should center on software-driven space planning platforms and Aichi Prefecture timber-processing assets. Monitor hospitality fixture commissioning volumes in Kyoto and Hokkaido as inflection signal for premium segment momentum.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Acceleration | Shrinks product launch timelines by 4-6 months, unlocking institutional procurement channels previously blocked to smaller workshops. |
| Captive Forestry Acquisition | Secures METI-compliant traceability documentation for hinoki and sugi sourcing, protecting margin pools in premium solid-wood segments. |
| Parametric Design Platform Deployment | Unifies customer measurement data with CNC routing instructions, collapsing custom storage lead times from weeks to days in Kanagawa workshops. |
| Subscription Leasing Model Launch | Captures urban millennial demand in Osaka and Fukuoka through flexible-access furniture bypassing traditional ownership cycles. |
| Antimicrobial Surface Certification | PMDA-registered treatments create premium positioning for hospital and eldercare seating as infection-control procurement budgets expand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with furniture manufacturing executives, procurement leads at hospitality developers, METI regulatory affairs specialists, and corporate facility managers with secondary validation. Customs records, JIS certification databases, METI circular-economy disclosure filings, and inbound tourism infrastructure development permits anchored supply-side assessment. Bottom-up volume modeling across product type, material, style, and end-user segments triangulated against top-down macroeconomic indicators.
Historical reference periods spanning the decade preceding the analysis window anchored growth trajectory assumptions and volatility calibration. Segmentation modeling captured product type, material composition, aesthetic style category, and end-user procurement authority across the projection horizon. CAGRs derived from regression analysis of correlated macro drivers including residential construction permits, hospitality development pipeline, and institutional healthcare capital expenditure. Forecast inputs incorporated METI regulatory phase-in schedules and apprenticeship pipeline demographics.
The model assumes a particular technology adoption path for parametric design and digital fabrication; alternative pathways for craft automation would alter the outlook for lead time compression and artisan employment. Forecasts reflect assumptions regarding Southeast Asian supply chain stability and JIS certification protocol evolution. Regulatory disclosure stringency, currency volatility in engineered wood imports, and hospitality development cycle timing warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Netherlands Home Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Bounding Table Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Indonesia Home Furniture Market
Furniture
Kids Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Europe Bamboo Furniture Market
Furniture
United States Home Furniture Market
Furniture
Upholstered Furniture Market
Furniture
Armchair on Casters Market
Furniture
Europe Upholstered Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Global Home Furniture Market
Furniture
GCC Luxury Furniture Market
Furniture
Chaises Longue Market