
 United States Home Furniture Market | 2026-2036
United States Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Home Furniture Market Analytics
Multifamily housing developers is rebalancing procurement toward modular and space-efficient furniture systems as urban density rises and unit footprints shrink. Wayfair Inc. leverages its digital-native platform to capture demand from remote-first households seeking direct-to-door delivery with virtual visualization tools. Ashley Global Retail LLC sustains manufacturing scale through captive domestic production networks that shorten lead times against import-dependent rivals. Williams-Sonoma Inc. anchors premium positioning through design-forward collections that command full-margin pricing in specialty channels.
United States home furniture encompasses movable articles designed for residential interior spaces, typically constructed from engineered wood substrates, solid hardwoods, steel alloys, or textile upholstery systems with dimensional tolerances governed by ASTM standards for stability and load-bearing performance. The category serves primary functions of seating, sleeping, surface support, and storage within dwelling units. Wood material segments dominate unit volume due to cost accessibility and refinishing longevity, while leather material commands concentrated margin pools in aspirational living room assortments. Online retail distribution accelerates fastest among channels as augmented reality tools reduce return friction, though specialty stores retain decisive influence in high-consideration purchases where tactile evaluation determines conversion.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1640 for upholstered furniture, compelling foam reformulation and barrier fabric adoption across domestic supply chains. California Air Resources Board CARB Phase 2 limits formaldehyde emissions from composite wood substrates, pushing manufacturers toward soy-based adhesives and no-added-formaldehyde resins. EPA guidelines on volatile organic compound content in furniture coatings further constrain finishing operations. Stakeholders must monitor evolving state-level chemical disclosure requirements and decide whether to standardize compliance nationally or maintain state-specific product variants.
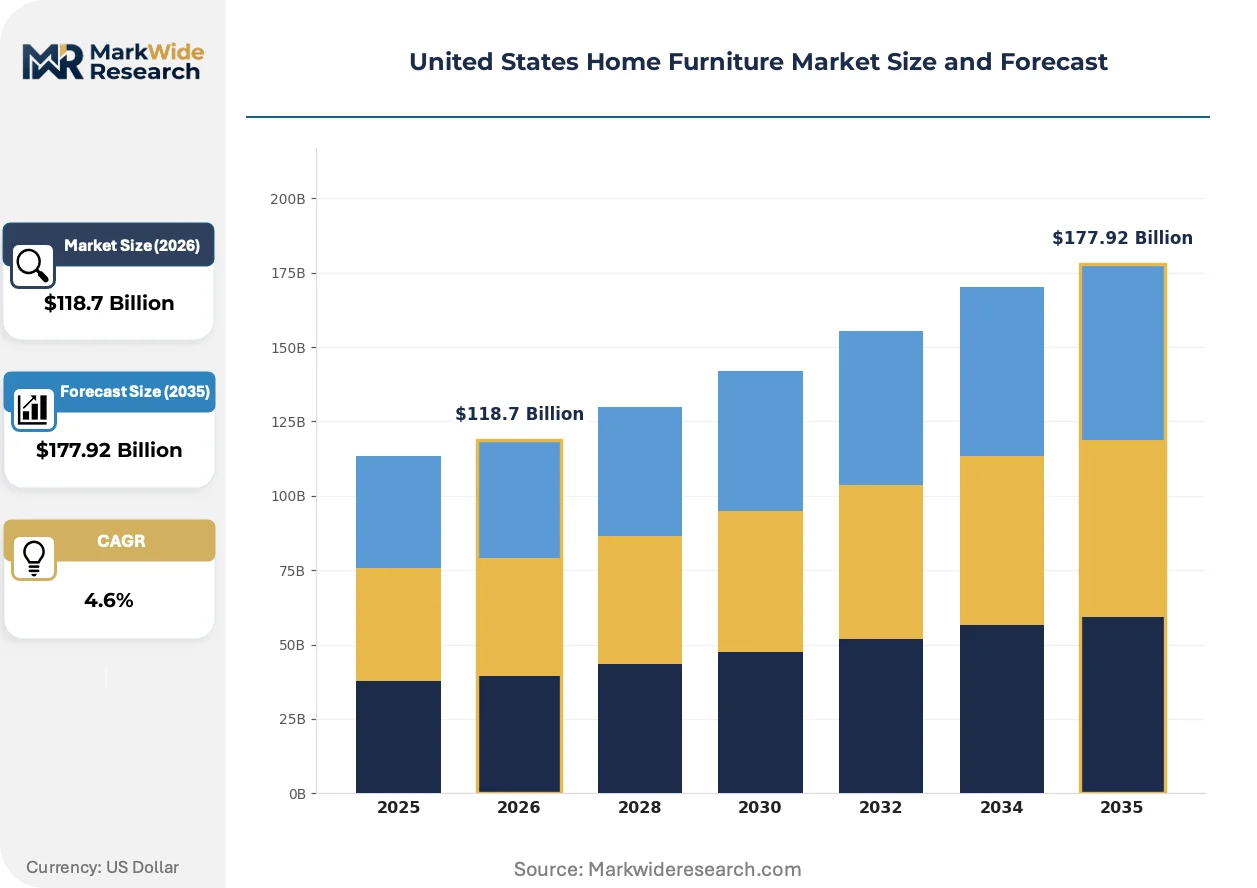
Market Dynamics
California's Title 20 appliance efficiency standards now extend to furniture-integrated lighting and power components, forcing suppliers to redesign electrical subsystems or exit the state entirely. This regulatory compression cascades through procurement specifications, manufacturing footprints, and distribution compliance costs across domestic supply chains.
Growth Catalysts
- CARB Phase 2 formaldehyde limits:California Air Resources Board emission caps on composite wood substrates accelerate manufacturer migration toward soy-based adhesives and no-added-formaldehyde resins, opening premium positioning for early compliant producers.
- Texas metropolitan corridor expansion:Dallas-Fort Worth and Houston housing starts sustain above-average category velocity as inbound migration concentrates demand for starter and trade-up furniture assortments.
- Multifamily density economics:Urban unit footprint compression drives developer procurement of modular, space-efficient furniture systems with integrated storage and convertible functionality.
Market Restraints
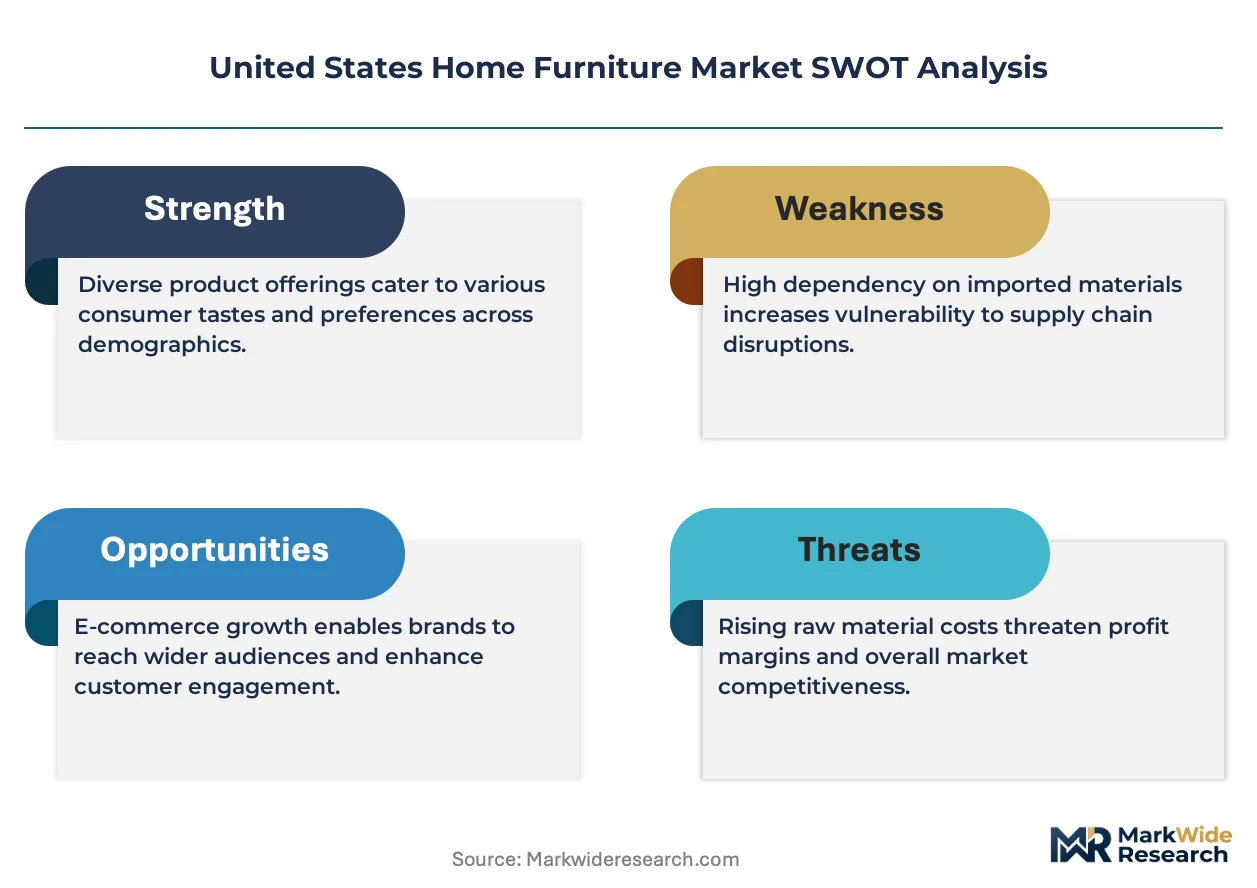
- Hardwood input cost volatility:Solid hardwood price swings tied to Pacific Northwest harvest constraints and Canadian softwood lumber duties compress margin predictability for mid-tier manufacturers.
- 16 CFR Part 1640 compliance friction:Consumer Product Safety Commission flammability standards for upholstered furniture mandate foam reformulation and barrier fabric adoption, raising per-unit material costs.
- Import-dependent supply concentration:Asian manufacturing clusters dominate engineered wood substrate and textile upholstery production, exposing lead time vulnerability to port congestion and tariff volatility.
Strategic Opportunities
- Southeastern Sun Belt migration:Florida, Georgia, and North Carolina population inflows create underpenetrated demand nodes for regional distribution center investment and localized last-mile fulfillment.
- Augmented reality visualization convergence:Web-based AR tools paired with direct-to-consumer logistics reduce return friction and enable showroom-free conversion in remote-first household segments.
- IRA residential energy incentives:Inflation Reduction Act tax credits for efficient home systems extend to certain furniture-integrated power components, creating specification pull from builder channels.
Industry Challenges
- EPA VOC coating compliance timeline:Volatile organic compound content limits in furniture finishes constrain finishing operation throughput and require capital-intensive spray booth reconfiguration.
- State-level chemical disclosure fragmentation:Evolving disclosure requirements across California, Washington, and Maine force decisions between national product standardization and state-specific variant maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Furniture Market |
| Market Size in 2026 | $118.7 Billion |
| Market Size in 2035 | $177.92 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Fabric, Leather Style: Contemporary, Traditional, Rustic, Minimalist Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Ashley Global Retail LLC, La-Z-Boy Incorporated, Wayfair Inc., Williams-Sonoma Inc., Restoration Hardware Inc., Ethan Allen Interiors Inc., Bassett Furniture Industries Inc., Inter IKEA Holding B.V., Crate and Barrel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Furniture Market Evolving Landscape
Digital-native platforms and regulatory chemistry mandates are jointly compressing traditional manufacturing and distribution models. Technology adoption curves and compliance timelines now determine competitive survival more than scale economies alone.
Web-based augmented reality visualization tools are rewriting how remote-first households evaluate furniture purchases without physical showroom visits. Millennial and Gen Z buyers now expect photorealistic 3D placement in their actual rooms before checkout. This capability compression is collapsing the traditional furniture retail real estate model and shifting margin capture toward logistics-integrated digital platforms.
California Air Resources Board Phase 2 formaldehyde emission standards now govern composite wood substrates nationwide through de facto harmonization. Manufacturers face reformulation costs or market exclusion from the country's largest state economy. Upholstered furniture segments with engineered wood frames experience the steepest compliance burden, accelerating supplier consolidation around captive adhesive chemistry capabilities.
Direct-to-door delivery with white-glove assembly unbundling is displacing traditional retail take-home models in metropolitan markets. Specialty stores lose conversion share where tactile evaluation once determined purchase. This channel rotation concentrates most visibly in Texas and Florida corridors where new household formation outpaces legacy retail footprint density.
United States Home Furniture Market Segmentation
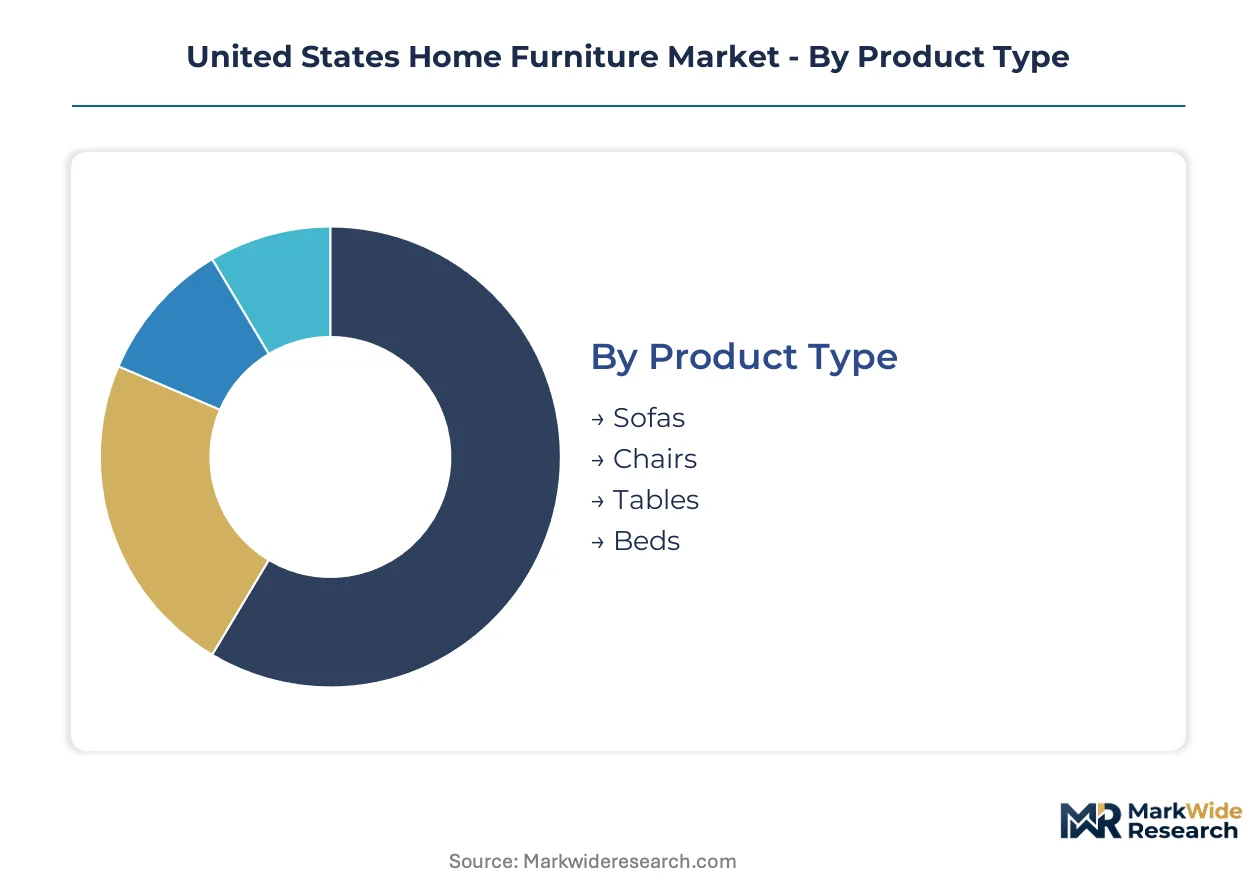
Segmentation in the United States home furniture market reveals how regulatory burdens, material chemistry requirements, and channel compliance costs concentrate differentially across product categories. Understanding these fault lines enables targeted investment in certification capabilities and geographic positioning.
Product Type:
Upholstered seating segments trigger 16 CFR Part 1640 flammability compliance, while case goods face CARB Phase 2 substrate mandates; sleep products intersect both regimes plus CPSC mattress ignition standards.
- Sofas:Engineered wood frames wrapped in polyurethane foam cushioning and textile or leather upholstery systems. Demand concentrates in Texas metropolitan corridors where multifamily developers specify modular sectional configurations for compressed living footprints. CARB Phase 2 and 16 CFR Part 1640 dual compliance elevates per-unit material costs.
- Chairs:Dining, accent, and recliner variants spanning solid hardwood, metal, and upholstered constructions. California Title 20 efficiency standards now extend to power recliner mechanisms, forcing electrical subsystem redesigns or state market exit.
- Tables:Dining, coffee, and side table assemblies predominantly utilizing composite wood substrates with veneer or laminate surfacing. EPA VOC coating limits constrain finishing throughput for domestic manufacturers.
- Beds:Platform, panel, and storage-integrated frames with slat or foundation support systems. CPSC 16 CFR Part 1633 mattress ignition standards propagate through attached headboard upholstered components.
Leading the category by volume: Sofas. Growing fastest: Beds with integrated storage and power components.
Material:
Material selection determines which state and federal chemical disclosure regimes apply, with composite wood and treated textiles facing the densest compliance matrices.
- Wood:Solid hardwoods and engineered substrates including MDF, particleboard, and plywood. CARB Phase 2 formaldehyde caps drive adhesive migration toward soy-based and no-added-formaldehyde resin systems, favoring manufacturers with captive chemistry capabilities.
- Metal:Steel alloy and aluminum framing for contemporary and industrial styling segments. Powder coating finishes face EPA VOC content thresholds, though generally lighter regulatory burden than wood substrates.
- Fabric:Natural and synthetic textile upholstery systems including polyester, cotton, linen, and blended weaves. 16 CFR Part 1640 mandates barrier fabric layers or foam reformulation, raising material costs for upholstered segments.
- Leather:Full-grain, top-grain, and bonded leather surfacing for premium living room assortments. Chrome tanning chemistry faces evolving state-level chemical disclosure requirements in California, Washington, and Maine.
Wood commands unit volume leadership. Leather maintains margin concentration despite smaller scale.
Style:
Style positioning correlates with material intensity and finishing complexity, translating to variable exposure on EPA coating compliance and hardwood input volatility.
- Contemporary:Clean lines, minimal ornamentation, and mixed material constructions emphasizing metal and glass. Lower finishing operation intensity reduces EPA VOC compliance exposure relative to traditional segments.
- Traditional:Ornate detailing, carved hardwood elements, and rich stain finishes. Solid hardwood dependency and multi-step finishing protocols concentrate vulnerability to Pacific Northwest harvest constraints and coating compliance timelines.
- Rustic:Distressed wood treatments, reclaimed material emphasis, and farmhouse aesthetic codes. Reclaimed wood sourcing complicates CARB Phase 2 substrate certification due to provenance uncertainty.
- Minimalist:Reduced material mass, hidden hardware, and neutral palettes. Space-efficient proportions align with multifamily developer procurement specifications in urban density corridors.
Contemporary styling holds volume leadership. Minimalist segments are expanding most quickly on urban unit compression trends.
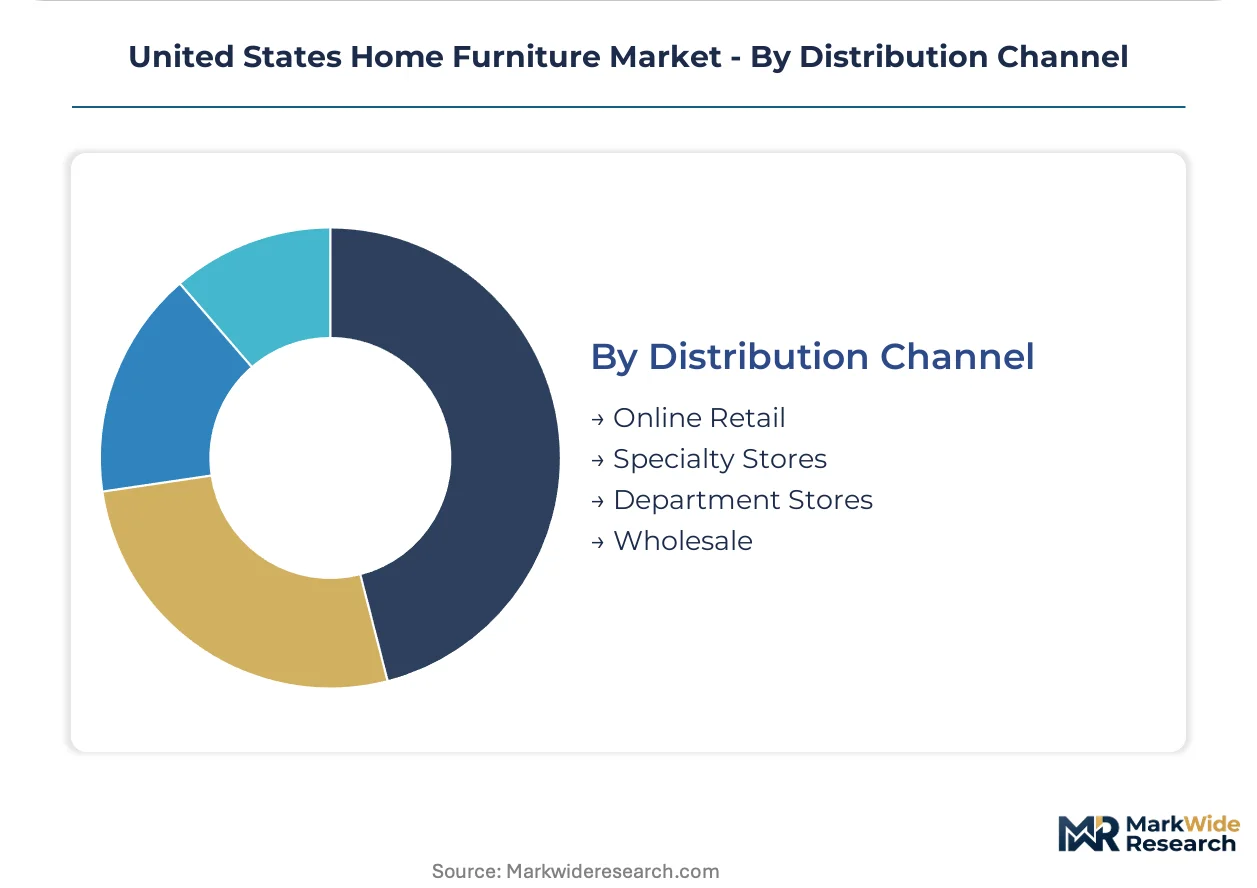
Distribution Channel:
Channel selection determines last-mile cost structures, return friction exposure, and the necessity of augmented reality investment for conversion optimization.
- Online Retail:Digital-native platforms with direct-to-door logistics and AR visualization tools. Remote-first household segments in Sun Belt migration corridors drive expansion, though return rates remain elevated without tactile evaluation.
- Specialty Stores:Dedicated furniture retailers with showroom floors and white-glove delivery services. High-consideration purchases retain channel preference where physical evaluation determines conversion, particularly for leather and premium wood segments.
- Department Stores:General merchandise retailers with curated furniture assortments. Footprint rationalization compresses category space allocation, shifting volume toward dedicated channels.
- Wholesale:Business-to-business supply for multifamily developers, hospitality specifiers, and institutional buyers. California Title 20 compliance requirements now propagate through procurement specifications, filtering supplier eligibility.
Specialty stores retain volume leadership. Online retail demonstrates the steepest expansion trajectory on logistics integration and AR tool deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas metropolitan corridors concentrate furniture demand acceleration through tax-advantaged development incentives tied to multifamily construction.
Texas
Dallas-Fort Worth and Houston housing starts sustain above-average category velocity as inbound migration concentrates demand for starter and trade-up furniture assortments. Texas does not impose state-level chemical disclosure requirements beyond federal CPSC mandates, reducing compliance friction for suppliers. Austin and San Antonio submarkets exhibit expanding procurement of modular, space-efficient systems for compressed urban unit footprints.
California
CARB Phase 2 formaldehyde emission caps and Title 20 appliance efficiency standards reshape supplier compliance obligations across upholstered and power-integrated segments. The California Air Resources Board enforces the nation's strictest composite wood substrate regulations, pushing manufacturers toward soy-based adhesives. Los Angeles and San Francisco Bay Area corridors concentrate premium furniture consumption despite regulatory cost compression.
Florida
Southeastern Sun Belt migration creates underpenetrated demand nodes for regional distribution center investment and localized last-mile fulfillment. Florida lacks state-specific chemical disclosure mandates beyond federal EPA guidelines. Miami and Tampa metropolitan areas drive demand for contemporary and minimalist styling aligned with multifamily developer specifications.
North Carolina
Historic furniture manufacturing clusters in High Point and Hickory retain production infrastructure despite Asian supply chain dominance. North Carolina maintains moderate regulatory posture with no additive chemical disclosure requirements beyond federal baselines. The Piedmont Triad region sustains domestic upholstery and case goods fabrication through captive manufacturing networks.
United States Home Furniture Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with digital-native platforms capturing remote-first household segments while captive production networks defend lead time advantages. The vendor base concentrates around three strategic archetypes: vertically integrated domestic producers, logistics-integrated digital retailers, and design-forward specialty houses. Competitive moves center on augmented reality tool deployment and white-glove delivery unbundling to reduce return friction.
Within the vertically integrated tier, Ashley Global Retail LLC and La-Z-Boy Incorporated exemplify domestic production scale that shortens lead times against import-dependent rivals. Wayfair Inc. occupies a position as the digital-native platform archetype, capturing demand through direct-to-door logistics paired with virtual visualization tools. Williams-Sonoma Inc. anchors the design-forward specialty segment, commanding full-margin pricing through curated collections in premium channels.
| Leading Market Players |
|---|
| Ashley Global Retail LLC |
| La-Z-Boy Incorporated |
| Wayfair Inc. |
| Williams-Sonoma Inc. |
| Restoration Hardware Inc. |
| Ethan Allen Interiors Inc. |
| Bassett Furniture Industries Inc. |
| Inter IKEA Holding B.V. |
| Crate and Barrel |
| Others |
Value Network & Pricing Analysis
North Carolina upholstery craftsmen anchor domestic production clusters where labor-cost differentials between Piedmont Triad manufacturing networks and Asian assembly operations widen pricing-tier spreads across premium handcrafted and mass-market import-dependent segments.
Pricing Analysis
Short lead time premiums command full-margin positioning against spot inventory discounting in clearance channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by customization depth and white-glove service bundling. Cost compression in mid-tier upholstery intensifies because Canadian softwood lumber duties and foam reformulation mandates squeeze material budgets. First-time homebuyers in Texas metropolitan corridors exhibit highest price sensitivity, while design-forward specialty purchasers accept premium positioning for curated collections.
Supply Chain Analysis
Domestic-content thresholds in federal procurement specifications and California Title 20 compliance mandates reshape sourcing toward captive Southeast manufacturing. Engineered wood substrates and textile upholstery production concentrate in Vietnam, Malaysia, and Indonesia, exposing networks to port congestion volatility. Solid hardwood inputs draw from Appalachian and Pacific Northwest harvest regions, with soy-based adhesive chemistry migrating toward no-added-formaldehyde resin systems. Tariff exposure on Chinese component imports constrains margin flexibility for import-dependent assemblers. Distribution runs through regional fulfillment centers in Dallas-Fort Worth and Atlanta corridors, with last-mile white-glove delivery unbundling from traditional retail take-home models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive adhesive chemistry capabilities and in-house finishing operations determine compliance survival against regulatory chemistry mandates.
For Market Incumbents: Anticipate consolidation pressure from digital-native platforms by securing captive manufacturing networks in North Carolina and Texas that compress lead times against Asian import rivals. Defend positioning through CARB Phase 2 certification investment and soy-based adhesive chemistry standardization that excludes smaller competitors from California procurement specifications.
For New Entrants and Emerging Players: IRA residential energy incentives in the United States open a window for furniture-integrated power component specialists to penetrate builder channel specifications previously locked by incumbent electrical subsystem suppliers. Target Florida Sun Belt migration corridors where underpenetrated demand nodes lack legacy retail footprint density. Deploy augmented reality visualization tools paired with direct-to-door logistics to capture remote-first household segments without showroom real estate investment.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated domestic producers given EPA VOC coating compliance timelines that favor capital-intensive spray booth reconfiguration capabilities. Long-term viability centers on five-to-ten year regulatory chemistry harmonization trajectories. Target acquisition archetypes include captive adhesive chemistry manufacturers and Southeast distribution hub operators. Monitor CPSC flammability standard expansion proposals as inflection signals for foam reformulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Footprint Expansion | North Carolina and Texas production networks shorten lead times against Vietnamese import-dependent rivals. |
| Soy-Based Adhesive Chemistry Standardization | CARB Phase 2 compliance enables California market access while excluding reformulation-limited competitors. |
| Augmented Reality Visualization Deployment | Web-based AR tools reduce return friction for Wayfair and digital-native platform conversions. |
| White-Glove Delivery Unbundling | Direct-to-door assembly services displace traditional retail take-home models in metropolitan corridors. |
| Title 20 Electrical Subsystem Redesign | California efficiency standards compliance preserves specification eligibility in multifamily developer procurement. |
Research Methodology
Document review covered SEC 10-K filings, CPSC regulatory dockets, and CARB compliance certifications, complemented by interviews with furniture manufacturing executives, multifamily developer procurement managers, specialty retail buyers, and chemical adhesive suppliers. Secondary validation drew from ASTM standards documentation, EPA VOC emission databases, and customs trade records. Bottom-up shipment data triangulated against top-down housing start correlations across Texas, California, Florida, and North Carolina metropolitan corridors.
Segment-level demand modeling produced volume and value trajectories across the projection horizon by product type, material chemistry, styling positioning, and distribution channel. The analytical framework incorporated upholstery flammability compliance tiering, composite wood substrate emission grading, and power-integrated component efficiency classification. CAGRs derived from regression analysis against household formation rates, inbound migration patterns, and multifamily unit compression indices.
Caveats apply where hardwood input cost volatility, tariff regime adjustments, or state-level chemical disclosure fragmentation could materially shift the outlook beyond modeled parameters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Sustainable Home Furniture Market
Furniture
Portering Chair Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
India Furniture Market
Furniture
Plastic Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
Lecterns Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Global Home Furniture Market
Furniture
GCC Home Furniture Market
Furniture
Europe Home Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
Brazil Furniture Market