
 United States Luxury Furniture Market | 2026-2036
United States Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Luxury Furniture Market Analytics
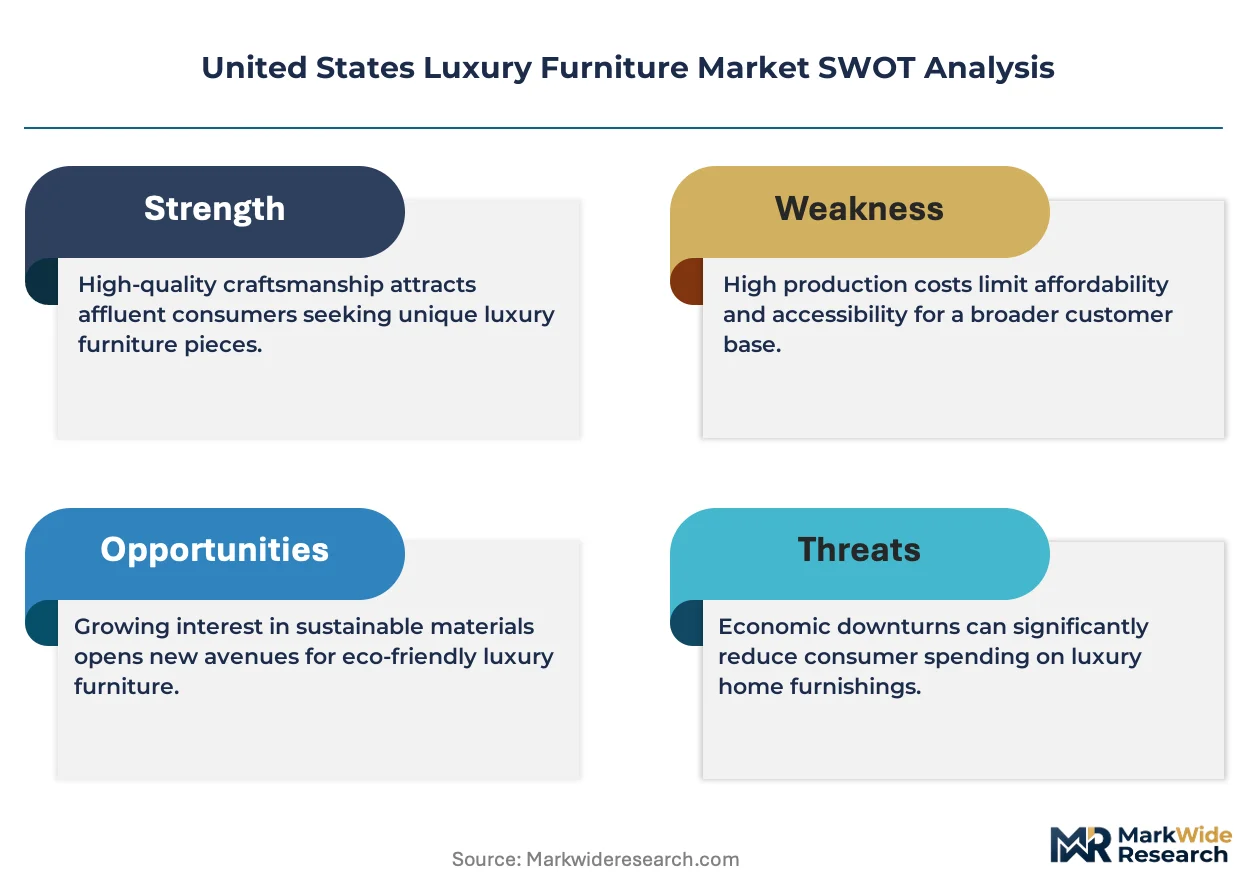
Sustainable engineered wood is decoupling from traditional solid hardwood in premium case goods, altering cost structures and finishing techniques across the supply base. RH (Restoration Hardware) leverages direct-to-consumer gallery networks to control pricing and brand narrative in major metros. Herman Miller anchors its position through deep R&D investment in ergonomic seating systems for executive environments. MillerKnoll competes by unifying heritage brands under a single commercial platform spanning residential and workplace segments.
United States luxury furniture comprises high-design interior products crafted from premium materials such as full-grain leather, FSC-certified hardwoods, and hand-finished metals, typically produced in limited runs with artisan-level fabrication for residential estates, hospitality venues, and corporate headquarters. Sofas and chairs command the largest share of consumer expenditure due to replacement frequency and visible placement in living spaces. The wood material segment sustains premium positioning through heirloom positioning and certified sourcing programs. Hospitality end users represent the fastest-growing demand pool as boutique hotel developers prioritize distinctive interior identities.
The EPA enforces formaldehyde emission standards under TSCA Title VI, compelling domestic manufacturers to certify composite wood products and maintain chain-of-custody documentation. California Air Resources Board regulations extend these requirements with additional testing protocols, effectively setting the compliance floor for national distribution. The Consumer Product Safety Commission monitors flammability standards for upholstered furniture, shaping foam and fabric selection across the value chain. Stakeholders must track evolving state-level chemical disclosure mandates and building code alignments that will determine which material portfolios retain market access.
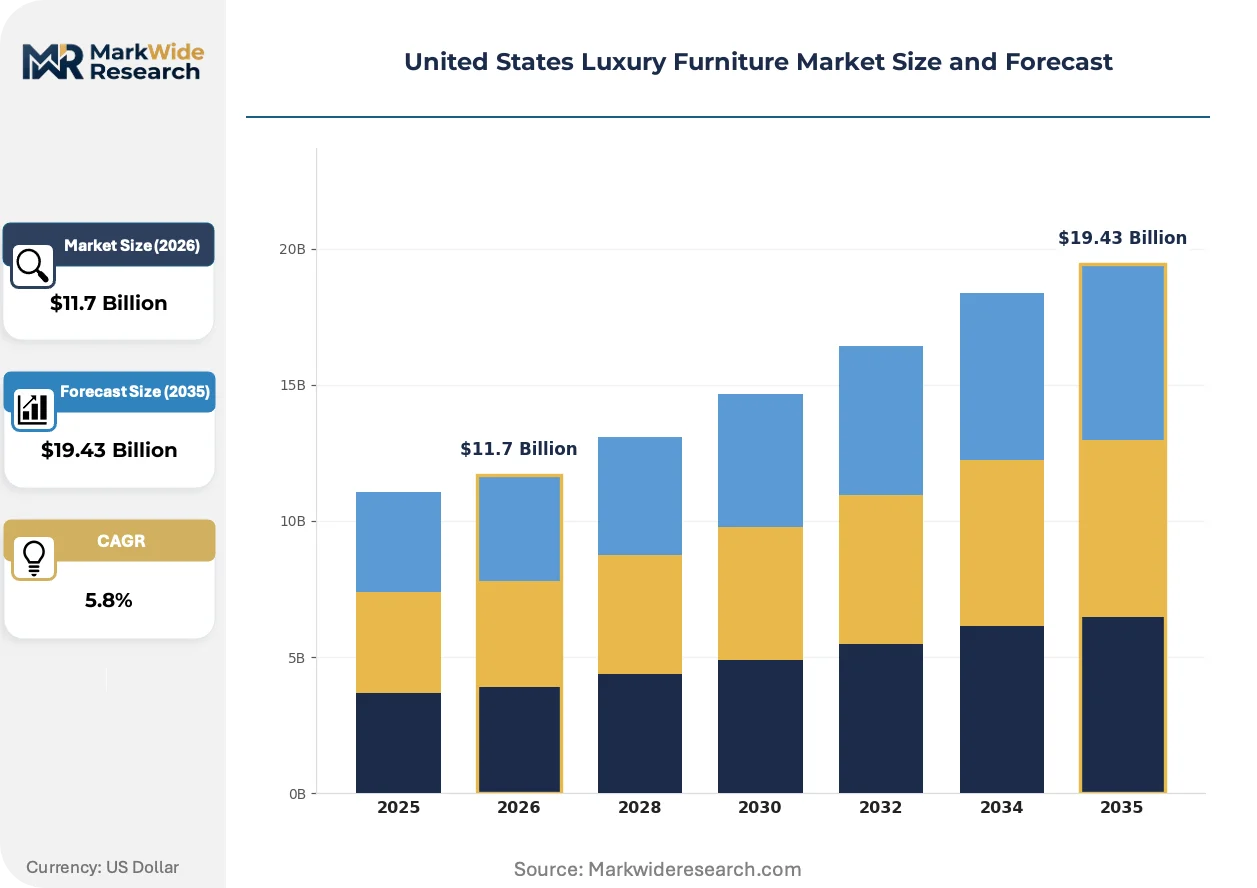
Market Dynamics
California's Title 24 energy efficiency standards and EPA TSCA Title VI formaldehyde emission rules are compressing material certification timelines while elevating compliance costs for domestic manufacturers serving high-net-worth residential buyers.
Growth Catalysts
- Boutique hotel development:Hospitality end users in Texas metropolitan corridors are prioritizing distinctive interior identities, pulling custom upholstery and case goods procurement into accelerated design cycles.
- FSC-certified hardwood sourcing:Heirloom positioning programs are expanding certified chain-of-custody documentation requirements across premium wood material segments.
- Texas luxury real estate:Dallas and Houston development activity is outpacing national averages, concentrating demand for estate-grade furnishings in these metropolitan corridors.
Market Restraints
- Composite wood certification costs:EPA TSCA Title VI compliance documentation and third-party testing are elevating fixed costs for engineered wood product lines.
- Artisan fabrication bottlenecks:Limited-run production capacity concentrates in specific craft clusters, constraining volume scaling for custom upholstery.
- Full-grain leather input volatility:Hide supply fluctuations and tanning chemical costs are compressing margin predictability for seating manufacturers.
Strategic Opportunities
- Direct-to-consumer gallery networks:Controlled showroom experiences in major metros are enabling pricing autonomy and narrative control for heritage brands.
- Ergonomic seating R&D convergence:Executive environment specifications are merging residential aesthetics with workplace performance requirements.
- California regulatory tailwind:CARB extended testing protocols are creating compliance differentiation for manufacturers with established documentation systems.
Industry Challenges
- Flammability standard adaptation:Consumer Product Safety Commission upholstered furniture requirements are forcing foam and fabric selection requalification across existing product lines.
- Chain-of-custody system integration:Legacy inventory management platforms require reconfiguration to capture material origin data for certification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Luxury Furniture Market |
| Market Size in 2026 | $11.7 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Leather, Wood, Upholstery, Metal Style: Modern, Traditional, Contemporary, Minimalist End User: Residential, Commercial, Hospitality, Office |
| Companies Covered | Steelcase Inc., Bernhardt Furniture, RH (Restoration Hardware), Baker Furniture, Herman Miller, Williams-Sonoma Inc., Haworth Inc., Hickory Chair, MillerKnoll, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Luxury Furniture Market Evolving Landscape
Sustainable engineered wood is actively decoupling from traditional solid hardwood positioning, while regulatory pressure on chemical emissions intensifies material substitution timelines across the value chain.
Cross-laminated timber and thermally modified wood are expanding into premium case goods fabrication, offering dimensional stability superior to traditional hardwoods in variable humidity environments. Hospitality developers in Austin and Miami are specifying these materials for high-traffic lobby and suite installations. The technology is expanding into finishing technique standardization, compressing the artisan labor component of surface preparation while maintaining visual depth.
EPA TSCA Title VI certification mandates are elevating third-party verification requirements for composite wood products used in residential interiors. Domestic manufacturers must maintain formaldehyde emission documentation across imported and domestic substrate supply chains. California-based producers face the most stringent compliance timelines, with CARB protocols effectively setting the national distribution floor for certified materials.
High-net-worth buyers are consolidating purchasing authority through interior design studios rather than direct retail engagement, compressing traditional furniture gallery foot traffic in secondary markets. Dallas and Houston design firms are capturing procurement decisions for entire residential projects, displacing piecemeal consumer selection. This channel concentration is most visible in Texas metropolitan corridors where luxury real estate development density supports dedicated design studio infrastructure.
United States Luxury Furniture Market Segmentation
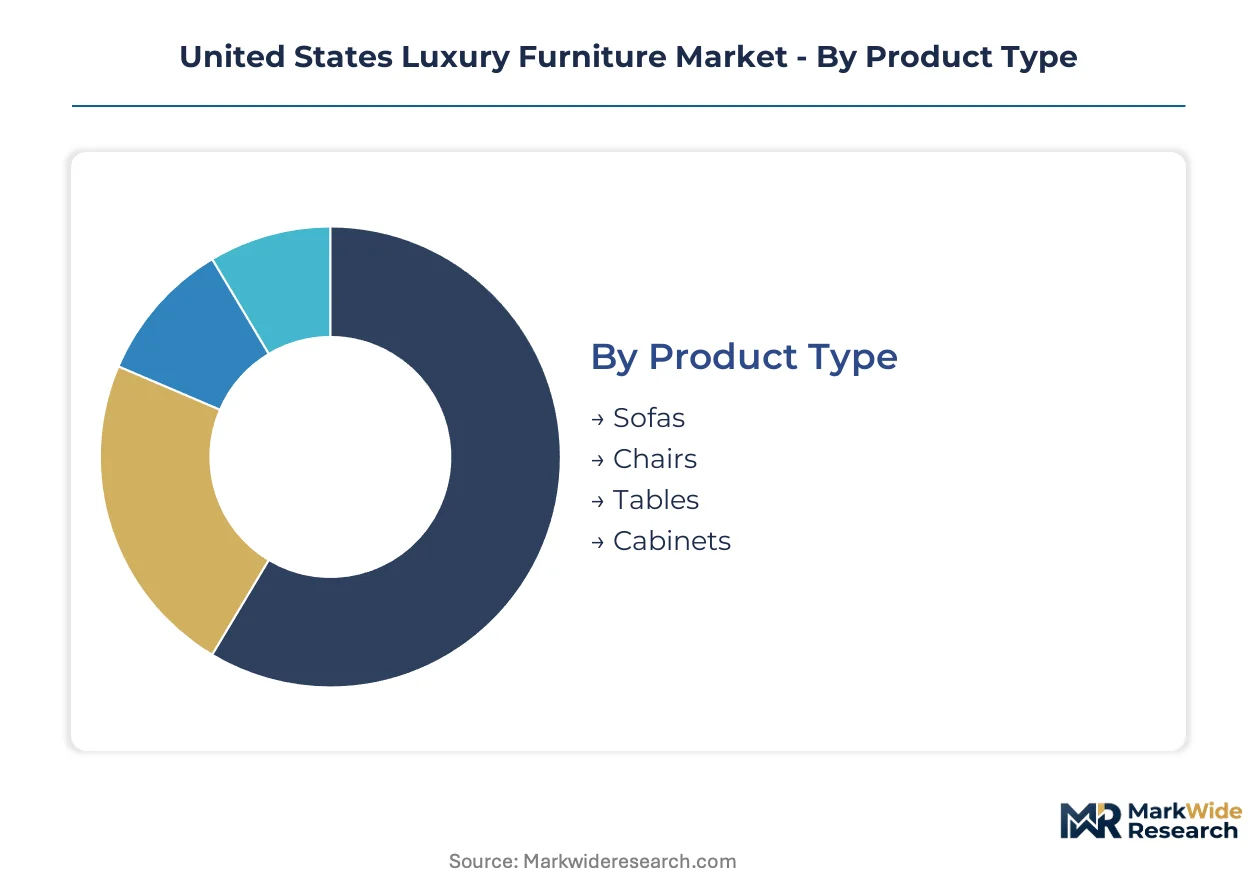
Luxury furniture procurement patterns diverge sharply between visible statement pieces and functional supporting elements. Understanding these splits enables manufacturers to align material certification investments with actual demand concentration rather than assumed category importance.
Product Type:
Volume concentrates in seating systems while premium margins attach to storage and surface categories.
- Sofas:Three-seat and sectional configurations dominate residential procurement in Dallas and Houston estates, where open-plan layouts demand substantial linear footage. Texas luxury real estate developers specify custom upholstery with FSC-certified hardwood frames to satisfy heirloom positioning requirements.
- Chairs:Accent and dining seating command replacement cycles faster than case goods, pulling ergonomic R&D investment from executive furniture specialists. Herman Miller and MillerKnoll compete aggressively for corporate headquarters specifications where residential aesthetics merge with workplace performance standards.
- Tables:Dining and occasional tables sustain artisan fabrication bottlenecks due to complex joinery requirements.
- Cabinets:Storage systems face compressed margins from engineered wood substitution in premium case goods.
Today's leader: Sofas. Tomorrow's challenger: Chairs.
Material:
Certification requirements reshape cost structures across traditional and emerging substrates.
- Leather:Full-grain hides from European tanneries face supply volatility from hide availability fluctuations and tanning chemical cost pressures. Texas design studios specify leather for visible seating in estate projects, though margin predictability compresses for manufacturers locked into long-term hide contracts.
- Wood:FSC-certified hardwoods sustain premium positioning through chain-of-custody documentation that satisfies California CARB protocols and EPA TSCA Title VI requirements. Cross-laminated timber and thermally modified variants are gaining specification in Austin and Miami hospitality installations for dimensional stability.
- Upholstery:High-performance fabrics face CPSC flammability requalification cycles.
- Metal:Hand-finished brass and bronze accent pieces concentrate in limited-run artisan production.
Wood commands current procurement authority. Leather faces the steepest input cost pressures.
Style:
Geographic taste formation drives specification divergence between coastal and interior markets.
- Modern:Clean lines and minimal ornamentation dominate California residential specifications, where Title 24 energy efficiency standards indirectly shape interior spatial planning. RH gallery networks in Los Angeles and San Francisco curate modern collections for tech-industry high-net-worth buyers.
- Traditional:Ornate detailing and heritage references concentrate in Dallas and Houston estates, where established wealth patterns favor classical proportion systems. Texas design studios specify traditional case goods for multi-generational family compounds.
- Contemporary:Transitional aesthetics bridge modern and traditional categories for hospitality developers.
- Minimalist:Reduced material palettes face specification limits in full-service luxury segments.
Modern styling leads coastal markets. Traditional maintains interior strongholds.
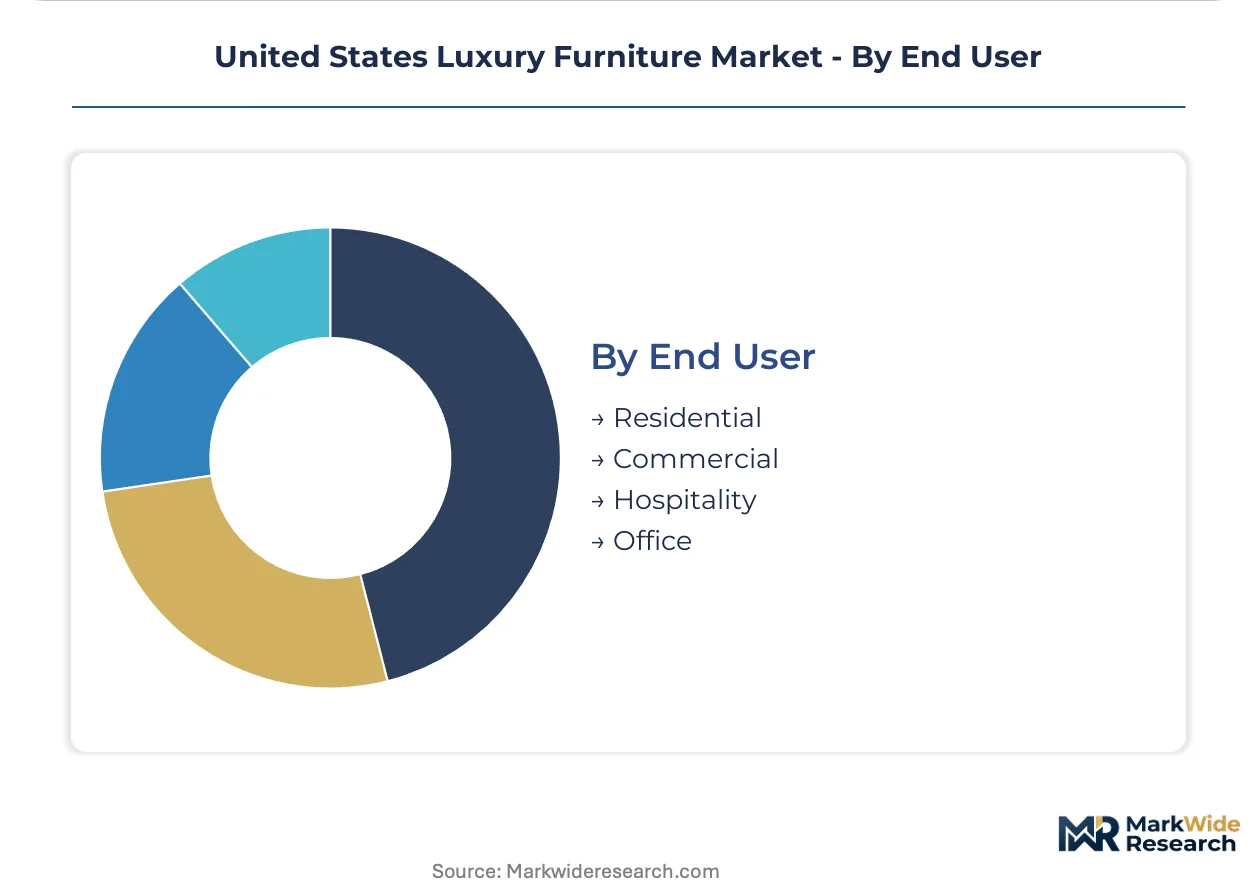
End User:
Channel concentration shifts procurement authority away from direct retail engagement.
- Residential:High-net-worth buyers in Texas metropolitan corridors consolidate purchasing through design studios rather than gallery visits, compressing foot traffic in secondary markets. Estate-grade furnishing decisions for entire projects now rest with Dallas and Houston firms.
- Hospitality:Boutique hotel developers in Austin and Miami are expanding most quickly, prioritizing distinctive interior identities that pull custom upholstery and case goods into accelerated design cycles. This segment demands materials that withstand high-traffic lobby and suite installations.
- Commercial:Corporate headquarters specifications merge residential aesthetics with ergonomic performance requirements.
- Office:Workplace transformation post-pandemic redirects procurement toward residential-influenced executive environments.
Residential holds volume dominance. Hospitality claims the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas metropolitan corridors anchor demand concentration in the United States luxury furniture market, with Dallas and Houston development activity outpacing national benchmarks. California regulatory frameworks establish compliance baselines that propagate nationwide. Interior design studios in both states are consolidating procurement authority for estate-grade residential projects.
California
Tech-industry high-net-worth buyers in Los Angeles and San Francisco drive modern styling preferences through RH gallery networks. CARB extended testing protocols exceed EPA TSCA Title VI baselines, forcing manufacturers to maintain dual certification documentation. San Diego and Orange County design studios specify FSC-certified hardwood frames for coastal estate projects facing Title 24 energy efficiency spatial constraints.
Texas
Dallas and Houston luxury real estate developers specify custom upholstery with heirloom positioning for multi-generational family compounds. State-level building codes align with federal flammability standards without additional chemical disclosure mandates. Austin boutique hotel developers accelerate design cycles for distinctive lobby installations, pulling thermally modified wood specifications from regional fabricators.
New York Metro
Corporate headquarters in Manhattan merge residential aesthetics with ergonomic performance requirements for executive environments. CPSC flammability monitoring shapes foam and fabric selection for upholstered furniture distributed through Tri-State area showrooms. Brooklyn and Queens craft clusters concentrate artisan fabrication capacity for limited-run case goods with complex joinery.
Florida
Miami hospitality developers specify cross-laminated timber for high-traffic suite installations requiring dimensional stability in humid coastal conditions. The state defers to federal EPA emission standards without additional substrate testing protocols. Palm Beach and Naples residential estates favor traditional styling through established wealth procurement patterns managed by dedicated design studios.
Pacific Northwest
Seattle and Portland residential buyers prioritize sustainable engineered wood with documented chain-of-custody for certified sourcing programs. Oregon and Washington state environmental regulations supplement federal requirements with additional wood product disclosure rules. Regional fabricators specialize in thermally modified surface preparation techniques that compress artisan labor components while maintaining visual depth.
United States Luxury Furniture Market Competitive Landscape
Global majors compete with regional champions across distribution architecture, with heritage conglomerates and direct-to-consumer platforms occupying distinct competitive tiers. The market structure fragments across gallery networks, design studio channels, and contract specification routes. Three archetypes dominate: vertically integrated heritage houses, ergonomic R&D specialists, and unified multi-brand platforms. Consolidation through brand portfolio unification and direct-to-consumer gallery expansion represent the dominant competitive moves.
Among heritage-focused fabricators, RH and Baker Furniture exemplify direct-to-consumer gallery strategies that control pricing autonomy in major metros. Herman Miller and MillerKnoll occupy positions spanning residential aesthetics and workplace performance requirements, with the latter representing unified platform consolidation of multiple heritage brands. Steelcase Inc. anchors the contract specification tier for corporate headquarters environments. These named entities illustrate archetype differentiation rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Steelcase Inc. |
| Bernhardt Furniture |
| RH (Restoration Hardware) |
| Baker Furniture |
| Herman Miller |
| Williams-Sonoma Inc. |
| Haworth Inc. |
| Hickory Chair |
| MillerKnoll |
| Others |
Value Network & Pricing Analysis
Texas design studio consolidation for estate-grade residential projects anchors pricing power in direct-to-consumer gallery networks and certified material premiums. CARB protocol compliance costs and FSC-certified hardwood scarcity feed directly into tiered pricing structures that separate heirloom-positioned pieces from engineered wood alternatives.
Pricing Analysis
Input-cost pass-through from European tannery hide supply fluctuations and tanning chemical volatility compresses margin predictability for full-grain leather seating manufacturers. Three-tier pricing structure across premium heirloom, certified standard, and economy-engineered levels differentiates by FSC certification grade and artisan labor intensity. Pricing pressure stems from EPA TSCA Title VI third-party testing requirements elevating fixed costs for composite wood product lines. Hospitality developers in Austin and Miami show least price sensitivity due to accelerated design cycle budgets, while secondary market retail galleries face greatest compression from channel displacement.
Supply Chain Analysis
Single-source vulnerability sits with Italian and German tanneries for full-grain hide supply to Texas upholstery fabricators. Raw material dependencies encompass FSC-certified Appalachian hardwoods, thermally modified timber from Pacific Northwest craft clusters, and brass casting capacity concentrated in Brooklyn and Queens artisan workshops. Supply chain risk centers on tariff exposure for European hide imports and CARB documentation bottlenecks for cross-border substrate distribution. Distribution runs through design studio procurement consolidation in Dallas and Houston, displacing traditional gallery foot traffic in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States luxury furniture market functions as a stable compounder, with Texas luxury real estate development density and hospitality specification cycles providing steady demand foundation across economic cycles.
For Market Incumbents: Extend gallery network control in California metros where Title 24 spatial constraints and tech-industry buyer concentration sustain pricing autonomy. Deepen backward integration into FSC-certified hardwood sourcing to defend against CARB documentation bottlenecks and EPA TSCA Title VI compliance cost escalation. Anchor position through ergonomic R&D convergence for executive environment specifications where Herman Miller and MillerKnoll compete aggressively. For New Entrants and Emerging Players: Design studio partnerships in Texas metropolitan corridors offer the most penetrable channel entry, as Dallas and Houston firms consolidate procurement authority for entire estate projects. Target Austin boutique hotel developers seeking distinctive interior identities with thermally modified wood specifications that compress artisan labor components. Lead with cross-laminated timber dimensional stability credentials for high-traffic hospitality installations in humid coastal conditions. For Investors and Strategic Acquirers: Heritage brand conglomerates represent the most active acquirer in this space, pursuing unified platform consolidation across residential and workplace segments. Long-term viability rests on direct-to-consumer gallery infrastructure and certified chain-of-custody documentation systems that create compliance differentiation. Monitor Texas luxury real estate permitting velocity as the signal to watch for demand inflection, with Austin hospitality development pipeline providing secondary confirmation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Gallery Expansion | Controlled showroom experiences in Los Angeles and San Francisco enable pricing autonomy for RH and heritage brands. |
| FSC-Certified Hardwood Backward Integration | Captive Appalachian sourcing defends against CARB documentation bottlenecks and EPA compliance cost escalation. |
| Ergonomic Seating R&D Convergence | Executive environment specifications merging residential aesthetics with workplace performance requirements anchor Herman Miller's position. |
| Design Studio Channel Partnership | Dallas and Houston procurement consolidation displaces traditional gallery foot traffic for estate-grade residential projects. |
| Thermally Modified Wood Certification | Pacific Northwest surface preparation techniques compress artisan labor while maintaining visual depth for Austin hospitality developers. |
Research Methodology
Bottom-up residential and hospitality procurement modeling reconciled against top-down material supply tracking forms the analytical core of this study. Primary interviews with Texas design studio principals, California gallery network directors, FSC chain-of-custody auditors, and EPA compliance officers combined with secondary validation from CARB regulatory filings, Title 24 energy code documentation, and hospitality development permit databases. Triangulation across these sources ensures segmentation integrity across product type, material certification grade, and end-user channel concentration.
Historical trendline analysis of luxury real estate permitting velocity and hospitality development pipeline activity informed projection framework construction. Segmentation modeling spans product type, material substrate, styling preference, and end-user channel, with geographic demand concentration calibrated to Texas metropolitan corridor development benchmarks. CAGRs derive from fitted trend analysis across the projection horizon, incorporating EPA regulatory timeline assumptions and FSC-certified hardwood supply elasticity parameters specific to Appalachian sourcing regions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California regulatory stringency evolution and European hide supply volatility. Forecasts reflect documented assumptions regarding Title 24 spatial constraint persistence and Texas luxury real estate development density maintenance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Bamboo Furniture Market
Furniture
Children Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Unfinished Wood Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
North America High-End Furniture Market
Furniture
Italy Furniture Market
Furniture
North America Slide Rails Market
Furniture
Chaises Longue Market
Furniture
Home Furnishings Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
Fireplace Mantels Market