
 Vietnam Automotive Engine Oils Market | 2026-2036
Vietnam Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Automotive Engine Oils Market Analytics
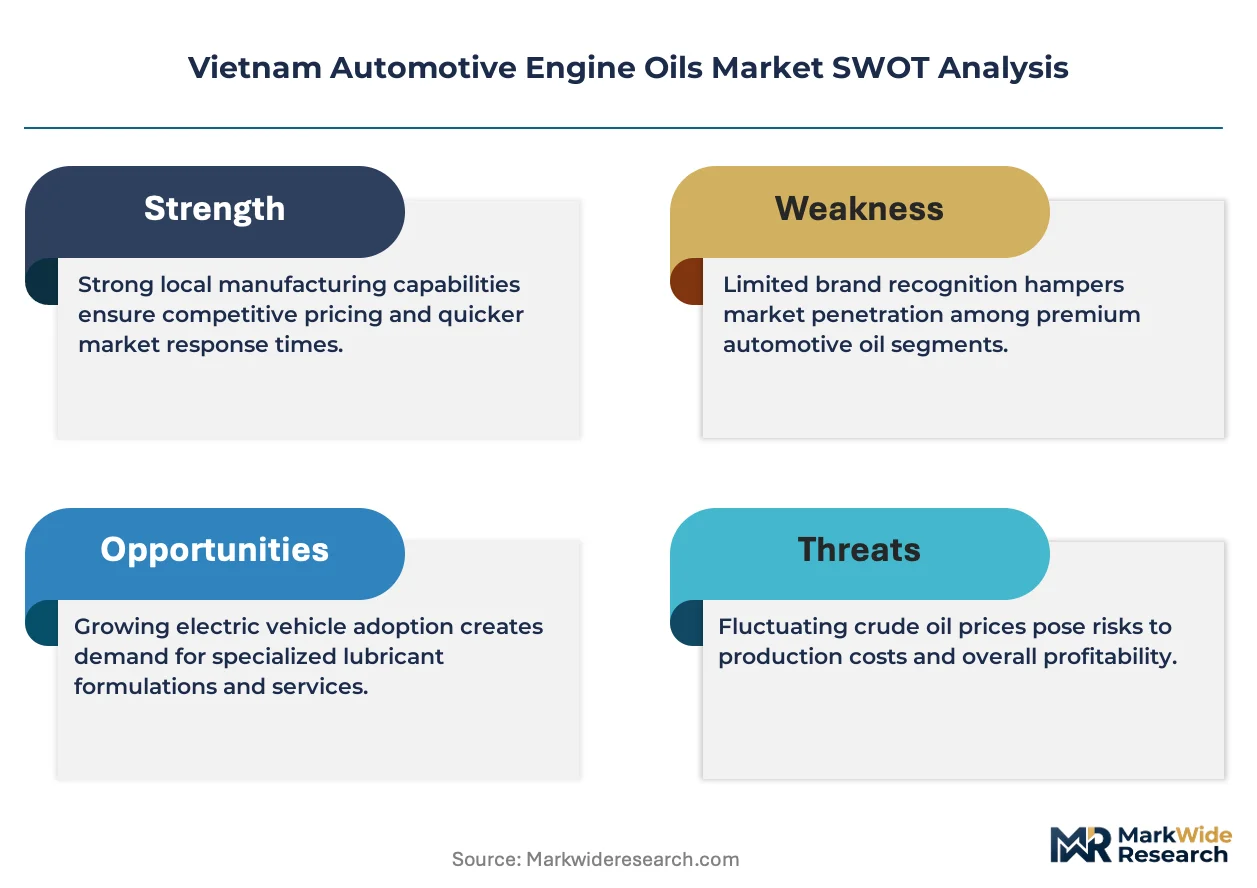
Group III base oils are displacing traditional mineral stocks and is realigning cost structures for domestic formulators. Shell Plc leverages its global supply chain to secure consistent Group III feedstock access for Vietnamese blending operations. Petrolimex (PLX) anchors its position through captive distribution across provincial fuel stations and service centers. BP Plc (Castrol) differentiates via technical service partnerships with authorized dealer networks in Ho Chi Minh City and Da Nang.
Vietnam automotive engine oils are lubricating formulations designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines operating under tropical humidity and stop-go traffic conditions; they typically comprise base oil blends (70-90%) plus detergent-dispersant, anti-wear, and viscosity modifier additive packages balanced to OEM drain interval specifications. Synthetic formulations command premium positioning as turbocharged gasoline direct injection engines proliferate in locally assembled passenger cars, while mineral oils retain volume leadership in the motorcycle segment where cost sensitivity dominates owner behavior and informal service channels prevail.
Vietnam's Ministry of Transport enforces Euro 5 emission standards that tighten limits on particulate matter and nitrogen oxides, compelling lubricant producers to develop lower SAPS (sulfated ash, phosphorus, sulfur) formulations compatible with exhaust aftertreatment systems. The country's national standards body (STAMEQ) administers TCVN conformity assessment requirements that govern product labeling, performance claims, and import documentation for engine oils distributed domestically. Stakeholders must monitor how proposed carbon intensity disclosure rules from the Ministry of Natural Resources and Environment reshape procurement criteria for fleet operators and state-owned transport enterprises.
Market Dynamics
The Ministry of Transport's Euro 5 emission deadlines are compressing formulation cycles for domestic blenders, forcing rapid transitions to lower-SAPS chemistries that protect exhaust aftertreatment hardware while maintaining engine durability under tropical operating conditions.
Growth Catalysts
- Euro 5 Compliance Deadlines:Vietnam's Ministry of Transport mandates tighter particulate and NOx limits, compelling fleet operators to upgrade lubricant specifications for compatibility with diesel particulate filters and selective catalytic reduction systems.
- Domestic Vehicle Assembly Expansion:Rising output from Hyundai, Toyota, and Kia manufacturing plants in Thai Nguyen and Quang Ninh provinces generates captive demand for factory-fill and service-fill formulations.
- Group III Base Oil Transition:Synthetic base stock adoption accelerates as turbocharged gasoline direct injection engines proliferate in locally assembled passenger cars, requiring higher oxidative stability and extended drain intervals.
Market Restraints
- Feedstock Import Dependence:Vietnam possesses no domestic Group II or Group III base oil production, leaving blenders exposed to Singapore refinery output fluctuations and freight cost volatility from Middle Eastern suppliers.
- Motorcycle Segment Price Sensitivity:Mineral oil formulations retain volume dominance in two-wheeler applications where informal service channels and owner self-maintenance resist premium synthetic pricing.
- Additive Package Concentration:Four global suppliers control the majority of detergent-dispersant and anti-wear chemistry, limiting domestic blenders' negotiating leverage on formulation costs.
Strategic Opportunities
- Mekong Delta Fleet Penetration:Commercial logistics operators in Can Tho and Long An provinces remain underserved by technical service networks, creating whitespace for branded distributor partnerships.
- Carbon Disclosure Procurement Criteria:Proposed carbon intensity reporting rules from Vietnam's Ministry of Natural Resources and Environment will favor lubricant suppliers with verified lifecycle assessments and renewable content certifications.
- Used Oil Collection Integration:Reverse logistics infrastructure for waste lubricant re-refining remains nascent, offering first-mover advantage to blenders establishing closed-loop collection programs with industrial fleet accounts.
Industry Challenges
- Formulation Talent Scarcity:Domestic universities produce limited tribology and lubricant chemistry specialists, forcing blenders to rely on expatriate technical staff or overseas R&D support from parent companies.
- TCVN Certification Timelines:STAMEQ conformity assessment procedures for new product registrations create 4-6 month approval windows that delay market entry for reformulated low-SAPS products.
- Counterfeit Product Infiltration:Mislabeled and adulterated lubricants distributed through unlicensed roadside vendors erode brand trust and create warranty liability exposure for authorized service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Automotive Engine Oils Market |
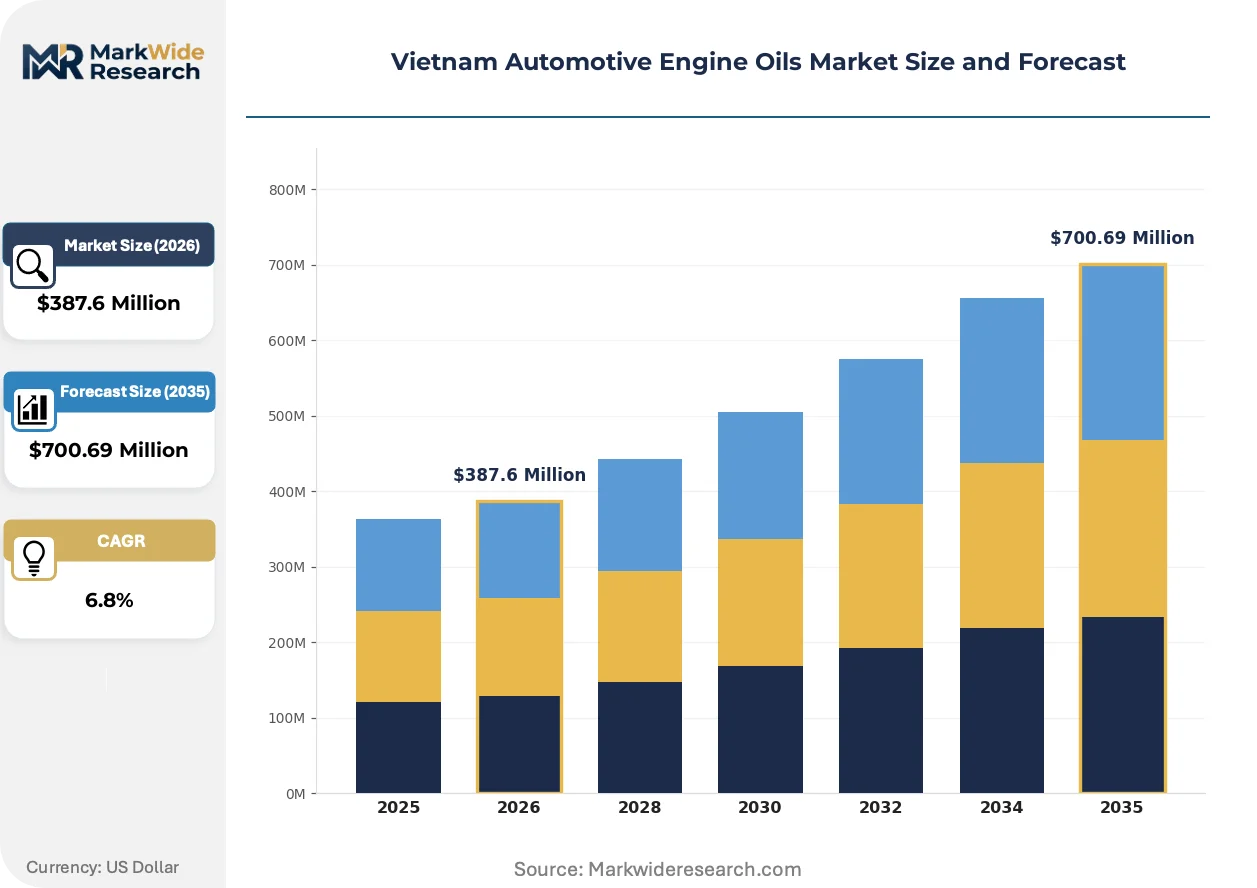
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Oil Type: Synthetic, Semi-synthetic, Mineral, Bio-based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Application: Passenger Cars, Light Trucks, Heavy-duty Vehicles, Motorcycles Packaging Type: Bottles, Drums, Bulk, Pails |
| Companies Covered | Petrolimex (PLX), Shell Plc, ExxonMobil Corporation, BP Plc (Castrol), TotalEnergies, PVOIL, AP Saigon Petro JSC, Mekong Petrochemical JSC, Motul Vietnam (Vilube), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and procurement behavior are diverging sharply between passenger car and motorcycle segments, with synthetic adoption racing ahead in four-wheeler applications while mineral formulations defend volume in two-wheeler service channels.
Group III+ base oils are rewriting performance expectations for gasoline engine lubricants in Vietnam's tropical climate. These highly refined synthetic stocks deliver superior oxidative stability and volatility control under stop-go traffic conditions. Authorized dealer networks for Honda, Mazda, and Ford are specifying Group III+ factory fills for turbocharged models at accelerating rates. This technology is compressing the viable service interval gap between premium synthetics and conventional mineral products.
Vietnam's Ministry of Transport enforces Euro 5 emission standards that tighten enforcement of particulate matter and nitrogen oxide limits nationwide. The regulation compels lubricant producers to develop lower-SAPS formulations compatible with exhaust aftertreatment systems in diesel commercial vehicles. Fleet operators in the Red River Delta corridor are responding by mandating ACEA C-grade specifications in procurement tenders, displacing older API CF-4 inventory.
Commercial fleet procurement is consolidating around technical service partnerships rather than transactional spot purchasing. Large logistics operators in Hanoi and Hai Phong are unbundling lubricant supply from general maintenance contracts, creating dedicated fluid management agreements with direct blender relationships. This pattern is most visible among refrigerated transport and construction equipment fleets where downtime costs exceed lubricant price sensitivity.
Vietnam Automotive Engine Oils Market Segmentation
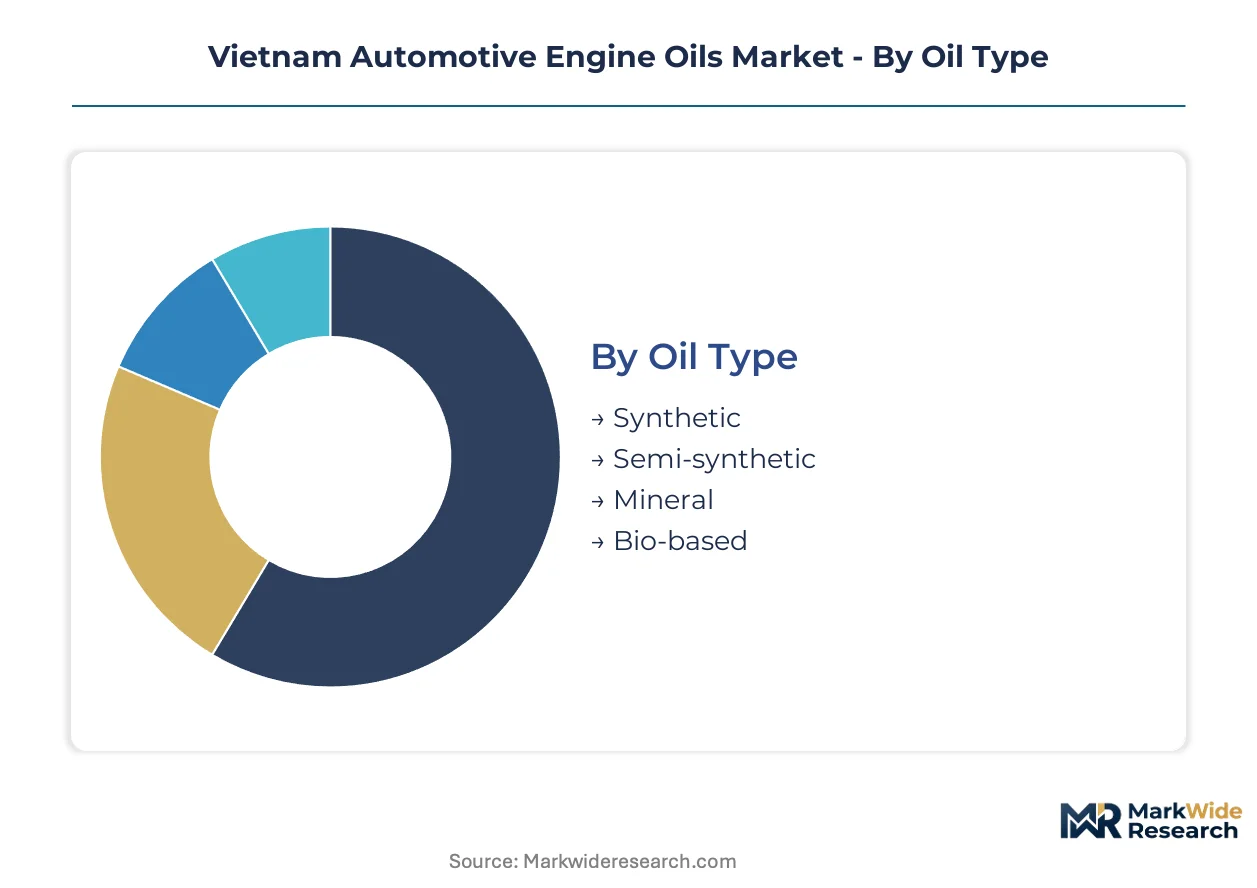
Segmentation in Vietnam's automotive engine oils market reveals how formulation chemistry, packaging economics, and vehicle fleet composition create distinct competitive arenas. Domestic blenders must calibrate product portfolios across four intersecting dimensions where technical specifications and distribution logistics diverge sharply.
Oil Type:
Customization intensity spans from commodity mineral stocks to precision-engineered synthetics, with cost-positioning and performance claims diverging across the spectrum.
- Synthetic:Group III and Group III+ base oils deliver oxidative stability for turbocharged gasoline direct injection engines in locally assembled passenger cars. Demand concentrates in Hanoi and Hai Phong dealer networks where extended drain intervals justify premium positioning against tropical stop-go operating conditions.
- Mineral:Solvent-refined base stocks dominate motorcycle service channels through provincial fuel stations and roadside mechanics. Cost sensitivity in owner self-maintenance segments resists synthetic conversion despite OEM recommendations.
- Semi-synthetic:Blended formulations occupy the mid-tier for aging passenger car fleets and light commercial vehicles seeking partial performance upgrade without full synthetic pricing.
- Bio-based:Vegetable-derived base stocks remain nascent, constrained by feedstock availability and TCVN certification timelines for novel chemistries.
Most installed capacity flows through Mineral formulations. Expansion is steepest in Synthetic grades.
Viscosity Grade:
Grade proliferation tracks engine downsizing trends and climate-specific operating windows across Vietnam's tropical geography.
- 5W-30:The workhorse specification for gasoline passenger cars balances cold-start protection with high-temperature shear stability. Red River Delta fleet operators specify this grade in technical service partnerships with direct blender relationships.
- 10W-40:Mineral-dominant grade defending volume in motorcycle crankcase fills and aging light truck fleets where informal service channels prevail.
- 0W-20:Ultra-low viscosity factory fill for hybrid and downsized turbo engines, requiring Group III+ base stocks with enhanced HTHS performance.
- 15W-50:Heavy-duty diesel specification for commercial vehicles operating in high-load, high-ambient conditions across Quang Ninh mining and construction corridors.
Volume leadership sits with 10W-40. The steepest climb belongs to 0W-20.
Application:
Vehicle category segmentation separates OEM-captive demand from fragmented aftermarket behavior.
- Passenger Cars:Factory-fill and service-fill specifications tied to Hyundai, Toyota, and Kia assembly plants in Thai Nguyen generate predictable demand for ACEA and API-licensed formulations.
- Motorcycles:Two-wheeler lubricant consumption exceeds all other categories combined, with mineral formulations defending share through Petrolimex provincial distribution and unlicensed roadside vendors.
- Heavy-duty Vehicles:Euro 5 compliance is compressing specification cycles for diesel particulate filter-compatible low-SAPS formulations in refrigerated transport and construction equipment fleets.
- Light Trucks:Intermediate duty cycle vehicles operating urban logistics routes in Ho Chi Minh City and Da Nang require versatile 10W-40 or 15W-40 mineral-synthetic blends.
Most formulation output serves Motorcycle applications. Passenger Cars are gaining share fastest.
Packaging Type:
Packaging economics separate retail consumer convenience from industrial procurement efficiency.
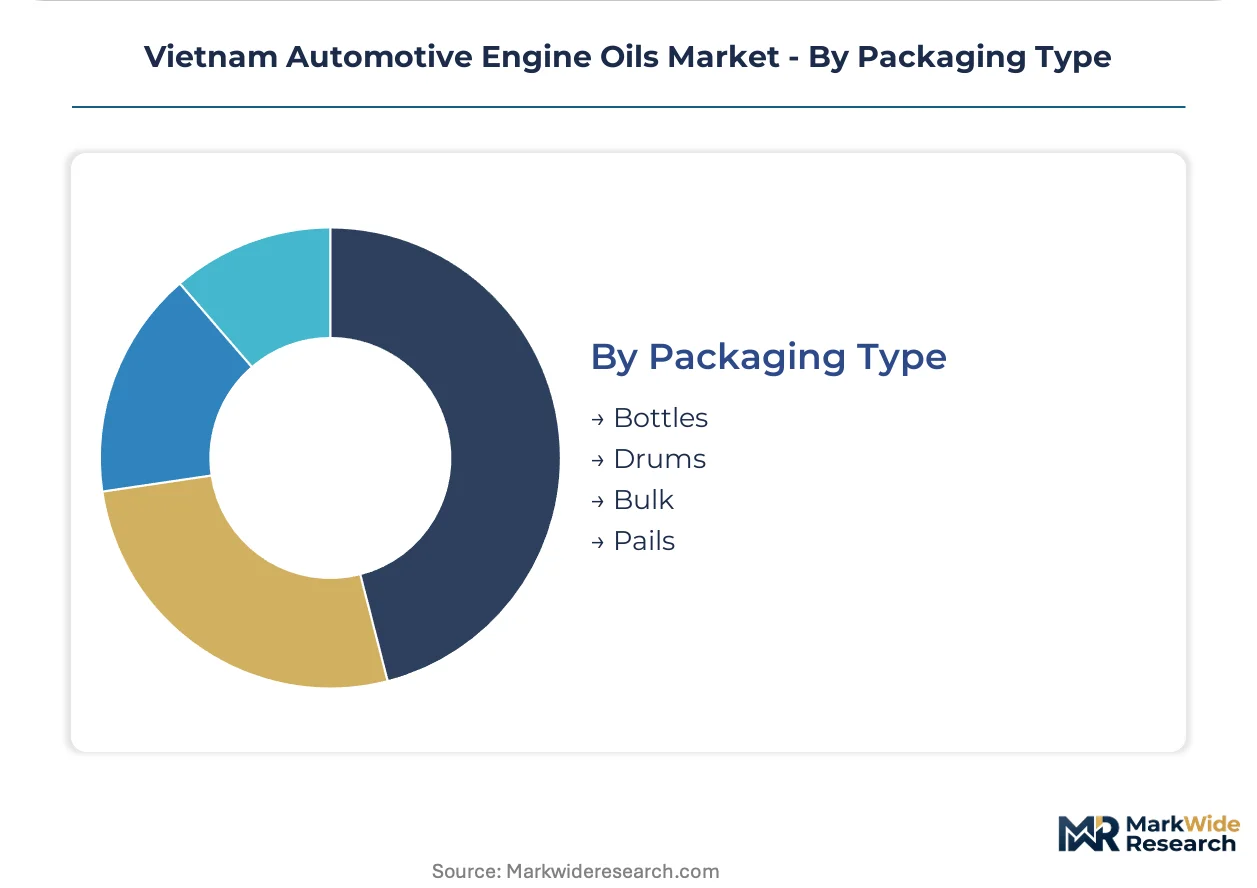
- Bottles:1-liter and 4-liter retail formats dominate motorcycle owner self-maintenance through convenience stores and service stations.
- Bulk:Tanker and flexitank deliveries support fleet direct procurement agreements with logistics operators unbundling fluid supply from general maintenance contracts.
- Drums:200-liter steel containers serve authorized dealer networks and mid-sized commercial workshops in Hai Phong and Can Tho.
- Pails:20-liter plastic containers bridge retail and industrial segments for small fleet operators and independent garages.
Bottles command the largest volume footprint. Bulk formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Delta corridor anchors Vietnam's automotive engine oils demand, with Hanoi and Hai Phong concentrating vehicle density and industrial logistics activity that outpaces southern provinces. Provincial fuel station networks and authorized dealer channels distribute formulations across distinct climate zones and fleet compositions.
Red River Delta
Hyundai and Toyota assembly plants in Thai Nguyen and Quang Ninh provinces generate captive factory-fill demand for ACEA-licensed formulations. The Ministry of Transport's Euro 5 enforcement tightens procurement specifications for diesel particulate filter-compatible lubricants across refrigerated transport fleets. Hai Phong's container port logistics operators unbundle fluid supply from general maintenance contracts, creating direct blender relationships.
Southeast Region
Ho Chi Minh City's urban logistics density drives 5W-30 and 0W-20 consumption for downsized turbo gasoline engines in passenger car fleets. STAMEQ's TCVN conformity assessment procedures govern product labeling and import documentation for distributed formulations. Da Nang's authorized dealer networks for Honda, Mazda, and Ford specify Group III+ factory fills at accelerating rates.
Mekong Delta
Commercial logistics operators in Can Tho and Long An provinces remain underserved by technical service networks, creating whitespace for branded distributor partnerships. The Ministry of Natural Resources and Environment proposes carbon intensity disclosure rules that will reshape procurement criteria for state-owned transport enterprises. Provincial fuel stations through Petrolimex's captive distribution network defend mineral oil volume in light truck applications.
Central Coast
Construction equipment fleets in Quang Ninh mining corridors specify 15W-50 heavy-duty diesel formulations for high-load, high-ambient operating conditions. Euro 5 compliance deadlines compress specification cycles for low-SAPS chemistries protecting selective catalytic reduction systems. Informal roadside service channels in Thanh Hoa and Nghe An resist synthetic conversion despite OEM recommendations.
Vietnam Automotive Engine Oils Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach in Vietnam's automotive engine oils sector. The vendor base separates into three tiers: integrated energy majors with captive supply chains, state-owned petroleum enterprises with provincial fuel station networks, and specialized lubricant blenders serving technical service partnerships. Consolidation pressure concentrates among mid-scale domestic formulators lacking Group III base oil procurement leverage. Dominant competitive moves include backward integration into additive package sourcing and geographic expansion through authorized dealer network partnerships.
Within the integrated energy major tier, Shell Plc and BP Plc (Castrol) occupy positions defined by global supply chain access and technical service infrastructure. Petrolimex (PLX) anchors the state-owned petroleum segment through its captive distribution across provincial fuel stations and service centers. ExxonMobil Corporation sits within the premium synthetic formulation archetype, representing the technology licensing approach to market development.
| Leading Market Players |
|---|
| Petrolimex (PLX) |
| Shell Plc |
| ExxonMobil Corporation |
| BP Plc (Castrol) |
| TotalEnergies |
| PVOIL |
| AP Saigon Petro JSC |
| Mekong Petrochemical JSC |
| Motul Vietnam (Vilube) |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation around ACEA C-grade specifications for Euro 5 compliance is compressing blenders' formulation flexibility and forcing sharper price differentiation between mineral and synthetic tiers. This specification pressure feeds directly into base oil sourcing decisions, with Group III feedstock premiums widening the cost gap against mineral stocks.
Pricing Analysis
Group II and Group III base oil cost pass-through from Singapore refineries dominates pricing dynamics for Vietnamese blenders lacking captive supply. Pricing stratifies across premium synthetic, standard semi-synthetic, and economy mineral tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the motorcycle segment is intensifying because informal service channels resist synthetic conversion despite OEM recommendations. Fleet operators show least price sensitivity, while owner self-maintenance segments in two-wheeler applications remain most cost-conscious.
Supply Chain Analysis
Reverse logistics infrastructure for waste lubricant collection and re-refining remains undeveloped across Vietnam's industrial corridors, constraining closed-loop material recovery. Base oil supply draws from Singapore, South Korea, and Middle Eastern sources, with additive packages resting on detergent-dispersant and anti-wear chemistry from concentrated global suppliers. Single-source vulnerability in Group III feedstock procurement exposes blenders to refinery output fluctuations and freight cost volatility. Distribution runs through Petrolimex's provincial fuel station network, Shell's technical service partnerships, and Castrol's authorized dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's automotive engine oils market functions as a geographic-arbitrage play where Euro 5 compliance deadlines accelerate specification upgrades faster than neighboring ASEAN markets, compressing reformulation cycles and rewarding first-movers with certified low-SAPS portfolios.
For Market Incumbents: Lock in backward integration into additive package sourcing or captive Group III supply agreements to defend margin position against feedstock volatility. Secure TCVN pre-certification for next-generation low-SAPS formulations ahead of STAMEQ approval windows, and deepen technical service partnerships with Red River Delta fleet operators to resist unbundling of fluid supply from maintenance contracts. For New Entrants and Emerging Players: Capture the Mekong Delta whitespace where Can Tho and Long An logistics operators lack technical service network coverage. Target carbon disclosure-ready procurement tenders from state-owned transport enterprises under proposed Ministry of Natural Resources and Environment rules, and establish distributor partnerships with provincial workshops bypassing Petrolimex's mineral-dominated channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale domestic blenders possessing TCVN certification infrastructure and established fleet relationships but lacking Group III procurement leverage. Long-term viability hinges on formulation chemistry capabilities and reverse logistics integration rather than pure distribution scale. Monitor STAMEQ approval velocity for low-SAPS products as inflection indicator for regulatory compliance advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Sourcing | Reduces dependency on four global suppliers controlling detergent-dispersant chemistry for domestic blenders. |
| Low-SAPS Formulation Pre-Certification | Compresses STAMEQ approval timelines ahead of Euro 5 enforcement deadlines for diesel particulate filter compatibility. |
| Mekong Delta Technical Service Expansion | Addresses underserved logistics operators in Can Tho and Long An through branded distributor partnerships. |
| Reverse Logistics Infrastructure Buildout | Captures first-mover advantage in waste lubricant collection for re-refining with industrial fleet accounts. |
| Carbon Disclosure Certification Investment | Aligns with Ministry of Natural Resources and Environment procurement criteria for state-owned transport enterprises. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant formulators, fleet procurement managers, Petrolimex distribution heads, and STAMEQ certification officers with secondary validation. Customs and trade data, vehicle production databases from Thai Nguyen and Quang Ninh assembly plants, and TCVN regulatory filings anchored supply-side modeling. Bottom-up volume builds from viscosity grade and application segmentation triangulated against top-down market sizing from blender capacity and import documentation.
Comparable historical periods anchored the projection framework, with growth trajectories calibrated to base oil import volumes and domestic vehicle assembly output trends across the analysis window. Segmentation dimensions modeled include oil type, viscosity grade, application, and packaging format alongside regional production cluster dynamics. CAGRs derived from regression analysis against macroeconomic drivers and fleet expansion patterns, with specific inputs from Euro 5 compliance timelines and Group III adoption curves in turbocharged gasoline direct injection engines.
Underlying measurement precision varies by segment; synthetic formulations and passenger car applications carry tighter precision than mineral motorcycle volumes where informal channel data remains sparse. Forecasts reflect assumptions around STAMEQ approval timelines, Singapore refinery output stability, and fleet procurement consolidation patterns. Practitioners should monitor STAMEQ certification velocity, Group III base oil freight cost movements, and carbon disclosure rule finalization from the Ministry of Natural Resources and Environment for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Poland Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
Industrial Gear Oil Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Global Process Oil Market
Lubricants
Philippines Commercial Vehicles Lubricants Market