
 Automotive Hypervisor Market | 2026-2036
Automotive Hypervisor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hypervisor Market Analysis
Buyer concentration among automotive OEMs is shifting from fragmented infotainment sourcing toward consolidated cockpit-domain contracts that bundle hypervisor licensing across multiple ECUs. Continental leverages its pre-integrated hardware-software stacks to anchor long-term supply relationships with European premium OEMs. NVIDIA competes through its DRIVE platform's virtualization capabilities, extending its data-center GPU architecture into automotive-grade hypervisor deployments. BlackBerry differentiates via QNX's safety certifications, occupying the high-integrity segment where ISO 26262 ASIL-D compliance is non-negotiable.
An automotive hypervisor is a thin software abstraction layer that partitions a single physical processor into multiple isolated virtual machines, each running distinct operating systems with deterministic resource allocation measured in sub-millisecond interrupt latency. Its primary purpose enables consolidation of disparate automotive functions—infotainment, instrument clusters, ADAS—onto unified compute hardware while maintaining fault containment between safety-critical and non-critical workloads. Type-1 hypervisors lead current deployment volumes due to their direct hardware access and minimal performance overhead, though microkernel architectures are gaining traction in next-generation zonal E/E architectures where formal verification of isolation properties is paramount. Infotainment Systems applications currently dominate licensing revenue, while Advanced Driver Assistance Systems represents the fastest-growing application segment as Level 2+ automation mandates hardware consolidation with mixed-criticality separation.
The EPA's emissions compliance timelines and NHTSA's automated driving system guidance in the US, alongside EMA's parallel emphasis on software traceability for type-approved vehicles in Europe, collectively compel OEMs to adopt certifiable virtualization platforms that document deterministic behavior. ISO 26262 functional safety standards and UN ECE cybersecurity regulations further constrain supplier selection to hypervisor vendors with pre-certified toolchains and documented security development lifecycles. Stakeholders must monitor how zonal E/E architecture transitions redistribute hypervisor value from central compute modules toward edge-domain controllers at the vehicle perimeter.
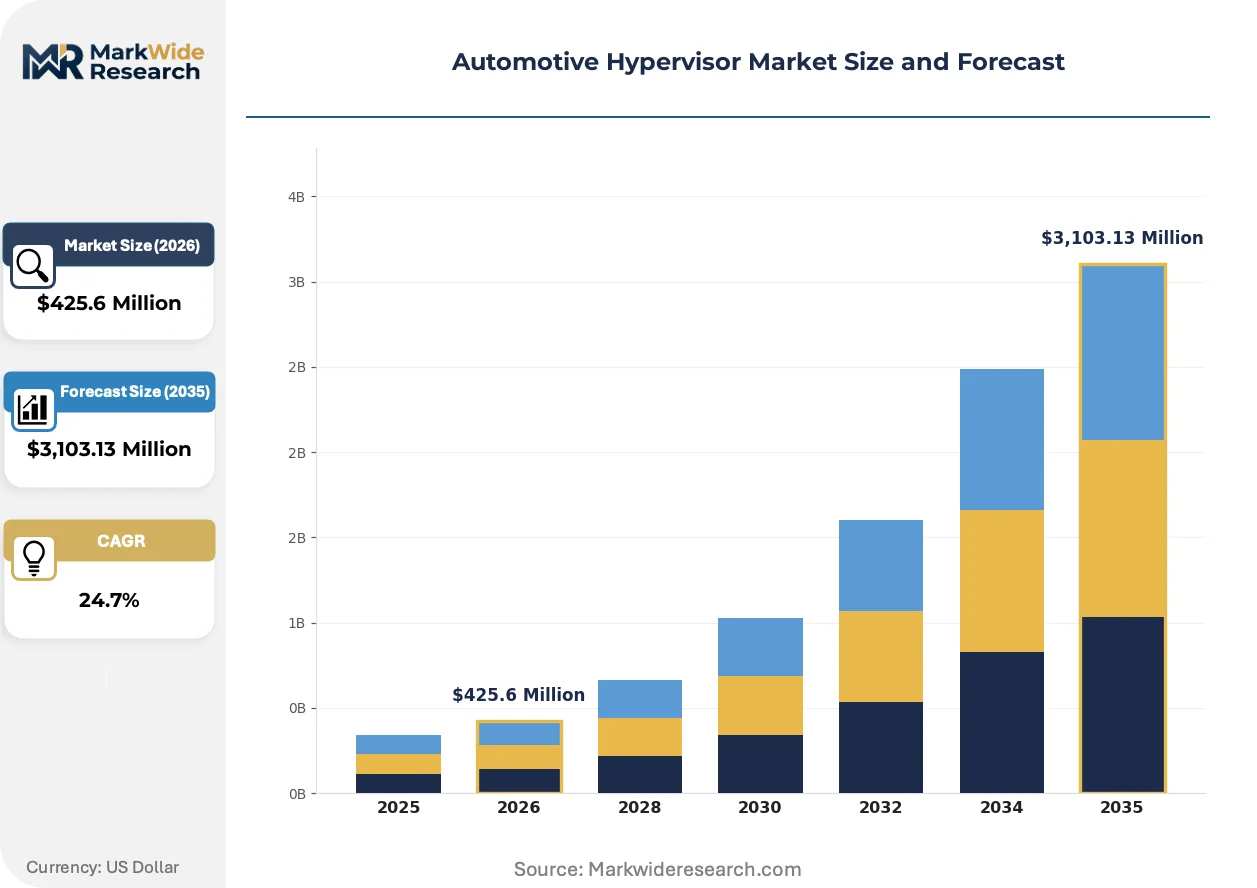
Market Dynamics
The zonal E/E architecture transition is compressing hypervisor deployment from centralized domain controllers toward edge compute nodes at the vehicle perimeter, redistributing software licensing value across the supply chain.
Growth Catalysts
- UN R155 cybersecurity mandates:European type-approval requirements for certified virtualization layers in autonomous driving systems are accelerating OEM procurement of pre-certified hypervisor stacks.
- Software-defined vehicle architectures:Consolidation of disparate ECU functions onto unified compute hardware is creating deterministic demand for mixed-criticality separation technologies.
- Germany's automotive engineering corridor:Engineering concentration around Stuttgart and Munich is generating clustered demand for hypervisor integration expertise and localized supplier development.
Market Restraints
- ISO 26262 ASIL-D certification costs:Functional safety documentation and toolchain qualification impose substantial upfront investment barriers for new market entrants.
- Silicon supply concentration:Dependence on a limited set of automotive-grade SoC vendors constrains hypervisor portability and creates platform lock-in risks for Tier 1 integrators.
- Deterministic latency requirements:Sub-millisecond interrupt response specifications for safety-critical workloads limit viable hypervisor architectures to formally verified microkernel designs.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic manufacturing incentives are attracting hypervisor localization investments for export-oriented production.
- Vehicle-to-cloud workload orchestration:Convergence of edge hypervisors with containerized cloud-native applications is opening new recurring-revenue service models.
- Japan's METI software-defined vehicle roadmap:National standardization initiatives are creating regulatory tailwinds for certified virtualization platforms in domestic OEM supply chains.
Industry Challenges
- Formal verification expertise scarcity:Microkernel isolation property proofing requires specialized mathematical skills that outpace current university pipeline output.
- Legacy ECU integration friction:Retrofitting existing vehicle networks with hypervisor-based consolidation demands extensive gateway reengineering and signal mapping.
- Multi-vendor certification alignment:Synchronizing safety case documentation across hypervisor, SoC, and operating system suppliers extends program timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hypervisor Market |
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $3,103.13 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type-1 Hypervisors, Type-2 Hypervisors, Microkernel, Bare-metal Hypervisors Application: Infotainment Systems, Advanced Driver Assistance Systems, In-Vehicle Networking, Telemetry Solutions End User: Automotive Manufacturers, Tier-1 Suppliers, Software Developers, Research Institutions Technology: Real-time Operating Systems, Virtualization Platforms, Cloud Computing, Edge Computing |
| Companies Covered | Continental, Renesas Electronics, Wind River, Siemens, Robert Bosch, Green Hills Software, NXP Semiconductors, NVIDIA, BlackBerry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hypervisor Market Emerging Trajectories
Virtualization technology is migrating from cockpit-domain consolidation toward zonal edge controllers, compressing the traditional boundary between central compute and distributed intelligence.
Microkernel-based Type-1 hypervisors are decentralizing automotive compute architectures by enabling deterministic workload isolation on resource-constrained edge controllers. Tier 1 suppliers are adopting these architectures for next-generation zonal gateway modules. This migration is decentralizing value capture from central domain controllers toward perimeter electronics.
Europe's CSRD sustainability reporting requirements are mandating software traceability documentation across automotive supply chains. OEMs must now demonstrate environmental impact accounting for embedded software components. Hypervisor vendors with pre-documented security development lifecycles are capturing preferential supplier status in German premium vehicle programs.
Consolidated platform contracting is displacing fragmented ECU-by-ECU software licensing across major OEM procurement organizations. Long-term cockpit-domain agreements now bundle hypervisor licensing across instrument cluster, infotainment, and HUD subsystems. This pattern is most visible in European premium OEM sourcing strategies, where multi-year architecture commitments lock in virtualization platform choices.
Automotive Hypervisor Market Segmentation
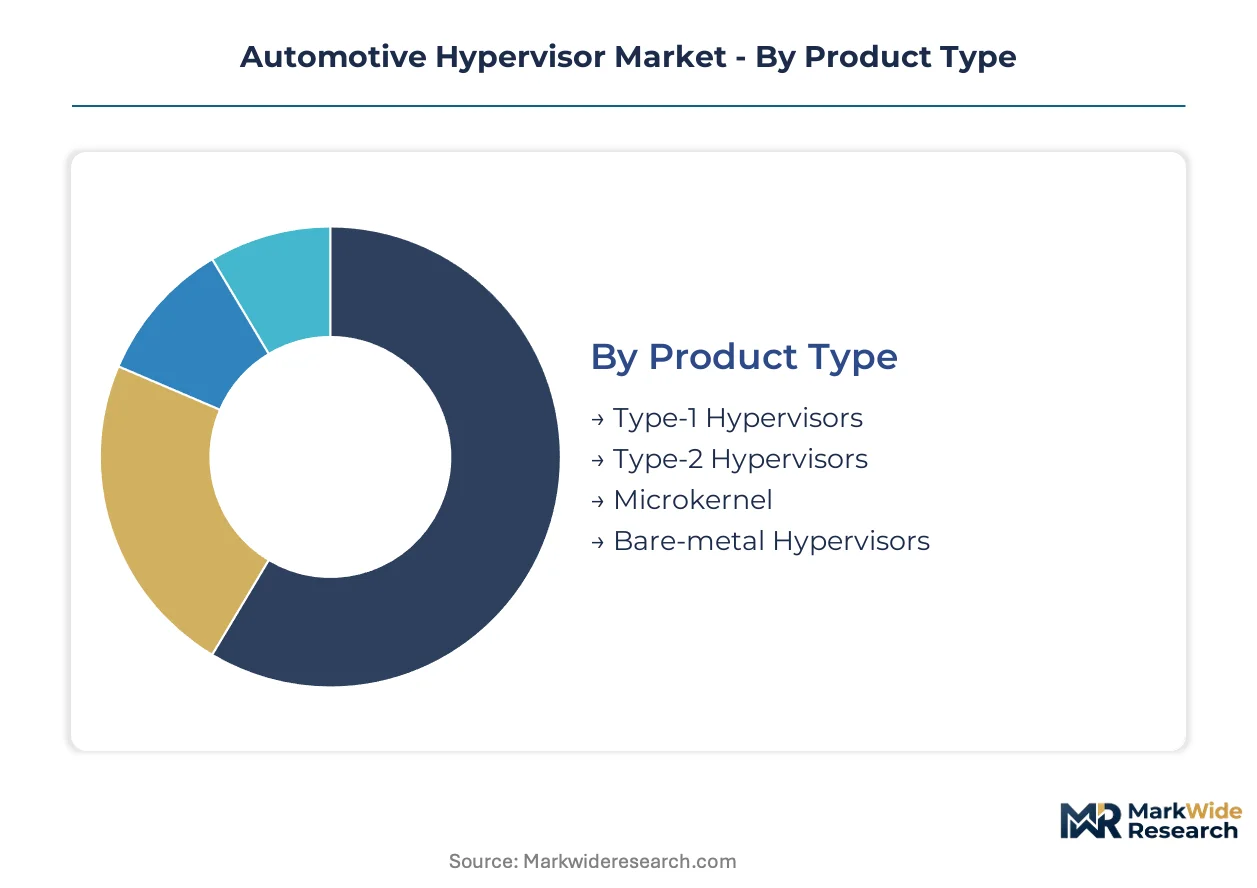
Hypervisor deployment patterns diverge sharply between high-volume cockpit consolidation and premium safety-critical systems. Understanding these splits reveals where licensing value concentrates and which certification tiers command pricing power.
Product Type:
Volume deployment favors bare-metal architectures with minimal overhead, while premium positioning requires formally verified isolation guarantees.
- Type-1 Hypervisors:Direct hardware access eliminates host OS overhead, delivering sub-millisecond interrupt latency for mixed-criticality workloads. Procurement concentrates in German premium OEM cockpit-domain contracts where deterministic performance is mandatory. This architecture anchors current deployment volumes across consolidated instrument cluster and infotainment platforms.
- Microkernel:Minimal trusted computing base enables mathematical proof of isolation properties required for ASIL-D certification. Engineering demand clusters around Stuttgart and Munich for next-generation zonal gateway modules. Formal verification capabilities differentiate suppliers in safety-critical ADAS procurement.
- Type-2 Hypervisors:Hosted architectures suit development environments and non-critical telemetry functions where latency tolerance permits abstraction overhead.
- Bare-metal Hypervisors:Stripped-down designs optimize resource-constrained edge controllers in perimeter zonal architectures.
Mature deployment sits with Type-1 Hypervisors. Newer deployment is concentrated in Microkernel architectures.
Application:
Revenue concentration tracks cockpit-domain consolidation, while growth trajectories align with automation hardware requirements.
- Infotainment Systems:Rich OS isolation from safety-critical instrument clusters drives bulk licensing volumes. European premium OEMs bundle multi-year cockpit-domain agreements spanning HUD, cluster, and center-stack functions. UN R155 cybersecurity mandates accelerate certified virtualization procurement for connected entertainment platforms.
- Advanced Driver Assistance Systems:Mixed-criticality separation enables sensor fusion and path planning on unified compute hardware. German engineering corridors generate clustered integration demand for Level 2+ automation programs. ISO 26262 ASIL-D constraints limit viable suppliers to pre-certified toolchain vendors.
- In-Vehicle Networking:Gateway virtualization consolidates legacy bus protocols onto Ethernet backbone architectures.
- Telemetry Solutions:Over-the-air update isolation and data logging partition non-critical cloud connectivity workloads.
Infotainment Systems capture current licensing value. Advanced Driver Assistance Systems are expanding most quickly.
End User:
Procurement authority is consolidating from fragmented Tier-1 sourcing toward direct OEM platform contracting.
- Automotive Manufacturers:Direct hypervisor licensing for software-defined vehicle architectures displaces historical ECU-by-ECU procurement. Long-term cockpit-domain commitments now lock in virtualization choices across vehicle programs. CSRD traceability requirements favor vendors with documented security development lifecycles.
- Tier-1 Suppliers:Pre-integrated hardware-software stacks anchor supply relationships through bundled hypervisor deployment. Integration expertise concentrates in Germany's automotive engineering corridor around Stuttgart and Munich.
- Software Developers:Virtualization platform access enables application porting across OEM customer bases.
- Research Institutions:Academic partnerships advance formal verification methods and microkernel isolation research.
Established procurement sits with Tier-1 Suppliers. Consolidating authority is shifting toward Automotive Manufacturers.
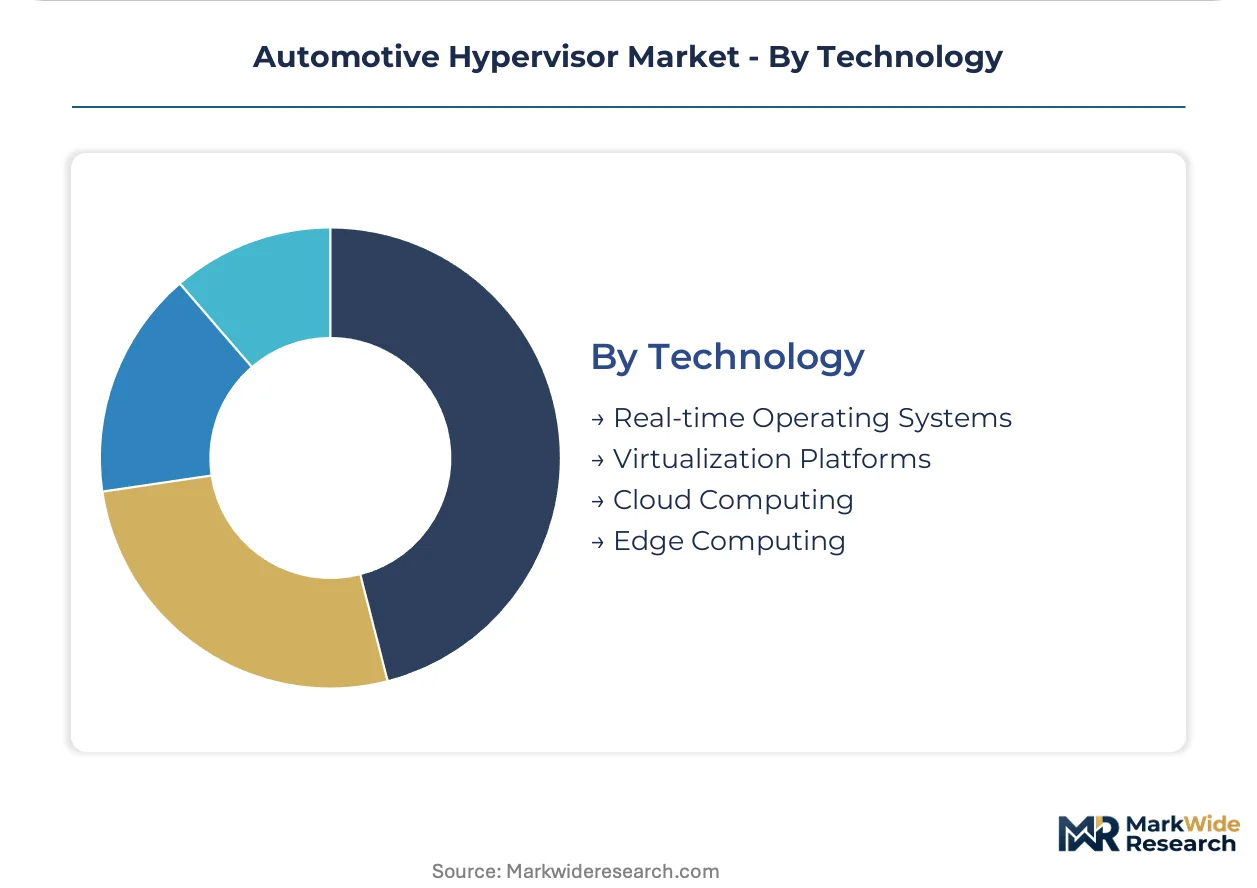
Technology:
Edge-cloud convergence is redistributing value from static virtualization toward orchestrated workload mobility.
- Virtualization Platforms:Core abstraction layer technology enabling OS consolidation and resource partitioning. Certification alignment across hypervisor, SoC, and guest OS suppliers determines program viability. Pre-certified stacks capture preferential status in European type-approval pathways.
- Real-time Operating Systems:Deterministic scheduling guarantees for safety-critical guest workloads. QNX and comparable platforms dominate high-integrity segments where formal verification is non-negotiable.
- Edge Computing:Distributed intelligence at zonal controllers reduces central compute dependency. METI software-defined vehicle roadmaps in Japan create regulatory tailwinds for certified edge virtualization.
- Cloud Computing:Containerized workload orchestration enables vehicle-to-cloud service models and recurring revenue architectures.
Mature integration sits with Virtualization Platforms. Steepest expansion trajectory is concentrated in Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering corridors concentrate hypervisor integration demand, while regulatory mandates in Japan and India reshape procurement patterns across three continents.
Germany
Stuttgart and Munich anchor European hypervisor development through clustered Tier-1 engineering centers and premium OEM headquarters. UN R155 cybersecurity mandates from the KBA accelerate certified virtualization procurement for autonomous driving type-approvals. Baden-Württemberg's automotive supplier density generates specialized integration expertise for zonal E/E architectures.
United States
NHTSA automated driving system guidance and EPA emissions compliance timelines compel OEM virtualization adoption for software-defined vehicle architectures. Silicon Valley semiconductor clusters and Detroit automotive engineering centers split demand between chip-level integration and vehicle-platform deployment. Michigan's traditional manufacturing base attracts hypervisor localization investments for North American vehicle programs.
Japan
METI software-defined vehicle roadmaps create regulatory tailwinds for certified virtualization platforms in domestic OEM supply chains. Nagoya's automotive manufacturing corridor and Tokyo's electronics clusters concentrate integration demand for Level 2+ automation systems. Toyota and Honda supplier networks drive microkernel architecture adoption for mixed-criticality separation.
India
PLI scheme incentives for automotive electronics attract hypervisor localization investments for export-oriented production. Karnataka's Bangalore tech corridor and Tamil Nadu's automotive manufacturing belt split demand between software development and hardware integration. Domestic OEM procurement is consolidating from fragmented Tier-1 sourcing toward direct platform contracting.
South Korea
Hyundai-Kia supplier networks and Samsung semiconductor capabilities create vertically integrated hypervisor deployment pathways. Seoul Capital Area engineering centers concentrate expertise for zonal gateway module development. MFDS-aligned functional safety expectations limit viable suppliers to pre-certified toolchain vendors.
Automotive Hypervisor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-compute specialization and cloud-native orchestration capabilities. The vendor base organizes around three strategic archetypes: semiconductor-integrated stack providers, safety-certified software specialists, and automotive Tier-1 system integrators. Dominant competitive moves include long-term cockpit-domain platform contracting and pre-integrated hardware-software bundling.
Among safety-certified software specialists, BlackBerry and Green Hills Software exemplify the high-integrity segment where ISO 26262 ASIL-D compliance functions as a non-negotiable barrier to entry. Within semiconductor-integrated providers, NVIDIA occupies a position representing the data-center-to-automotive architecture migration path. Continental anchors the Tier-1 integrator archetype through bundled hardware-software supply relationships with European premium OEMs.
| Leading Market Players |
|---|
| Continental |
| Renesas Electronics |
| Wind River |
| Siemens |
| Robert Bosch |
| Green Hills Software |
| NXP Semiconductors |
| NVIDIA |
| BlackBerry |
| Others |
Supply Flow & Price Mechanics
Automotive-grade silicon wafer pricing indices cascade through Tier 1 integrator margins into hypervisor licensing tiers, compressing standard-grade margins while ASIL-D certified stacks retain pricing power through formal verification scarcity.
Pricing Analysis
Volume deployment of Type-1 hypervisors for infotainment consolidation runs on per-unit royalty models with thin margins, while microkernel architectures for ADAS command project-based licensing with substantial certification premiums. Price differentiation hinges on ISO 26262 ASIL-D compliance grade and bundled toolchain qualification depth. Cost compression in standard-tier cockpit-domain contracts is intensifying because OEMs are consolidating procurement across multiple ECUs. Tier 1 suppliers represent the most price-sensitive buyers, whereas German premium OEMs direct-sourcing for software-defined architectures exhibit lowest sensitivity to unit-cost fluctuations.
Supply Chain Analysis
Automotive-grade SoC supply rests on Taiwan semiconductor foundries, South Korean memory fabricators, and German automotive engineering clusters for integration expertise. Hypervisor portability draws from ARM architecture licensing, safety-certified compiler toolchains, and pre-validated guest operating system stacks. Single-source vulnerability concentrates around automotive-qualified silicon vendors with limited second-source alternatives. Distribution runs through Tier 1 system integrators bundling hardware-software stacks for OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive hypervisor market sits in a technology-transition phase where microkernel architectures displace legacy Type-1 deployments in safety-critical domains.
For Market Incumbents: Cement long-term cockpit-domain platform contracts before zonal E/E architectures redistribute value toward edge controllers. Deepen formal verification capabilities through academic partnerships in Stuttgart and Munich engineering corridors to defend against emerging semiconductor-integrated stack providers. Prioritize QNX and comparable pre-certified toolchain investments as regulatory barriers tighten.
For New Entrants and Emerging Players: Capture white-space in India's PLI scheme electronics manufacturing zones where localization incentives attract export-oriented hypervisor development. Target zonal gateway module virtualization as the most penetrable segment, leveraging microkernel expertise scarcity against established Type-1 incumbents. Pursue cloud-native workload orchestration partnerships with vehicle-to-cloud service providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors safety-certified software specialists with existing ISO 26262 toolchains over raw technology plays. Long-term viability centers on formal verification capabilities that outpace university pipeline output. Monitor METI software-defined vehicle roadmap implementation velocity and KBA UN R155 enforcement consistency as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated cockpit-domain contracts lock OEMs into multi-year hypervisor architecture commitments. |
| Software-Defined Vehicle Investment | Direct OEM procurement displaces fragmented Tier 1 sourcing for virtualization licensing. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts hypervisor localization for export-oriented automotive electronics production. |
| Strategic Partnership | Academic collaborations in Baden-Württemberg advance microkernel isolation property verification methods. |
| Acquisition of Specialist Firm | Formal verification expertise scarcity makes mathematical proofing capabilities prime acquisition targets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, semiconductor product managers, and automotive cybersecurity officers. KBA type-approval documentation, UN ECE regulatory submissions, SEC automotive supplier disclosures, and vehicle production registration databases supplied validation layers. Bottom-up hypervisor licensing volume estimates triangulated against top-down software-defined vehicle architecture spending projections.
Segmentation granularity modeled hypervisor type, application domain, and end-user procurement authority at the country level across the analysis window. Vehicle class, propulsion architecture, and regional regulatory cluster dimensions captured automotive-specific variation. CAGRs derived from S-curve technology adoption modeling calibrated to zonal E/E architecture transition timelines. Safety certification pipeline data and SoC vendor roadmap disclosures informed penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UN R155 enforcement consistency and microkernel verification talent pipeline expansion. Forecasts reflect documented assumptions about OEM consolidation timelines and silicon vendor qualification pathways. A small set of triggers—METI roadmap implementation velocity, PLI scheme disbursement rates, and ASIL-D certification backlog duration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global UIUX Software Market
Software & Services
Tenant Billing System Market
Software & Services
Vlog Editing Software Market
Software & Services
Network Documentation Software Market
Software & Services
Social Collaboration Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
File Sharing Software Market
Software & Services
Mining Software Market
Software & Services
Parametric Design Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Case Management Software (CMS) Market