
 Global Product Lifecycle Management Software Market | 2026-2036
Global Product Lifecycle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Lifecycle Management Software Market Foresight
Aerospace and defense is pivoting toward integrated digital thread architectures, demanding tighter configuration control across distributed supplier networks. Siemens AG leverages deep CAD-to-manufacturing connectivity to dominate European industrial accounts. Dassault Systèmes SE sustains leadership in complex system modeling for aviation OEMs. PTC Inc. differentiates through IoT-augmented service lifecycle extensions, competing directly with Autodesk Inc. in mid-market mechanical design segments.
Product Lifecycle Management Software constitutes an enterprise application suite governing data continuity from concept through disposal, typically built on relational database architectures with version-controlled document vaults and workflow engines. Its primary commercial purpose centers on reducing engineering change order latency and eliminating data silos between design, procurement, and field service organizations. Cloud-based deployment now leads new installations as manufacturers prioritize remote collaboration infrastructure, while on-premises retention persists in defense and pharmaceutical segments where data sovereignty requirements dominate procurement. Quality control applications attract disproportionate investment as regulatory traceability mandates tighten across medical device and automotive supply chains.
ISO 10303 standards for STEP data exchange shape interoperability requirements, while FDA 21 CFR Part 11 in the United States and EMA Annex 11 in Europe impose validation burdens on pharmaceutical PLM deployments. China's GB standards for industrial software security and the EU AI Act's risk classification framework for automated decision systems are creating divergent compliance roadmaps. Stakeholders must monitor whether emerging cross-border data localization rules fragment cloud architecture strategies or spur federated platform investments.
Market Dynamics
Cloud-native architectures are compressing deployment cycles while ISO 10303 STEP standards force interoperability investments across aerospace supply chains. Defense contractors now mandate digital thread compliance from tier-three suppliers, restructuring procurement specifications.
Growth Catalysts
- EMA Annex 11 validation requirements:Pharmaceutical manufacturers in Europe are accelerating PLM upgrades to maintain batch traceability across contract manufacturing networks.
- Digital thread mandates:US Department of Defense contracts now require model-based systems engineering data continuity from design through sustainment.
- AI-augmented generative design:Automotive OEMs are embedding machine learning into PLM workflows to compress concept-to-prototype timelines.
Market Restraints
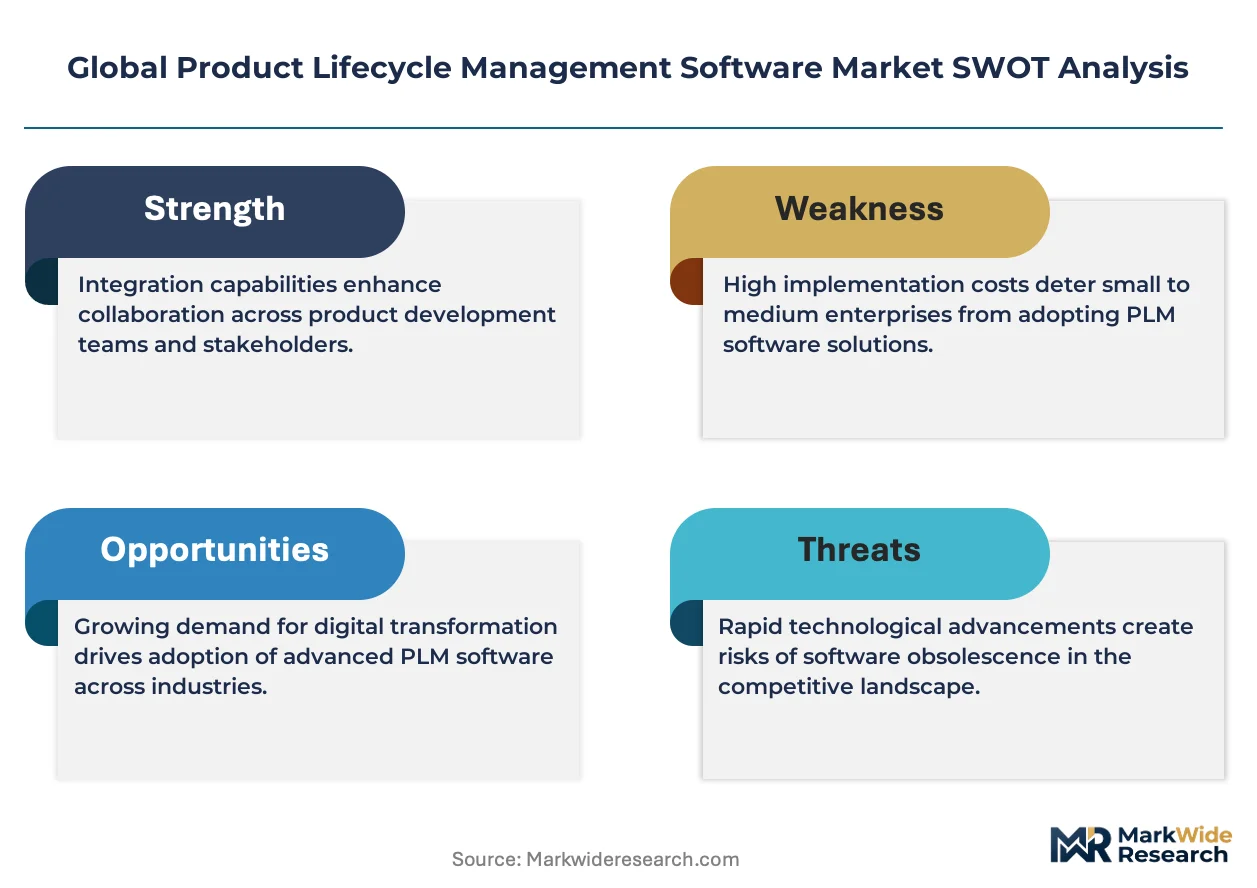
- Cloud concentration risk:Three hyperscale providers dominate PLM hosting infrastructure, creating single-point-of-failure exposure for multi-tenant deployments.
- Legacy data migration costs:Decades of CAD file versions and non-relational document vaults require specialized transformation tooling before cloud migration.
- Substitution by lightweight PDM:Mid-market mechanical design teams are adopting product data management tools with stripped-down workflow engines instead of full PLM suites.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers establishing operations under production-linked incentives require compliant PLM infrastructure for export certification.
- Sustainability data integration:EU CSRD reporting mandates are creating demand for carbon footprint tracking modules embedded within lifecycle management platforms.
- Digital twin convergence with IoT:Real-time sensor data streaming into PLM environments enables predictive maintenance service models for industrial equipment.
Industry Challenges
- Systems integration architect scarcity:Enterprises lack personnel capable of mapping ERP-MES-PLM data flows across heterogeneous vendor environments.
- FDA 21 CFR Part 11 validation timelines:Medical device software deployments require 12-18 month qualification periods before production release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Lifecycle Management Software Market |
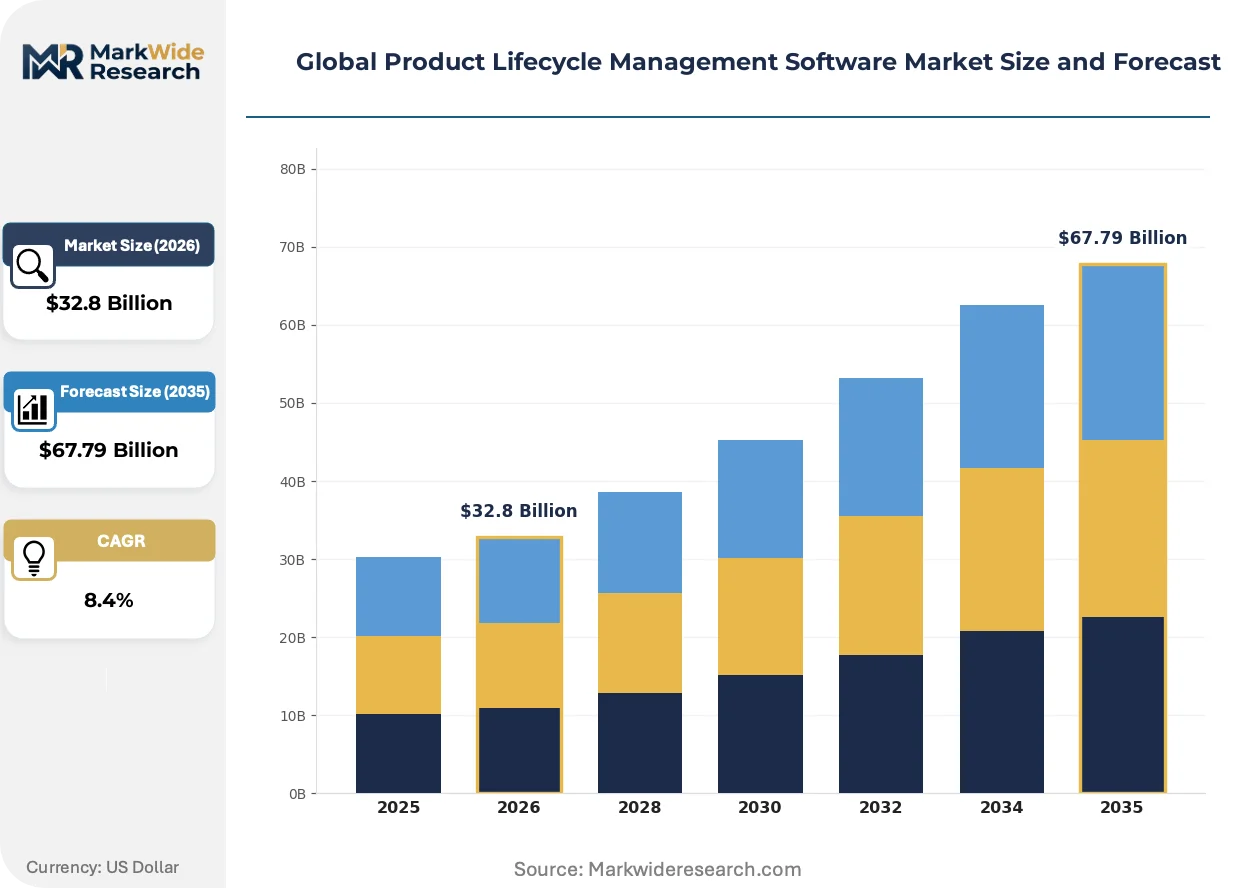
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile-Based Solution Type: Collaborative, Automotive & Transportation, Aerospace & Defense, Electronics & High-Tech, Industrial Machinery Application: Design Management, Process Management, Quality Control, Compliance Management, Supplier Collaboration End User Industry: Manufacturing, Consumer Goods, Energy & Utilities, Pharmaceuticals, Construction |
| Companies Covered | Siemens AG, Dassault Systèmes SE, PTC Inc., Autodesk Inc., SAP SE, Oracle Corporation, Aras Corporation, IBM Corporation, Infor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Lifecycle Management Software Market Shifts & Advancements
Generative AI and edge computing are restructuring how engineering data propagates through manufacturing networks. Platform vendors are racing to embed these capabilities without fragmenting core data models.
Multi-tenant SaaS PLM is consolidating vendor landscapes by absorbing point solutions for simulation data management and supplier collaboration. Aerospace primes are migrating entire supplier portals to unified cloud instances. This consolidation is compressing the addressable market for standalone configuration management tools.
The EU AI Act's risk classification framework is forcing PLM vendors to document automated decision pathways within design optimization modules. High-risk system categorization triggers conformity assessment requirements. German automotive suppliers are front-loading compliance investments ahead of enforcement deadlines.
Subscription pricing is displacing perpetual license models across mid-market mechanical design segments. Value-added resellers are pivoting toward implementation services as recurring revenue replaces upfront margins. This shift is most pronounced in Japan, where METI's digital transformation subsidies accelerate cloud procurement decisions.
Global Product Lifecycle Management Software Market Segmentation
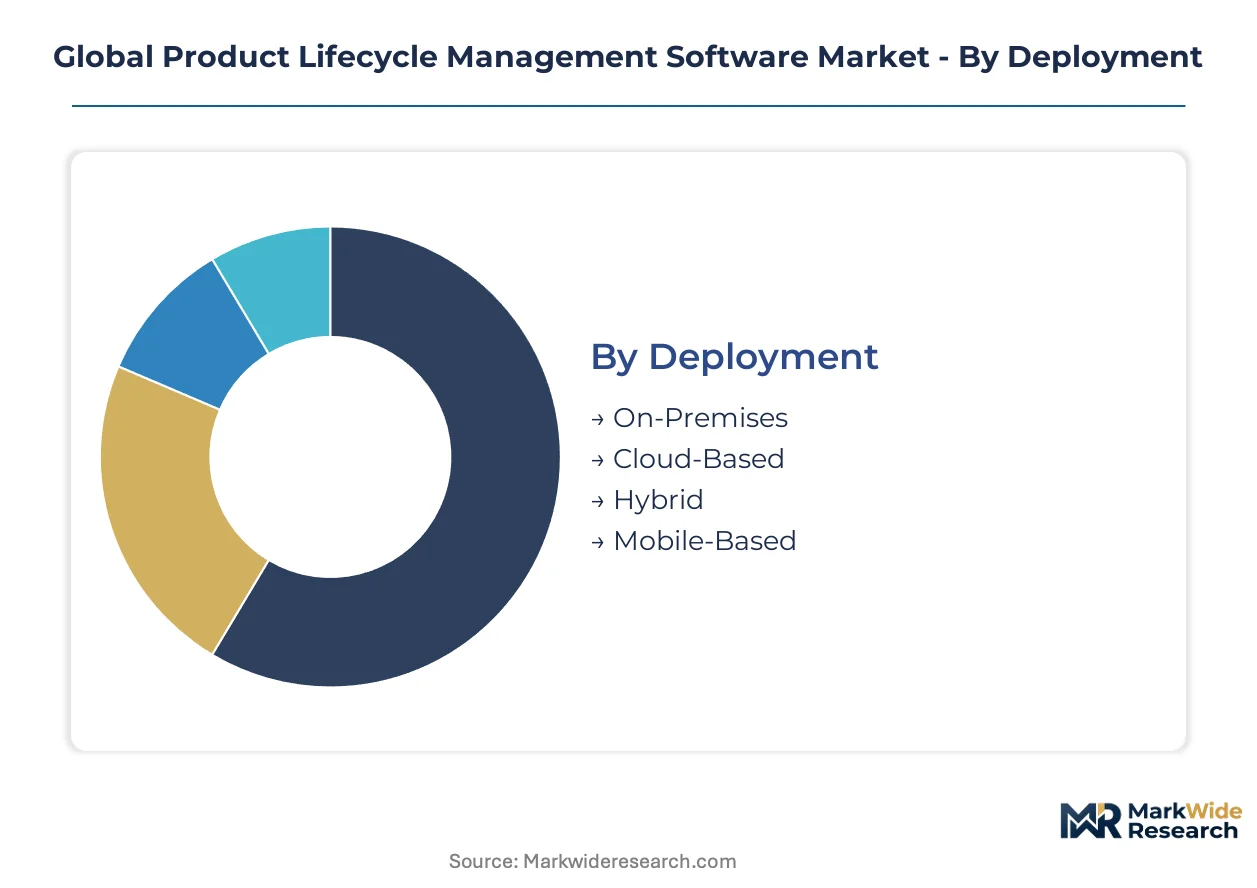
PLM software segmentation reveals how procurement criteria diverge across buyer sophistication levels and regulatory exposure. Deployment preferences split between cloud-native manufacturers seeking collaboration velocity and defense contractors bound by data sovereignty mandates. Solution specialization tracks industry-specific compliance burdens, while application modules align with organizational maturity in digital thread adoption.
Deployment:
Buyers differentiate primarily by data control requirements and IT infrastructure legacy burden.
- Cloud-Based:Multi-tenant SaaS architectures dominate new installations among discrete manufacturers prioritizing remote engineering collaboration. German automotive suppliers and Japanese electronics contract manufacturers are migrating entire supplier portals to unified cloud instances under METI digital transformation subsidies.
- On-Premises:Single-tenant deployments persist where regulatory validation cycles or classified data handling preclude third-party hosting. US defense contractors and European pharmaceutical manufacturers maintain on-premises vaults to satisfy FDA 21 CFR Part 11 and EMA Annex 11 audit trail requirements.
- Hybrid:Split configurations isolate sensitive IP in private infrastructure while exposing collaboration layers to cloud accessibility. Aerospace primes use this model to protect model-based systems engineering data while enabling tier-three supplier portal access.
- Mobile-Based:Lightweight field service applications extend PLM data to maintenance technicians via tablet-optimized interfaces. Industrial machinery OEMs deploy these for customer equipment diagnostics.
Cloud-Based leads volumes today; Hybrid is gaining share fastest among regulated industries.
Solution Type:
Specialization depth correlates with supply chain complexity and certification documentation intensity.
- Aerospace & Defense:Model-based systems engineering modules with digital thread continuity from design through sustainment. US Department of Defense contracts now mandate this data architecture from prime contractors down to tier-three suppliers.
- Automotive & Transportation:Embedded compliance with ISO 26262 functional safety and UN ECE cybersecurity regulations. German OEMs anchor European demand for these integrated toolchains.
- Electronics & High-Tech:Rapid prototyping integration with PCB design tools and semiconductor process data management. India's PLI scheme for electronics manufacturing is accelerating compliant infrastructure procurement among contract manufacturers.
- Industrial Machinery:IoT-augmented service lifecycle modules supporting predictive maintenance revenue models. Japanese and German machine builders lead adoption.
- Collaborative:Cross-enterprise workflow engines standardizing supplier data exchange without industry-specific customization. Mid-market mechanical design teams favor this for lower implementation complexity.
Aerospace & Defense commands premium pricing; Electronics & High-Tech shows steepest expansion trajectory.
Application:
Module selection reflects organizational priorities between innovation velocity and regulatory risk mitigation.
- Quality Control:Batch traceability and non-conformance tracking with automated CAPA workflows. Pharmaceutical manufacturers under EU MDR and FDA quality system regulations drive disproportionate investment here.
- Compliance Management:Validated document control with electronic signatures and audit trail generation. This module attracts mandatory procurement in medical device and pharmaceutical segments facing 12-18 month qualification timelines.
- Design Management:CAD vaulting and engineering change order routing with version-controlled BOM evolution. Discrete manufacturers across all geographies treat this as foundational PLM capability.
- Process Management:Manufacturing execution integration with work instruction distribution and as-built configuration capture. Automotive and industrial machinery sectors prioritize this for production line synchronization.
- Supplier Collaboration:Tiered portal access with controlled data visibility across distributed supply networks. Aerospace primes are consolidating standalone configuration tools into unified supplier platforms.
Quality Control anchors current spending; Supplier Collaboration is climbing the fastest as digital thread mandates deepen.
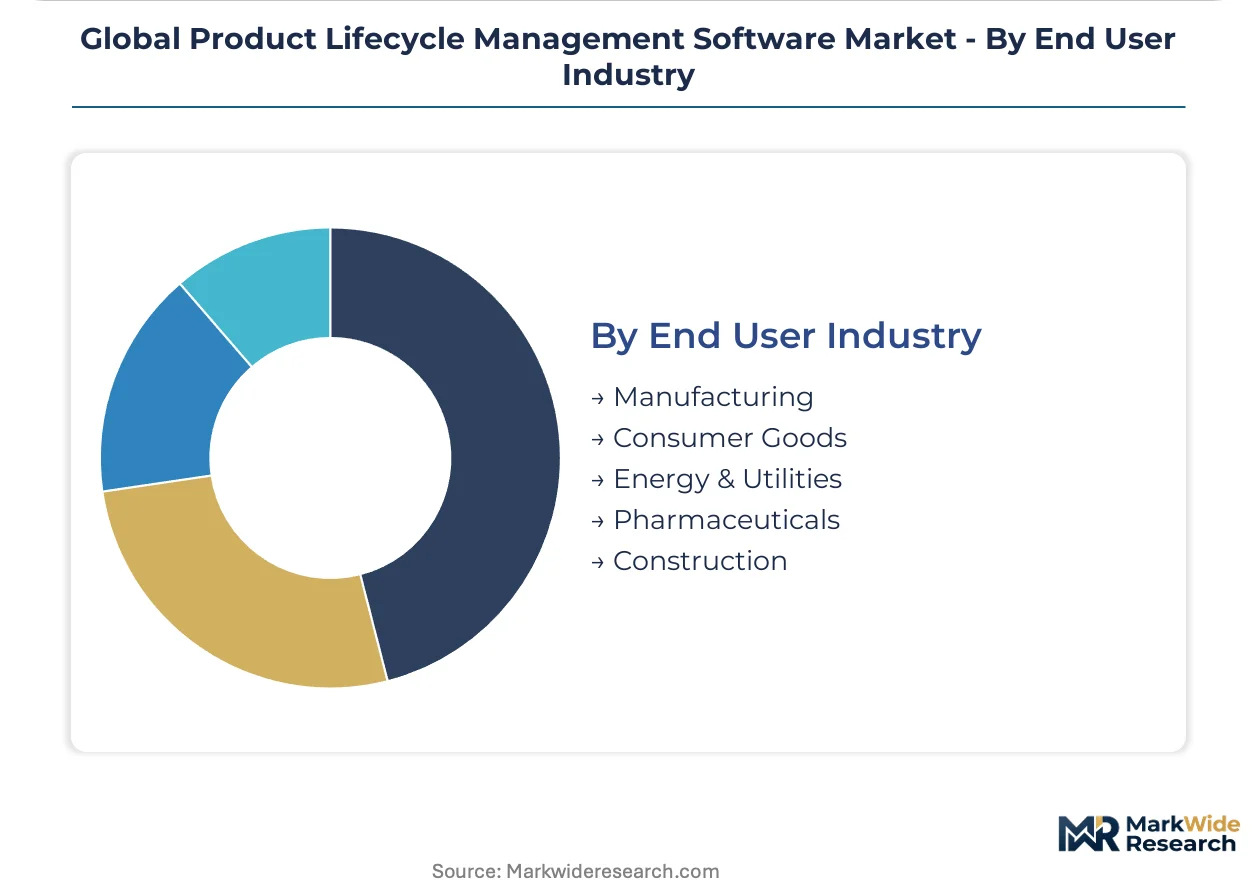
End User Industry:
Industry selection determines regulatory validation burden and integration complexity with adjacent enterprise systems.
- Pharmaceuticals:Validated PLM environments with electronic records integrity for FDA 21 CFR Part 11 and EMA Annex 11 compliance. Batch release documentation and audit trail automation dominate procurement specifications.
- Manufacturing:Broad category spanning discrete and process industries with varying degrees of digital maturity. Automotive, electronics, and industrial equipment subsegments show divergent cloud migration timelines.
- Energy & Utilities:Asset lifecycle management for capital-intensive infrastructure with decades-long operational horizons. Predictive maintenance modules and regulatory compliance for environmental permits shape purchasing.
- Consumer Goods:Fast-moving product development cycles with emphasis on packaging specification management and retailer compliance documentation. Sustainability data integration for EU CSRD reporting is emerging as a procurement criterion.
- Construction:Building information modeling integration with project delivery documentation and handover data packages. This segment lags in PLM adoption relative to manufacturing verticals.
Manufacturing dominates absolute spending; Pharmaceuticals delivers highest per-seat margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting PLM procurement toward jurisdictions with streamlined validation pathways, as pharmaceutical and aerospace contractors seek to compress compliance timelines without sacrificing audit readiness.
United States
Defense contractors in Virginia and California are accelerating digital thread investments to meet Department of Defense model-based systems engineering mandates. FDA 21 CFR Part 11 validation requirements for medical device manufacturers create extended procurement cycles in Minnesota and Massachusetts medical technology clusters. Boston's biotech corridor sustains premium PLM spending for electronic batch record integrity.
Germany
Automotive OEMs in Stuttgart and Munich anchor European demand for ISO 26262-integrated toolchains as functional safety regulations tighten. EMA Annex 11 compliance drives pharmaceutical manufacturers in Ludwigshafen and Frankfurt toward validated document control upgrades. Baden-Württemberg's industrial machinery builders are embedding IoT service modules into legacy PLM environments.
China
Electronics contract manufacturers in Shenzhen and Suzhou are procuring compliant PLM infrastructure under GB standards for industrial software security. MIIT dual carbon goals are forcing carbon footprint tracking module integration among Yangtze River Delta automotive suppliers. Shanghai's aviation cluster is adopting STEP data exchange protocols for Commercial Aircraft Corporation supplier coordination.
India
Electronics manufacturing services firms in Bengaluru and Chennai are deploying PLM systems to satisfy PLI scheme export certification requirements. CDSCO medical device regulations are pushing Hyderabad and Ahmedabad manufacturers toward quality control module investments. Maharashtra's automotive component suppliers are migrating engineering data to cloud-native platforms under accelerated digitization programs.
Japan
Machine builders in Nagoya and Osaka are consolidating supplier portals into unified cloud instances for predictive maintenance revenue models. METI digital transformation subsidies are compressing procurement decisions among Tokyo-area electronics contract manufacturers. Yokohama's industrial equipment sector is prioritizing mobile field service extensions for customer diagnostics.
Global Product Lifecycle Management Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated platforms dominating aerospace and pharmaceutical accounts while fragmented point solutions persist in mid-market mechanical design. The vendor landscape organizes into three strategic archetypes: integrated enterprise suites with deep CAD-to-manufacturing connectivity, cloud-native challengers with rapid deployment models, and industry-specific specialists with pre-validated regulatory templates. M&A activity concentrates on absorbing simulation data management capabilities, while strategic partnerships with hyperscale cloud providers are restructuring hosting economics.
Within the integrated enterprise tier, Siemens AG and Dassault Systèmes SE occupy positions defined by decades of CAD-to-manufacturing connectivity investments. PTC Inc. sits within the IoT-augmented service lifecycle segment, competing for industrial machinery accounts seeking predictive maintenance revenue models. These three companies exemplify how vendor selection tracks buyer sophistication levels and regulatory exposure intensity across aerospace, automotive, and pharmaceutical verticals.
| Leading Market Players |
|---|
| Siemens AG |
| Dassault Systèmes SE |
| PTC Inc. |
| Autodesk Inc. |
| SAP SE |
| Oracle Corporation |
| Aras Corporation |
| IBM Corporation |
| Infor Inc. |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investments by Siemens, Dassault Systèmes, and PTC anchor both supply security and pricing power across aerospace and pharmaceutical accounts. This vertical integration into hyperscale hosting insulates premium tier pricing from margin erosion while forcing mid-market vendors toward channel discounting.
Pricing Analysis
Direct-to-OEM enterprise agreements command 40-60% discounts off list pricing for multi-year digital thread deployments, while value-added reseller margins compress to 15-20% on SaaS renewals. Pricing stratifies across premium, standard, and economy tiers with ISO 26262 certification and FDA 21 CFR Part 11 validation as primary differentiation drivers. Cost compression in the mid-market mechanical design segment intensifies as lightweight PDM substitutes erode PLM suite pricing. Small electronics contract manufacturers in India exhibit highest price sensitivity; defense contractors in Virginia and California show least sensitivity due to mandate-driven procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive OEMs and US defense primes, while cloud-native deployment draws from AWS, Microsoft Azure, and Google Cloud infrastructure concentrated in the United States, Ireland, and Singapore. Relational database licensing and GPU compute capacity for AI-augmented design modules represent critical input dependencies. Single-source vulnerability in hyperscale hosting creates concentration exposure for multi-tenant SaaS PLM. Distribution runs through value-added resellers in Japan, systems integrators in Germany, and direct enterprise sales teams in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global PLM software constitutes a late-cycle quality story as aerospace and pharmaceutical buyers prioritize validated, audit-ready platforms over cost-optimized alternatives. EU AI Act risk classification and FDA validation timelines favor incumbent investments in compliance infrastructure.
For Market Incumbents: Anticipate substitution pressure from cloud-native challengers by deepening CAD-to-manufacturing connectivity moats and pre-validating regulatory templates for EMA Annex 11 and FDA 21 CFR Part 11 deployments. Channel control through certified implementation partner networks in Germany and Japan represents a critical defensive lever against margin compression. For New Entrants and Emerging Players: Generative AI-augmented design optimization modules offer a technology-first wedge into mid-market mechanical design teams currently underserved by full PLM suites. India's electronics manufacturing services sector under PLI scheme certification requirements presents the most penetrable geography, with SaaS-native deployment and rapid onboarding as the preferred go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for simulation data management specialists because aerospace primes are consolidating standalone configuration tools into unified supplier platforms, creating exit demand for point-solution vendors. Long-term viability favors platforms with validated pharmaceutical templates and defense clearance pathways. Watch CDSCO medical device regulation enforcement in India as an inflection indicator for quality control module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD vaulting with IoT sensor streams for predictive maintenance revenue models at German machinery OEMs. |
| Acquisition of Specialist Firm | Absorbs simulation data management capabilities that aerospace primes are consolidating into digital thread architectures. |
| Strategic Partnership | Hyperscale cloud alliances with AWS or Azure restructure hosting economics for multi-tenant SaaS deployments. |
| Product Launch | Carbon footprint tracking modules address EU CSRD reporting mandates for automotive and consumer goods manufacturers. |
| Geographic Expansion | Validated PLM infrastructure targets India's PLI scheme electronics manufacturers seeking export certification compliance. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation from SEC filings, hyperscaler capex disclosures, and ISO standards documentation. Bottom-up segment sizing triangulates against top-down market reconstruction.
Rate-of-change decomposition separates volume growth from value expansion across deployment model, organization size, vertical industry, and integration complexity dimensions throughout the forecast period. CAGRs derive from modeled adoption curves for cloud-native versus on-premises installations, with AI-augmented workflow penetration and regulatory validation timeline compression as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border data localization rule fragmentation and federated platform investment cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Linux Operating System Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Programming Language Market
Software & Services
Avionics Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Global Survey Software Market
Software & Services
Global Workforce Management Software Market
Software & Services
VFX Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Content Moderation Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Live Software Market
Software & Services
Photobooth Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Global Press Release Distribution Software Market