
 Workstation Software Market | 2026-2036
Workstation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Workstation Software Market Outlook
The workstation software landscape is recalibrating around a widening gap between premium engineering suites and commoditized design tools. Autodesk dominates the architectural and media segments through extensive channel control and subscription stickiness. Dassault Systèmes anchors the high-end manufacturing tier with deep integration into aerospace supply chains. Bentley Systems specializes in infrastructure lifecycle management, leveraging its position in transportation and utility verticals.
Workstation software encompasses specialized applications that execute computationally intensive tasks for design, engineering, and digital content creation on high-performance hardware configurations, typically requiring multi-core processors, professional graphics cards, and substantial memory allocations to handle complex 3D modeling, finite element analysis, or real-time rendering workflows. CAD Software occupies the largest revenue pool as legacy installed bases in automotive and industrial machinery resist platform switching, while Cloud-Based deployment represents the fastest structural expansion as engineering firms renegotiate capital expenditure models toward operational spending frameworks.
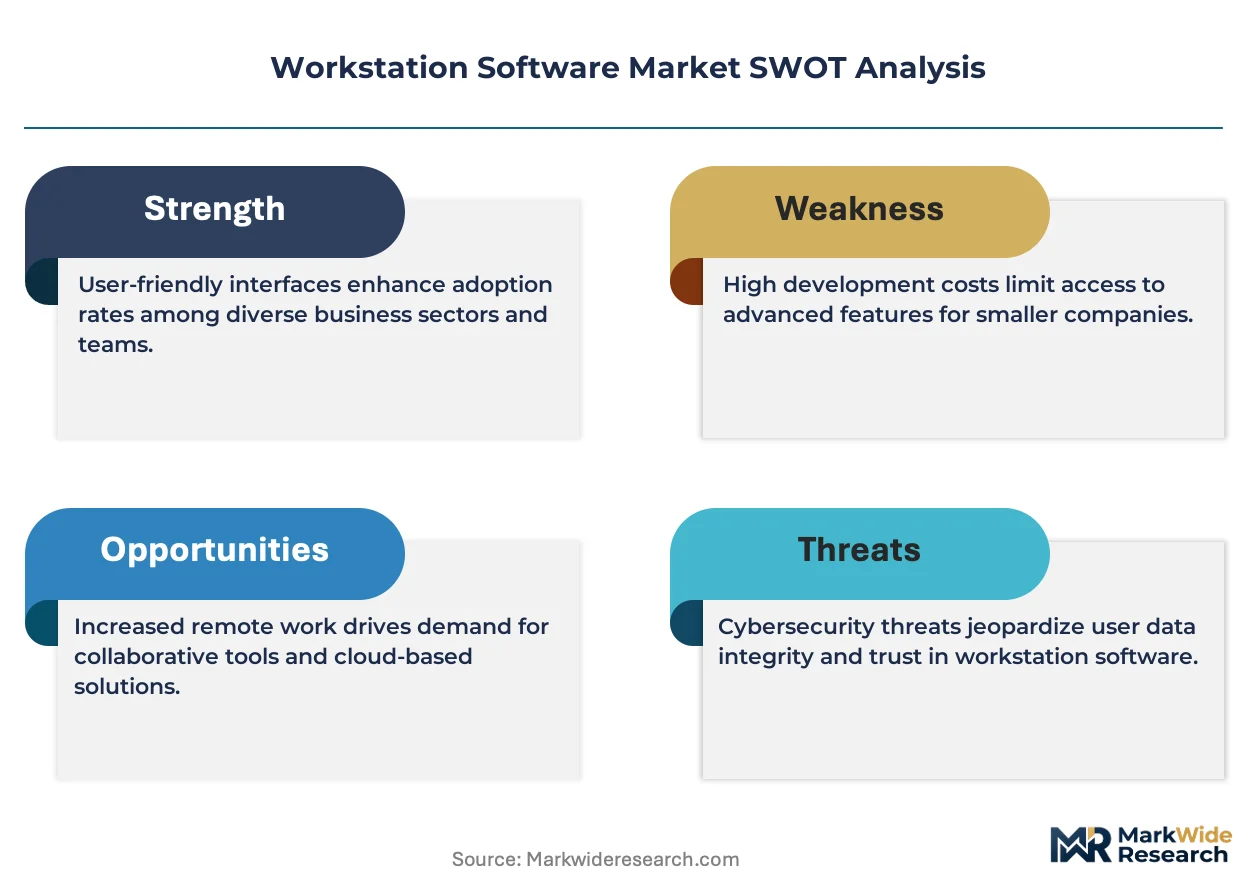
ISO standards for product data exchange, FDA quality system regulations for medical device design traceability, and EPA emissions compliance documentation requirements collectively shape validation protocols that workstation software must support. The EU AI Act introduces emerging obligations for automated design optimization tools, pressuring vendors to embed auditability features. Stakeholders must weigh the pace of cloud migration against persistent latency and intellectual property concerns in regulated industries.
Market Dynamics
Workstation software markets are compressing around a fundamental restructuring of how engineering compute is provisioned, as hybrid cloud architectures displace perpetual license models and force vendors to rebuild revenue recognition around consumption metering rather than upfront seat sales.
Growth Catalysts
- EU AI Act compliance mandates:Automated design optimization tools now require embedded auditability features, compelling manufacturers to upgrade legacy CAD environments to certified platforms that document algorithmic decision trails.
- Automotive electrification engineering intensity:Battery pack thermal simulation and electric drivetrain packaging workflows demand GPU-accelerated solver licenses that scale with vehicle program complexity.
- Cloud infrastructure maturation:Microsoft Azure and AWS GovCloud instances now host ITAR-compliant simulation environments, clearing regulatory barriers that previously trapped defense contractors in on-premises deployments.
Market Restraints
- Professional GPU supply concentration:NVIDIA's dominance in datacenter AI training has diverted foundry capacity away from Quadro and RTX A-series workstation cards, extending lead times for visualization-heavy engineering teams.
- Perpetual license stranded asset risk:Enterprises holding depreciated Autodesk and Dassault Systèmes perpetual seats face escalating maintenance penalties that compress migration timelines to subscription models.
- Latency constraints on real-time collaboration:Sub-20ms round-trip requirements for synchronous multi-user CAD sessions limit cloud adoption for geographically distributed teams across India and Southeast Asia.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Contract manufacturers establishing PCB and semiconductor packaging facilities require EDA and mechanical design tool licenses at scale previously concentrated in China and Taiwan.
- Digital twin convergence with IoT sensor streams:Bentley Systems and infrastructure software vendors can embed operational data from SCADA systems into lifecycle models, creating recurring revenue from asset monitoring rather than design-only licenses.
- Outcome-based performance engineering contracts:Aerospace suppliers are piloting agreements where software vendors share risk on physical test reduction, aligning license fees to measurable prototype elimination.
Industry Challenges
- GPU programming talent scarcity:CUDA and OptiX optimization expertise required for real-time ray tracing implementations commands premium compensation that software vendors struggle to match against hyperscaler hiring.
- Multi-vendor interoperability certification:ISO 10303 STEP AP242 compliance testing across Siemens NX, PTC Creo, and CATIA environments delays release cycles and fragments development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workstation Software Market |
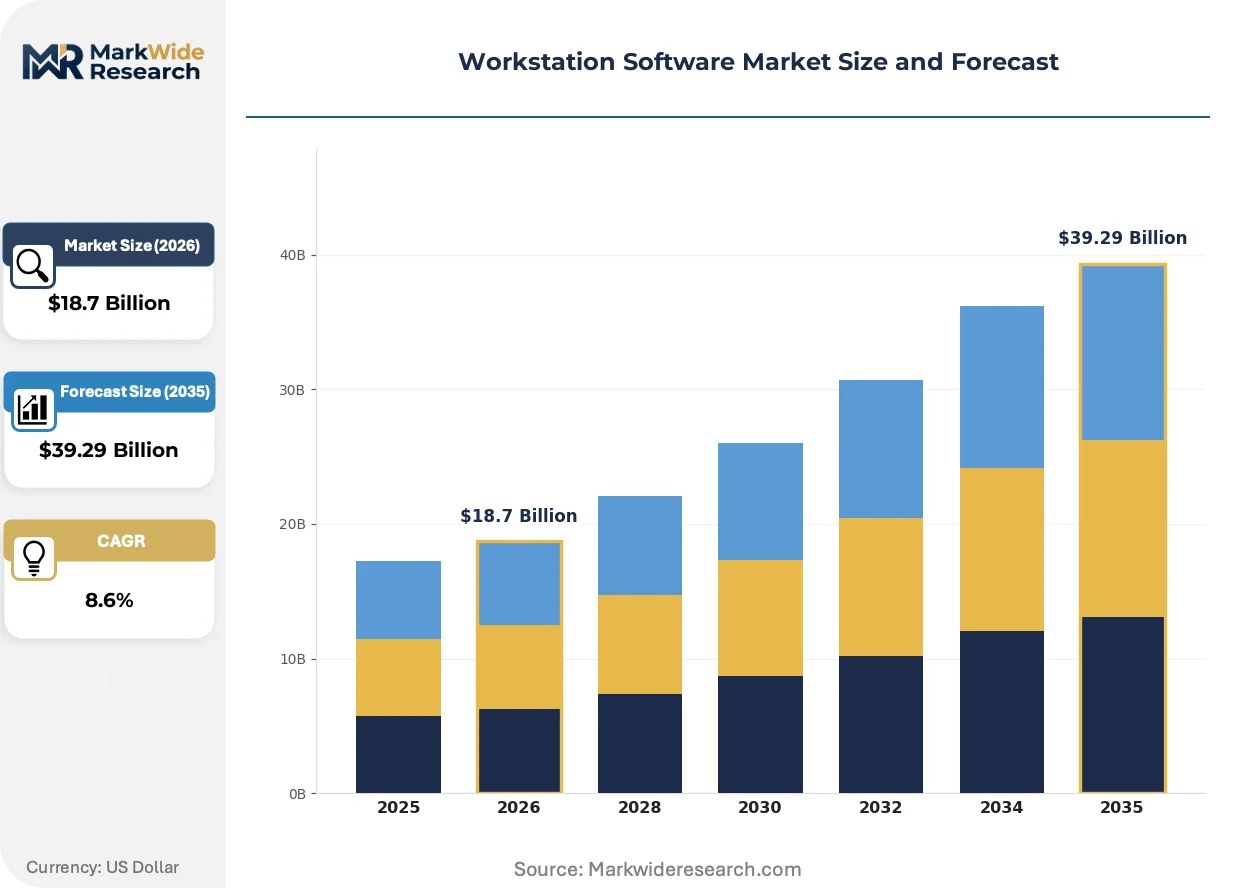
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software, CAM Software, Simulation Software, Visualization Software Deployment: On-Premise, Cloud-Based, Hybrid Solutions, SaaS End User: Engineering Firms, Architectural Firms, Manufacturing, Education Feature: 3D Modeling, Real-Time Collaboration, Data Analytics, User Customization |
| Companies Covered | PTC, Bentley Systems, Autodesk, Figma, Adobe, Dassault Systèmes, Trimble, Procore Technologies, Siemens Digital Industries Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workstation Software Market Strategic Shifts
Computational workflows are fragmenting across edge, on-premises, and cloud substrates as engineering organizations reject monolithic platform consolidation in favor of modular toolchains that swap specialized solvers by project phase.
GPU-native real-time rendering is decentralizing visualization pipelines that previously required centralized render farms. Automotive studios in Germany and media production houses in California now deploy Unreal Engine and Omniverse on local RTX workstations, collapsing review cycles from days to hours. This compression is eliminating the procurement justification for dedicated visualization clusters and redistributing compute budgets toward individual engineer productivity.
REACH substance restriction amendments are forcing materials database updates across simulation suites. Vendors must now embed restricted substance flags directly into polymer and alloy property libraries used by finite element analysis solvers, with automotive OEMs in Stuttgart and Wolfsburg demanding automated compliance checking before any design release. Software providers are responding with subscription-tiered certification modules that gate advanced materials functionality.
Engineering procurement teams are unbundling maintenance and support from core license agreements. German automotive suppliers now negotiate separate statements of work for implementation consulting, compressing upfront contract values while elongating vendor cash conversion cycles. This behavioral shift is most pronounced in industrial machinery verticals where capital expenditure scrutiny has intensified under European Central Bank rate policies.
Workstation Software Market Segmentation
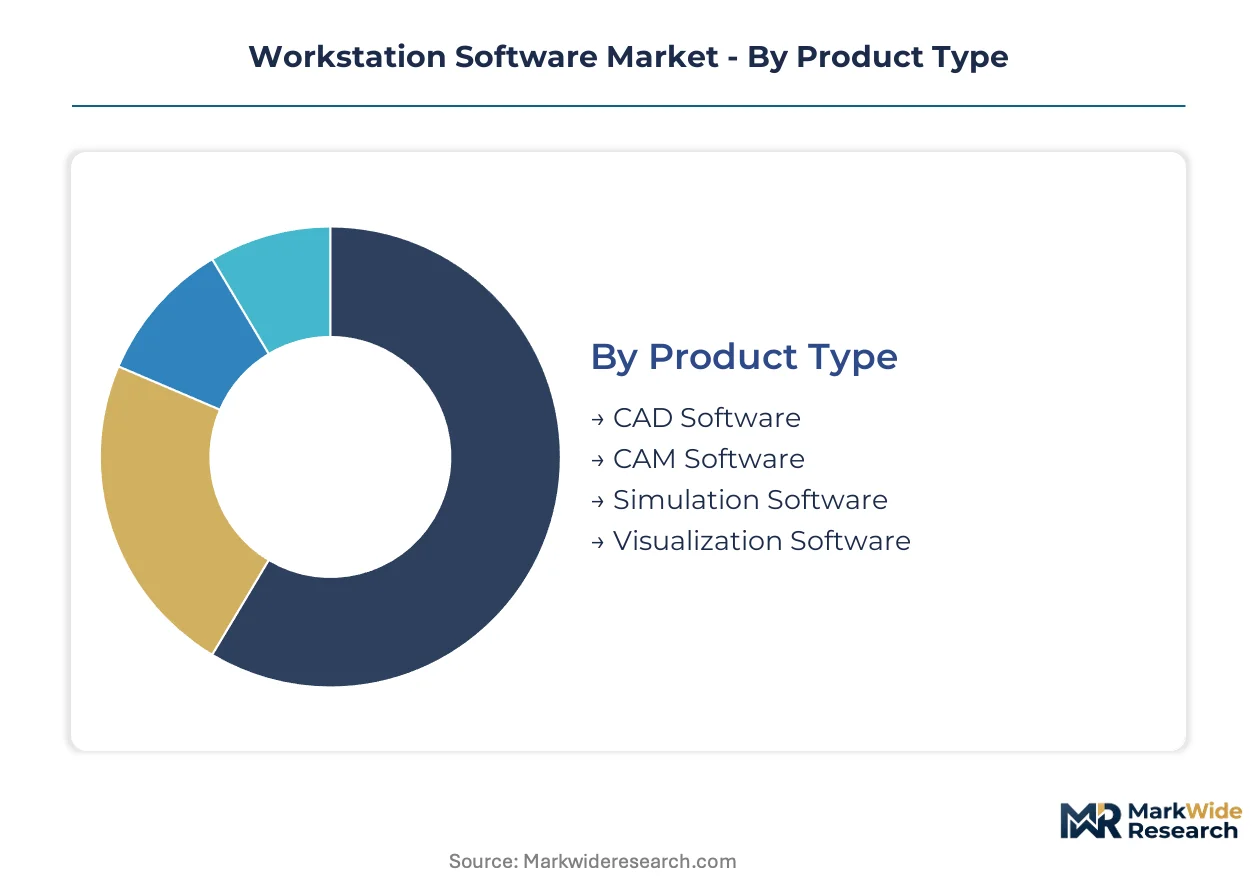
Workstation software purchasing patterns fragment sharply across integration depth, with standalone engineering suites commanding premium pricing while embedded modules penetrate through OEM hardware bundles. Understanding these structural divides reveals how vendors allocate R&D between flagship platforms and lightweight implementations.
Product Type:
CAD Software anchors most enterprise deployments as the foundational design environment, while Visualization Software increasingly embeds into hardware-accelerated review workflows rather than operating as discrete purchases.
- CAD Software:Core geometric modeling engines with parametric constraint solvers and assembly management capabilities. Demand concentrates among automotive OEMs in Stuttgart and Wolfsburg where legacy CATIA and NX installations resist platform migration due to embedded design history dependencies.
- Simulation Software:Finite element analysis and computational fluid dynamics solvers requiring GPU acceleration for mesh convergence. Battery pack thermal modeling for electric vehicle programs in Michigan and Bavaria drives license expansion as physical prototyping cycles compress.
- CAM Software:Toolpath generation and post-processor configurations linking design geometry to CNC machine control. Machine shops in Japan's Aichi prefecture and Germany's Baden-Württemberg region standardize on integrated CAD/CAM bundles.
- Visualization Software:Real-time rendering and virtual reality presentation tools. Media production houses in California deploy Unreal Engine and Omniverse on local RTX workstations, collapsing review cycles from days to hours.
CAD Software leads volumes today; Visualization Software is gaining share fastest.
Deployment:
Cost tier stratification separates capital-intensive perpetual licenses from operational expenditure models, with hybrid architectures capturing firms navigating regulatory constraints on cloud data residency.
- On-Premise:Perpetual license models with annual maintenance contracts executing on customer-managed hardware. Defense contractors in the United States remain trapped in on-premises deployments due to ITAR compliance requirements until Azure and AWS GovCloud instances cleared regulatory barriers.
- Cloud-Based:Browser-accessible engineering environments with consumption metering replacing upfront seat sales. Engineering firms in India and Southeast Asia face latency constraints limiting synchronous multi-user CAD sessions below 20ms round-trip thresholds.
- Hybrid Solutions:Split architectures reserving sensitive IP on local workstations while bursting compute-intensive solvers to cloud infrastructure. German automotive suppliers negotiate separate statements of work for implementation consulting, compressing upfront contract values.
- SaaS:Fully managed subscription tiers with automatic feature updates and collaborative workspace provisioning. Bentley Systems and infrastructure software vendors embed operational data from SCADA systems into lifecycle models.
On-Premise retains the largest installed base; Cloud-Based deployment shows the steepest expansion trajectory.
End User:
Application intensity varies dramatically, with manufacturing verticals demanding solver-grade performance while education markets prioritize accessibility over computational throughput.
- Manufacturing:Industrial machinery and electronics producers requiring multi-physics simulation and tolerance analysis. Contract manufacturers establishing PCB and semiconductor packaging facilities under India's PLI scheme require EDA and mechanical design tool licenses at scale.
- Engineering Firms:Consulting practices delivering design and analysis services across client-mandated platforms. ISO 10303 STEP AP242 compliance testing across Siemens NX, PTC Creo, and CATIA environments fragments development resources and delays release cycles.
- Architectural Firms:Building information modeling and structural documentation for commercial construction. Autodesk dominates this segment through extensive channel control and subscription stickiness.
- Education:University laboratories and technical training programs operating on discounted academic licenses. CUDA and OptiX optimization expertise required for real-time ray tracing implementations commands premium compensation that software vendors struggle to match.
Manufacturing generates the highest revenue per seat; Engineering Firms represent the most price-sensitive procurement behavior.
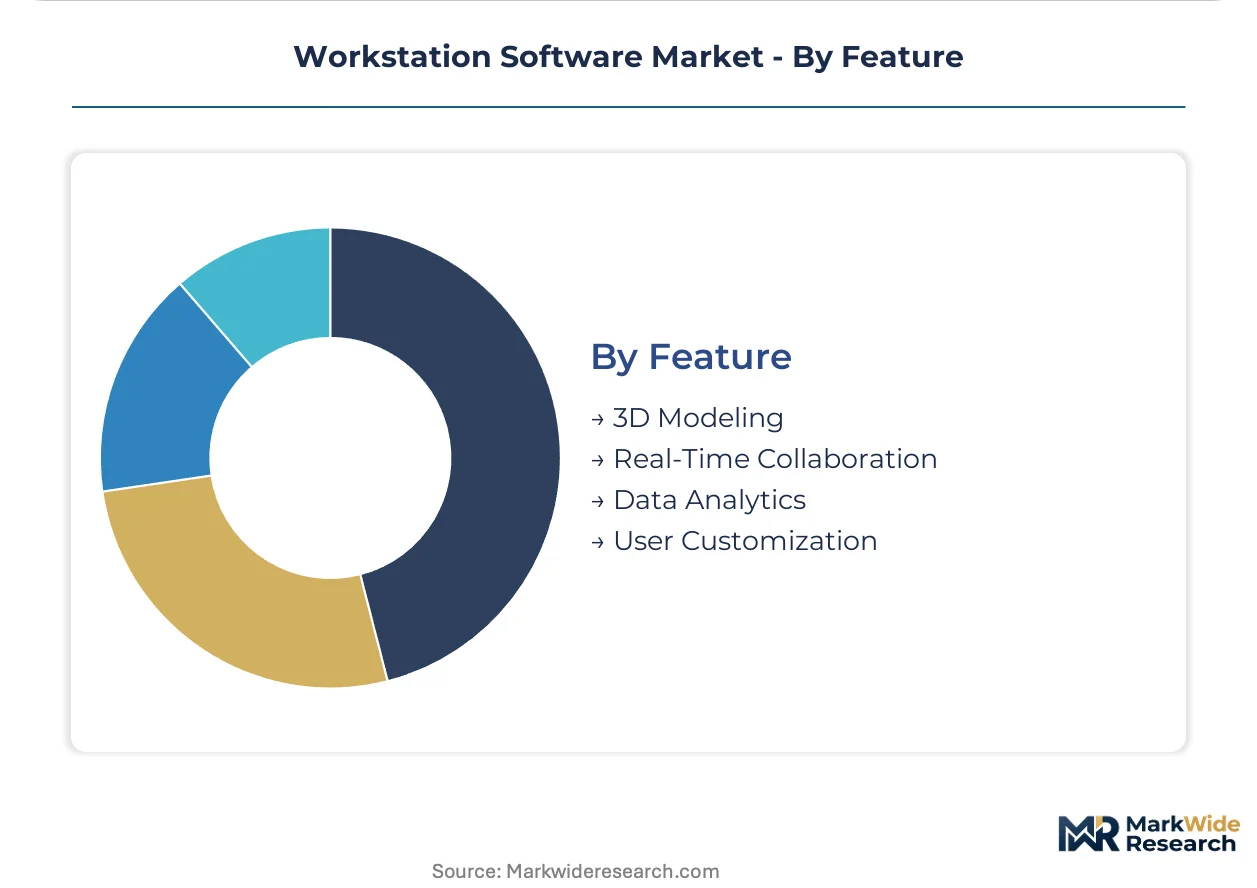
Feature:
Customer type differentiation separates enterprise buyers seeking auditability compliance from individual practitioners prioritizing workflow customization.
- 3D Modeling:Solid and surface geometry creation with direct editing and history-based parametrics. REACH substance restriction amendments force materials database updates across simulation suites, with restricted substance flags embedding into polymer and alloy property libraries.
- Real-Time Collaboration:Synchronous multi-user editing with conflict resolution and version branching. The EU AI Act introduces emerging obligations for automated design optimization tools, pressuring vendors to embed auditability features for algorithmic decision trails.
- Data Analytics:Design performance metrics, simulation result aggregation, and predictive maintenance integration. Aerospace suppliers pilot outcome-based performance engineering contracts where software vendors share risk on physical test reduction.
- User Customization:API access, scripting environments, and interface personalization for specialist workflows. German automotive suppliers now negotiate maintenance and support unbundled from core license agreements.
3D Modeling remains the baseline purchase criterion; Real-Time Collaboration is climbing the fastest as distributed engineering teams proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering software talent clusters in Stuttgart, Munich, and Wolfsburg anchor European demand, while aerospace and defense contractors in the United States sustain perpetual license volumes. Cloud infrastructure maturation is redistributing procurement gravity toward India and Southeast Asia as latency barriers erode.
United States
Aerospace manufacturers in Seattle and defense contractors in Southern California drive enterprise licensing for ITAR-compliant simulation environments. The FAA and NHTSA shape validation protocols for digital design documentation. Greater Boston hosts biotech firms demanding FDA 21 CFR Part 11 traceability in CAD workflows.
Germany
Automotive OEMs in Stuttgart and Wolfsburg resist platform migration due to embedded CATIA design history dependencies. REACH substance restriction amendments force materials database updates across simulation suites. Bavarian machine builders standardize on integrated CAD/CAM bundles for toolpath generation.
India
The PLI scheme for electronics manufacturing is pulling contract manufacturers into PCB and semiconductor packaging facilities requiring EDA licenses. TRAI regulations on data localization influence cloud deployment decisions. Engineering services clusters in Bangalore and Hyderabad face latency constraints on synchronous multi-user CAD sessions.
Japan
Machine shops in Aichi prefecture anchor demand for CAM software linking design geometry to CNC control. METI industrial policy supports digital twin adoption in precision manufacturing. Kanto region automotive suppliers pilot outcome-based performance engineering contracts with software vendors.
United Kingdom
London architectural practices sustain Autodesk subscription volumes through building information modeling mandates. The UK Building Safety Regulator imposes digital documentation standards on construction workflows. Cambridge engineering consultancies navigate ISO 10303 STEP AP242 compliance testing across multi-vendor environments.
Workstation Software Market Competitive Environment
Top-tier vendors anchor high-end manufacturing and infrastructure tiers, while mid-market specialists compete on vertical customization and API accessibility. The structure concentrates around three strategic archetypes: diversified engineering platform providers, domain-specific lifecycle managers, and cloud-native collaboration tools. Competitive moves center on unbundling maintenance from core licenses and embedding consumption metering into hybrid deployment architectures.
Within the diversified engineering platform tier, Dassault Systèmes and Siemens Digital Industries Software occupy positions defined by deep manufacturing integration and multi-physics simulation breadth. Bentley Systems represents the infrastructure lifecycle management archetype, while Autodesk exemplifies subscription stickiness through channel control in architectural and media segments.
| Leading Market Players |
|---|
| PTC |
| Bentley Systems |
| Autodesk |
| Figma |
| Adobe |
| Dassault Systèmes |
| Trimble |
| Procore Technologies |
| Siemens Digital Industries Software |
| Others |
Value Chain & Pricing Dynamics
German automotive suppliers unbundling maintenance from core license agreements are compressing upfront contract values and elongating vendor cash conversion cycles, forcing workstation software providers to restructure revenue recognition around consumption metering rather than perpetual seat sales.
Pricing Analysis
The bundled-versus-unbundled service split separates enterprise procurement into tiered subscription models and à-la-carte implementation consulting. Three-tier pricing structure across premium, standard, and economy levels gates advanced materials functionality and auditability compliance. Cost compression in the mid-market tier is intensifying because engineering procurement teams now negotiate separate statements of work for support services. Education and small engineering firms exhibit the highest price sensitivity, while aerospace and automotive OEMs absorb premium tiers for ITAR-compliant and GPU-accelerated solver licenses.
Supply Chain Analysis
CUDA and OptiX optimization expertise scarcity in Bangalore and Hyderabad commands premium compensation that software vendors struggle to match against hyperscaler hiring, constraining development velocity for GPU-native rendering features. The supply chain draws from the United States for hyperscaler cloud infrastructure, Germany for automotive engineering talent clusters, and India for electronics manufacturing services under the PLI scheme. Single-source vulnerability concentrates in NVIDIA's datacenter GPU allocation, which diverts foundry capacity from workstation-class RTX A-series cards. Distribution runs through direct enterprise sales teams for large accounts and value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in workstation software hinges on the shift from perpetual license depreciation to recurring subscription revenue, amplified by consumption-metered cloud deployment reducing customer acquisition costs.
For Market Incumbents: Deepen vertical integration into GPU-optimized solver development to reduce dependency on scarce CUDA talent pools. Anchor high-retention customer segments through embedded auditability features mandated by the EU AI Act. Defend against cloud-native challengers by accelerating hybrid architecture certification for ITAR and FDA-regulated environments. For New Entrants and Emerging Players: Launch via API-first integration marketplaces targeting mid-sized engineering firms burdened by multi-vendor interoperability testing delays. Penetrate India's contract manufacturing expansion under the PLI scheme with lightweight SaaS tiers for EDA and mechanical design workflows. Emphasize real-time collaboration features that address sub-20ms latency constraints plaguing distributed teams across Southeast Asia. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized simulation vendors holding GPU-native IP and established aerospace supply chain relationships. Long-term viability favors platforms demonstrating successful unbundling of maintenance revenue with minimal churn escalation. Watch for inflection signals in outcome-based performance engineering contract adoption, where software vendors share physical test reduction risk with aerospace suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD, simulation, and lifecycle data across Dassault Systèmes and Siemens environments. |
| Geographic Expansion | Captures India's PLI-driven electronics manufacturing demand for EDA and packaging design tools. |
| Strategic Partnership | Aligns Bentley Systems with SCADA vendors for digital twin recurring revenue from asset monitoring. |
| Product Launch | Deploys GPU-native real-time rendering on local RTX workstations, eliminating centralized render farms. |
| Acquisition of Specialist Firm | Consolidates CUDA optimization talent pools against hyperscaler hiring competition. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and EDA industry association reports. Bottom-up license volume estimates triangulated against top-down IT spending surveys across manufacturing and engineering services verticals.
Segment-weighting distributed value across deployment models, organization size tiers, vertical applications, and regional adoption patterns. CAGRs derived from historical trajectory analysis adjusted for structural shifts in cloud migration and regulatory compliance mandates. Industry-specific inputs included GPU supply allocation forecasts and EU AI Act implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged semiconductor supply constraints or accelerated hyperscaler entry into engineering software. Material deviation in NVIDIA foundry allocation or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Automation Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
North America Automotive Software Market
Software & Services
Global Saas Backup Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
App Development Software Market
Software & Services
Global Online Community Management Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market