
 Construction Equipment Fleet Management Software Market | 2026-2036
Construction Equipment Fleet Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Fleet Management Software Market Insights
The OEM-direct software channel is reconfiguring as construction equipment manufacturers embed fleet management tools into original machine sales. Caterpillar leverages its dealer network to bundle subscription-based analytics with new equipment deliveries. Trimble anchors its position through precision agriculture and construction crossover technology. Samsara competes by offering cloud-native platforms that appeal to mid-sized rental fleets seeking rapid deployment without legacy infrastructure.
Construction Equipment Fleet Management Software encompasses integrated digital platforms that collect machine telematics, geolocation, fuel consumption, and operator behavior data through onboard sensors and cellular or satellite transmission modules. These systems process information through centralized dashboards to enable real-time asset visibility, automated maintenance triggers, and compliance documentation for dispersed heavy equipment fleets. Cloud-based deployment leads adoption due to lower capital requirements and remote accessibility for multi-site contractors, while predictive maintenance within solution offerings commands premium pricing because it directly reduces unplanned downtime costs. Equipment rental companies represent the fastest-growing end user category as they seek to differentiate through guaranteed uptime and transparent utilization reporting.
FAA regulations governing drone-based site surveying intersect with EPA emissions tracking requirements to expand the data capture scope of integrated fleet platforms. OSHA workplace safety standards further compel documentation of operator certification and equipment inspection intervals within these systems. Stakeholders must evaluate whether to consolidate around OEM-embedded solutions or maintain interoperability with independent software providers as regulatory data requirements proliferate across jurisdictions.
Market Dynamics
Telematics mandates and EPA emissions enforcement are compressing adoption timelines for construction equipment fleet management software, forcing contractors to integrate real-time monitoring systems ahead of planned capital cycles.
Growth Catalysts
- EPA Tier 4 Final Standards:Diesel engine emissions rules in the United States compel fleet operators to deploy automated compliance documentation and remote diagnostics to avoid penalties.
- Equipment Rental Expansion:Rental companies seeking guaranteed uptime guarantees are embedding fleet management subscriptions into customer service agreements.
- 5G Network Deployment:Low-latency cellular infrastructure enables real-time video streaming from cab-mounted cameras for remote operator coaching and incident reconstruction.
Market Restraints
- Semiconductor Supply Concentration:Telematics control unit production depends on Taiwan-based foundry capacity, exposing hardware procurement to geopolitical disruption.
- Legacy Fleet Inertia:Contractors operating equipment beyond 15-year depreciation cycles face prohibitive retrofit costs for sensor installation and connectivity modules.
- Data Sovereignty Fragmentation:Cross-border equipment movement triggers conflicting storage requirements under GDPR in Europe and state-level privacy laws in the United States.
Strategic Opportunities
- India Infrastructure Buildout:National highway and metro rail projects create first-mover advantage for cloud-native platforms targeting emerging contractor digitization.
- OSHA Silica Dust Rules:Workplace safety mandates drive integration between fleet management systems and environmental monitoring sensors on demolition equipment.
- Drone-Fleet Convergence:FAA Part 107 compliance tools for unmanned aerial surveying are merging with heavy equipment telematics into unified site management dashboards.
Industry Challenges
- Telematics Technician Shortage:Installation and troubleshooting of cellular/satellite transmission modules requires specialized field service skills that vocational programs have not scaled to meet.
- Interoperability Protocol Gaps:OEM-proprietary data formats prevent seamless aggregation of mixed-fleet information into contractor-preferred third-party analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Fleet Management Software Market |
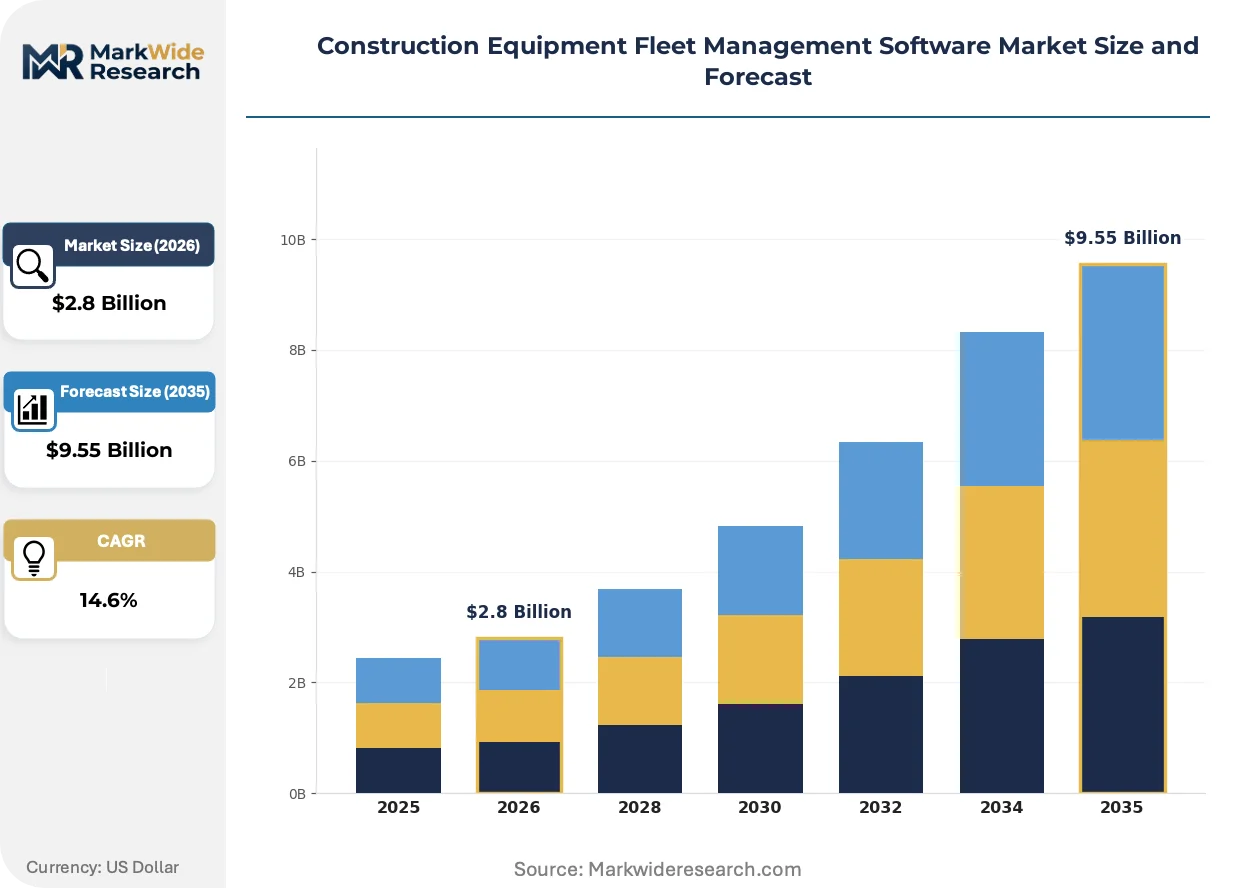
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Application: Asset Tracking, Maintenance Scheduling, Fuel Management, Operator Management, Compliance Monitoring End User: Contractors, Equipment Rental Companies, Property Managers, Infrastructure Developers Solution Offering: Real-Time Analytics, Predictive Maintenance, Mobile Integration, IoT Connectivity, Reporting Tools |
| Companies Covered | Caterpillar, Volvo Construction Equipment, Hitachi Construction Machinery, John Deere, Komatsu, Trimble, Samsara, Geotab, Teletrac Navman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Fleet Management Software Market Trends and Innovations
Edge computing architectures and AI-powered predictive models are redefining how construction fleets process operational data, shifting analytical workloads from distant cloud servers to machine-mounted processors.
Machine learning for predictive maintenance is migrating from centralized cloud training to onboard edge inference, enabling immediate fault detection without cellular connectivity gaps. Mid-sized earthmoving contractors in the United States are piloting these systems on excavator hydraulic circuits. This compression of decision latency is eliminating the 15-30 minute alert delays that previously allowed catastrophic component failures to progress.
OSHA's updated crane operator certification requirements are forcing integration between fleet management platforms and personnel qualification databases. Contractors must now demonstrate real-time verification of certified operators before equipment ignition authorization. Heavy civil construction segments in California and Texas are experiencing the steepest compliance workflow redesigns.
Rental fleet procurement patterns are pivoting from perpetual software licenses to consumption-based telemetry subscriptions tied to actual equipment utilization hours. Independent rental companies in the southeastern United States are abandoning upfront capital commitments for monthly per-asset fees. This unbundling of software from hardware acquisition is accelerating vendor switching and compressing contract renewal negotiations.
Construction Equipment Fleet Management Software Market Segmentation
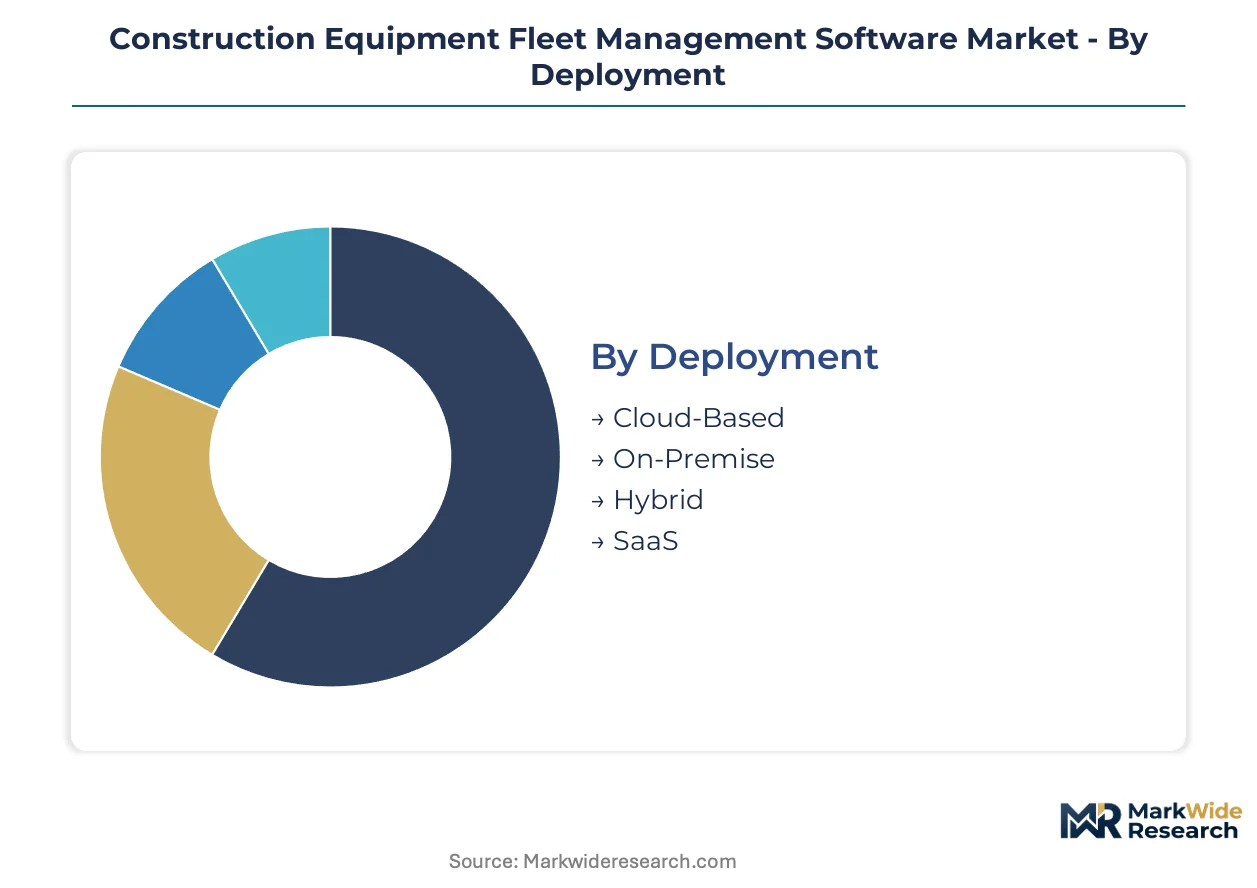
Construction equipment fleet management software segments around deployment architecture, operational application, end-user procurement patterns, and solution sophistication tiers. Vendors configure pricing and service models distinctly across these dimensions, with cloud-native platforms commanding premium positioning against legacy on-premise installations.
Deployment:
Mature on-premise systems coexist with emerging cloud-native architectures as contractors weigh data control against accessibility requirements.
- Cloud-Based:Multi-tenant architectures host telemetry processing on remote servers, eliminating capital expenditure for server infrastructure. Demand concentrates among mid-sized earthmoving contractors in Texas and California seeking remote site accessibility without dedicated IT staffing.
- On-Premise:Localized server installations retain raw telematics data within contractor firewall perimeters, satisfying defense and critical infrastructure security protocols. Large civil contractors operating near sensitive government facilities in Virginia and Maryland specify these deployments to satisfy contractual data residency clauses.
- Hybrid:Split architectures process sensitive operator credentials locally while pushing non-critical utilization metrics to cloud dashboards.
- SaaS:Subscription licensing bundles software, cellular connectivity, and support into per-asset monthly fees.
Cloud-Based handles the majority of throughput; SaaS is the fastest mover on share.
Application:
Functional modules align with specific operational pain points, with compliance and maintenance functions commanding implementation priority.
- Asset Tracking:Geofencing and utilization monitoring modules deliver real-time equipment location across dispersed job sites. Rental fleet operators in the southeastern United States embed these capabilities into customer service level agreements to guarantee equipment availability windows.
- Maintenance Scheduling:Automated work order generation based on engine hour accumulation and diagnostic fault codes. Heavy civil contractors in the Pacific Northwest deploy these systems to synchronize shop capacity with seasonal weather windows.
- Fuel Management:Consumption analytics identify idle time patterns and theft incidents through tank level sensors.
- Operator Management:Certification tracking and behavior scoring modules integrate with ignition interlock systems.
- Compliance Monitoring:EPA emissions documentation and OSHA inspection interval logging for regulatory audit defense.
Asset Tracking anchors current revenue; Predictive Maintenance is expanding most quickly as AI modules mature.
End User:
Procurement sophistication varies sharply across customer categories, with rental companies driving standardization requirements.
- Equipment Rental Companies:Multi-tenant platform configurations enabling customer self-service utilization portals. National rental chains in the United States mandate API interoperability to consolidate mixed-fleet data from competing OEM telematics systems.
- Contractors:Job-site-centric deployments prioritizing mobile accessibility and rapid technician onboarding. Regional earthmoving specialists in the Midwest select platforms with simplified tablet interfaces to minimize training overhead for seasonal operators.
- Property Managers:Facilities maintenance applications tracking smaller equipment fleets across distributed commercial real estate portfolios.
- Infrastructure Developers:Long-term project platforms integrating equipment telemetry with schedule and budget management systems.
Contractors represent the established volume base; Equipment Rental Companies are gaining share fastest through subscription bundling.
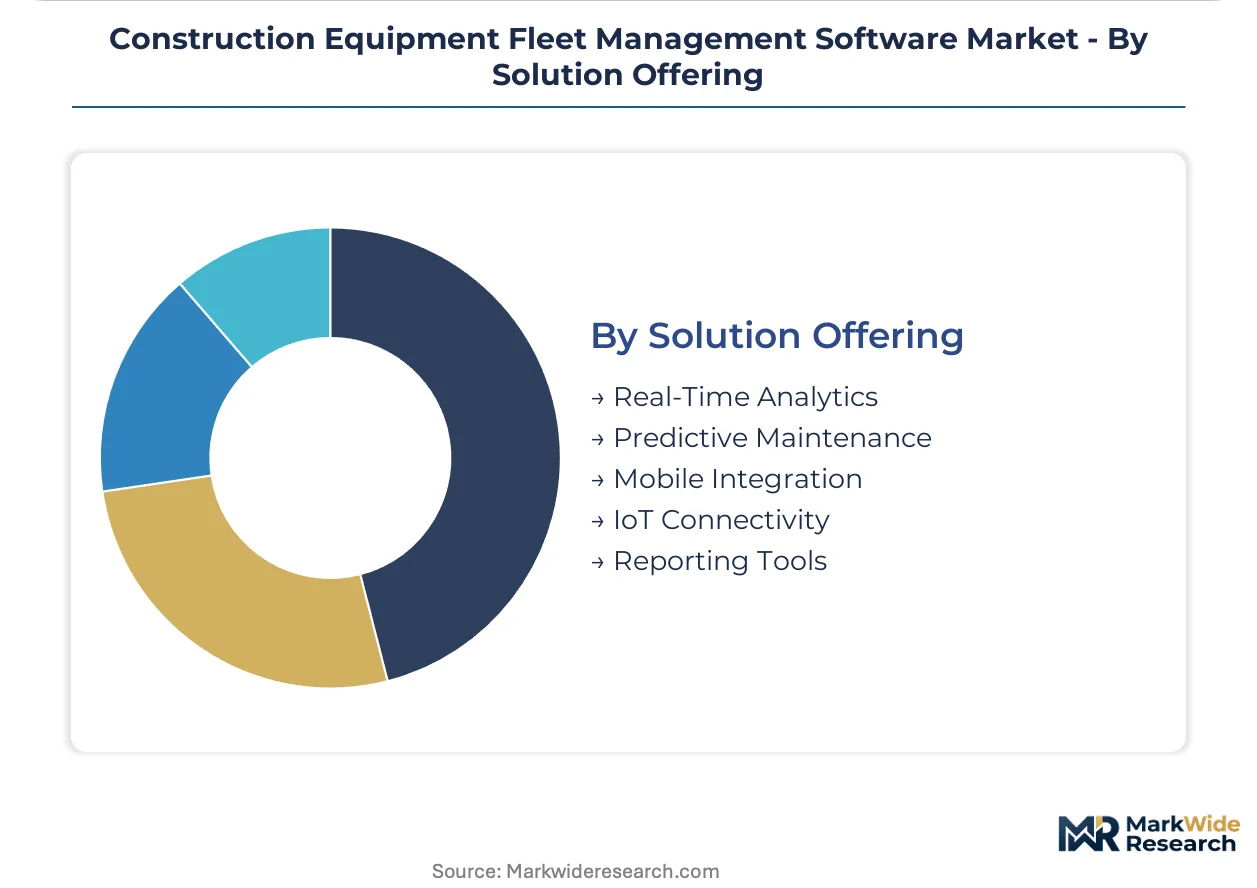
Solution Offering:
Capability tiers stratify around data processing sophistication, with predictive and mobile functions commanding pricing premiums.
- Predictive Maintenance:Machine learning models trained on hydraulic pressure, temperature, and vibration signatures to forecast component failures before operational impact. Excavator fleets in California pilot these systems to eliminate unplanned downtime during compressed construction seasons.
- Real-Time Analytics:Stream processing dashboards delivering immediate visibility into fleet utilization, fuel consumption, and operator productivity metrics.
- Mobile Integration:Native iOS and Android applications enabling field supervisors to access equipment status without desktop dependency.
- IoT Connectivity:Cellular and satellite transmission modules supporting equipment operation in remote locations beyond terrestrial network coverage.
- Reporting Tools:Configurable documentation generators for regulatory submissions and internal performance reviews.
Real-Time Analytics carries the current volume; Predictive Maintenance shows the steepest expansion trajectory as edge computing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards and infrastructure investment packages are accelerating fleet management software adoption across major construction markets. Contractors in high-regulation jurisdictions face compressed implementation timelines. Equipment rental chains are standardizing platform requirements across national footprints.
United States
Heavy civil contractors in Texas and California are deploying cloud-native platforms to manage dispersed highway and rail projects. OSHA crane operator certification mandates now require real-time verification systems before equipment ignition. The Pacific Northwest cluster around Seattle is piloting edge-computing predictive maintenance on excavator fleets to eliminate unplanned downtime during compressed construction seasons.
Germany
Construction equipment manufacturers in Baden-Württemberg are embedding fleet analytics into original machine sales through dealer networks. The EU Green Deal and national emissions targets compel automated compliance documentation for diesel engine fleets. Industrial clusters in Bavaria are integrating telematics with precision agriculture crossover technology from established measurement systems vendors.
China
National highway and metro rail buildouts are creating first-mover opportunities for cloud platforms targeting contractor digitization. MIIT telematics standards and dual carbon goals mandate real-time emissions monitoring for construction fleets. The Yangtze River Delta construction equipment hub around Shanghai is consolidating mixed-fleet data from competing OEM systems into unified analytics dashboards.
India
Infrastructure investment under national highway and urban rail programs is driving initial fleet management software adoption among emerging contractors. BIS equipment safety standards and state-level construction regulations are beginning to require documented maintenance intervals. The Delhi-Mumbai Industrial Corridor contractor base is selecting platforms with simplified mobile interfaces to minimize training overhead for seasonal operators.
United Arab Emirates
Mega-project developments in Dubai and Abu Dhabi are specifying fleet visibility platforms for international contractor consortia. MOHAP workplace safety protocols and municipal environmental regulations are expanding data capture requirements to include operator certification tracking. The NEOM construction zone in the northwest is mandating unified site management dashboards that merge heavy equipment telematics with drone-based surveying compliance tools.
Construction Equipment Fleet Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers. Original equipment manufacturers leverage embedded hardware and captive dealer networks to bundle subscription analytics with new machine deliveries. Independent software vendors compete through cloud-native architectures that minimize deployment friction for mid-sized rental fleets. Telecommunications and precision measurement specialists are crossing over from adjacent verticals to capture construction-specific workflows. Dominant competitive moves include strategic partnerships between OEMs and cellular connectivity providers, plus portfolio diversification into predictive maintenance modules that command premium pricing.
Within the OEM-embedded tier, Caterpillar and Volvo Construction Equipment exemplify manufacturers using dealer networks to distribute subscription-based fleet analytics. Among independent platform specialists, Samsara occupies a position representing cloud-native vendors that appeal to rental companies seeking rapid deployment without legacy infrastructure investment. These three anchors illustrate the structural tension between integrated hardware-software bundles and modular best-of-breed alternatives that contractors must evaluate as regulatory data requirements proliferate.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| John Deere |
| Komatsu |
| Trimble |
| Samsara |
| Geotab |
| Teletrac Navman |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Los Angeles container freight corridors transmit semiconductor shortage pressures into telematics hardware costs, compressing margins for mid-tier software vendors while enabling premium pricing for vertically integrated OEM bundles that bypass component spot markets.
Pricing Analysis
Certification level creates the primary spread between solution tiers, with EPA-compliant emissions documentation modules and OSHA-integrated operator verification systems commanding subscription premiums over basic asset tracking. SaaS-tiered licensing dominates, though consumption-based telemetry fees tied to engine hours are displacing flat per-asset rates among rental fleets. Price differentiation rests on predictive maintenance AI sophistication and edge-computing deployment. Pricing pressure intensifies in the mid-market as cloud-native entrants undercut legacy on-premise installations. Equipment rental companies exhibit highest price sensitivity due to thin utilization margins, while infrastructure developers absorbing long-term project costs show lowest sensitivity.
Supply Chain Analysis
Taiwan-based foundries and South Korean memory manufacturers hold concentrated capacity for telematics control units and onboard data storage modules. Component sourcing draws from Chinese PCB assembly, Mexican cable harness production, and German automotive-grade sensor suppliers. Raw material dependencies include lithium-ion cells for backup power, rare earth elements for antenna modules, and industrial-grade silicon for edge processors. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, exposing hardware procurement to geopolitical disruption. Distribution runs through OEM captive dealer networks, independent telematics installers, and direct cloud-platform provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction equipment fleet management software functions as a service-attach opportunity where predictive maintenance subscriptions and compliance documentation layers expand faster than base telematics hardware sales.
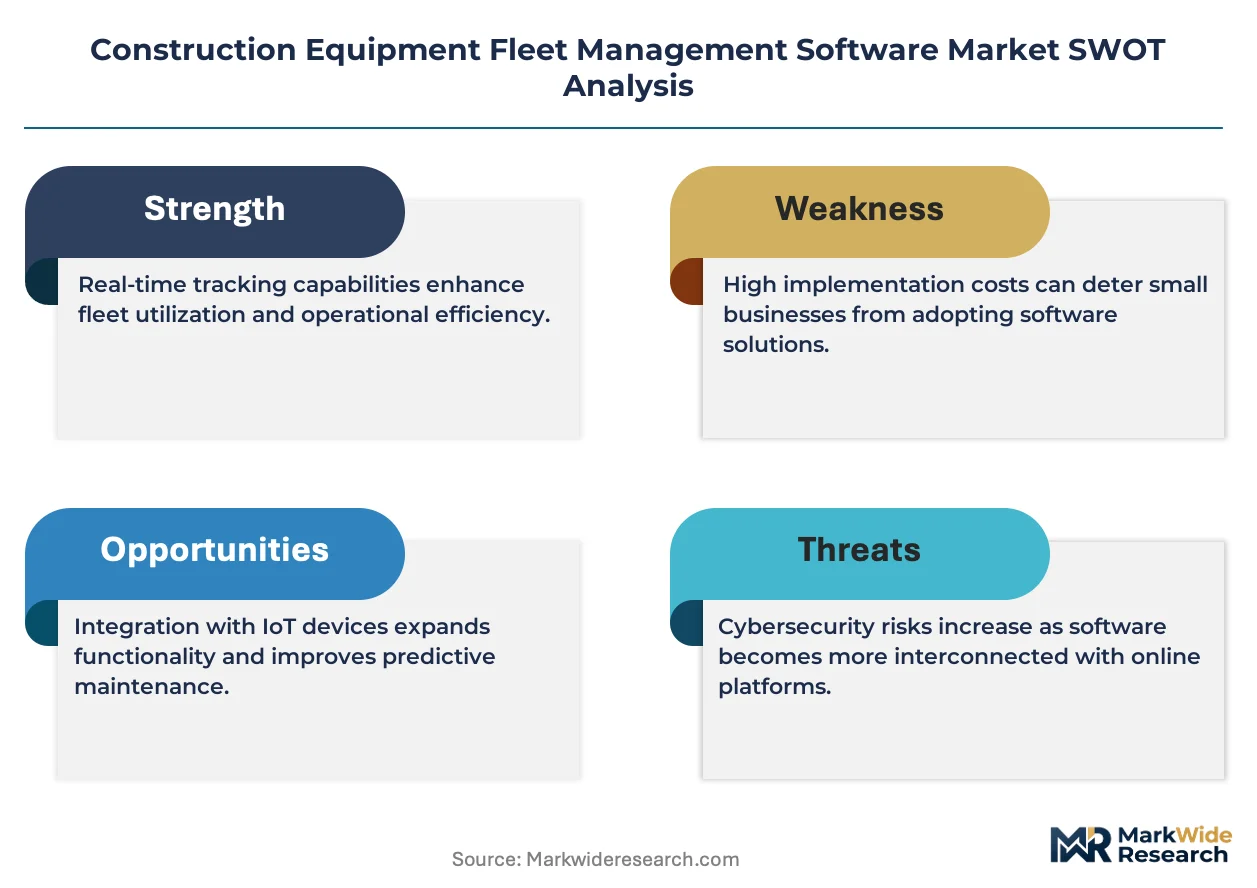
For Market Incumbents: Build switching-cost moats through deep integration with OEM ignition interlock systems and operator certification databases. Consolidate dealer network analytics partnerships to preempt cloud-native competitors from accessing equipment-generated data streams. Counter the threat of modular best-of-breed platforms by embedding proprietary edge-computing processors that lock telemetry formats to manufacturer-specific architectures. For New Entrants and Emerging Players: Establish a beachhead in India's emerging contractor digitization wave, where national infrastructure buildouts precede entrenched vendor relationships. Target mid-sized earthmoving specialists in secondary US markets seeking rapid deployment without legacy infrastructure overhaul. Penetrate through mobile-first platforms with simplified tablet interfaces that minimize seasonal operator training overhead. For Investors and Strategic Acquirers: Carve-out targets emerge from construction equipment manufacturers seeking to monetize captive telematics data through standalone software subsidiaries. Long-term viability hinges on regulatory compliance depth rather than feature breadth, favoring platforms with EPA and OSHA integration moats. Watch for inflection when edge-computing cost curves enable predictive maintenance at price points accessible to sub-50-asset fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Module Launch | Machine learning on hydraulic signatures reduces unplanned downtime for California excavator fleets. |
| OEM Dealer Network Partnership | Caterpillar leverages captive distribution to bundle subscription analytics with new equipment deliveries. |
| Edge Computing Architecture Deployment | Onboard inference eliminates cellular latency gaps that previously allowed catastrophic component failures. |
| Regulatory Compliance Integration | OSHA crane certification verification merges with ignition authorization in Texas and California workflows. |
| Cloud-Native Platform Expansion | Samsara targets mid-sized rental fleets seeking rapid deployment without legacy infrastructure investment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers at heavy civil contractors, telematics product directors at OEMs, rental company operations executives, and cellular connectivity procurement leads. Secondary validation incorporated EPA enforcement action databases, OSHA regulatory filing repositories, FCC equipment authorization records, and construction equipment production statistics from customs and trade sources. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against infrastructure investment flows anchored market sizing.
Calibration against historical telematics penetration curves and cross-vertical software-as-a-service expansion patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, operational application module, end-user procurement sophistication, and solution capability tier. CAGRs derived from equipment replacement cycle compression, regulatory mandate timelines, and 5G network rollout schedules. Edge-computing cost decline curves and predictive maintenance algorithm accuracy improvements served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in infrastructure appropriations, semiconductor availability, or cellular data pricing would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement continuity and OSHA rulemaking pace. Supply chain disruption risk and cross-border data sovereignty fragmentation represent primary revision triggers. Cross-checking against hyperscaler construction vertical revenue disclosures and OEM services segment growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global CMDB Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Packaged Software Market
Software & Services
PCB CAD Software Market
Software & Services
Course Authoring Software Market
Software & Services
Artwork Management Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Global Portal Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Business Rules Management System Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Global Electronic Data Capture Software Market