
 Corrugated Box Printer Slotter Machine Market | 2026-2036
Corrugated Box Printer Slotter Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Box Printer Slotter Machine Market Outlook
High-speed flexographic specification tiers is rotating demand toward machines rated above 15,000 sheets per hour with inline quality inspection. BOBST leverages its Swiss engineering heritage to dominate premium installations across European board mills. Keshenglong anchors cost-competitive automatic lines for Asian packaging converters scaling export capacity. Fosber extends its corrugator-to-finishing integration expertise into printer slotter bundles that reduce make-ready waste.
A corrugated box printer slotter machine combines rotary die-cutting, flexographic or digital printing, and slotting functions to convert flat corrugated board into finished shipping containers ready for folding and gluing. Modern units integrate servo-driven registration systems maintaining ±0.2 mm print-to-cut accuracy at production speeds exceeding 300 meters per minute, serving food, electronics, and pharmaceutical distribution networks. Automatic configurations command the largest installed base due to labor cost arbitrage and throughput requirements at tier-one packaging companies. Digital technology segments expand fastest among short-run e-commerce specialists requiring SKU-level customization without plate changeover downtime.
CE marking and EU machinery directives enforce guarding, noise emission, and electrical safety standards that shape European equipment design and import eligibility. EPA air quality rules in the United States restrict volatile organic compound emissions from solvent-based flexographic operations, accelerating converter migration to water-based and UV-cured ink systems. ISO 9001 quality management and ISO 14001 environmental certification increasingly filter supplier qualification for multinational packaging company procurement panels. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in the European Union redirect capital toward energy recovery and substrate lightweighting technologies.
Market Dynamics
E-commerce fulfillment velocity is compressing make-ready windows and forcing converters toward servo-driven registration systems that eliminate manual plate mounting. Tier-one packaging companies now demand inline quality inspection as a standard configuration, not a premium add-on.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based drying systems is accelerating capital replacement cycles across German and Italian board mills. Converters must retrofit or replace thermal equipment to maintain operating permits.
- Food contact compliance:Migration testing requirements for mineral oil saturated hydrocarbons in corrugated packaging are pushing European converters toward water-based ink configurations and dedicated food-grade production lines.
- Pharmaceutical distribution:Cold-chain serialization mandates in the United States are creating demand for printer slotter machines with integrated track-and-trace coding modules and tamper-evident slot configurations.
Market Restraints
- Steel price volatility:Machine frames and rotary die cylinders rely heavily on cold-rolled steel, exposing European and Asian OEMs to input cost swings that compress margin visibility on long-delivery contracts.
- Skilled technician scarcity:Servo system diagnostics and color management expertise concentrate in Germany, Switzerland, and Japan, limiting deployment speed in emerging manufacturing clusters.
- REACH chemical restrictions:The European Chemicals Agency's expanding candidate list of substances of very high concern is complicating ink formulation stability and extending qualification timelines for new consumable suppliers.
Strategic Opportunities
- India packaging automation:The country's PLI scheme for food processing and logistics infrastructure is creating first-mover advantage for equipment vendors establishing local assembly and service presence.
- UV-LED curing convergence:Combination of instant-dry UV chemistry with low-energy LED arrays is opening retrofit markets for existing flexographic installations seeking solvent emission elimination without full line replacement.
- Short-run e-commerce specialization:Digital hybrid configurations that eliminate plate inventory are capturing contract packaging specialists serving direct-to-consumer brands with high-SKU, low-volume requirements.
Industry Challenges
- ISO 14001 certification timelines:Multinational packaging company procurement panels now require environmental management system documentation, extending sales cycles by four to six months for uncertified suppliers.
- Legacy mechanical registration integration:Converters with 1990s-era folder-gluers face synchronization complexity when connecting modern servo-driven printer slotters to downstream equipment lacking compatible communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Box Printer Slotter Machine Market |
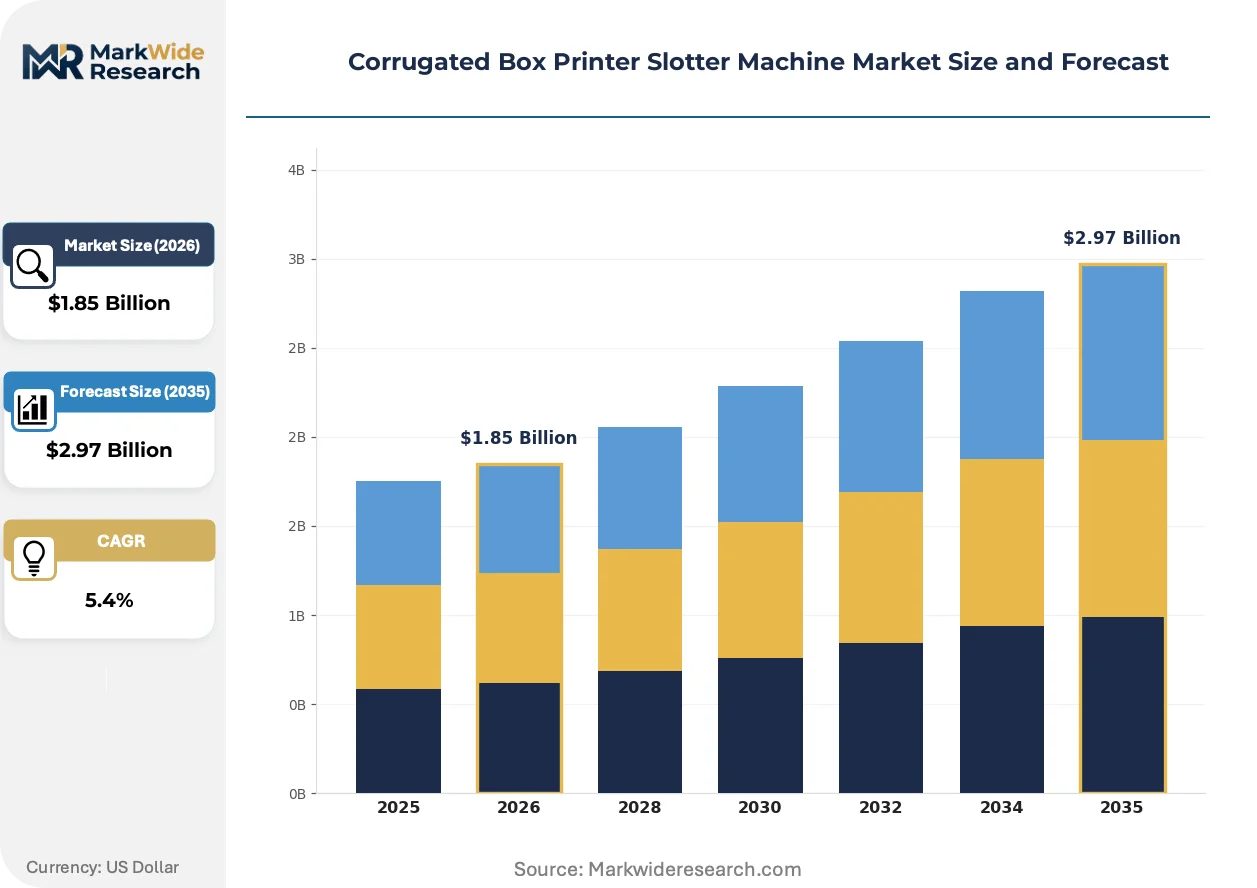
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Specialty Technology: Digital, Flexographic, Lithographic, Offset End User: Packaging Companies, E-commerce, Retailers, Manufacturers Application: Food Packaging, Electronics, Automotive, Pharmaceuticals |
| Companies Covered | Colines, Emba, BOBST, Esko, Jagenberg, BHS Corrugated, Fosber, Keshenglong, MPS Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Box Printer Slotter Machine Market Strategic Shifts
Machine architecture is pivoting from mechanical line shafts to distributed servo motion control, enabling independent axis adjustment and real-time register correction. This shift is compressing changeover intervals and expanding the viable application range of flexographic platforms.
Vision-based 100% inspection is displacing manual sampling protocols at high-volume food and pharmaceutical converters. Cameras mounted post-printing and post-slotting detect color deviation, board debris, and dimensional variance at production speed. Major European dairy and beverage packagers now specify this capability as a contract qualification requirement, forcing mid-tier equipment suppliers to develop partnerships with machine vision specialists or risk exclusion from tender shortlists.
EPA air quality enforcement under the National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound limits for flexographic operations in the United States. Solvent-based ink systems face escalating compliance costs and permitting delays. Converters in California, Texas, and the Midwest are migrating capital budgets toward water-based and electron beam curing alternatives, with equipment purchases increasingly contingent on demonstrated emission reduction trajectories.
After-sales service unbundling is fragmenting traditional OEM revenue models. Packaging converters in Germany and the Netherlands are separating hardware procurement from maintenance contracts, engaging third-party technical service networks for preventive maintenance and spare parts logistics. This disintermediation pressures incumbent suppliers to defend attachment rates through proprietary diagnostics software and remote monitoring subscriptions that lock in recurring revenue streams independent of initial equipment margins.
Corrugated Box Printer Slotter Machine Market Segmentation
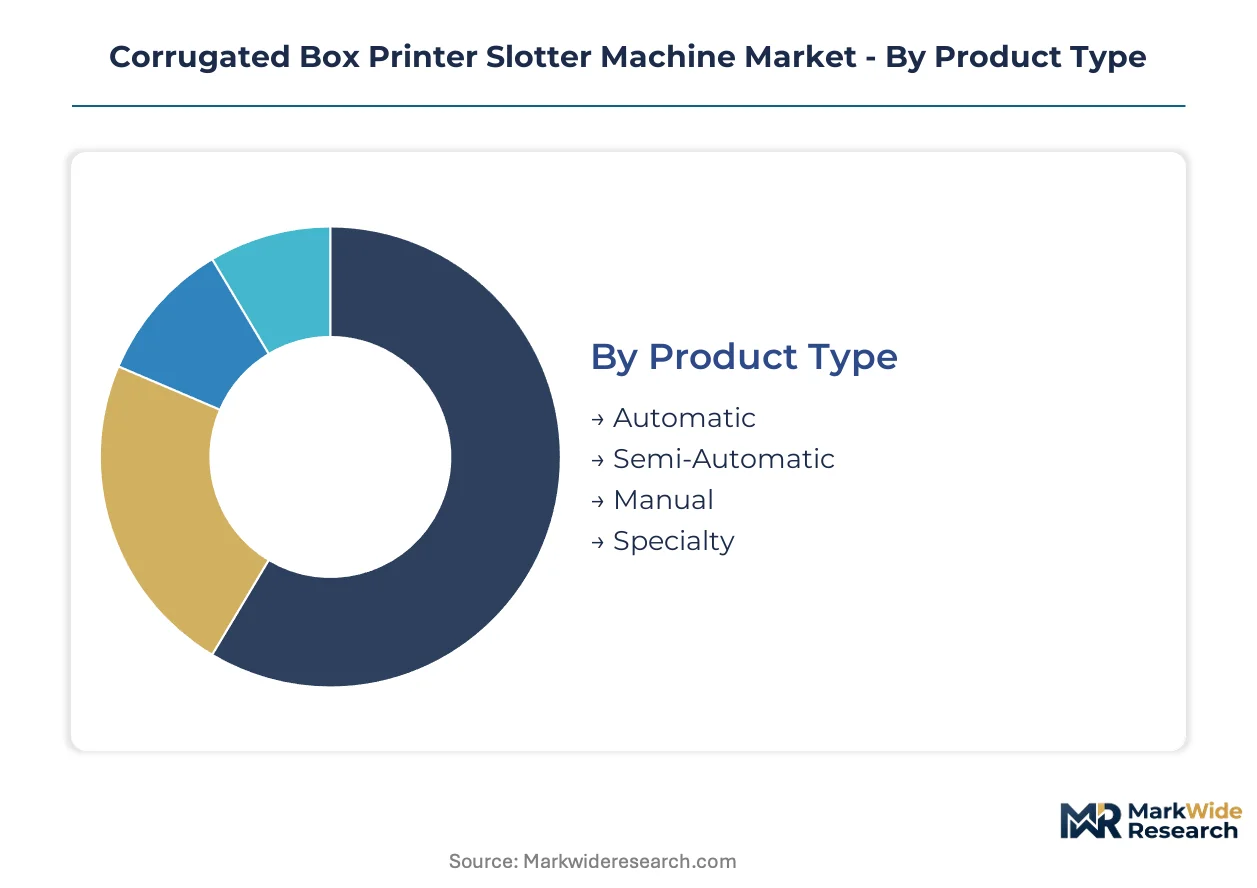
Printer slotter machine segmentation reveals how capital allocation splits between throughput-maximizing automation and customization-enabling digital platforms. Each dimension carries distinct margin profiles, certification requirements, and aftermarket service attach rates that shape vendor positioning.
Product Type:
Margin pools concentrate in configurations that reduce labor dependency and compress changeover intervals at high-volume converters.
- Automatic:Servo-driven registration systems maintain ±0.2 mm accuracy at speeds exceeding 300 meters per minute. German and Italian board mills dominate procurement as EU F-Gas Regulation compliance forces thermal equipment replacement cycles.
- Semi-Automatic:Hybrid mechanical-servo architectures serve mid-tier converters balancing throughput needs against capital constraints. Indian packaging automation initiatives under the PLI scheme are accelerating uptake among food processing infrastructure investors.
- Manual:Entry-level configurations persist in artisanal packaging and prototype production where batch sizes fall below 500 units.
- Specialty:Custom-built units handle oversized agricultural containers and heavy-duty industrial crating with reinforced frames and extended slotting beds.
The dominant share belongs to Automatic, while Digital technology segments are closing the gap fastest.
Technology:
Capital deployment intensity varies sharply by ink chemistry and curing architecture, with environmental compliance costs restructuring total cost of ownership calculations.
- Digital:Piezoelectric inkjet arrays eliminate plate inventory and enable SKU-level customization without makeready delays. E-commerce fulfillment specialists in California and Texas are migrating capital budgets toward these configurations as EPA emission enforcement tightens solvent-based permitting.
- Flexographic:Rotary letterpress systems with photopolymer plates dominate food and beverage volume production. Water-based ink configurations are displacing solvent systems across European converters responding to REACH chemical restrictions and mineral oil migration testing mandates.
- Lithographic:Planographic transfer methods serve premium retail packaging requiring photographic image reproduction on coated board substrates.
- Offset:Indirect printing architectures persist in long-run pharmaceutical and cosmetic applications where color consistency across million-unit batches outweighs makeready time penalties.
Flexographic retains the largest installed base, though Digital platforms are expanding most quickly among short-run specialists.
End User:
Procurement sophistication diverges between multinational packaging companies with centralized capital committees and fragmented contract converters serving regional brand owners.
- Packaging Companies:Tier-one converters with ISO 14001 certification demand inline quality inspection and remote diagnostics as standard configurations. German equipment suppliers capture premium installations through Swiss-engineered servo systems and CE-marked safety architectures.
- E-commerce:Fulfillment velocity requirements are compressing order-to-delivery windows below 24 hours. This end user segment is driving fastest adoption of digital hybrid machines that eliminate plate changeover downtime for high-SKU, low-volume direct-to-consumer brands.
- Retailers:Private-label packaging divisions at mass merchandisers specify standardized box formats that favor automatic lines with minimal changeover flexibility.
- Manufacturers:Captive packaging operations at electronics and automotive OEMs prioritize tamper-evident slot configurations and track-and-trace coding modules for cold-chain serialization compliance.
Packaging Companies command the dominant procurement volume, while E-commerce is gaining share fastest through fulfillment infrastructure expansion.
Application:
Regulatory stringency and substrate specification requirements create tiered pricing power across end-use verticals.
- Food Packaging:Dairy and beverage converters in Europe now specify vision-based 100% inspection as contract qualification requirements. Migration testing for mineral oil saturated hydrocarbons is pushing dedicated food-grade production lines with water-based ink configurations.
- Electronics:Anti-static coatings and precision slot tolerances protect sensitive components during distribution. Japanese and South Korean semiconductor packaging clusters drive demand for cleanroom-compatible machine specifications.
- Automotive:Heavy-duty triple-wall constructions and reinforced stacking features serve just-in-time parts logistics. German automotive supplier parks anchor regional capital concentration for high-tonnage automatic configurations.
- Pharmaceuticals:Cold-chain serialization mandates in the United States require integrated track-and-trace coding and tamper-evident slot geometries. FDA compliance documentation extends sales cycles but locks in multi-year service contracts.
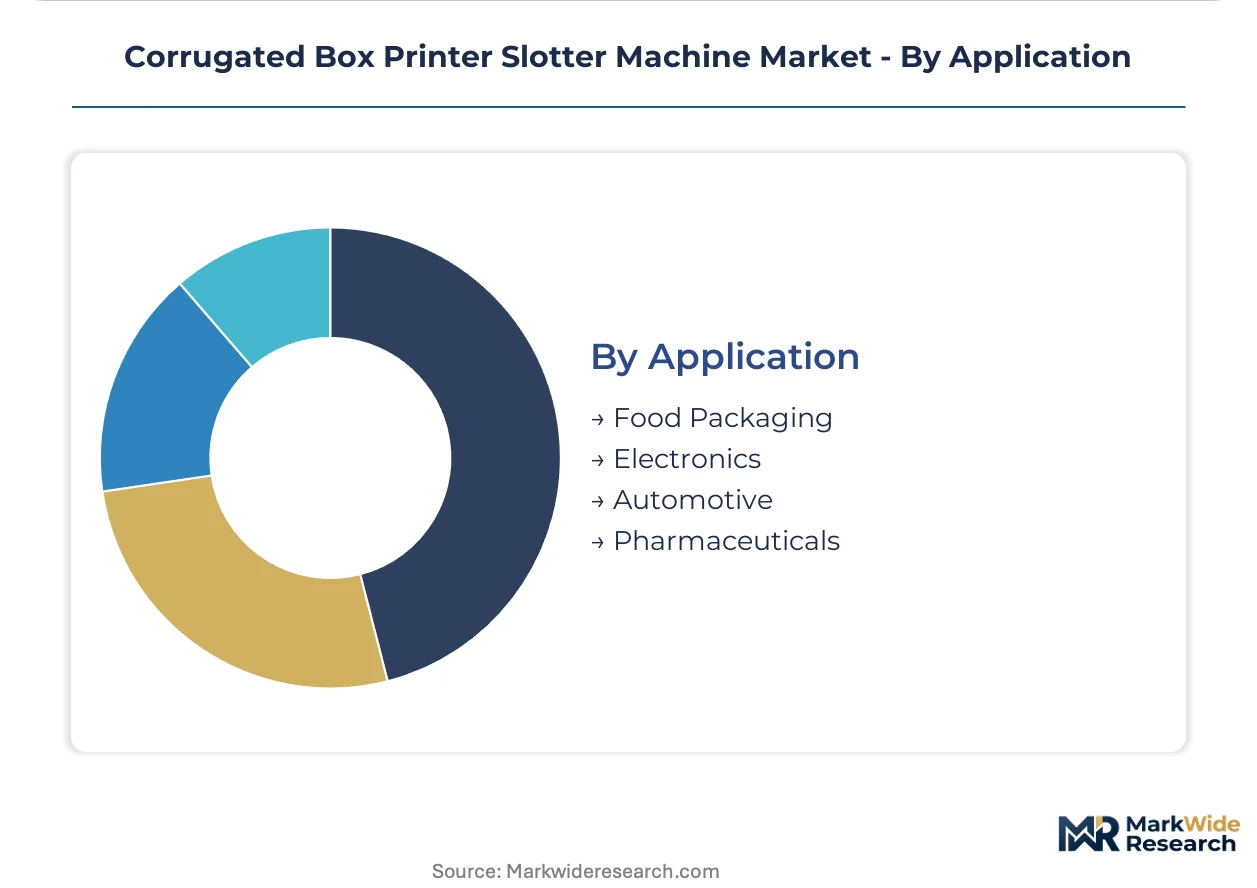
Food Packaging holds the dominant share, while Pharmaceuticals is climbing fastest on regulatory compliance-driven equipment refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. German board mills absorb premium servo-driven systems for EU F-Gas compliance, while Indian converters prioritize capital efficiency under PLI scheme incentives. Japanese semiconductor packaging clusters demand cleanroom-compatible specifications regardless of cost.
Germany
Automotive supplier parks in Baden-Württemberg and Lower Saxony anchor demand for heavy-duty automatic configurations with reinforced stacking features. The EU F-Gas Regulation forces thermal equipment replacement cycles across Bavarian board mills. Stuttgart and Hamburg concentrate premium installations where Swiss-engineered servo systems dominate procurement panels.
United States
EPA enforcement under National Emission Standards for Hazardous Air Pollutants accelerates converter migration to water-based and UV-cured ink systems in California and Texas. Cold-chain serialization mandates from FDA create demand for integrated track-and-trace coding modules. Midwest dairy and beverage packagers now specify vision-based inspection as contract qualification requirements.
China
Dual carbon goals redirect capital toward energy recovery systems and substrate lightweighting technologies in Yangtze River Delta packaging clusters. Export-oriented converters in Guangdong Province scale automatic line capacity for e-commerce fulfillment. Shanghai and Shenzhen equipment buyers prioritize retrofit compatibility with existing corrugator installations.
India
PLI scheme incentives for food processing infrastructure accelerate packaging automation uptake in Maharashtra and Gujarat. Mid-tier converters balance throughput needs against capital constraints through hybrid mechanical-servo architectures. Ahmedabad and Mumbai packaging clusters represent first-mover advantage for vendors establishing local assembly presence.
Japan
Semiconductor packaging clusters in Kanto and Kyushu drive cleanroom-compatible machine specifications with anti-static coatings and precision slot tolerances. METI industrial policy supports domestic equipment vendor consolidation. Osaka and Nagoya electronics manufacturers prioritize tamper-evident configurations for sensitive component distribution.
Corrugated Box Printer Slotter Machine Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the supplier base. The market exhibits tiered concentration with premium Swiss and German engineering houses commanding high-margin installations, while Asian fabricators capture volume through standardized automatic configurations. Three archetypes dominate: precision engineering specialists with servo system expertise, scale-oriented manufacturers of cost-competitive lines, and corrugator-to-finishing integrators reducing make-ready waste. Competitive moves center on geographic expansion into India's PLI-driven automation wave and technology licensing partnerships for UV-LED curing retrofits.
Among precision engineering specialists, BOBST leverages its Swiss heritage to dominate premium European board mill installations. Keshenglong anchors cost-competitive automatic lines for Asian packaging converters scaling export capacity. Fosber extends corrugator-to-finishing integration expertise into printer slotter bundles that reduce synchronization complexity with downstream equipment. These three represent distinct strategic positions without overlapping customer segments.
| Leading Market Players |
|---|
| Colines |
| Emba |
| BOBST |
| Esko |
| Jagenberg |
| BHS Corrugated |
| Fosber |
| Keshenglong |
| MPS Systems |
| Others |
Value Chain & Pricing Dynamics
Water-based ink configurations displacing solvent systems across European converters simultaneously redraws supply geography toward REACH-compliant chemical clusters and compresses pricing power for legacy thermal drying equipment. This substitution dynamic concentrates procurement leverage among German and Italian board mills while forcing Asian OEMs to absorb margin compression on long-delivery contracts.
Pricing Analysis
After-sales service contracts now drive lifetime value, with remote diagnostics subscriptions and spare parts logistics capturing recurring revenue streams independent of initial equipment margins. Three-tier pricing structure across premium Swiss-engineered servo systems, standard automatic configurations, and economy semi-automatic lines stratifies by certification grade and after-sales bundling. Cost compression in mid-tier segments is intensifying because steel price volatility exposes European and Asian fabricators to input cost swings. Contract converters in India exhibit highest price sensitivity, while German automotive supplier parks absorb premium installations regardless of cost.
Supply Chain Analysis
Extended lead times for cold-rolled steel rotary die cylinders and servo drive components now stretch delivery windows for European OEMs. Manufacturing concentrates in Germany, Italy, and China, with precision engineering anchored in Swiss-German corridors and cost-competitive fabrication scaling in Guangdong Province. Supply chains draw from specialty steel mills in Japan, linear motion suppliers in Switzerland, and ink chemistry formulators in the Netherlands. Single-source vulnerability concentrates in servo system diagnostics expertise limited to Germany, Switzerland, and Japan. Distribution runs through direct OEM sales teams for premium installations and third-party technical service networks for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring subscriptions and preventive maintenance contracts are expanding faster than hardware sales, reframing this market as a service-attach opportunity where recurring revenue layers determine long-term vendor viability.
For Market Incumbents: Consolidate aftermarket service networks through proprietary diagnostics software that locks in attachment rates against third-party technical service disintermediation. Defend premium positioning by deepening backward integration into servo drive manufacturing, reducing exposure to Japanese and Swiss component suppliers. Capacity expansion in Maharashtra and Gujarat captures India's PLI-driven automation wave before local assembly presence solidifies competitive moats.
For New Entrants and Emerging Players: Lead with UV-LED curing retrofit kits for existing flexographic installations, targeting California and Texas converters facing EPA emission enforcement without full line replacement capital. India's mid-tier packaging clusters under PLI scheme incentives represent the most penetrable geography, with hybrid mechanical-servo architectures balancing throughput needs against capital constraints. Partner with machine vision specialists to meet European dairy and beverage packager inspection requirements.
For Investors and Strategic Acquirers: The market sits at a compliance-forced replacement cycle phase that favors precision engineering specialists with servo system expertise and established CE marking pathways. Long-term viability hinges on service revenue attachment rates and retrofit technology licensing rather than pure hardware shipment volume. Watch for FDA cold-chain serialization mandate expansion as the signal indicating accelerated pharmaceutical equipment refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Curing Retrofit Development | Eliminates solvent emissions for EPA-regulated converters without full line replacement capital. |
| Remote Diagnostics Platform Launch | Locks in recurring service revenue against third-party technical service disintermediation. |
| India Local Assembly Establishment | Captures PLI scheme incentives before mid-tier converter procurement panels consolidate. |
| Machine Vision Partnership | Meets European dairy packager inspection requirements that now filter tender shortlists. |
| Servo Drive Backward Integration | Reduces margin exposure to Japanese and Swiss component supplier concentration. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with packaging plant engineers, OEM procurement teams, aftermarket service heads, and corrugated board mill maintenance directors; and secondary validation through SEC filings of listed equipment vendors, EU F-Gas Regulation compliance databases, EPA National Emission Standards enforcement records, and ISO certification registries. Bottom-up equipment shipment tracking triangulated against top-down capital expenditure surveys of tier-one packaging companies.
Across the projection horizon, the analytical framework modeled segmentation across automation tier, ink chemistry architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, e-commerce fulfillment infrastructure buildout trajectories, and compliance-forced thermal equipment phaseout schedules. Forecast inputs incorporated steel price volatility indices and skilled technician availability by geography.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement, stable steel input costs, or continued PLI scheme funding would require recalibration. Forecasts reflect documented assumptions about replacement cycle timing and compliance cost pass-through. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Lipstick Molding Machines Market