
 Multiphysics Software Market | 2026-2036
Multiphysics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multiphysics Software Market Foresight
Academic licensing channels is rewriting how multiphysics tools reach early-career engineers. ANSYS leverages university partnerships to seed future enterprise adoption. COMSOL anchors its position through specialized electrochemistry modules that dominate battery research labs. Siemens competes by bundling multiphysics capabilities with its digital twin platform, creating captive demand among industrial automation buyers.
Multiphysics software integrates multiple physical models—thermal, structural, fluid, electromagnetic—into unified simulation environments, typically solving coupled partial differential equations across shared meshes to predict real-world system behavior before physical prototyping. Finite Element Analysis commands the largest installed base due to decades of validation in structural safety certification, while Computational Fluid Dynamics tools capture premium pricing in turbomachinery and aerodynamics workflows where mesh refinement demands specialized expertise. Cloud-based deployment is expanding fastest among mid-tier manufacturers that lack on-premises HPC infrastructure but require burst capacity for complex coupled simulations.
FDA validation requirements for computational modeling in medical device submissions shape healthcare sector demand, while FAA certification pathways for digital twins in aircraft propulsion systems mandate traceable simulation workflows. EU AI Act risk classifications for autonomous systems are beginning to influence how automotive OEMs document simulation-based safety claims. Stakeholders must weigh cloud dependency against export control restrictions on high-performance simulation codes when structuring platform strategies.
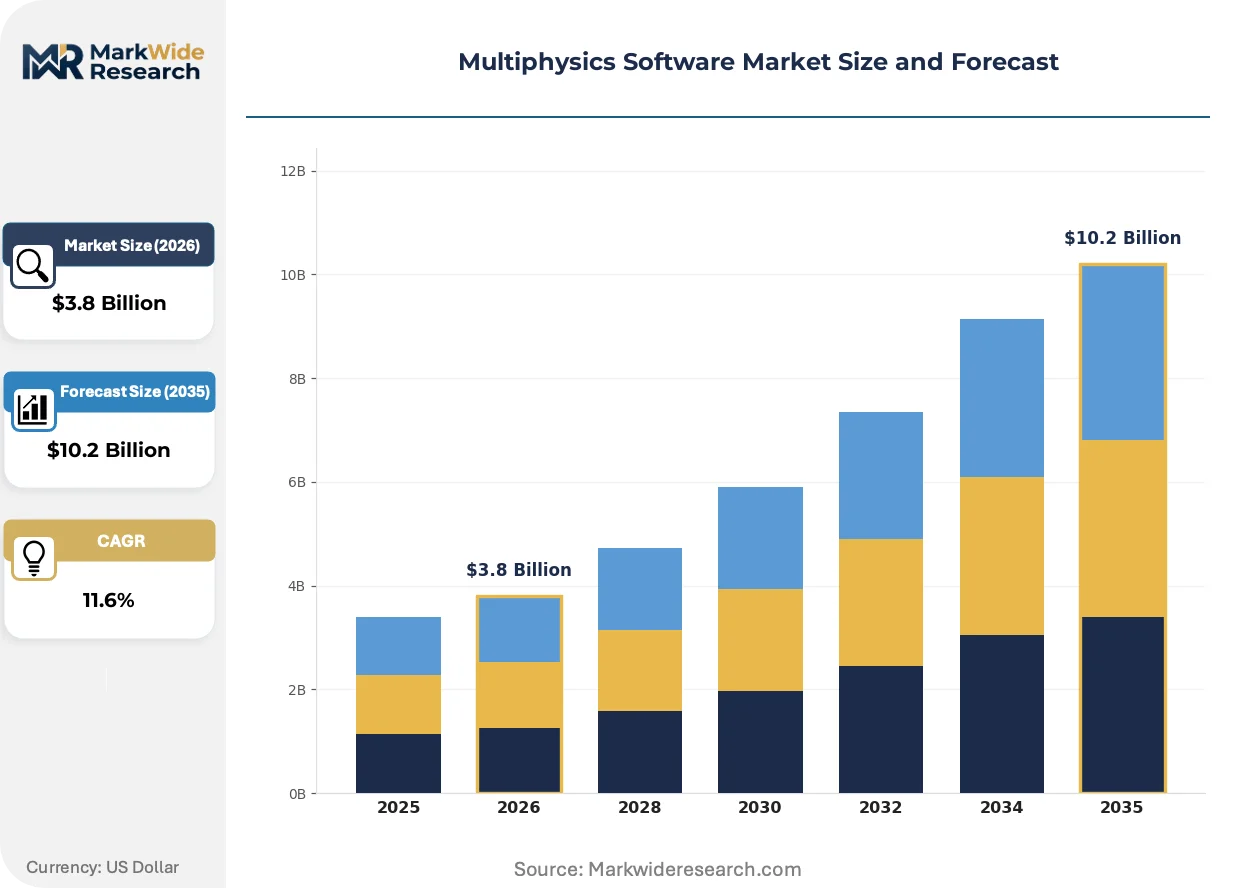
Market Dynamics
Automotive electrification programs in Germany and Japan are compressing thermal-electric simulation cycles, forcing software vendors to pre-integrate battery degradation models with structural solvers before procurement bids close.
Growth Catalysts
- EU AI Act risk classifications:Automotive OEMs in Stuttgart and Wolfsburg now document simulation-based safety claims for autonomous systems, expanding validation software budgets.
- Battery research labs:Electrochemistry-thermal coupling modules dominate procurement in solid-state cell development programs across South Korea and Japan.
- Cloud burst capacity:Mid-tier manufacturers without on-premises HPC infrastructure access coupled physics simulations through metered cloud instances.
Market Restraints
- Export control restrictions:US Commerce Department licensing delays block high-performance simulation code transfers to Chinese aerospace institutes.
- Specialized mesh refinement expertise:Computational fluid dynamics workflows require PhD-level talent pools concentrated in Munich, Toulouse, and Cambridge MA.
- Perpetual license amortization:Defense contractors in Arlington and Bethesda resist subscription migration, locking maintenance revenue at 1990s price points.
Strategic Opportunities
- FAA digital twin certification pathways:Aircraft propulsion system suppliers in Hartford and Cincinnati invest in traceable simulation workflows for turbine blade lifing.
- Digital twin platform bundling:Industrial automation buyers in Siemens' installed base accept captive multiphysics modules as standard digital infrastructure.
- University partnership seeding:ANSYS and COMSOL anchor early-career engineer preference through curriculum-embedded academic licensing.
Industry Challenges
- Legacy solver integration:Aerospace supply chains in Toulouse and Hamburg maintain 30-year-old Fortran-based structural codes that resist API modernization.
- Cross-disciplinary talent scarcity:Coupled physics simulation teams require simultaneous expertise in finite element methods, computational fluid dynamics, and electromagnetic theory.
- FDA 510(k) validation timelines:Medical device submissions in Minneapolis and Irvine face 18-month computational modeling review cycles for patient-specific implant simulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiphysics Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finite Element Analysis, Computational Fluid Dynamics, Multibody Dynamics, Electromagnetic Simulation End User: Aerospace, Automotive, Energy, Healthcare Deployment: On-premises, Cloud-based, Hybrid, SaaS Application: Product Design, Performance Optimization, Structural Analysis, Thermal Management |
| Companies Covered | ANSYS, COMSOL, Dassault Systèmes, Siemens, Altair Engineering, Autodesk, Cadence Design Systems, ESI Group, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiphysics Software Market Shifts & Advancements
Simulation workflows are compressing from months to weeks through solver architecture changes and deployment model shifts, with three forces now determining competitive positioning in procurement cycles.
Reduced-order modeling is migrating from research environments into production engineering workflows. Automotive thermal management teams in Stuttgart now deploy neural-surrogate models for real-time battery pack optimization, collapsing overnight batch jobs into interactive design loops that enable same-day iteration cycles previously requiring week-long solver runs.
FDA validation requirements for computational modeling in medical device submissions now mandate documented solver verification for patient-specific orthopedic implants. Minneapolis-based spine hardware manufacturers must submit mesh convergence studies and code verification evidence alongside traditional mechanical testing data, extending regulatory dossiers by 40 percent but creating captive demand for pre-validated simulation platforms.
Engineering consultancies in Chicago and Houston now unbundle perpetual licenses in favor of consumption-based cloud access. Burst pricing for coupled thermal-structural runs allows mid-size firms to compete for turbomachinery contracts without capitalizing on-premises HPC clusters, shifting vendor revenue recognition from upfront bookings to metered usage ramps.
Multiphysics Software Market Segmentation
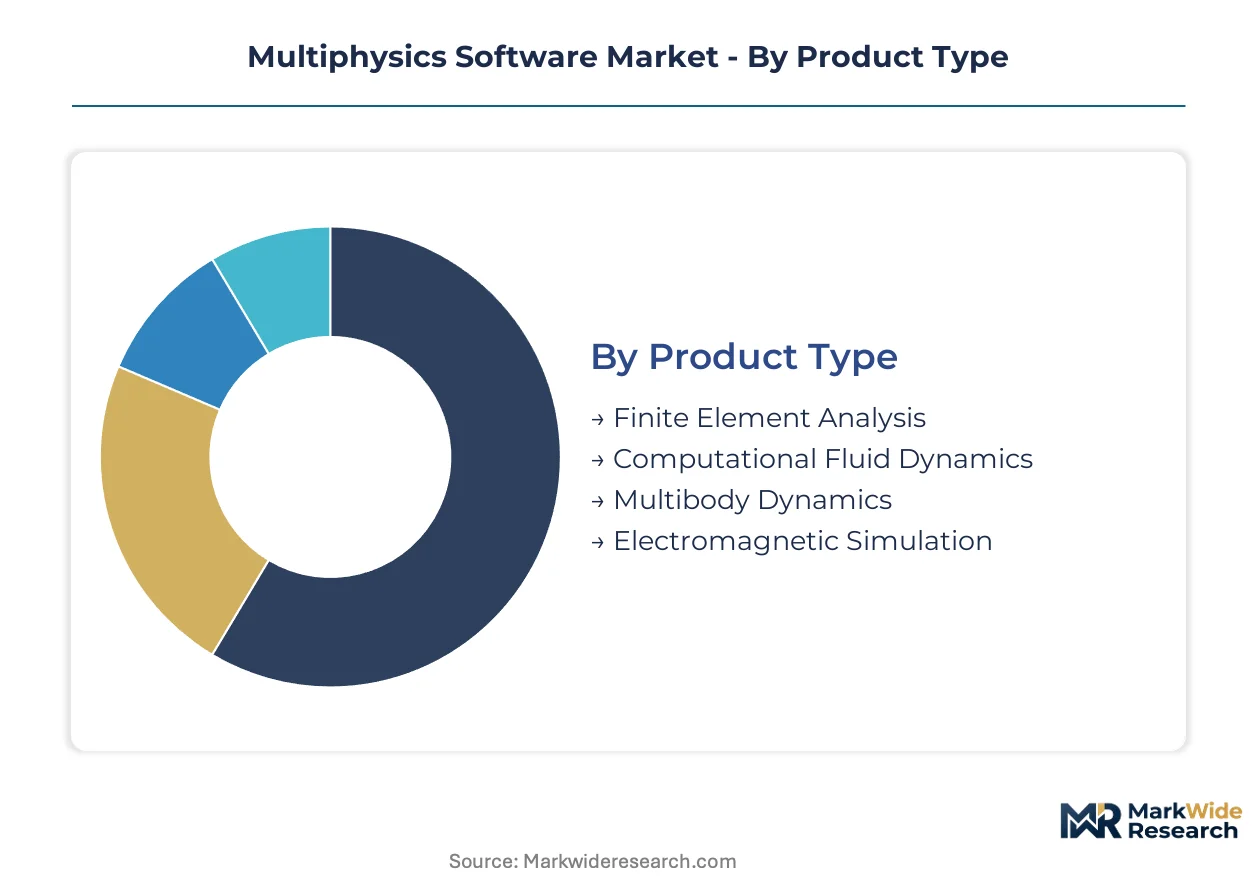
Multiphysics software procurement follows distinct technical and commercial logics across engineering disciplines. Deployment constraints, solver specialization, and regulatory validation requirements create divergent purchasing patterns that vendors must navigate through tailored licensing structures.
Product Type:
Engineering teams select solvers based on the dominant physics governing their design failure modes, with thermal-electric coupling and fluid-structure interaction driving hybrid tool adoption.
- Finite Element Analysis:Structural mechanics solvers discretize continuum domains into mesh elements for stress, vibration, and deformation prediction. Aerospace supply chains in Toulouse and Hamburg maintain decades of validation data for safety-critical airframe certification, creating high switching costs for alternative methods.
- Computational Fluid Dynamics:Navier-Stokes solvers resolve turbulent flow fields with specialized mesh refinement near boundary layers. Turbomachinery designers in Cincinnati and Hartford pay premium licensing for conjugate heat transfer modules that couple blade aerodynamics with thermal stress lifing calculations.
- Multibody Dynamics:Rigid and flexible body kinematics simulators model articulated mechanical systems with contact and constraint equations. Automotive suspension development teams deploy these tools for ride comfort optimization.
- Electromagnetic Simulation:Maxwell equation solvers predict field distributions for antenna design, motor torque mapping, and eddy current heating. Battery research labs in South Korea and Japan prioritize electrochemistry-coupled electromagnetic modules for solid-state cell development.
The dominant share belongs to Finite Element Analysis, while Electromagnetic Simulation is closing the gap fastest.
End User:
Capital intensity and regulatory burden vary sharply across sectors, with certification-driven industries accepting higher per-seat costs for traceable solver validation.
- Aerospace:Airframe and propulsion manufacturers require FAA-compliant simulation workflows with version-controlled solver releases and audit trails. Hartford-based turbine suppliers invest in digital twin platforms for blade lifing documentation.
- Automotive:OEMs in Stuttgart and Wolfsburg compress thermal-electric simulation cycles for battery pack integration, pre-integrating degradation models with structural solvers.
- Energy:Wind turbine and power generation equipment makers optimize drivetrain reliability through coupled mechanical-electromagnetic analysis.
- Healthcare:Minneapolis spine hardware manufacturers face FDA-mandated mesh convergence studies for patient-specific orthopedic implants, extending regulatory dossiers substantially.
Aerospace commands the highest per-seat pricing, though Healthcare is expanding validation software budgets most aggressively.
Deployment:
Infrastructure ownership patterns determine whether engineering teams capitalize HPC clusters or convert fixed costs to metered consumption.
- On-premises:Perpetual licenses with local compute resources suit defense contractors in Arlington and Bethesda resisting subscription migration. These installations maintain maintenance revenue at historical price points.
- Cloud-based:Metered burst capacity enables mid-tier manufacturers without on-premises infrastructure to compete for complex coupled simulations. Engineering consultancies in Chicago and Houston favor consumption-based access for turbomachinery contracts.
- Hybrid:Mixed deployments reserve sensitive preprocessing on local workstations while offloading solver iterations to external clusters.
- SaaS:Fully managed browser-accessible environments lower entry barriers for academic licensing channels seeding early-career engineer preference.
On-premises retains the largest installed base, yet Cloud-based deployment is climbing the fastest among new procurement cycles.
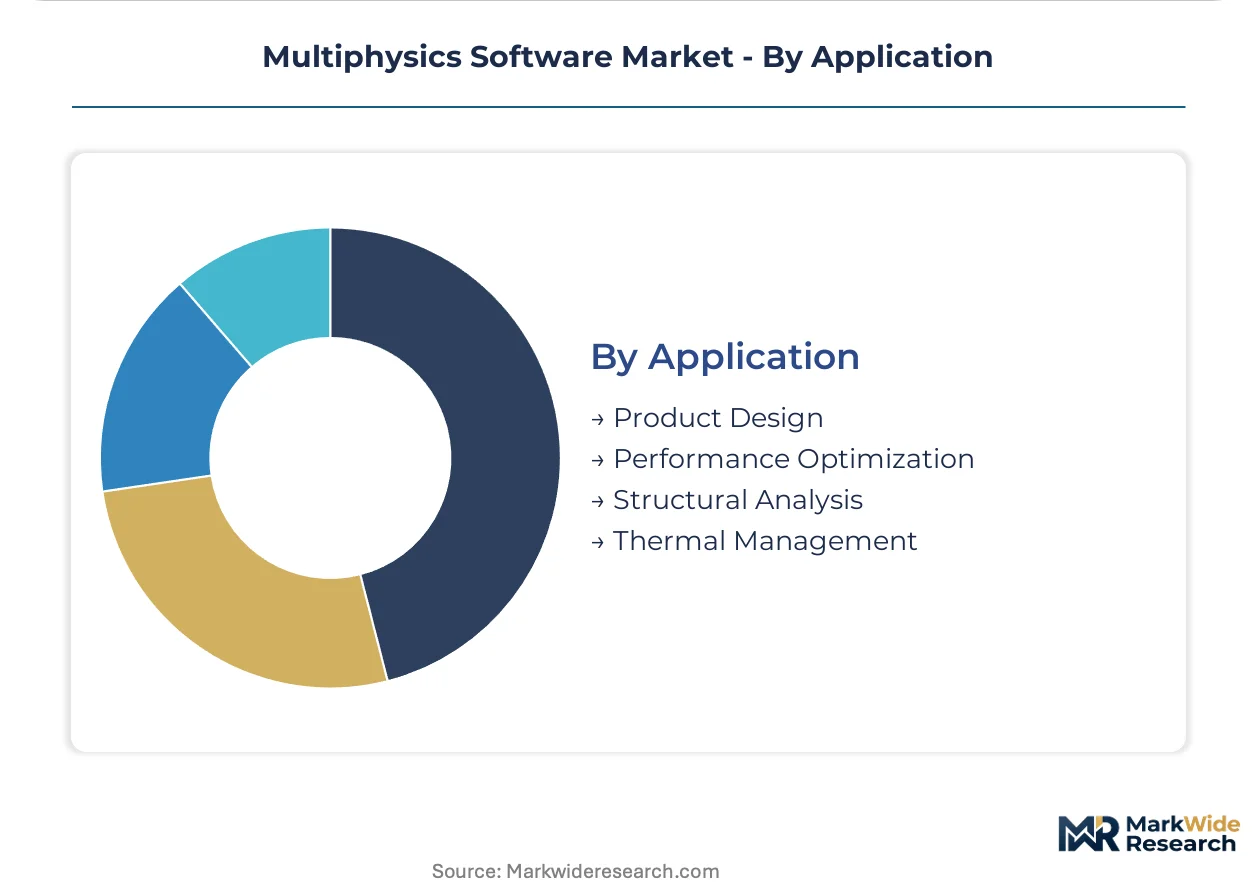
Application:
Simulation maturity across the product lifecycle determines whether tools support exploratory design or formal verification activities.
- Product Design:Early-stage topology optimization and concept validation require rapid iteration with reduced-order models. Stuttgart automotive thermal management teams deploy neural-surrogate models for real-time battery pack optimization.
- Performance Optimization:Multi-objective sweeps across operating envelopes identify robust design points. Turbomachinery workflows prioritize efficiency and durability trade-offs.
- Structural Analysis:Safety factor verification against yield and ultimate limits dominates aerospace certification pathways.
- Thermal Management:Heat dissipation and thermal stress prediction governs electronics packaging and electrified powertrain development.
Product Design absorbs the broadest user base, while Performance Optimization is gaining share fastest as reduced-order modeling compresses iteration cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering clusters while Japanese battery labs drive module specialization premiums. North American consultancies convert fixed infrastructure costs to metered cloud consumption, compressing regional margin spreads.
United States
FAA certification pathways for aircraft propulsion digital twins anchor demand in Hartford and Cincinnati turbine corridors. Defense contractors in Arlington and Bethesda perpetuate legacy license structures that resist subscription migration. FDA validation requirements for computational modeling in medical devices shape Minneapolis and Irvine procurement budgets for orthopedic implant simulations.
Germany
Automotive electrification programs in Stuttgart and Wolfsburg compress thermal-electric simulation cycles for battery pack integration. EU AI Act risk classifications mandate documented simulation-based safety claims for autonomous systems. KBA oversight intersects with OEM procurement timelines, forcing vendors to pre-integrate degradation models before bids close.
Japan
Solid-state cell development programs across domestic battery research labs prioritize electrochemistry-thermal coupling modules. METI industrial policy supports simulation infrastructure for automotive electrification supply chains. Toyota City and Nagoya manufacturing clusters deploy coupled physics tools for powertrain thermal management optimization.
South Korea
Battery research labs in Daejeon and Seoul drive procurement for electrochemistry-specialized multiphysics platforms. MFDS regulatory frameworks for medical device computational modeling remain less prescriptive than FDA equivalents, creating export-focused validation strategies. Samsung and LG supply chain clusters in Gyeonggi Province anchor regional solver demand.
China
US Commerce Department export control licensing delays block high-performance simulation code transfers to aerospace institutes in Beijing and Xi'an. Domestic substitution programs accelerate local solver development for thermal-structural applications. MIIT standards frameworks for autonomous vehicle simulation documentation partially offset foreign platform access restrictions.
Multiphysics Software Market Competitive Landscape
Full-stack platform vendors and specialized module developers split the market into distinct competitive spheres. Consolidation pressure concentrates among industrial automation buyers seeking bundled digital twin infrastructure. Three archetypes dominate: integrated CAE conglomerates, physics-specialized independents, and cloud-native entrants. Strategic moves center on university partnership seeding for early-career engineer capture and academic licensing channel expansion.
Within the integrated platform tier, ANSYS and Siemens occupy positions that exemplify divergent bundling strategies. ANSYS anchors enterprise preference through curriculum-embedded academic licensing that seeds future procurement decisions. Siemens leverages its industrial automation installed base to create captive demand for multiphysics modules as standard digital infrastructure. COMSOL represents the specialized independent archetype, occupying a position defined by electrochemistry module dominance in battery research applications.
| Leading Market Players |
|---|
| ANSYS |
| COMSOL |
| Dassault Systèmes |
| Siemens |
| Altair Engineering |
| Autodesk |
| Cadence Design Systems |
| ESI Group |
| PTC |
| Others |
Supply & Pricing Matrix
Shanghai-Los Angeles container corridor cost volatility feeds directly into cloud infrastructure pricing for metered simulation workloads, compressing margins for vendors serving mid-tier manufacturers while amplifying differentiation premiums for pre-integrated battery degradation modules in Stuttgart procurement cycles.
Pricing Analysis
The customization-premium spread separates standard SaaS-tiered subscriptions from configured-to-order perpetual licenses with electrochemistry module bundling. Pricing stratifies across premium, standard, and economy tiers based on solver certification level—FAA-compliant traceable releases command substantial premiums over academic licensing channels—and vertical integration depth with digital twin platforms. Pricing pressure stems from defense contractors in Arlington and Bethesda resisting subscription migration, locking maintenance revenue at historical benchmarks. Mid-tier engineering consultancies in Chicago exhibit highest price sensitivity, while Hartford turbine suppliers demonstrate lowest sensitivity due to FAA certification pathway requirements.
Supply Chain Analysis
Contract manufacturing concentration for HPC hardware rests with Taiwan Semiconductor Manufacturing and Samsung Foundry for GPU accelerators critical to coupled physics simulations. Software development draws from engineering talent pools concentrated in Germany, Japan, and the United States, with electrochemistry module specialization anchored in South Korean battery research clusters. Supply chain risk centers on US Commerce Department export control licensing delays blocking high-performance simulation code transfers to Chinese aerospace institutes. Distribution runs through direct enterprise sales teams for perpetual licenses and hyperscaler marketplaces for cloud-based consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
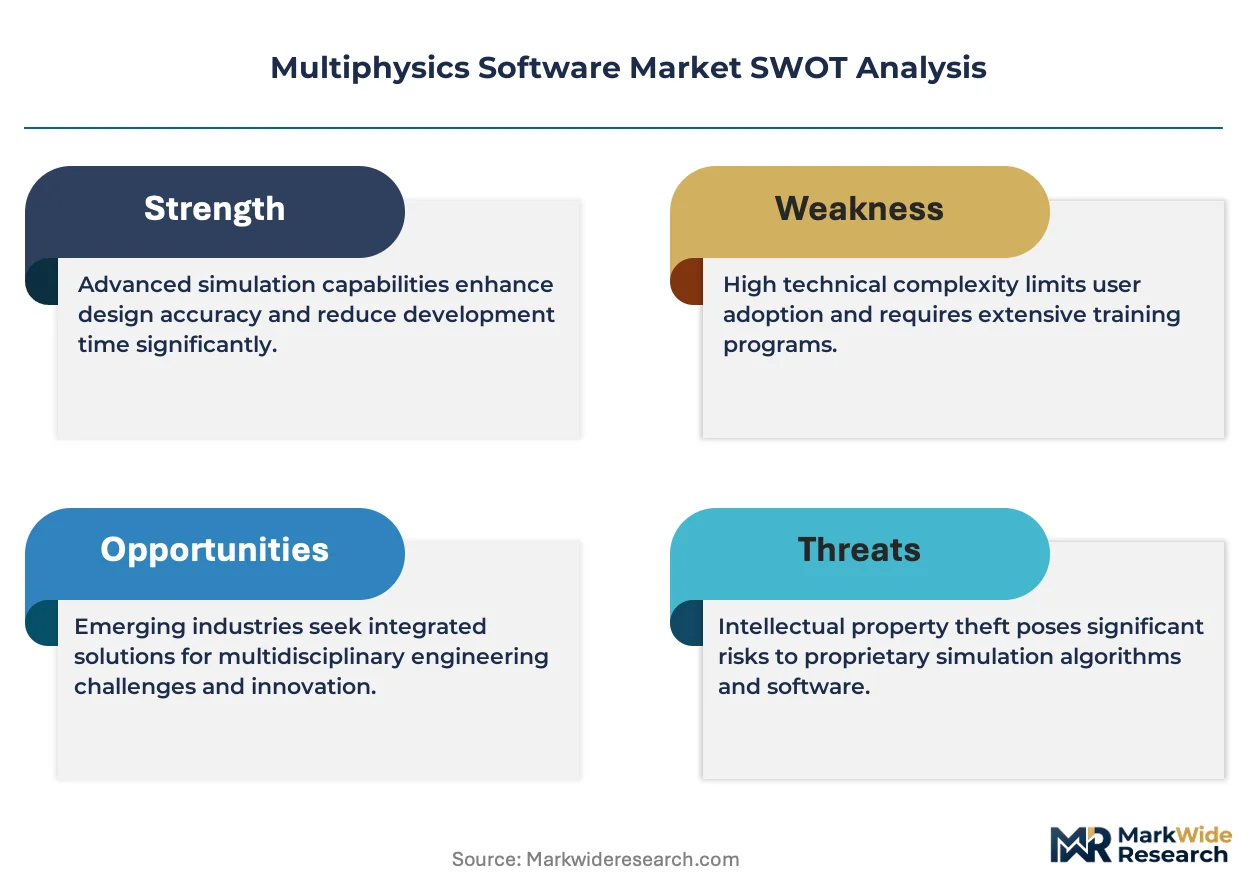
Platform economics inflection is underway as digital twin interoperability standards force bundling decisions across industrial automation ecosystems, with Siemens' captive demand creation now pressuring standalone solver vendors toward API standardization or acquisition.
For Market Incumbents: Entrench academic licensing channel dominance through curriculum-embedded partnerships that seed early-career engineer preference before procurement authority consolidates. Deepen backward integration into cloud infrastructure partnerships to secure burst capacity pricing advantages against hyperscaler-native entrants. FDA validation documentation investments create switching cost moats for Minneapolis medical device manufacturers.
For New Entrants and Emerging Players: Pursue reduced-order modeling specialization for real-time battery pack optimization workflows in Stuttgart automotive thermal management teams, where neural-surrogate model demand outpaces incumbent solver architecture refresh cycles. Target cloud-native SaaS delivery for mid-tier manufacturers in Chicago and Houston lacking on-premises HPC infrastructure. Lead with consumption-based pricing transparency against legacy perpetual license opacity.
For Investors and Strategic Acquirers: Physics-specialized independents with electrochemistry module dominance represent priority acquisition archetypes as battery research lab procurement concentrates in South Korea and Japan. Long-term viability hinges on solver verification documentation depth for regulatory submission pathways rather than raw computational performance benchmarks. Watch FDA computational modeling validation timeline compression as inflection signal for pre-validated platform premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Digital twin bundling creates captive demand among Siemens industrial automation buyers. |
| Acquisition of Specialist Firm | Electrochemistry module developers anchor battery research lab procurement in Daejeon. |
| Product Launch | Reduced-order modeling tools collapse Stuttgart automotive thermal simulation cycles to hours. |
| Strategic Partnership | University curriculum embedding seeds ANSYS enterprise preference among early-career engineers. |
| Geographic Expansion | Cloud burst capacity enables Chicago consultancies to compete for turbomachinery contracts. |
Research Methodology
Cross-validation between primary interviews with simulation software procurement officers, platform engineering directors, and regulatory affairs leads at medical device manufacturers anchors the qualitative findings, supplemented by secondary validation against FAA certification pathway documentation, FDA computational modeling guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model adoption patterns and top-down reconciliation with industrial automation software spending aggregates produced convergent estimates.
Calibration against historical solver licensing transitions and cloud migration patterns informed the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, end-use industry vertical, solver physics specialization, and regulatory validation tier. CAGRs were derived from coupling intensity trends in automotive electrification programs and medical device submission volumes, with electrochemistry-thermal coupling module penetration and reduced-order modeling adoption velocity serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure pricing, defense procurement cycles, or EU AI Act enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding solver verification timeline compression and academic licensing channel expansion. Quarterly review of FDA computational modeling submission volumes, Stuttgart OEM procurement bid timelines, and US Commerce Department export control licensing queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ccaas Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Cemetery Management Software Market
Software & Services
Data Integration Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
File Sharing Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Performance Management Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Quick Service Restaurants (QSR) IT Market