
 Middle East HR Payroll Software Market | 2026-2036
Middle East HR Payroll Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East HR Payroll Software Market Analytics
Wage Protection System mandates across Gulf states is decoupling compliance from manual payroll processing, forcing employers to absorb new software costs or face operational penalties. SAP SE leverages deep enterprise relationships across hydrocarbon and logistics sectors to sustain platform stickiness. Oracle Corporation anchors its regional position through localized tax engines that handle zakat and social insurance calculations. ZenHR competes aggressively on Arabic-language interfaces and Sharia-compliant leave management modules.
HR payroll software comprises cloud-hosted and on-premise systems that automate salary calculation, statutory deductions, and disbursement workflows across multi-currency, multi-jurisdiction workforces. Core functional parameters include real-time gross-to-net engines, bank integration APIs, and audit trails that satisfy labor ministry inspection protocols. Cloud-based deployment leads segment value as Gulf enterprises abandon legacy server farms for SaaS models with automatic regulatory updates. Small and medium enterprises represent the fastest-expanding customer type, drawn by per-employee pricing that eliminates capital expenditure barriers. Payroll management functionality captures the largest margin pool, though tax compliance modules command premium pricing during fiscal calendar transitions.
Saudi Arabia's Ministry of Human Resources and Social Development enforces Nitaqat quotas that require granular workforce reporting only automated platforms can deliver. The UAE Central Bank's Wage Protection System interfaces directly with approved software vendors, creating a de facto certification barrier for market entry. Bahrain's Labor Market Regulatory Authority and Oman's Ministry of Labor are implementing comparable digital wage transparency frameworks. Stakeholders must monitor which national regulators mandate direct system integration versus open-data reporting, as this distinction determines vendor development roadmaps and client switching costs.
Market Dynamics
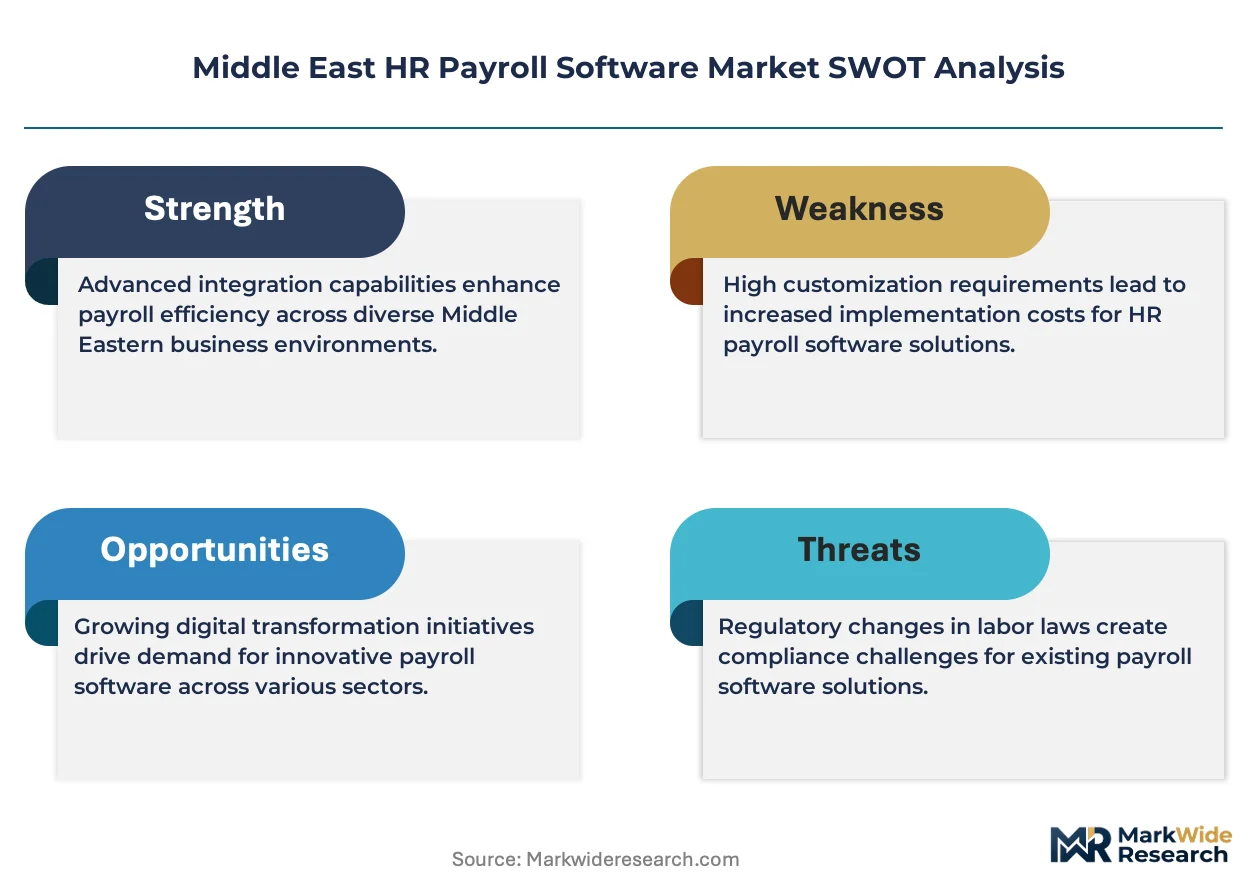
Gulf governments are weaponizing payroll transparency mandates to accelerate workforce localization, forcing employers to replace fragmented HR systems with unified platforms that can generate real-time compliance documentation for labor ministry inspectors.
Growth Catalysts
- Wage Protection System mandates:Saudi Arabia's Ministry of Human Resources and Social Development and the UAE Central Bank now require direct electronic wage disbursement tracking, eliminating cash payroll viability.
- Construction sector digitization:Mega-project developers across the Gulf Cooperation Council are deploying automated payroll to manage multi-national workforces exceeding 50,000 workers per site.
- Cloud migration acceleration:Gulf enterprises are abandoning on-premise server infrastructure for SaaS payroll models that deliver automatic regulatory updates without IT overhead.
Market Restraints
- Data residency requirements:Saudi Arabia's National Cybersecurity Authority mandates local cloud infrastructure, fragmenting vendor architectures and raising deployment costs.
- Legacy system entrenchment:Hydrocarbon sector incumbents operate decade-old ERP payroll modules with deep customization, creating switching friction.
- Interoperability gaps:Bank integration APIs vary across Gulf Cooperation Council jurisdictions, forcing vendors to maintain separate technical stacks per country.
Strategic Opportunities
- Oman and Bahrain digitization waves:These markets are implementing Wage Protection System analogs, creating first-mover advantages for vendors with pre-certified platforms.
- Small and medium enterprise penetration:Per-employee SaaS pricing is unlocking a previously unserved segment that relied on spreadsheet payroll.
- Artificial intelligence and predictive analytics convergence:Vendors are embedding turnover forecasting and compensation benchmarking to differentiate beyond core payroll functionality.
Industry Challenges
- Arabic-English localization complexity:Payroll platforms must handle right-to-left interface rendering, Hijri calendar conversion, and dual-language statutory report generation.
- Zakat and social insurance calculation expertise:Engineering teams lack depth in Islamic tax jurisprudence, slowing product development for Saudi Arabia and Kuwait markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East HR Payroll Software Market |
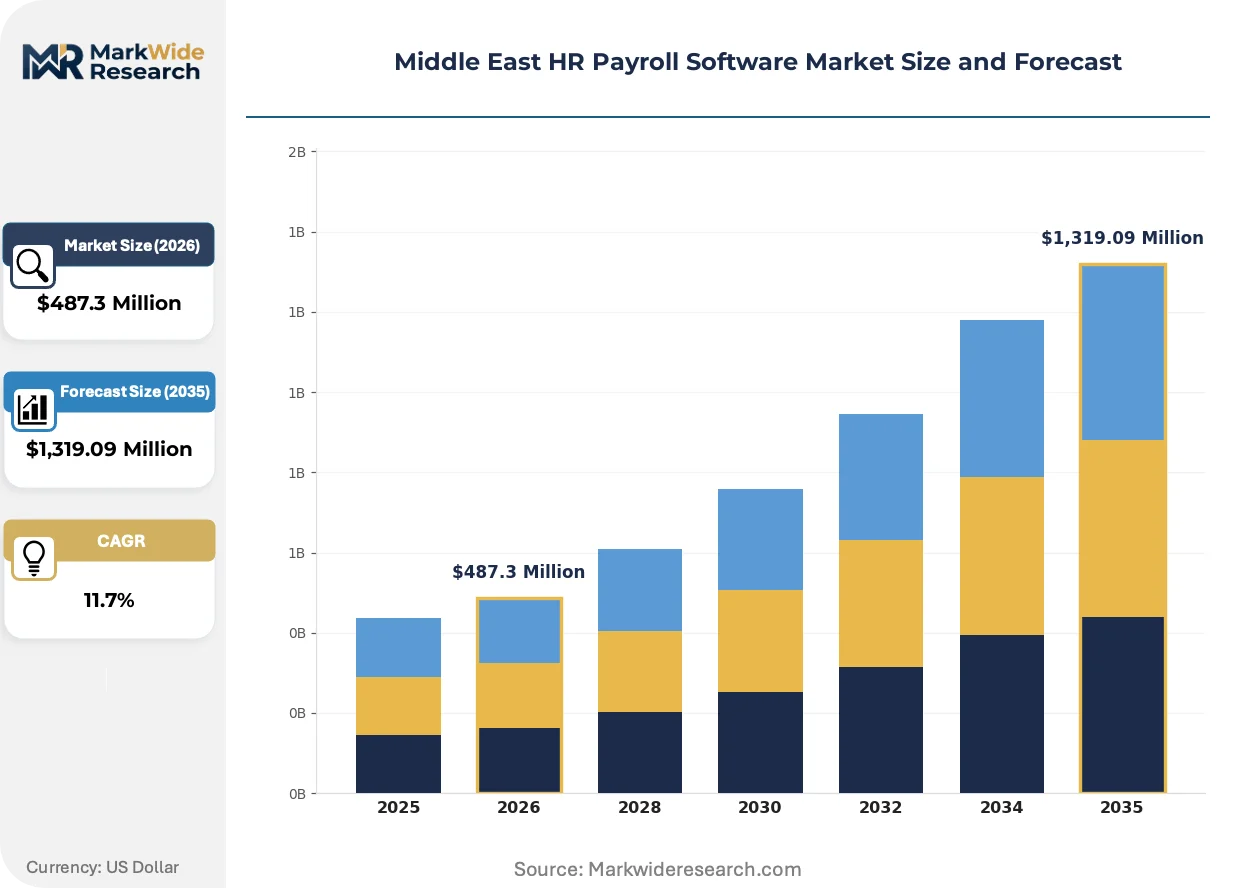
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Customer Type: Small Enterprises, Medium Enterprises, Large Enterprises, Government Organizations Functionality: Payroll Management, Time Tracking, Tax Compliance, Employee Self-Service Industry Vertical: Healthcare, Retail, Manufacturing, Education |
| Companies Covered | Workday, Inc., Decibel 360 Cloud, SAP SE, ZenHR, GulfHR, Oracle Corporation, BambooHR LLC, Bayzat, Automatic Data Processing, Inc. (ADP), Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East HR Payroll Software Market Evolving Landscape
Real-time gross-to-net calculation engines are becoming the baseline competitive requirement, with differentiation shifting toward predictive workforce analytics and embedded compliance automation that anticipates regulatory changes before they take effect.
Embedded banking partnerships between payroll platforms and Gulf financial institutions are electrifying the disbursement workflow. Construction conglomerates and retail chains are adopting these integrated models to eliminate manual bank file uploads and reconciliation delays. This convergence is compressing payment cycles from days to hours while generating new revenue streams through wage-access financial products.
Saudi Arabia's Nitaqat localization quotas are restructuring vendor competitive dynamics. The policy requires granular Saudization ratio reporting that only automated workforce analytics can deliver. Large employers are now procuring platforms specifically for compliance dashboard capabilities, elevating regulatory reporting modules to primary purchase criteria alongside core payroll functionality.
Subscription pricing models are displacing perpetual license structures across the Gulf Cooperation Council. Small and medium enterprises in Dubai and Riyadh are rejecting upfront capital expenditure in favor of monthly per-employee fees that scale with headcount volatility. This shift is most visible in the hospitality and logistics verticals, where seasonal workforce fluctuations make fixed software costs economically untenable.
Middle East HR Payroll Software Market Segmentation
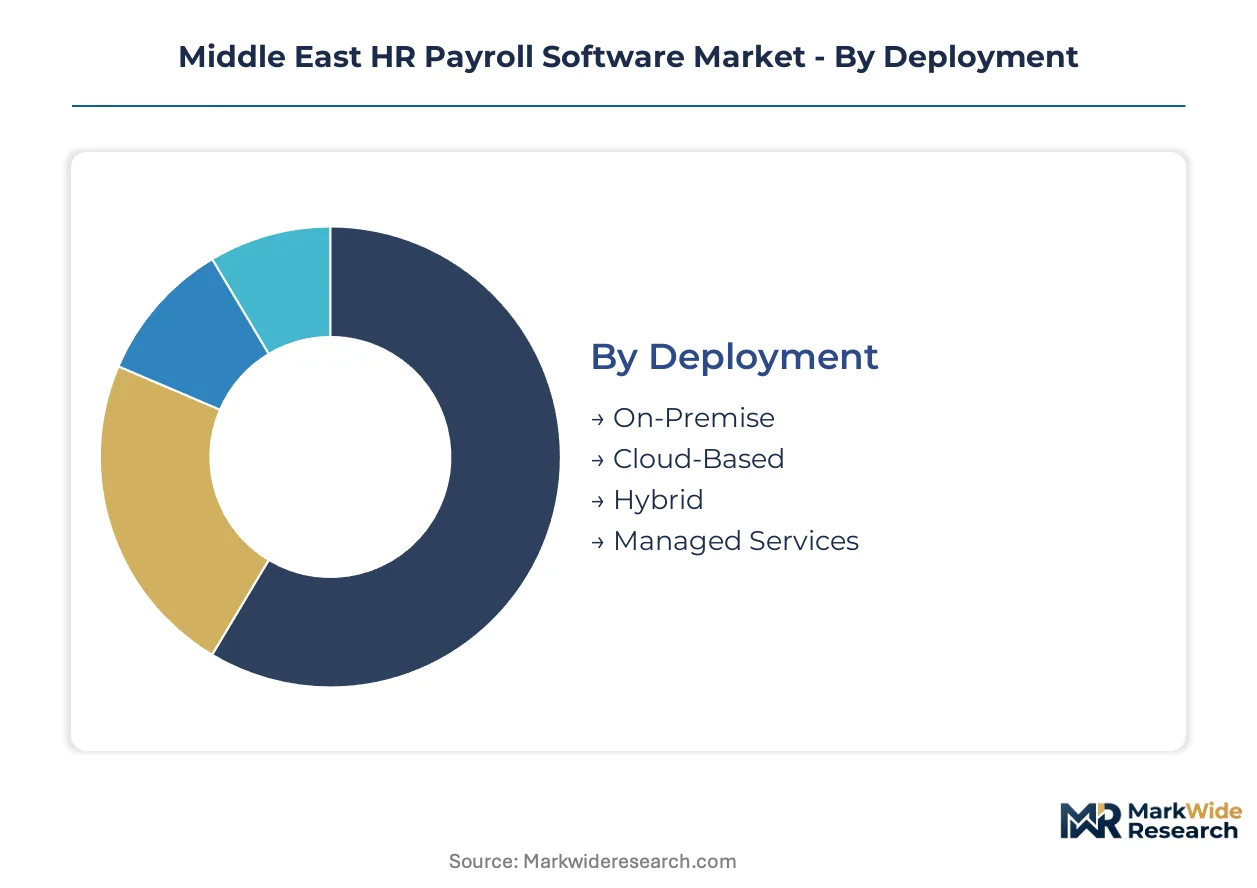
Deployment architecture determines total cost of ownership and regulatory agility for Gulf employers navigating Wage Protection System mandates. Customer scale dictates pricing model acceptance, while functionality depth separates compliance-focused buyers from those seeking workforce analytics convergence.
Deployment:
IT infrastructure strategy and data sovereignty requirements drive vendor selection across Saudi Arabia, UAE, and neighboring Gulf markets.
- Cloud-Based:Multi-tenant SaaS platforms with automatic regulatory patch deployment eliminate on-premise maintenance overhead. Saudi Arabia's National Cybersecurity Authority mandates local cloud infrastructure, fragmenting vendor architectures and raising deployment costs for foreign providers.
- On-Premise:Dedicated server installations within client data centers retain full data control and customization latitude. Hydrocarbon sector incumbents across the Gulf Cooperation Council favor this model for deep ERP integration and legacy workflow preservation.
- Hybrid:Split architectures process sensitive payroll data locally while routing non-critical functions to cloud nodes. Bahrain's Labor Market Regulatory Authority and Oman's Ministry of Labor are implementing digital wage transparency frameworks that favor this intermediate approach.
- Managed Services:Third-party operated platforms where vendors assume full infrastructure and compliance responsibility. Small enterprises in Dubai and Riyadh adopt this model to eliminate dedicated IT payroll staffing.
Cloud-Based leads on scale; Managed Services leads on momentum.
Customer Type:
Headcount volatility and procurement sophistication shape pricing model acceptance and platform complexity requirements.
- Large Enterprises:Organizations exceeding 1,000 employees demand multi-entity payroll consolidation across Gulf jurisdictions. Construction conglomerates managing 50,000-plus worker sites require real-time gross-to-net engines with bank integration APIs.
- Small Enterprises:Firms under 50 employees prioritize per-employee SaaS pricing that eliminates capital expenditure barriers. Hospitality and logistics verticals with seasonal workforce fluctuations find fixed software costs economically untenable.
- Medium Enterprises:Mid-scale employers balance customization needs against implementation speed. These buyers drive demand for pre-configured industry templates with moderate workflow adaptation.
- Government Organizations:Public sector entities require audit trails satisfying labor ministry inspection protocols and granular Saudization ratio reporting for Nitaqat compliance.
Large Enterprises leads on scale; Small Enterprises leads on momentum.
Functionality:
Core automation depth versus predictive capability determines platform stickiness and renewal pricing power.
- Payroll Management:Gross-to-net calculation engines with multi-currency disbursement and statutory deduction automation form the foundational module. This functionality captures the largest margin pool across Gulf vendor offerings.
- Tax Compliance:Zakat, social insurance, and jurisdiction-specific withholding engines command premium pricing during fiscal calendar transitions. Engineering teams lacking Islamic tax jurisprudence depth slow product development for Saudi Arabia and Kuwait markets.
- Time Tracking:Biometric and geofenced attendance integration supports construction sector digitization and remote workforce management. Mega-project developers deploy these tools to coordinate multi-national labor pools.
- Employee Self-Service:Mobile-accessible payslip viewing, leave requests, and document submission reduce HR administrative burden. Arabic-language interfaces and Sharia-compliant leave management modules differentiate regional specialists.
Payroll Management leads on scale; Tax Compliance leads on momentum.
Industry Vertical:
Workforce composition and regulatory exposure determine compliance module prioritization and implementation urgency.
- Healthcare:Complex shift differentials, credential tracking, and Ministry of Health reporting requirements drive specialized configurations. Saudi Arabia's workforce nationalization targets intensify platform procurement for hospital networks.
- Retail:High turnover, commission structures, and seasonal hiring patterns demand flexible per-employee pricing models. Dubai and Riyadh-based retail chains reject upfront capital expenditure in favor of scalable SaaS fees.
- Manufacturing:Multi-site payroll consolidation and production incentive calculations require robust gross-to-net engines. Industrial zones across the Gulf Cooperation Council favor platforms with pre-built manufacturing templates.
- Education:Academic calendar alignment, grant-funded payroll splits, and Ministry of Education compliance reporting shape procurement criteria. Private university networks prioritize platforms with Hijri calendar conversion capabilities.
Healthcare leads on scale; Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expatriate workforces exceeding 15 million across Gulf Cooperation Council states anchor regional demand for automated payroll infrastructure. Saudi Arabia and the UAE concentrate the highest software procurement volumes as localization mandates intensify compliance complexity.
Saudi Arabia
Nitaqat workforce nationalization quotas and mega-project construction drives dominate procurement. The Ministry of Human Resources and Social Development enforces granular Saudization ratio reporting that only integrated platforms can deliver. Riyadh-based hospital networks and Eastern Province industrial zones are replacing manual payroll with cloud systems to satisfy labor ministry inspection protocols.
United Arab Emirates
The UAE Central Bank's Wage Protection System mandates direct electronic wage disbursement tracking, eliminating cash payroll viability. MOHAP compliance requirements for healthcare networks add secondary procurement pressure. Dubai's construction conglomerates managing 50,000-plus worker sites deploy real-time gross-to-net engines with bank integration APIs.
Kuwait
Zakat calculation complexity and social insurance engineering gaps slow foreign vendor penetration. The country's national labor regulator maintains strict data residency requirements for payroll platforms. Kuwait City-based oil sector incumbents favor on-premise ERP modules with deep customization over SaaS alternatives.
Bahrain
The Labor Market Regulatory Authority is implementing digital wage transparency frameworks comparable to UAE and Saudi models. Bahrain's financial services sector generates concentrated demand for multi-currency disbursement automation. Manama-based retail chains and logistics operators are adopting per-employee SaaS pricing to eliminate capital expenditure barriers.
Oman
The Ministry of Labor is rolling out Wage Protection System analogs, creating first-mover advantages for pre-certified platform vendors. Hydrocarbon sector digitization lags regional peers due to legacy system entrenchment. Muscat industrial zones and port logistics clusters represent emerging demand pockets as compliance deadlines approach.
Middle East HR Payroll Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and customer segments. The market exhibits moderate consolidation around enterprise-grade platforms with localized tax engines, while mid-market SaaS entrants fragment the small enterprise tier. Three archetypes dominate: global ERP incumbents with Gulf-specific regulatory modules, regional specialists emphasizing Arabic-language interfaces, and cloud-native challengers attacking per-employee pricing tiers. Competitive moves concentrate on embedded banking partnerships and AI-enabled predictive analytics differentiation.
Within the global ERP tier, SAP SE and Oracle Corporation anchor enterprise positioning through hydrocarbon sector relationships and localized zakat calculation capabilities. ZenHR and Bayzat exemplify the regional specialist archetype, competing on Sharia-compliant leave management and right-to-left interface rendering. GulfHR occupies a position bridging regional customization depth with cloud delivery models. Workday, Inc. and Automatic Data Processing, Inc. (ADP) represent scale-driven SaaS alternatives penetrating mid-market construction and retail verticals.
| Leading Market Players |
|---|
| Workday, Inc. |
| Decibel 360 Cloud |
| SAP SE |
| ZenHR |
| GulfHR |
| Oracle Corporation |
| BambooHR LLC |
| Bayzat |
| Automatic Data Processing, Inc. (ADP) |
| Others |
Value Network & Pricing Analysis
Enterprise-grade compliance certification splits the Middle East HR payroll software market into divergent pricing and sourcing configurations. Premium-tier platforms with pre-certified Wage Protection System integration command sustained margin pools through direct regulator relationships, while commodity SaaS offerings compete on per-employee rates without embedded banking partnerships or automatic regulatory patch deployment.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across deployment tiers. SaaS subscription models with automatic zakat calculation updates dominate enterprise procurement, while per-employee pricing without compliance modules attracts small enterprises. Price differentiation rests on Arabic-language localization depth and Sharia-compliant leave management certification. Cost compression in the mid-market tier is intensifying because cloud-native challengers are undercutting legacy ERP annual maintenance fees. Government organizations exhibit lowest price sensitivity due to audit trail mandates, while hospitality operators face acute margin pressure from seasonal headcount volatility.
Supply Chain Analysis
Reverse-logistics flows for payroll data—archival retrieval, compliance reconstruction, and cross-border workforce reclassification—shape vendor infrastructure investments. Software development concentrates in India, UAE, and Saudi Arabia, with cloud hosting increasingly tethered to local data centers per National Cybersecurity Authority mandates. Raw material dependencies include biometric hardware components, API middleware licenses, and cybersecurity certification services. Single-source vulnerability runs through Saudi cloud infrastructure providers subject to data residency enforcement. Distribution runs through direct enterprise sales teams and regional system integrators serving hydrocarbon and construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East HR payroll software market represents a late-cycle quality story as Nitaqat localization quotas force employers toward premium platforms with granular Saudization reporting capabilities.
For Market Incumbents: Acquire specialized Arabic-language UX engineering teams to defend against cloud-native challengers exploiting interface localization gaps. Incumbent platforms must deepen backward integration into biometric hardware supply chains to secure construction sector mega-project contracts, while embedding predictive workforce analytics to counter margin erosion from commoditized gross-to-net engines. For New Entrants and Emerging Players: Small enterprises in Oman's port logistics clusters represent the most penetrable buyer archetype as Wage Protection System analogs approach enforcement deadlines. New entrants should target per-employee SaaS pricing without upfront implementation fees, leveraging pre-certified compliance modules as the primary go-to-market wedge against legacy ERP incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where data residency requirements fragment vendor architectures and raise deployment costs for foreign providers. Long-term viability favors platforms with localized tax engines and embedded banking partnerships. Acquisition targets should demonstrate direct regulator integration capabilities. Investors should monitor Saudi Ministry of Human Resources certification list updates as inflection indicators for vendor market access.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Banking Partnership | Direct wage disbursement integration with UAE Central Bank Wage Protection System accelerates payment cycles from days to hours. |
| Regulatory Certification Investment | Pre-approved vendor status with Saudi Ministry of Human Resources creates de facto market entry barriers for unqualified competitors. |
| AI-Enabled Predictive Analytics | Turnover forecasting modules differentiate platforms beyond core payroll functionality for Riyadh-based hospital networks. |
| Vertical Specialization | Construction sector templates with biometric geofencing capture mega-project developers managing 50,000-plus worker sites. |
| Hybrid Deployment Architecture | Split local-cloud processing satisfies Bahrain Labor Market Regulatory Authority transparency frameworks without full on-premise burden. |
Research Methodology
Coverage spans Saudi Arabia, UAE, Kuwait, Bahrain, and Oman, with primary inputs from each jurisdiction combined with secondary validation. The research team conducted structured interviews with HR technology procurement officers, labor ministry compliance directors, construction project payroll managers, and cloud platform integration specialists. Secondary sources included SEC filings of listed software vendors, Gulf Cooperation Council labor ministry regulatory circulars, Wage Protection System technical specifications, and hyperscaler cloud infrastructure capex disclosures. Bottom-up deployment counts and top-down enterprise IT spending estimates were triangulated to derive market sizing.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, customer scale tier, functional module depth, and industry vertical regulatory exposure. CAGRs were derived from elasticity-adjusted adoption curves reflecting Wage Protection System mandate enforcement timelines. Forecast inputs incorporated Nitaqat quota trajectory assumptions and cloud migration velocity indices by enterprise size class.
Inputs from labor ministry officials and vendor sales operations were available through the study window; gaps in small enterprise spreadsheet-to-platform transition timing introduce uncertainty bands around adoption curve inflection points. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud infrastructure localization cost trajectories. Practitioners should monitor Saudi National Cybersecurity Authority data center certification announcements and UAE Central Bank Wage Protection System API specification updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Employee Wellness Software Market
Software & Services
BIM Objects Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Job Description Management Software Market
Software & Services
Commissioning Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Intranet Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Feedback Management Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Small Business Marketing Software Market