
 Software As a Service (Saas) Market | 2026-2036
Software As a Service (Saas) Market Size, Share, and Industry Trends Forecast 2026-2036
Software As a Service (Saas) Market Intelligence
Premium enterprise SaaS is decoupling from commodity productivity tools in both pricing architecture and implementation complexity. Salesforce anchors the high-value CRM tier through deep workflow customization and industry-specific data models. Microsoft Corporation dominates the productivity-integrated layer, leveraging Azure backbone synergies to sustain subscription stickiness across mid-market accounts.
Software as a Service denotes cloud-hosted applications delivered via subscription licensing, where vendors manage infrastructure, security patching, and feature updates through multi-tenant architectures operating on shared compute pools. The model eliminates on-premise server capital expenditure while shifting IT expenditure to operational budgets with usage-scaled pricing. Public Cloud deployment leads volume adoption among startups and digital-native enterprises, yet Hybrid Cloud configurations capture the fastest expansion as financial institutions and government agencies mandate data residency controls. Customer Relationship Management solutions occupy the deepest margin pools due to high switching costs and proprietary data accumulation, while Human Capital Management competes aggressively on implementation speed and payroll integration density.
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification framework shape product roadmaps for any SaaS vendor serving European enterprises, forcing investment in explainability tooling and regional data centers. The SEC's cybersecurity disclosure rules and HIPAA safeguards for US healthcare data create parallel compliance obligations that differentiate vendors with certified audit trails from those lacking enterprise-grade governance. Stakeholders must monitor how sovereign cloud requirements proliferate beyond Europe into Asia-Pacific jurisdictions, as this fragmentation determines which vendors can operate across regulated industries without architectural overhaul.
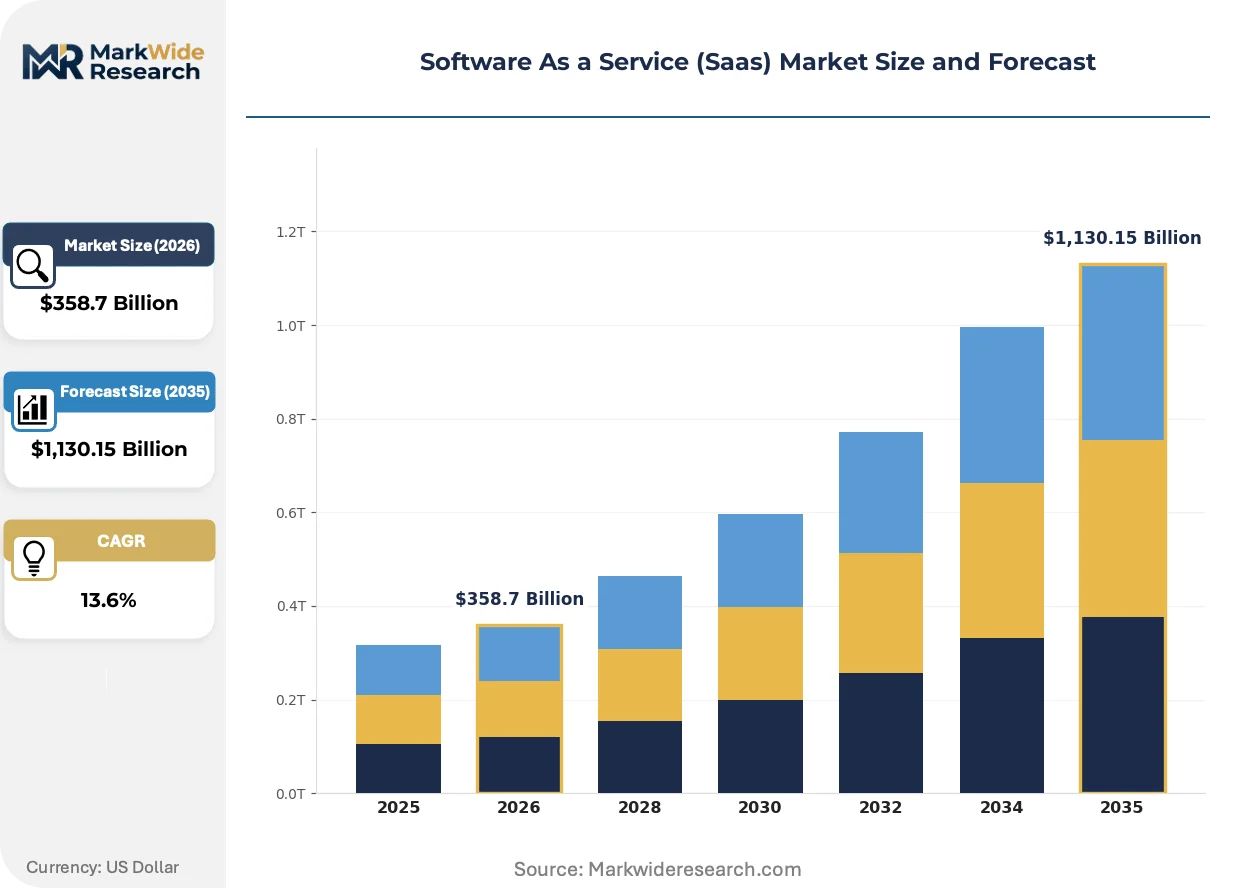
Market Dynamics
Sovereign data requirements are fragmenting SaaS architectures as EU AI Act risk classifications and GDPR enforcement force vendors to deploy region-specific infrastructure rather than centralized global instances.
Growth Catalysts
- GDPR Enforcement:European data protection authorities are mandating audit-ready data lineage tools, compelling enterprises to replace shadow IT with compliant SaaS procurement.
- Healthcare Cloud Migration:HIPAA-covered entities are abandoning on-premise patient management systems for cloud-hosted alternatives with automated security patching.
- Industrial ERP Modernization:Germany's Mittelstand manufacturers in Munich and Stuttgart industrial clusters are retiring legacy SAP instances for modular cloud ERP with API-first integration.
Market Restraints
- Data Residency Compliance Costs:Multi-tenant architectures require expensive regional data center replication to satisfy divergent national sovereignty laws.
- Vendor Concentration Risk:Hyperscaler cloud infrastructure dependency creates single-point-of-failure exposure for SaaS vendors operating on AWS, Azure, or Google Cloud.
- API Rate Limiting:Platform dependency on third-party integration endpoints restricts workflow customization depth for mid-market customers.
Strategic Opportunities
- Edge SaaS for Manufacturing:Latency-sensitive predictive maintenance applications in German automotive plants require localized compute with cloud orchestration.
- CSRD Reporting Automation:EU Corporate Sustainability Reporting Directive mandates are creating demand for ESG data collection SaaS with automated disclosure workflows.
- Federated Learning Architectures:Convergence of differential privacy techniques with multi-party computation enables cross-border analytics without raw data transfer.
Industry Challenges
- Observability Engineering Talent:Cloud-native monitoring and SRE skill shortages delay deployment timelines for enterprise customers requiring 99.99% uptime SLAs.
- Legacy System Integration:COBOL-era core banking and mainframe ERP systems resist API abstraction, extending implementation cycles for financial services SaaS deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software As a Service (Saas) Market |
| Market Size in 2026 | $358.7 Billion |
| Market Size in 2035 | $1,130.15 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Customer Relationship Management, Enterprise Resource Planning, Human Capital Management, Supply Chain Management, Content Management Application: Sales Automation, Workforce Management, Financial Analysis, Project Collaboration, Marketing Automation End User Industry: Information Technology Firms, Financial Institutions, Educational Institutions, Telecommunication Providers, Government Agencies |
| Companies Covered | Salesforce, Microsoft Corporation, Oracle Corporation, ServiceNow, SAP SE, Adobe Inc., IBM Corporation, Google LLC, Atlassian Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software As a Service (Saas) Market Strategic Shifts & Innovations
Agentic AI capabilities are compressing the traditional SaaS configuration cycle from months to days, forcing vendors to rearchitect around autonomous workflow execution rather than static feature modules.
Large language model orchestration layers are unifying previously siloed SaaS applications into conversational interfaces. Enterprise buyers in professional services and legal sectors are piloting natural language query systems that span CRM, document management, and billing platforms. This unification is collapsing the traditional best-of-breed integration market by embedding connectivity into the interaction layer itself.
The EU AI Act's risk-classification framework is mandating explainability documentation for high-risk automated decision systems. SaaS vendors serving credit scoring, recruitment, and healthcare diagnostics must now embed algorithmic audit trails and human-in-the-loop checkpoints. German automotive suppliers and French healthcare networks are demanding pre-certified compliance modules before contract signature.
Consumption-based pricing models are displacing seat-based subscriptions in data-intensive verticals. Infrastructure monitoring and data warehouse vendors now meter by query volume and storage throughput rather than user count. This shift is most pronounced among Series C software companies in San Francisco and Berlin, where finance teams prioritize cost predictability over unlimited access.
Software As a Service (Saas) Market Segmentation
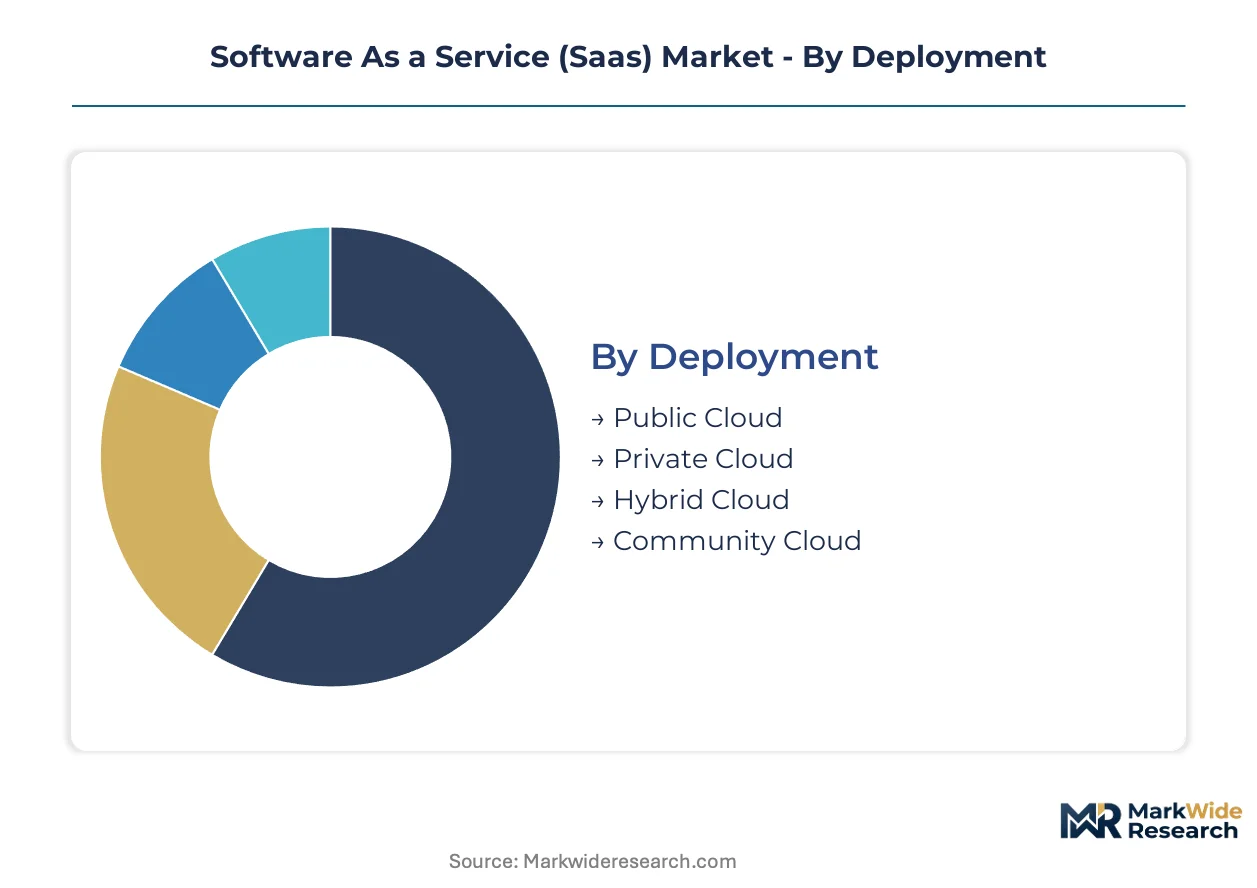
SaaS market segmentation reveals how deployment architecture, solution specialization, and industry verticals create distinct commercial zones with diverging margin profiles and switching-cost economics. Understanding these boundaries helps vendors allocate R&D resources and pricing power effectively.
Deployment:
The customization-vs-standardization spectrum runs from fully managed multi-tenant instances to sovereign infrastructure with client-controlled security patching.
- Public Cloud:Shared compute pools with vendor-managed infrastructure eliminate capital expenditure for startups and digital-native enterprises. Demand concentrates among venture-backed software companies in Berlin and San Francisco seeking elastic scaling without data center procurement cycles.
- Hybrid Cloud:Workload orchestration across on-premise and cloud environments satisfies financial institutions in Frankfurt and healthcare networks in Munich requiring patient data residency with burst compute flexibility. Expansion is steepest here as EU AI Act risk classifications mandate explainability tooling that straddles both environments.
- Private Cloud:Single-tenant deployments with dedicated hardware serve defense contractors and central banks with air-gapped security requirements.
- Community Cloud:Shared infrastructure among organizations with common compliance obligations, such as research universities under identical federal funding rules.
Most installed capacity flows through Public Cloud configurations. Expansion is steepest in Hybrid Cloud as regulated industries reconcile agility mandates with sovereignty enforcement.
Solution Type:
Margin concentration tracks with data gravity and workflow entrenchment, separating high-switching-cost systems from commodity productivity layers.
- Customer Relationship Management:Proprietary data accumulation and deep workflow customization create defensive moats. German automotive suppliers in Stuttgart anchor demand for industry-specific data models with predictive lead scoring.
- Enterprise Resource Planning:Modular cloud ERP with API-first integration is displacing legacy SAP instances among Mittelstand manufacturers. Financial analysis modules and supply chain orchestration drive renewal rates above other solution categories.
- Human Capital Management:Payroll integration density and rapid implementation cycles compete aggressively on speed-to-value rather than data lock-in.
- Supply Chain Management:Real-time visibility tools with EDI connectivity serve logistics operators managing multi-modal freight networks.
- Content Management:Document collaboration with version control and compliance archiving supports legal and professional services firms with audit-ready retention policies.
Revenue gravity centers on Customer Relationship Management due to accumulated proprietary data. Fastest share gains are occurring in Enterprise Resource Planning as industrial clusters modernize legacy infrastructure.
Application:
Functional depth determines pricing architecture, with revenue operations commanding premium tiers over administrative automation.
- Sales Automation:Pipeline forecasting and commission calculation engines with CRM integration serve B2B technology vendors in London and Tel Aviv. Expansion is most rapid as AI-powered lead scoring reduces manual qualification overhead.
- Marketing Automation:Campaign orchestration across email, social, and paid channels with attribution modeling supports e-commerce operators and SaaS companies seeking product-led growth mechanics.
- Workforce Management:Shift scheduling and labor compliance tools with union rule engines serve retail and hospitality chains with distributed hourly workforces.
- Financial Analysis:Consolidation and planning tools with multi-entity reporting support private equity portfolio companies and multinational subsidiaries.
- Project Collaboration:Task management with resource allocation and time tracking serves professional services firms billing by engagement.
Deployment volume concentrates in Sales Automation among technology vendors. Steepest expansion is occurring in Marketing Automation as performance marketing budgets shift from agency retainers to in-house platform subscriptions.
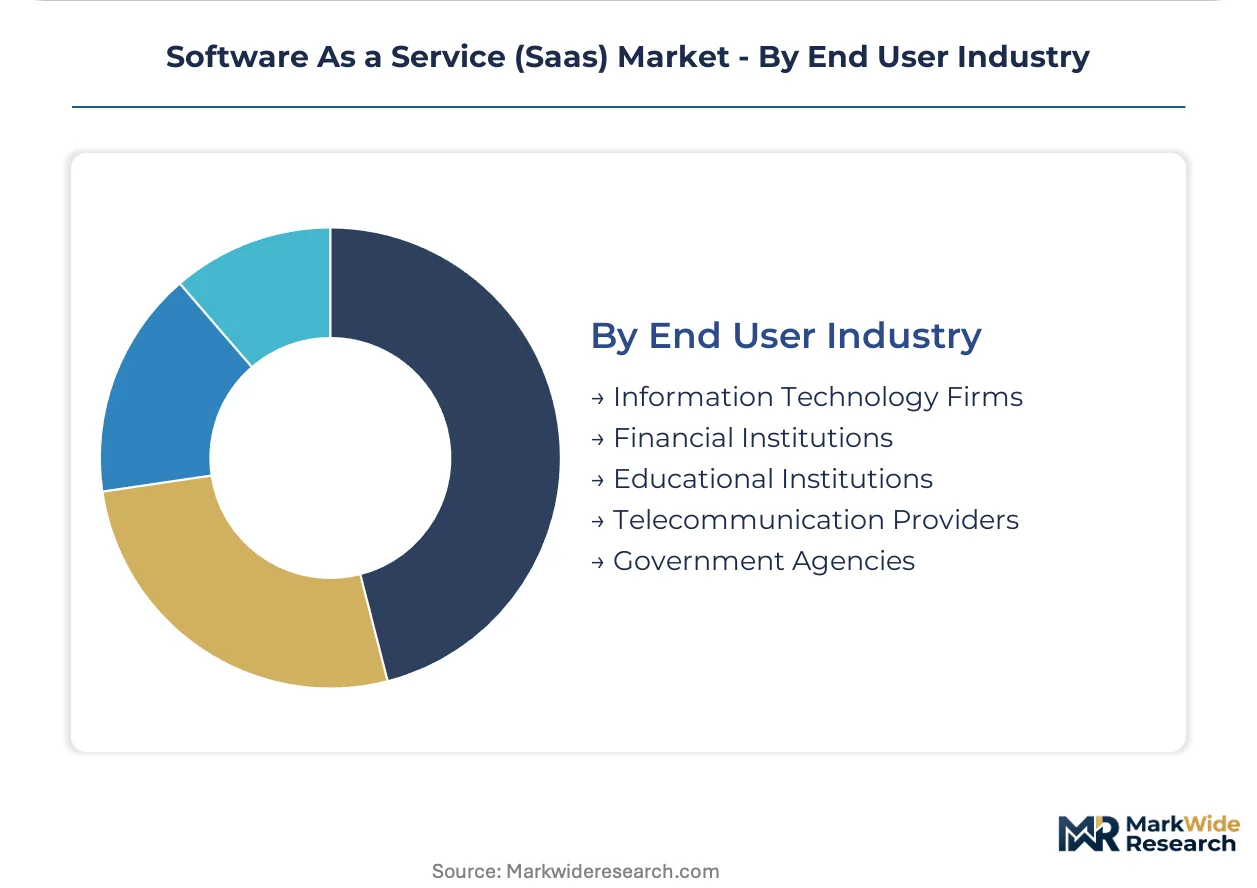
End User Industry:
Compliance burden and procurement sophistication separate enterprise-grade deployments from self-serve adoption.
- Financial Institutions:Basel III capital reporting and SEC cybersecurity disclosure rules mandate certified audit trails and regional data residency. Frankfurt-based insurers and London investment banks drive demand for sovereign cloud configurations.
- Government Agencies:FedRAMP and GDPR-compliant procurement with classified data handling requirements favors vendors with pre-certified compliance modules.
- Information Technology Firms:Developer tooling integration and API-native architectures support software companies with internal platform engineering teams.
- Educational Institutions:Student information systems with financial aid integration and learning management connectivity serve universities with complex enrollment cycles.
- Telecommunication Providers:Network operations center integration and subscriber data management support operators with 5G infrastructure deployments.
Contract value concentrates in Financial Institutions due to compliance complexity. Fastest expansion is occurring in Government Agencies as digital service mandates accelerate cloud procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native engineering talent concentrates in the San Francisco Bay Area, Tel Aviv's cybersecurity corridor, and Bangalore's enterprise software parks, anchoring regional SaaS development capacity across three continents.
United States
HIPAA-covered healthcare networks in Boston and the Research Triangle accelerate cloud migration for patient management systems. SEC cybersecurity disclosure rules mandate certified audit trails for SaaS procurement in financial services. Silicon Valley's venture capital density funds Series C infrastructure monitoring vendors adopting consumption-based pricing models.
Germany
Mittelstand manufacturers in Stuttgart and Munich industrial clusters drive modular ERP replacement of legacy SAP instances. EU AI Act risk classifications force explainability tooling investment for automated decision systems. Berlin's SaaS startup ecosystem specializes in CSRD reporting automation for ESG disclosure mandates.
United Kingdom
London's investment banking sector demands sovereign cloud configurations for Basel III capital reporting workflows. GDPR enforcement by the Information Commissioner's Office compels audit-ready data lineage replacement of shadow IT. Fintech clusters in Manchester and Edinburgh pilot federated learning architectures for cross-border analytics compliance.
India
Bangalore's enterprise software parks and Hyderabad's IT corridors anchor offshore development centers for global SaaS vendors. The central bank's data localization directives push financial institutions toward hybrid cloud deployments. Pune's automotive suppliers adopt edge SaaS for latency-sensitive predictive maintenance in connected manufacturing.
Japan
Tokyo's financial institutions require regional data residency for core banking system modernization under METI cloud security guidelines. Osaka's pharmaceutical networks migrate clinical trial management to compliant SaaS platforms. Nagoya's automotive OEMs demand pre-certified AI explainability modules for supply chain risk scoring applications.
Software As a Service (Saas) Market Key Industry Players
Top-tier vendors anchor the premium enterprise tier with deep workflow customization and proprietary data models, while mid-market specialists compete on implementation speed and API integration density. The vendor base stratifies across three functional layers: productivity-integrated platforms, industry-specific vertical solutions, and infrastructure-monitoring utilities. Two dominant competitive moves define current positioning: sovereign cloud infrastructure expansion to satisfy data residency mandates, and agentic AI capability acquisition to compress configuration cycles.
Within the hyperscaler-backed tier, Salesforce, Microsoft Corporation, and SAP SE exemplify divergent strategic archetypes. Salesforce occupies the high-value CRM position through accumulated proprietary data gravity and predictive lead scoring modules. Microsoft Corporation leverages Azure backbone synergies to sustain subscription stickiness across productivity-integrated mid-market accounts. SAP SE anchors industrial ERP modernization among German manufacturers through API-first modular architectures. Each represents a distinct path for defending margin pools as consumption-based pricing displaces seat-based subscriptions in data-intensive verticals.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Corporation |
| Oracle Corporation |
| ServiceNow |
| SAP SE |
| Adobe Inc. |
| IBM Corporation |
| Google LLC |
| Atlassian Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into hyperscaler infrastructure anchors both supply resilience and pricing power for SaaS vendors serving regulated European enterprises. This backward integration choice forces vendors to absorb regional data center replication costs while commanding premium tiers for sovereign cloud configurations.
Pricing Analysis
The bundled-vs-unbundled service split separates consumption-based metering from traditional seat-based subscriptions. Pricing stratifies across premium, standard, and economy tiers based on compliance certification level and customization depth. Cost compression in the mid-market tier is intensifying because API rate limiting from hyperscaler dependencies restricts workflow differentiation. Healthcare networks and financial institutions in Frankfurt demonstrate the least price sensitivity due to mandatory audit trail requirements, while seed-stage startups in Berlin exhibit the highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and French healthcare networks mandate multi-cloud qualification across AWS, Azure, and Google Cloud. Compute capacity concentrates in the United States, Ireland, and Germany, with specialized GPU clusters anchoring in Taiwan and South Korea. Raw material dependencies span silicon wafers, rare earth elements for data center cooling, and submarine cable bandwidth. Single-source vulnerability runs through Taiwan Semiconductor's advanced node production. Distribution runs through direct enterprise sales teams with certified implementation partners for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as enterprise buyers shift demand toward pre-certified compliance modules and explainability tooling that command sustained premium pricing.
For Market Incumbents: Hedge against hyperscaler concentration risk by qualifying secondary cloud infrastructure in Singapore and Dubai. Invest in captive sovereign cloud deployments to defend margin pools as GDPR enforcement accelerates regional data center mandates. Prioritize acquisition of differential privacy startups to anchor federated learning capabilities before EU AI Act deadlines tighten.
For New Entrants and Emerging Players: Channel partners specializing in Mittelstand manufacturing integration represent the fastest path to revenue. Target Stuttgart automotive suppliers with modular ERP replacement needs where legacy SAP fatigue creates immediate white space. Pursue CSRD reporting automation for Berlin-based sustainability consultancies seeking automated ESG disclosure workflows.
For Investors and Strategic Acquirers: Consolidation pressure builds where vendor count exceeds procurement capacity in sovereign cloud infrastructure. The five-to-ten-year viability window favors platforms with pre-certified EU AI Act compliance modules and established regional data center footprints. Monitor hyperscaler capex allocation shifts as the signal indicating which vendors will capture burst compute demand from financial services modernization.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Expansion | Regional data center deployment satisfies GDPR and EU AI Act mandates for Frankfurt insurers. |
| Agentic AI Acquisition | Autonomous workflow capabilities compress implementation cycles for Stuttgart automotive suppliers. |
| API-First Platform Integration | Modular connectivity accelerates legacy SAP displacement among Munich manufacturers. |
| Compliance Certification Investment | Pre-certified explainability tooling unlocks healthcare procurement in Boston and Tokyo. |
| Edge SaaS Partnership | Localized compute orchestration captures predictive maintenance demand from Nagoya automotive OEMs. |
Research Approach
Bottom-up enterprise procurement modeling reconciled against top-down hyperscaler capacity tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Berlin, San Francisco, and Bangalore combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation across these sources ensures demand-side adoption patterns align with supply-side infrastructure deployment.
Historical trendline analysis of subscription revenue trajectories and deployment architecture shifts informed the projection framework. Segmentation dimensions modeled span deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to each segment, with specific inputs including EU AI Act implementation timelines and HIPAA-covered entity cloud migration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sovereign cloud requirement proliferation and hyperscaler pricing power concentration. Deviation in GDPR enforcement intensity or EU AI Act risk classification scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Non-Profit Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
VFX Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Server Management Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Childcare Management Software Market
Software & Services
Global Municipal Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Global Email Software Market
Software & Services
Live Software Market
Software & Services
Global Note Taking App Market
Software & Services
Global Recipe Apps Market