
 Foot and Mouth Disease (FMD) Vaccine Market | 2026-2036
Foot and Mouth Disease (FMD) Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Foot and Mouth Disease (FMD) Vaccine Market Analysis
India is reconfiguring regional vaccine supply dynamics through expanded public-sector manufacturing partnerships. Boehringer Ingelheim International GmbH leverages multi-site production networks across Europe and Asia to sustain consistent antigen supply for endemic markets. Indian Immunologicals Limited anchors domestic self-sufficiency through its Hyderabad-based bulk manufacturing facility, while Biogénesis Bagó competes across Latin America with specialized trivalent and polyvalent formulations calibrated to local serotype prevalence.
Foot and Mouth Disease vaccines are biologic preparations containing inactivated or attenuated viral antigens designed to induce protective neutralizing antibodies against FMD virus serotypes O, A, Asia 1, SAT 1-3, and C, with potency standardized by international reference sera and typically requiring cold-chain storage at two to eight degrees Celsius. Their primary purpose is to prevent clinical disease in cloven-hoofed livestock and to support national freedom-from-disease status required for international trade in animals and animal products. Inactivated vaccine formulations dominate current procurement volumes due to established efficacy records and regulatory familiarity, though DNA vaccine platforms represent the fastest-growing development pipeline as researchers pursue differentiation through marker vaccine compatibility and DIVA-compliant serological surveillance. Intramuscular administration routes retain the largest installed base across cattle and pig operations, while oral delivery formats are gaining structural traction in extensive grazing systems where mustering for injectable dosing proves logistically prohibitive.
OIE-WOAH standards, national veterinary regulator protocols in India under CDSCO-aligned import frameworks, and USDA-APHIS foreign animal disease preparedness directives collectively shape product registration pathways and cross-border shipment eligibility for FMD vaccines. These frameworks determine antigen strain selection, potency testing requirements, and emergency use authorization mechanisms that manufacturers must navigate for market access. Stakeholders must monitor serotype shift patterns and evolving DIVA policy adoption to align R&D portfolios with the next generation of trade-compatible vaccination strategies.
Market Dynamics
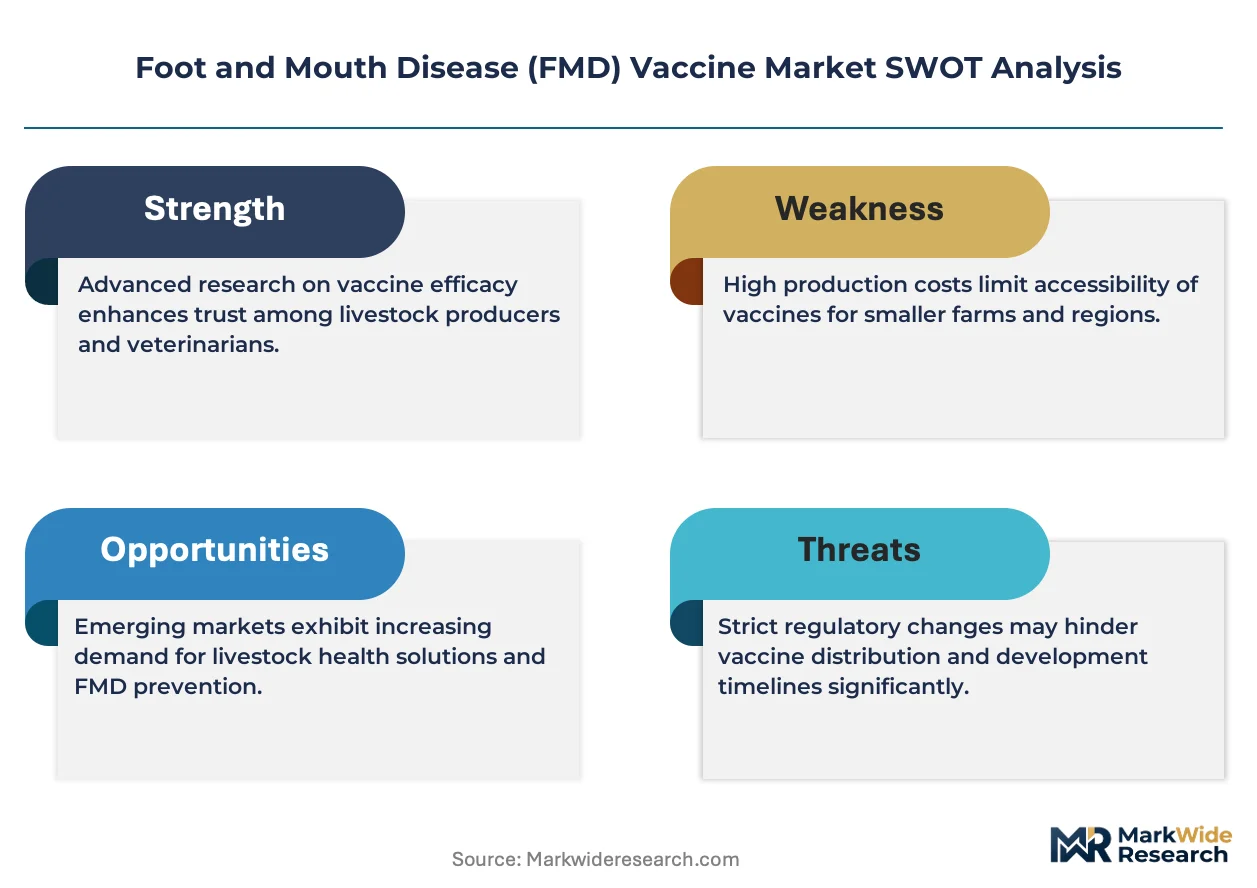
Recombinant subunit and DNA vaccine platforms are compressing the dominance of conventional inactivated formulations across national control programs, forcing manufacturers to reconfigure R&D pipelines and antigen production networks to maintain procurement eligibility.
Growth Catalysts
- India's PLI scheme for veterinary biologics:Domestic manufacturing incentives under the Production Linked Incentive scheme are expanding public-sector bulk antigen capacity and reducing import dependency for regional eradication campaigns.
- DNA vaccine platform maturation:Marker vaccine compatibility and DIVA-compliant serological surveillance capabilities are accelerating platform adoption in trade-sensitive livestock sectors seeking freedom-from-disease certification.
- Southeast Asian government procurement:National livestock immunization programs across Vietnam, Thailand, and Indonesia are scaling centralized vaccine purchases to meet OIE-WOAH progressive control pathway milestones.
Market Restraints
- Cold-chain infrastructure gaps:Two-to-eight-degree Celsius storage requirements create distribution bottlenecks in extensive grazing systems across sub-Saharan Africa and Central Asia where last-mile refrigeration remains unreliable.
- Serotype complexity:Seven distinct FMDV serotypes with multiple subtypes necessitate polyvalent formulation development, increasing antigen matching costs and complicating inventory management for manufacturers serving heterogeneous endemic zones.
- Regulatory fragmentation:Divergent potency testing protocols and strain selection criteria between OIE-WOAH, USDA-APHIS, and national regulators like CDSCO create redundant registration burdens and delay market access timelines.
Strategic Opportunities
- Oral delivery format expansion:Bait-based vaccination systems for wild ungulate reservoirs and extensive cattle operations in Brazil's Pantanal and Argentina's pampas regions are opening procurement channels beyond injectable formats.
- Latin American regional harmonization:Pan-American Foot-and-Mouth Disease Center (PANAFTOSA) initiatives are aligning serotype surveillance and vaccine matching protocols across Mercosur members, simplifying multi-country tender participation.
- Biogeneric subunit manufacturing:Biosimilar recombinant antigen production using microbial expression systems is lowering capital barriers for mid-scale entrants targeting price-sensitive public-sector tenders in South Asia.
Industry Challenges
- DIVA assay standardization:Inconsistent non-structural protein antibody test validation across reference laboratories complicates post-vaccination monitoring and trade certification documentation for export-oriented producers.
- Antigen bank maintenance:Strategic reserve stockpiling requirements for emergency outbreak response strain national veterinary budgets and create demand forecasting volatility for manufacturers dependent on scheduled procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot and Mouth Disease (FMD) Vaccine Market |
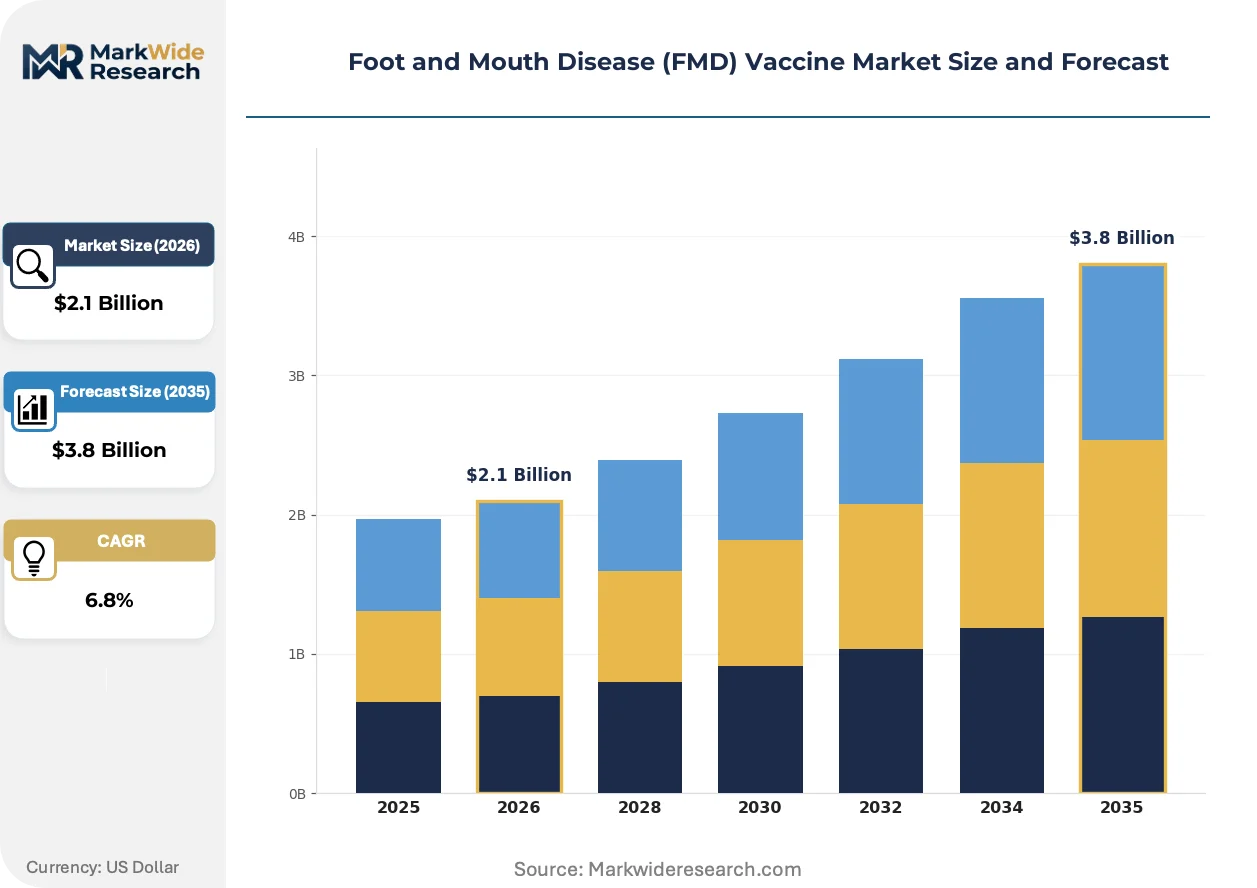
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccine, Live Attenuated Vaccine, Subunit Vaccine, DNA Vaccine Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Target Animal: Cattle, Goats, Sheep, Pigs Distribution Channel: Veterinary Clinics, Online, Pharmacies, Distributors |
| Companies Covered | Boehringer Ingelheim International GmbH, Merck & Co., Inc., Indian Immunologicals Limited, Biogénesis Bagó, Zoetis Inc., Godrej Agrovet Limited, Ceva Santé Animale S.A., Elanco Animal Health Incorporated, VECOL S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot and Mouth Disease (FMD) Vaccine Market Emerging Trajectories
Platform biotechnology advances and regulatory pressure for trade-compatible vaccination are converging to reshape product development priorities and procurement specifications across endemic and FMD-free zones.
Recombinant subunit vaccines using baculovirus expression systems are virtualizing the traditional reliance on live virus propagation in biosafety level three facilities. Large-scale cattle operations in Brazil and feedlot systems in Argentina are piloting these platforms to reduce production biosecurity costs. The technology is virtualizing capital-intensive manufacturing infrastructure, enabling decentralized antigen production and shortening supply lead times for regional emergency response.
CDSCO's alignment with OIE-WOAH standards for veterinary biologics import frameworks is streamlining strain update approvals for international manufacturers seeking Indian market access. The regulatory convergence reduces redundant potency testing requirements and accelerates emergency use authorizations during serotype shift events. Domestic manufacturers like Indian Immunologicals Limited are responding by upgrading Hyderabad facilities to meet dual national-international certification standards.
Public-sector tender consolidation is compressing supplier fragmentation across Southeast Asian veterinary services. National livestock departments in Vietnam and Thailand are aggregating provincial procurement into centralized multi-year supply agreements with volume guarantees and performance-linked payment terms. This purchasing model shift is most visible in Indonesia's transmigration zone cattle development programs, where single-source contracting is replacing fragmented district-level acquisitions.
Foot and Mouth Disease (FMD) Vaccine Market Segmentation
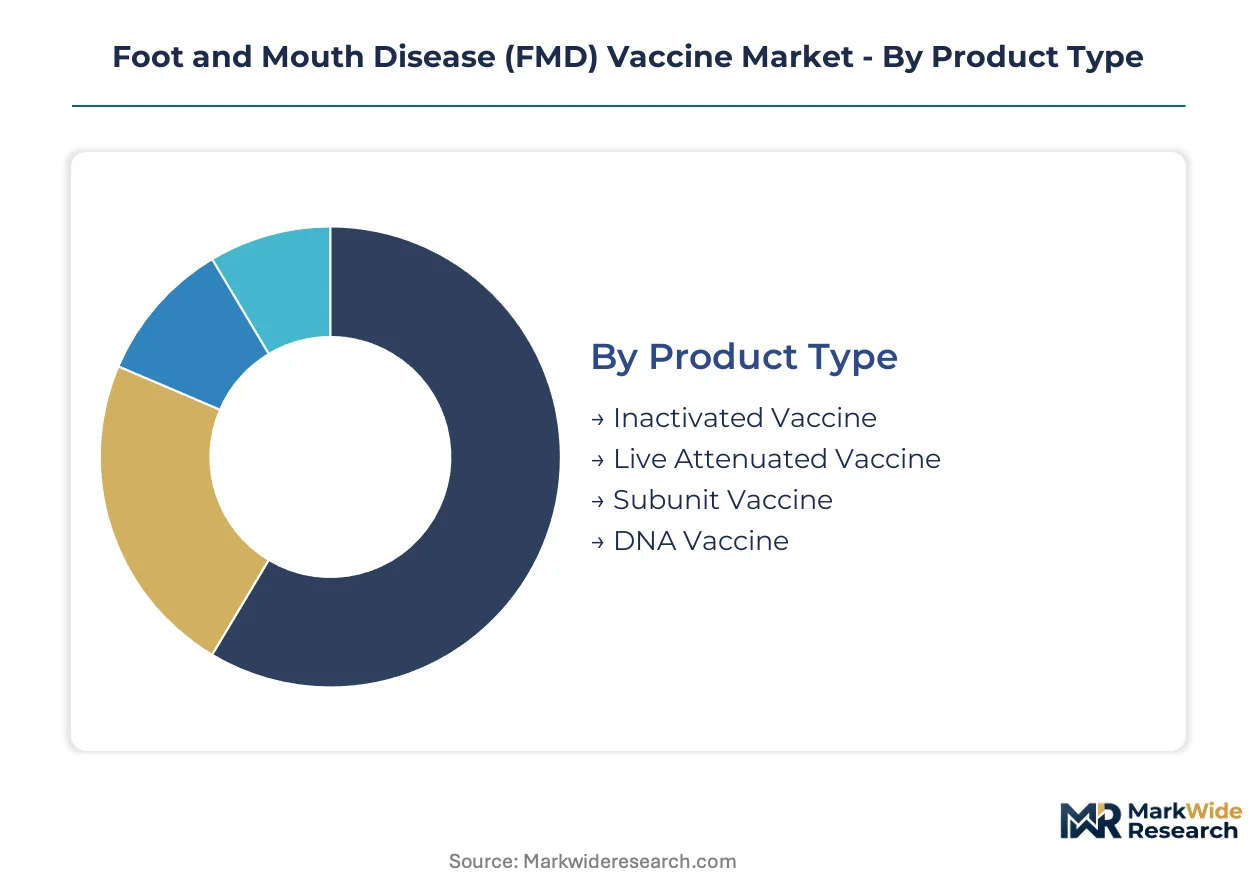
Segmentation in the FMD vaccine market reveals how procurement specifications, delivery logistics, and animal husbandry practices fragment demand across incompatible product categories. Manufacturers must configure antigen production, cold-chain packaging, and dosing equipment to serve distinct customer workflows without cross-leveraging infrastructure.
Product Type:
After-sales service intensity varies sharply by platform maturity—inactivated formulations require minimal technical support while DNA vaccine deployments demand sustained veterinary training and assay validation assistance.
- Inactivated Vaccine:Viral particles chemically or physically neutralized to destroy infectivity while preserving immunogenic surface epitopes. Demand concentrates in Indian government tenders and Brazilian federal procurement where established regulatory dossiers accelerate emergency approvals. Cold-chain dependency and periodic booster requirements create recurring service touchpoints for distributor field teams.
- DNA Vaccine:Plasmid vectors encoding FMDV capsid proteins delivered without viral components, enabling DIVA-compliant serological differentiation. Argentina's feedlot sector and Thailand's progressive control zones are adopting these platforms fastest where trade certification requirements dominate purchasing criteria. Technical support intensity peaks during initial herd immunity establishment and NSP antibody test interpretation.
- Live Attenuated Vaccine:Temperature-sensitive formulations with residual virulence risk, restricted to specific endemic corridors with limited export orientation.
- Subunit Vaccine:Purified recombinant antigens produced in baculovirus or microbial expression systems, gaining traction in Vietnam's dairy cooperatives seeking reduced biosafety handling costs.
By volume, Inactivated Vaccine leads. By growth pace, DNA Vaccine is ahead.
Administration Route:
Cost tier stratification separates capital-intensive injectable infrastructure from low-unit-cost oral delivery systems suited to extensive grazing economics.
- Intramuscular:Needle-based delivery into skeletal muscle mass, yielding superior antigen presentation and duration of immunity. Indonesian commercial cattle operations and Indian organized dairy clusters maintain the largest installed base of syringe-based vaccination teams. Equipment sterilization protocols and skilled labor requirements elevate total cost of ownership relative to alternative routes.
- Oral:Bait-encapsulated or drinking-water formulations enabling mass treatment without animal restraint. Brazil's Pantanal wetland ranchers and Argentina's pampas extensive systems are expanding procurement fastest where mustering costs exceed vaccine expenditure. Delivery system simplicity compresses per-dose service overhead to minimum thresholds.
- Subcutaneous:Dermal deposition beneath skin layers, common in small ruminant operations with limited muscle mass.
- Intranasal:Mucosal administration stimulating local IgA responses, piloted in Vietnamese pig confinement facilities seeking reduced needle-stick injuries.
By volume, Intramuscular leads. By growth pace, Oral is gaining share fastest.
Target Animal:
Application-specific potency requirements and serotype prevalence patterns fragment antigen formulation strategies across species lines.
- Cattle:The dominant commercial segment requiring highest-valency formulations against O, A, and Asia 1 serotypes. Indian government programs and Brazilian federal campaigns concentrate procurement volume in multi-million dose annual tenders. Breed-specific susceptibility variations and lactation-stage safety constraints shape technical service protocols.
- Pigs:Susceptible to distinct FMDV strains with accelerated transmission dynamics in confinement settings. Thailand's integrated pork operations and Vietnam's commercial pig zones are expanding trivalent vaccine purchases where SAT serotype cross-protection becomes relevant. Vaccination timing relative to slaughter weight targets creates recurring veterinary consultation demand.
- Sheep:Smaller body mass requiring dose-adjusted formulations, prevalent in Central Asian transhumant systems.
- Goats:Hardy small ruminants in arid grazing zones where injectable delivery competes with oral alternatives for cost efficiency.
By volume, Cattle leads. By growth pace, Pigs shows steepest expansion trajectory.
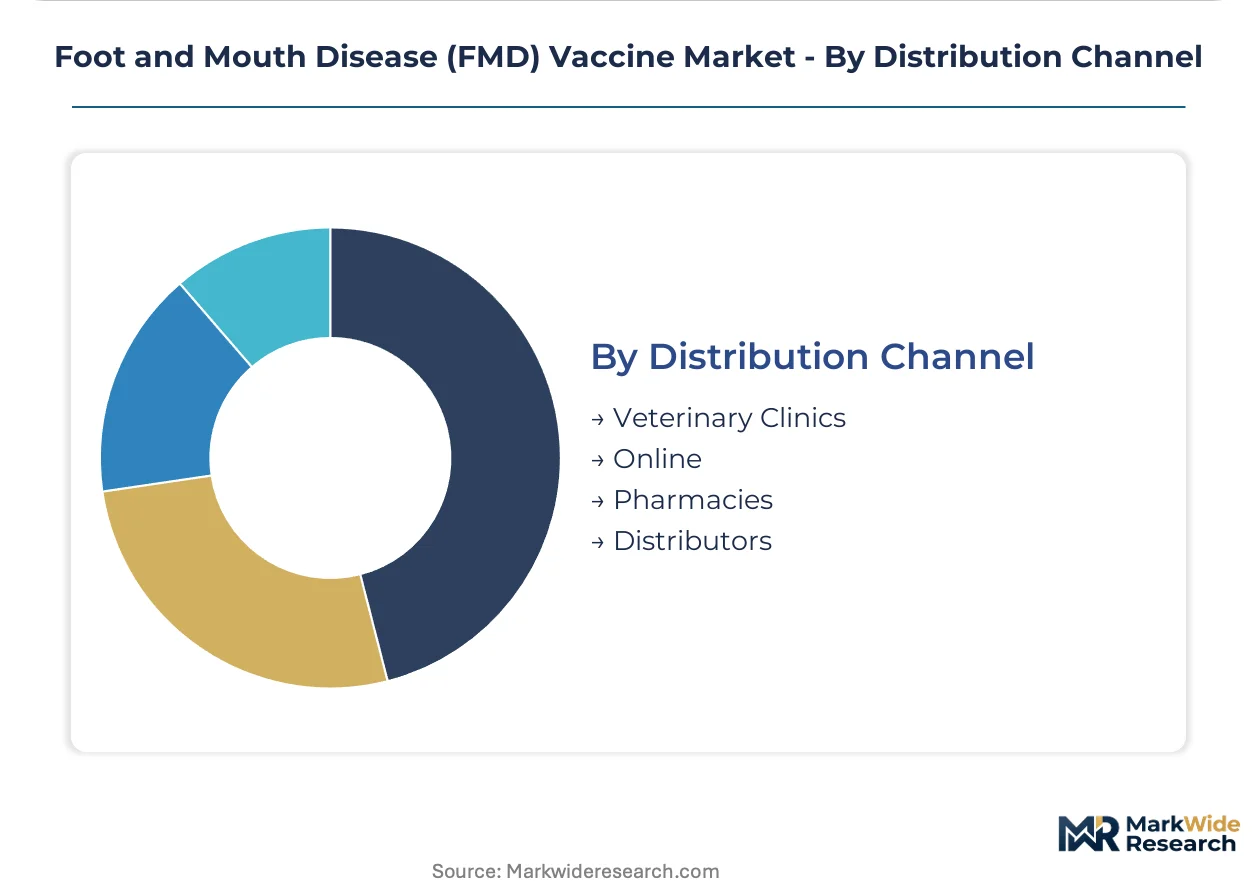
Distribution Channel:
Customer type heterogeneity—public procurement officers versus private veterinarians versus retail farmers—forces parallel channel strategies with incompatible margin structures.
- Distributors:Wholesale intermediaries consolidating provincial demand for government tender fulfillment. Indonesian national livestock programs and Indian state veterinary services route bulk purchases through authorized distributors with cold-chain custody documentation. Inventory financing and strain-matching advisory services constitute core value-add functions.
- Veterinary Clinics:Clinical service points dispensing individual animal or small-batch treatments. Argentina's regional veterinary networks and Brazil's cooperative-affiliated clinics serve commercial producers seeking customized vaccination schedules. Diagnostic bundling and immunity testing integration elevate service intensity.
- Pharmacies:Retail access points for smallholder emergency purchases, limited by cold-chain maintenance capabilities.
- Online:Emerging direct-to-producer platforms in Indian private dairy sectors, constrained by temperature-controlled last-mile logistics.
By volume, Distributors leads. By growth pace, Veterinary Clinics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in Brazil anchors South American vaccine distribution networks, handling bulk antigen shipments from European manufacturers before inland transfer to the Pantanal and pampas ranching zones. Cold-chain corridors radiating from this hub sustain just-in-time delivery to federal procurement depots across Mercosur member states.
India
Hyderabad's bulk manufacturing cluster underwrites domestic self-sufficiency through expanded public-sector antigen capacity. CDSCO's alignment with OIE-WOAH import frameworks streamlines strain update approvals for international suppliers. The Telangana-based production network now serves neighboring Bangladesh and Nepal through regional tender participation.
Brazil
Federal livestock immunization campaigns drive multi-million dose procurement through PANAFTOSA-coordinated serotype matching protocols. ANVISA's veterinary biologics registration pathway governs emergency use authorizations during outbreak response. São Paulo state's dairy cooperative networks pilot oral delivery formats in extensive grazing systems where mustering costs dominate economics.
Argentina
Feedlot operators in Buenos Aires province accelerate DNA vaccine adoption for DIVA-compliant trade certification with Chilean and Uruguayan markets. The national agricultural technology institute validates non-structural protein antibody protocols for post-vaccination surveillance. Córdoba's veterinary service networks integrate immunity testing with slaughter weight optimization consulting.
Vietnam
Provincial procurement consolidation under the progressive control pathway aggregates demand into centralized multi-year supply agreements. The agriculture ministry's livestock department governs trivalent formulation specifications for commercial pig zones in the Red River Delta. Da Nang's cold-chain distribution hub serves transmigration zone cattle development programs in the Central Highlands.
Thailand
Integrated pork operations in Chachoengsao and Saraburi provinces expand SAT serotype cross-protection purchases for confinement settings. The national veterinary service administers potency testing protocols aligned with OIE-WOAH reference standards. Bangkok's distributor networks bundle diagnostic services with customized vaccination scheduling for export-oriented producers.
Foot and Mouth Disease (FMD) Vaccine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying bulk antigens and formulation expertise. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with multi-site production networks, regional champions anchored to domestic manufacturing partnerships, and emerging biosimilar entrants targeting price-sensitive public tenders. Structural consolidation concentrates procurement eligibility among holders of dual national-international certification standards. Competitive positioning hinges on strain-matching agility and cold-chain custody documentation rather than manufacturing scale alone.
Among European-based pharmaceutical conglomerates, Boehringer Ingelheim International GmbH exemplifies the platform-integrator archetype through multi-continental production networks. Indian Immunologicals Limited occupies a position within the regional champion tier, anchoring domestic supply security through Hyderabad-based bulk manufacturing. Biogénesis Bagó represents the Latin American specialist archetype, with formulation development calibrated to local serotype prevalence patterns across Mercosur markets.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Indian Immunologicals Limited |
| Biogénesis Bagó |
| Zoetis Inc. |
| Godrej Agrovet Limited |
| Ceva Santé Animale S.A. |
| Elanco Animal Health Incorporated |
| VECOL S.A. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Indian bulk antigen manufacturing is compressing spot-market pricing for standard inactivated formulations while simultaneously pressuring European suppliers to defend premium positioning through DIVA-compliant certification tiers. This utilization asymmetry between Hyderabad's expanded public-sector capacity and Western marker-vaccine specialization is bifurcating procurement economics across endemic and trade-sensitive zones.
Pricing Analysis
Volume-discount tiering structures dominate public-sector tender economics, with Indian state veterinary services and Brazilian federal campaigns extracting steep per-dose reductions for multi-million annual commitments. Price differentiation hinges on cold-chain custody documentation quality and OIE-WOAH strain-matching certification grade, with premium tiers commanding substantial markups for emergency-use authorization speed. Cost compression in standard inactivated formulations is intensifying because biosimilar entrants from South Asian microbial expression platforms are undercutting legacy suppliers. Smallholder retail channels exhibit highest price sensitivity, while export-oriented feedlot operations in Argentina demonstrate lowest elasticity due to trade-certification compliance requirements.
Supply Chain Analysis
Upstream feedstock dependencies center on fetal bovine serum for viral propagation media and specialized cell culture substrates, with supply concentration in Argentina, Australia, and New Zealand grazing regions. Antigen production draws from European multi-site manufacturing networks for high-potency reference strains, while formulation and fill-finish operations cluster in India, Brazil, and Thailand. Single-source vulnerability pervades the seven-valent strain bank maintenance, where exclusive supplier relationships for SAT serotype antigens create outbreak-response bottlenecks. Distribution runs through federally authorized cold-chain corridors with custody documentation mandatory for tender eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Government procurement cyclicality—driven by electoral-cycle livestock program announcements—creates demand troughs that favor manufacturers with diversified geographic exposure over single-market dependents.
For Market Incumbents: Insulate margin structures by securing backward integration into fetal bovine serum supply through Argentine pampas sourcing partnerships, while simultaneously accelerating CDSCO-OIE dual certification investments to preempt biosimilar entrants in Indian public tenders. DNA platform substitution threatens inactivated formulation incumbents most acutely in Argentina's feedlot sector, where DIVA compliance is becoming non-negotiable for Chilean market access. For New Entrants and Emerging Players: Pursue oral delivery format specialization for Brazil's Pantanal extensive grazing systems, where mustering cost economics favor bait-based vaccination over injectable infrastructure. Vietnam's provincial procurement consolidation presents the most penetrable entry channel, with centralized multi-year agreements offering volume visibility absent from fragmented district-level systems. Go-to-market execution should anchor on PANAFTOSA serotype-matching protocol pre-qualification to unlock Mercosur cross-border eligibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated manufacturers with multi-year government supply agreements and antigen bank maintenance contracts. Long-term viability over the coming decade favors asset-light recombinant subunit specialists over capital-intensive live-virus propagation facilities. Acquisition screening should prioritize Indian manufacturers with CDSCO export certification and Hyderabad cluster proximity. The critical inflection signal to monitor is DIVA policy adoption velocity across Southeast Asian progressive control zones.| Strategic Initiative | Industry Significance |
|---|---|
| Antigen Bank Maintenance Contracting | Strategic reserve stockpiling secures multi-year revenue visibility with national veterinary services. |
| CDSCO-OIE Dual Certification Investment | Dual standards alignment accelerates strain update approvals and emergency use authorizations in India. |
| Oral Delivery Format Development | Bait-based systems unlock procurement channels in Brazil's Pantanal where mustering costs dominate. |
| Recombinant Subunit Platform Migration | Baculovirus expression reduces biosafety level three facility dependency and production lead times. |
| PANAFTOSA Protocol Pre-Qualification | Mercosur serotype harmonization simplifies multi-country tender participation across South America. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of OIE-WOAH outbreak notification databases, national veterinary service procurement records, and CDSCO import registration filings. Primary interviews engaged vaccine manufacturing executives, regulatory affairs specialists at Indian and Brazilian agencies, livestock department procurement officers, and cold-chain logistics coordinators. Secondary validation incorporated customs trade data for antigen bulk shipments, PANAFTOSA serotype surveillance reports, and ANVISA veterinary biologics registration disclosures. Bottom-up demand modeling from national immunization program targets was cross-checked against top-down manufacturer capacity disclosures.
Forecast inputs span product type segmentation across inactivated, DNA, and subunit platforms; administration route economics comparing injectable infrastructure versus oral delivery systems; and target animal specifications for cattle, pig, and small ruminant formulations. Geographic clustering captures Indian state-level tender aggregation, Brazilian federal campaign scheduling, and Southeast Asian progressive control pathway milestones. CAGRs were derived from trend extrapolation of procurement volume trajectories, adjusted for serotype shift probability and regulatory approval timelines. Industry-specific inputs include antigen strain bank rotation schedules and DIVA assay standardization progress across reference laboratories.
Sensitivities concentrate around serotype emergence events requiring emergency strain updates, cold-chain infrastructure investment gaps in sub-Saharan expansion zones, and regulatory divergence between OIE-WOAH and national potency testing protocols. Forecasts reflect documented assumptions regarding government procurement continuity and trade-certification policy stability. Cross-checking against FAO livestock disease control expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Scales Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Global Dog Vaccines Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Pet DNA Testing Market
Veterinary
Spay and Neuter Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Wearable Sensors for Animal Health Management Market