
 Global Veterinary Care Market | 2026-2036
Global Veterinary Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Care Market Foresight
Companion animal specialty-grade diagnostics is bifurcating the competitive landscape into premium precision-medicine providers and volume-driven generalists. Zoetis Inc. leverages its molecular diagnostics portfolio to command premium positioning in reference laboratory services. Merck & Co., Inc. anchors its position through vaccine manufacturing scale across North American and European production networks. Boehringer Ingelheim International GmbH differentiates via its integrated pharmaceutical-nutrition platform spanning livestock and companion species.
Veterinary care encompasses the medical, surgical, and preventive health management of animals, incorporating diagnostic imaging modalities operating at 1.5–3.0 Tesla for MRI and 40–150 kVp for digital radiography, plus immunoassay platforms with picogram-per-milliliter sensitivity thresholds for endocrine and infectious disease panels. Its commercial purpose centers on sustaining animal productivity in food systems while extending companion animal healthspan and quality of life. Preventive care and diagnostic testing capture disproportionate margin pools as pet owners shift from episodic sick visits to wellness protocols. Companion animals dominate value generation, though livestock segments sustain volume throughput tied to protein supply chains. Telemedicine delivery mode is expanding fastest from a small base, constrained by regulatory scope-of-practice limitations that vary by jurisdiction.
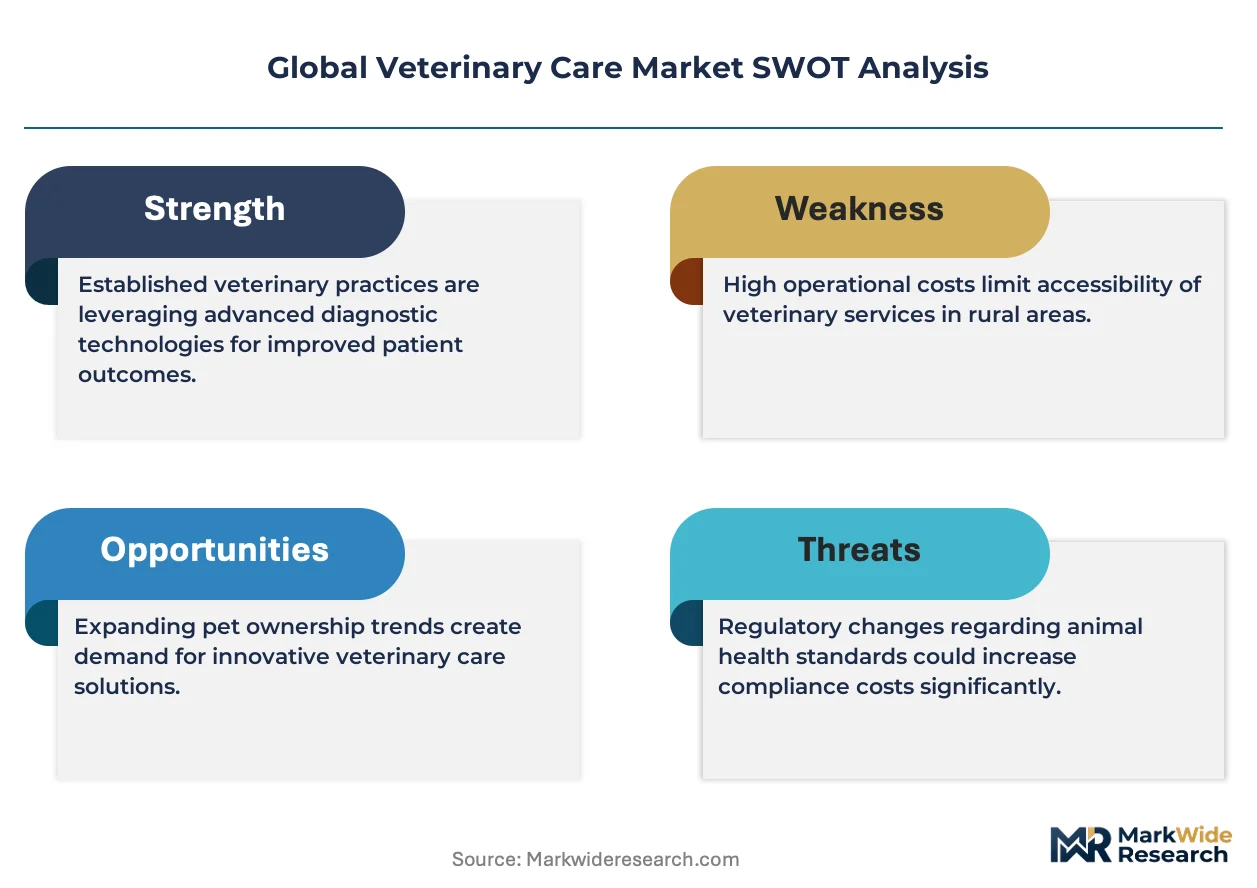
The FDA Center for Veterinary Medicine governs pharmaceutical approval pathways and residue monitoring, while the EMA coordinates centralized marketing authorizations across EU member states. The USDA Animal and Plant Health Inspection Service regulates interstate movement, biologics licensing, and emergency response for foreign animal diseases. Stakeholders must monitor evolving telemedicine scope-of-practice rulings and antimicrobial stewardship mandates that will reshape service economics and pharmaceutical formularies.
Market Dynamics
Telemedicine platforms are decomposing traditional clinic-based service models across rural and peri-urban veterinary markets, forcing incumbents to reconfigure asset-light delivery networks while regulatory scope-of-practice rulings lag behind technological capability.
Growth Catalysts
- Companion Animal Humanization:Pet owners in Australia and Brazil now demand specialty-grade diagnostics previously reserved for livestock operations, expanding addressable service intensity per household.
- EMA Centralized Marketing Authorizations:Streamlined pharmaceutical registration across EU member states accelerates cross-border product launches and reduces regulatory duplication costs for biologics manufacturers.
- Point-of-Care Immunoassay Miniaturization:Picogram-sensitivity testing devices enable same-visit diagnostic confirmation in general practice settings, capturing margin pools previously reserved for reference laboratories.
Market Restraints
- Veterinarian Labor Supply Concentration:Accredited veterinary schools in the US and UK produce insufficient graduates to match companion animal service demand, inflating salary costs and appointment wait times.
- Active Pharmaceutical Ingredient Import Dependence:Chinese and Indian API manufacturers supply critical antibiotic and vaccine precursors, exposing formulators to geopolitical supply disruptions and quality enforcement variability.
- Antimicrobial Stewardship Mandates:FDA veterinary feed directives and EU restrictions on prophylactic antibiotic use compress livestock pharmaceutical margins while requiring R&D reinvestment in alternative therapeutics.
Strategic Opportunities
- Mobile Delivery Unit Expansion:Brazil's agricultural interior and Australia's Northern Territory present coverage gaps where veterinary service deserts exceed 200 kilometers from fixed facilities.
- AI-Assisted Radiography Interpretation:Machine learning algorithms trained on 40–150 kVp digital radiography datasets enable general practitioners to flag orthopedic and thoracic abnormalities without specialist consultation delays.
- USDA Biologics Licensing Simplification:Emergency use pathways for foreign animal disease countermeasures reduce time-to-market for novel vaccine platforms during outbreak scenarios.
Industry Challenges
- Telemedicine Regulatory Fragmentation:State-level veterinary medical boards in the US impose inconsistent prescription authority and VCPR establishment rules, complicating national platform rollouts.
- Diagnostic Equipment Obsolescence Cycles:MRI systems operating at 1.5–3.0 Tesla require seven-figure capital commitments with ten-year depreciation schedules, straining independent practice cash flows.
- Cross-Border Credential Recognition:Specialist certification reciprocity gaps between the AVMA, RCVS, and Australian Veterinary Boards restrict labor mobility during regional shortage events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Care Market |
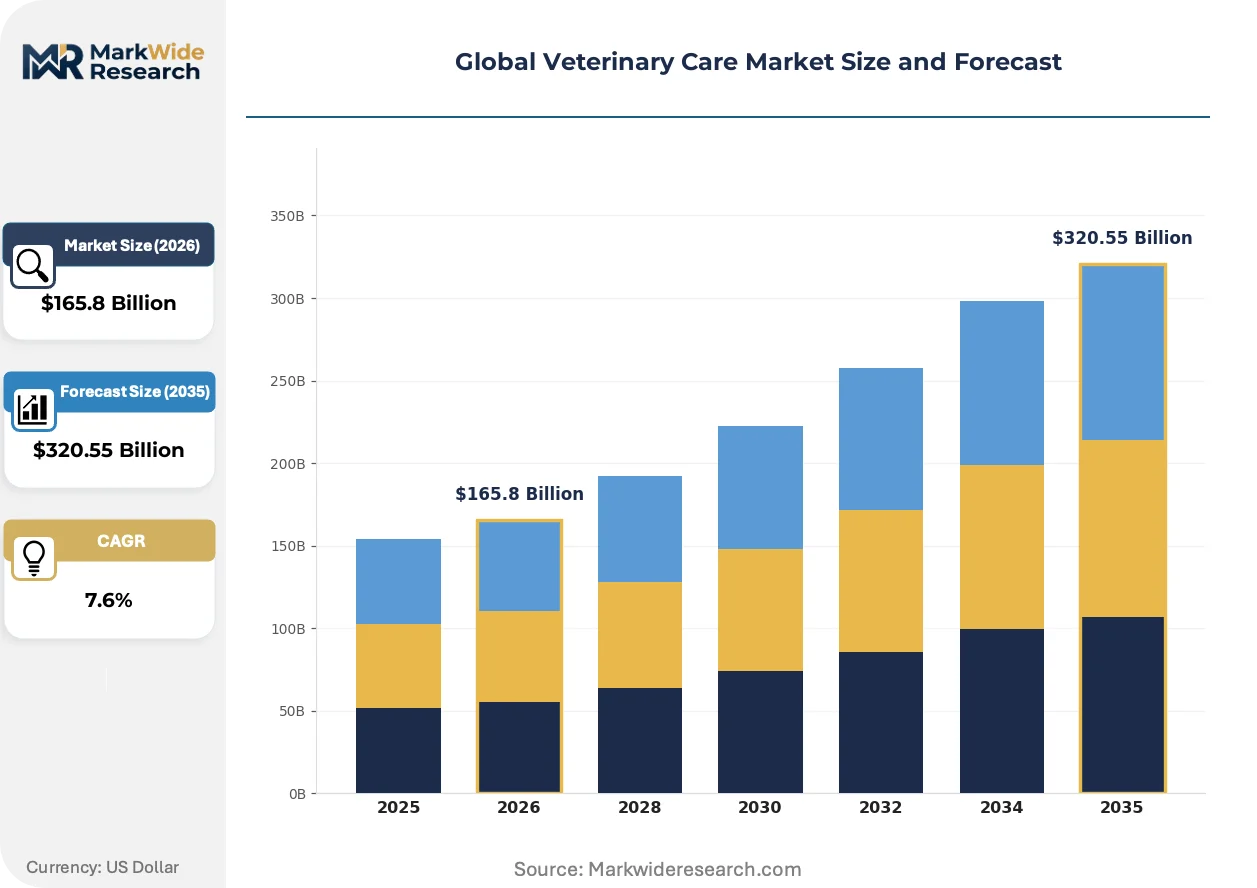
| Market Size in 2026 | $165.8 Billion |
| Market Size in 2035 | $320.55 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Care, Surgical Services, Diagnostic Testing, Emergency Care, Behavioral Therapy Animal Type: Companion Animals, Livestock, Equine, Exotic Pets, Aquatic Species End User: Veterinary Clinics, Research Institutions, Animal Shelters, Zoos, Pet Owners Delivery Mode: In-Clinic, Mobile Veterinary Units, Telemedicine, Home Visits, Community Outreach Programs |
| Companies Covered | Zoetis Inc., Merck & Co., Inc., Boehringer Ingelheim International GmbH, Elanco Animal Health Inc., IDEXX Laboratories, Inc., Ceva Santé Animale S.A., Virbac S.A., Dechra Pharmaceuticals PLC, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Care Market Shifts & Advancements
Artificial intelligence and portable diagnostics are redistributing clinical decision-making from centralized reference laboratories to point-of-care environments, while antimicrobial policy tightening forces therapeutic portfolio restructuring.
Portable ultrasound systems with cloud-connected image transmission are decomposing the traditional referral pathway for cardiac and abdominal imaging. General practitioners in Germany and Japan now acquire real-time specialist interpretation without patient transport, compressing diagnostic turnaround from days to hours and capturing revenue previously lost to tertiary centers.
EMA's revised veterinary pharmacovigilance guidelines now mandate real-world safety data collection post-authorization, elevating compliance infrastructure costs for pharmaceutical sponsors. Manufacturers serving EU livestock markets must deploy digital adverse event reporting systems, with feed additive and vaccine segments facing the steepest documentation burden increases.
Subscription-based wellness protocols are displacing episodic sick-visit economics in companion animal segments. Pet owners in Canada and South Korea now pre-commit to annual diagnostic panels and preventive care bundles through veterinary practice membership programs, smoothing revenue seasonality while locking in client retention against competing clinics.
Global Veterinary Care Market Segmentation
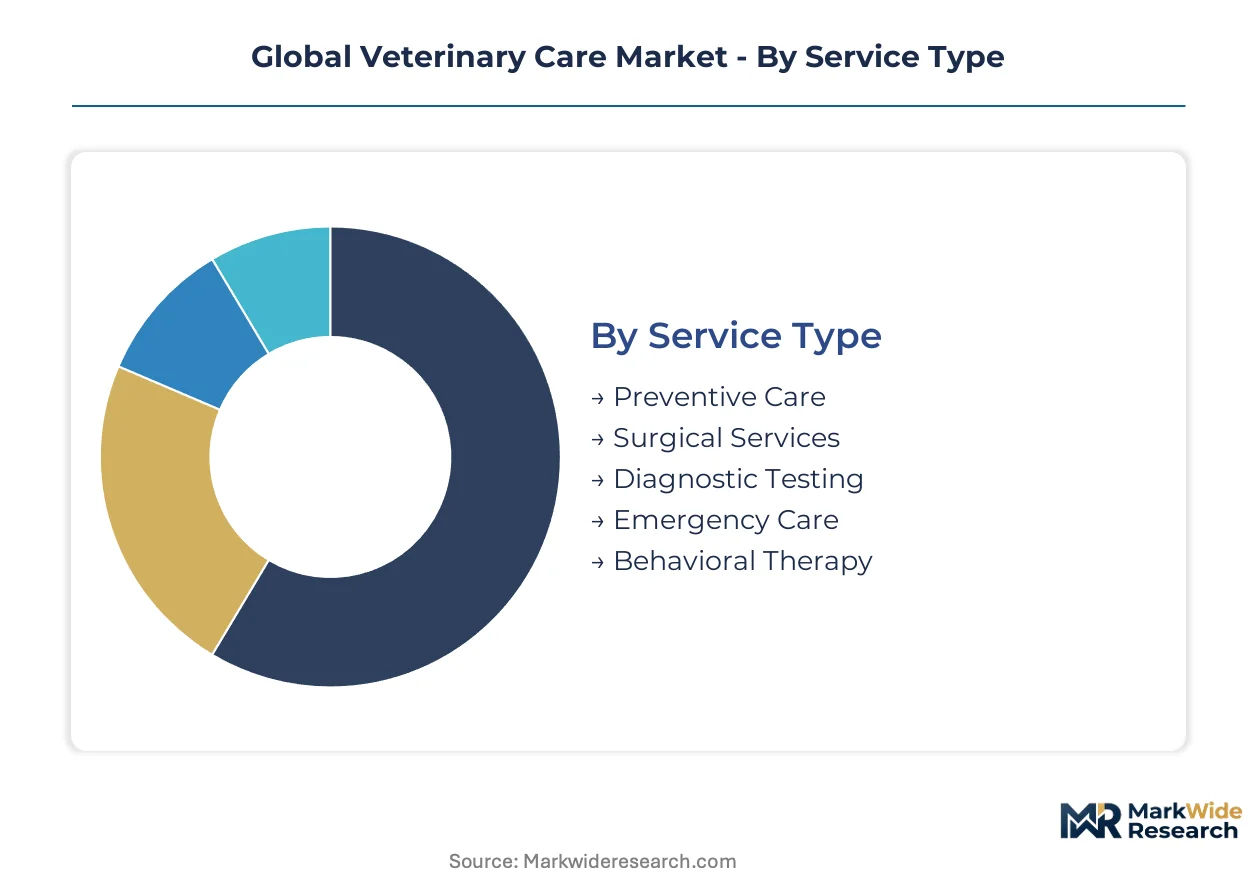
Segmentation in veterinary care reveals how regulatory frameworks, species-specific disease burdens, and delivery infrastructure constraints create distinct margin profiles across service categories. Understanding these divisions enables stakeholders to align capital deployment with jurisdictional licensing requirements and reimbursement pathways.
Service Type:
FDA Center for Veterinary Medicine and EMA pharmacovigilance requirements differentiate service economics through prescription authority and diagnostic validation standards.
- Preventive Care:Wellness protocols encompassing vaccination schedules, parasite control, and nutritional counseling. German and Japanese pet owners now pre-commit to annual diagnostic bundles through subscription models, locking client retention while smoothing clinic revenue seasonality.
- Diagnostic Testing:Immunoassay platforms with picogram-per-milliliter sensitivity thresholds enable same-visit pathogen and endocrine confirmation. Point-of-care miniaturization is capturing margin pools previously reserved for reference laboratories in Australian general practice settings.
- Surgical Services:Soft-tissue and orthopedic procedures requiring controlled substance licensing and facility accreditation.
- Emergency Care:After-hours critical intervention with specialized equipment and staffing mandates.
- Behavioral Therapy:Pharmacological and conditioning interventions for anxiety and aggression disorders.
Preventive care handles the majority of throughput; diagnostic testing is climbing the fastest on share.
Animal Type:
Species classification determines pharmaceutical formularies, biologics licensing pathways, and antimicrobial stewardship obligations.
- Companion Animals:Dogs and cats driving specialty-grade diagnostics demand. Brazilian and Australian owners now expect MRI and advanced imaging previously reserved for livestock operations, expanding service intensity per household.
- Livestock:Cattle, swine, and poultry populations sustaining volume throughput tied to protein supply chains. USDA APHIS foreign animal disease protocols and EU antibiotic restrictions compress pharmaceutical margins while requiring alternative therapeutic R&D.
- Equine:Performance and pleasure horse populations with specialized surgical and reproductive service needs.
- Exotic Pets:Avian, reptile, and small mammal species requiring species-specific formularies and handling protocols.
- Aquatic Species:Ornamental and commercial fish populations with water-quality-integrated health management.
Livestock maintains volume dominance; companion animals deliver the steepest expansion trajectory.
End User:
Facility type dictates equipment depreciation schedules, credentialing requirements, and client acquisition economics.
- Veterinary Clinics:Fixed-site general and specialty practices with seven-figure diagnostic capital commitments. Independent operators in the US face cash flow strain from ten-year MRI depreciation schedules while competing against corporate roll-ups.
- Research Institutions:Academic and contract research organizations conducting toxicology and efficacy studies. EMA revised pharmacovigilance guidelines now mandate real-world safety data collection, elevating compliance infrastructure costs for pharmaceutical sponsors.
- Animal Shelters:Non-profit and municipal facilities with high-volume sterilization and preventive care mandates.
- Zoos:Conservation and exhibition institutions with exotic species veterinary requirements.
- Pet Owners:Direct-to-consumer telemedicine and retail pharmacy channels.
Veterinary clinics absorb the majority of service delivery; research institutions are expanding most quickly on protocol volume.
Delivery Mode:
Physical infrastructure requirements and scope-of-practice regulations fragment competitive positioning across access models.
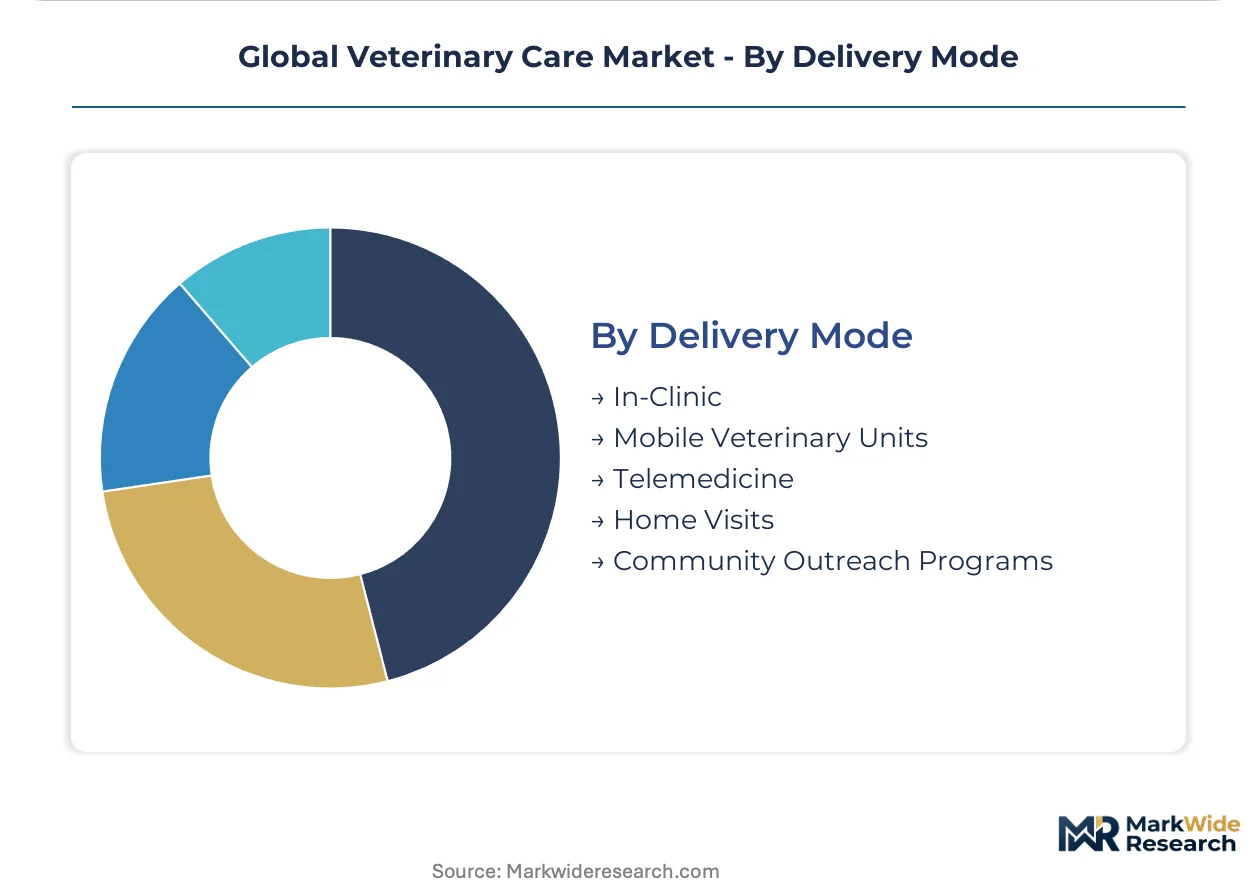
- Telemedicine:Digital consultation platforms constrained by state-level VCPR establishment rules. US veterinary medical boards impose inconsistent prescription authority, complicating national platform rollouts despite technological capability.
- Mobile Veterinary Units:Asset-light delivery for coverage gaps exceeding 200 kilometers from fixed facilities. Brazil's agricultural interior and Australia's Northern Territory present expansion opportunities where service deserts persist.
- In-Clinic:Traditional fixed-facility service with full diagnostic and surgical capability.
- Home Visits:Concierge-style delivery for geriatric or mobility-limited patient populations.
- Community Outreach Programs:Subsidized preventive care for underserved urban and rural populations.
In-clinic delivery retains the majority of revenue; telemedicine is gaining share fastest from its small base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal owners in Germany and Japan demonstrate the lowest price elasticity for specialty diagnostics, while livestock producers in Brazil and India face acute cost pressure on veterinary pharmaceutical inputs. This demand bifurcation shapes regional investment priorities and regulatory compliance burdens.
United States
Pet owners in California and New York Metro drive premium service intensity for MRI and orthopedic surgery previously concentrated in equine markets. The FDA Center for Veterinary Medicine governs pharmaceutical approval pathways and residue monitoring, extending product registration timelines. Greater Boston hosts diagnostic imaging equipment manufacturers supplying 1.5–3.0 Tesla systems to specialty referral hospitals nationwide.
Germany
Livestock producers in Lower Saxony demand precision medicine protocols for dairy herd management amid tightening EU antibiotic restrictions. The EMA coordinates centralized marketing authorizations across member states, accelerating cross-border biologics launches. Bavaria's veterinary research clusters pioneer AI-assisted radiography interpretation for general practice deployment.
Brazil
Cattle ranchers in Mato Grosso and São Paulo sustain volume throughput for vaccine and reproductive services despite compressed pharmaceutical margins. ANVISA regulates veterinary pharmaceutical registration with evolving telemedicine scope-of-practice rulings. The agricultural interior presents mobile delivery unit expansion opportunities where fixed facility coverage gaps exceed 200 kilometers.
Australia
Companion animal owners in New South Wales and Victoria now expect specialty-grade diagnostics comparable to human healthcare standards. The TGA governs veterinary pharmaceutical importation and telemedicine platform compliance. The Northern Territory's veterinary service deserts drive asset-light delivery model experimentation for remote livestock operations.
Japan
Pet owners in Tokyo and Osaka demonstrate highest willingness-to-pay for preventive care bundles and wellness protocols. METI coordinates antimicrobial stewardship mandates reshaping livestock pharmaceutical formularies. The Kansai region's veterinary equipment distributors supply portable ultrasound systems with cloud-connected specialist interpretation.
Global Veterinary Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the veterinary care market. Pharmaceutical and diagnostic manufacturers with molecular diagnostics portfolios command premium positioning in reference laboratory services, while volume-driven vaccine manufacturers anchor livestock segments through production scale. Three archetypes dominate: integrated pharmaceutical-nutrition platforms spanning multiple species, precision-medicine diagnostic specialists, and scale-driven vaccine and API formulators. M&A activity concentrates corporate veterinary practice ownership, while strategic partnerships between equipment manufacturers and telemedicine platforms reshape service delivery networks.
Within the integrated platform tier, Zoetis Inc. and Boehringer Ingelheim International GmbH exemplify archetypes combining pharmaceutical, diagnostic, and nutrition assets across companion and livestock species. Merck & Co., Inc. occupies a position representing scale-driven vaccine manufacturing with North American and European production network concentration. These three entities anchor competitive dynamics through divergent R&D prioritization and geographic licensing strategies.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck & Co., Inc. |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health Inc. |
| IDEXX Laboratories, Inc. |
| Ceva Santé Animale S.A. |
| Virbac S.A. |
| Dechra Pharmaceuticals PLC |
| Phibro Animal Health Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day API inventory buffers at North American formulators concentrate pricing power with Chinese and Indian precursor manufacturers, while Brazilian and Australian veterinary service providers absorb equipment depreciation costs through subscription-model repricing.
Pricing Analysis
After-sales service contracts and extended diagnostic warranties drive lifetime value for MRI and immunoassay equipment manufacturers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Cost compression in livestock pharmaceutical segments is intensifying because EU and FDA antimicrobial stewardship mandates force R&D reinvestment. Livestock producers in Brazil and India demonstrate highest price sensitivity; companion animal owners in Germany and Japan show lowest elasticity for specialty diagnostics.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing chokepoints in Zhejiang Province and Hyderabad anchor global veterinary antibiotic and vaccine precursor availability. Formulators in the US and Europe draw from Chinese and Indian API supply for critical inputs including tetracyclines, penicillins, and adjuvant compounds. Single-source vulnerability concentrates in pandemic-era bioreactor capacity for mRNA vaccine platforms. Distribution runs through regional veterinary distributors with cold-chain mandates for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate veterinary practice roll-ups in the US and UK have shifted buyer power toward consolidated clinic networks, fragmenting pricing leverage for independent pharmaceutical suppliers.
For Market Incumbents: Consolidate reference laboratory networks to defend margin pools against point-of-care immunoassay miniaturization. Acquire mobile delivery unit operators in Australia's Northern Territory and Brazil's Mato Grosso to preempt coverage-gap entrants. Deepen backward integration into API manufacturing to reduce exposure to Chinese and Indian supply disruptions. For New Entrants and Emerging Players: Differentiate on AI-assisted radiography interpretation for general practice deployment in Germany and Japan. Target telemedicine platform licensing in US states with harmonized VCPR rules as the most penetrable regulatory cluster. Pursue white-label diagnostic device partnerships with existing clinic networks to bypass capital-intensive equipment depreciation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical parents with underperforming veterinary nutrition divisions. Long-term viability hinges on antimicrobial stewardship compliance infrastructure and molecular diagnostics portfolio depth. Watch FDA and EMA pharmacovigilance guideline revisions as the signal for compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Licensing | ANVISA and TGA rulings on VCPR establishment rules determine addressable market scope. |
| Point-of-Care Diagnostic Miniaturization | Picogram-sensitivity immunoassay devices capture margin pools from reference laboratories. |
| API Manufacturing Backward Integration | In-house precursor production reduces dependence on Chinese and Indian supply concentration. |
| Subscription Wellness Protocol Rollout | German and Japanese pet owner pre-commitment models smooth clinic revenue seasonality. |
| Mobile Delivery Unit Expansion | Brazilian agricultural interior coverage gaps exceed 200 kilometers from fixed facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with veterinary practice owners, pharmaceutical regulatory affairs leads, diagnostic equipment procurement managers, and livestock producer cooperatives; and secondary validation through FDA Center for Veterinary Medicine filings, EMA centralized marketing authorization databases, USDA APHIS biologics licensing records, and national veterinary medical board scope-of-practice rulings. Bottom-up service volume estimates triangulated against top-down pharmaceutical shipment data.
Across the projection horizon, the analytical framework modeled segmentation dimensions including service type, animal species, end-user facility category, and delivery mode. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated antimicrobial stewardship mandate timelines and telemedicine platform penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained companion animal humanization trends and stable API trade flows would require recalibration. Practitioners should keep alternative scenarios live as FDA veterinary feed directive enforcement and EU pharmacovigilance documentation burdens evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Global Dog Vaccines Market
Veterinary
Vet Software Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Pet Cremation Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Bovine Respiratory Disease Treatment Market