
 Vestibular Testing System Market | 2026-2036
Vestibular Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Vestibular Testing System Market Outlook
Hospital neurology departments are recalibrating capital allocation toward outpatient balance clinics, diverting spend from inpatient imaging suites. Natus Medical anchors its position through R&D intensity in video oculography platforms. Interacoustics dominates European distribution channels for caloric irrigators. Neuro Kinetics specializes in rotary chair systems for research institutions.
A vestibular testing system comprises diagnostic instrumentation that quantifies peripheral and central vestibular function through nystagmus recording, postural stability measurement, and otolith organ assessment, typically employing infrared video goggles, thermal air or water stimulators, and force-plate platforms to detect angular and linear acceleration responses. Video Nystagmography leads product type revenue due to its ubiquity in standard dizziness workups, while Vestibular Evoked Myogenic Potentials represents the fastest-growing modality as clinicians expand beyond semicircular canal evaluation to otolith dysfunction detection. Software Solutions within the technology dimension commands expanding margin pools as vendors bundle AI-assisted waveform interpretation with hardware contracts.
FDA 510(k) clearance requirements for diagnostic electromedical devices and CE marking under the EU Medical Device Regulation shape product standardization and market access timelines for manufacturers. The country's national pharmaceutical and medical device regulator in Japan, PMDA, imposes additional clinical data requirements that filter entrants without local trial infrastructure. Stakeholders must monitor reimbursement coding revisions for computerized dynamic posturography as payors recalibrate coverage policies for balance disorder diagnostics.
Market Dynamics
Hospital neurology departments are recalibrating capital allocation toward outpatient balance clinics, diverting spend from inpatient imaging suites and compressing traditional equipment procurement cycles. This structural reallocation is unifying diagnostic workflows across ambulatory settings.
Growth Catalysts
- CE marking under EU MDR:Streamlined conformity assessment pathways for Class II diagnostic electromedical devices are accelerating product standardization timelines for vestibular testing platforms across European markets.
- University hospitals in Germany:Specialized dizziness centers at Heidelberg and Munich academic medical centers are anchoring regional adoption through centralized procurement consortia.
- AI-assisted waveform interpretation:Machine learning algorithms embedded in video oculography software are reducing specialist interpretation burden and expanding clinic throughput capacity.
Market Restraints
- Force-plate component concentration:Precision load cell manufacturing concentrates in Japanese and German supplier networks, exposing equipment makers to input bottlenecks.
- PMDA clinical data requirements:Japan's national pharmaceutical and medical device regulator imposes additional local trial infrastructure demands that filter market entrants without captive research capabilities.
- Reimbursement coding volatility:Payor recalibration of computerized dynamic posturography coverage policies creates revenue uncertainty for clinic operators.
Strategic Opportunities
- Vestibular Evoked Myogenic Potentials expansion:Otology practices are extending diagnostic protocols beyond semicircular canal assessment to otolith dysfunction detection, opening modality upgrade revenue streams.
- Telemedicine-integrated remote testing:Home-based balance assessment platforms are penetrating rural audiology markets previously underserved by specialist-equipped facilities.
- Research institution rotary chair procurement:Academic medical centers in the United States and Germany are funding specialized motion platform installations for central vestibular pathway studies.
Industry Challenges
- Video oculography technician certification:Specialized infrared goggle operation and nystagmus pattern recognition require training pipelines that outpace workforce supply in expanding clinic networks.
- Legacy EMR integration complexity:Proprietary data formats from standalone vestibular testing systems resist seamless connectivity with hospital information systems, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vestibular Testing System Market |
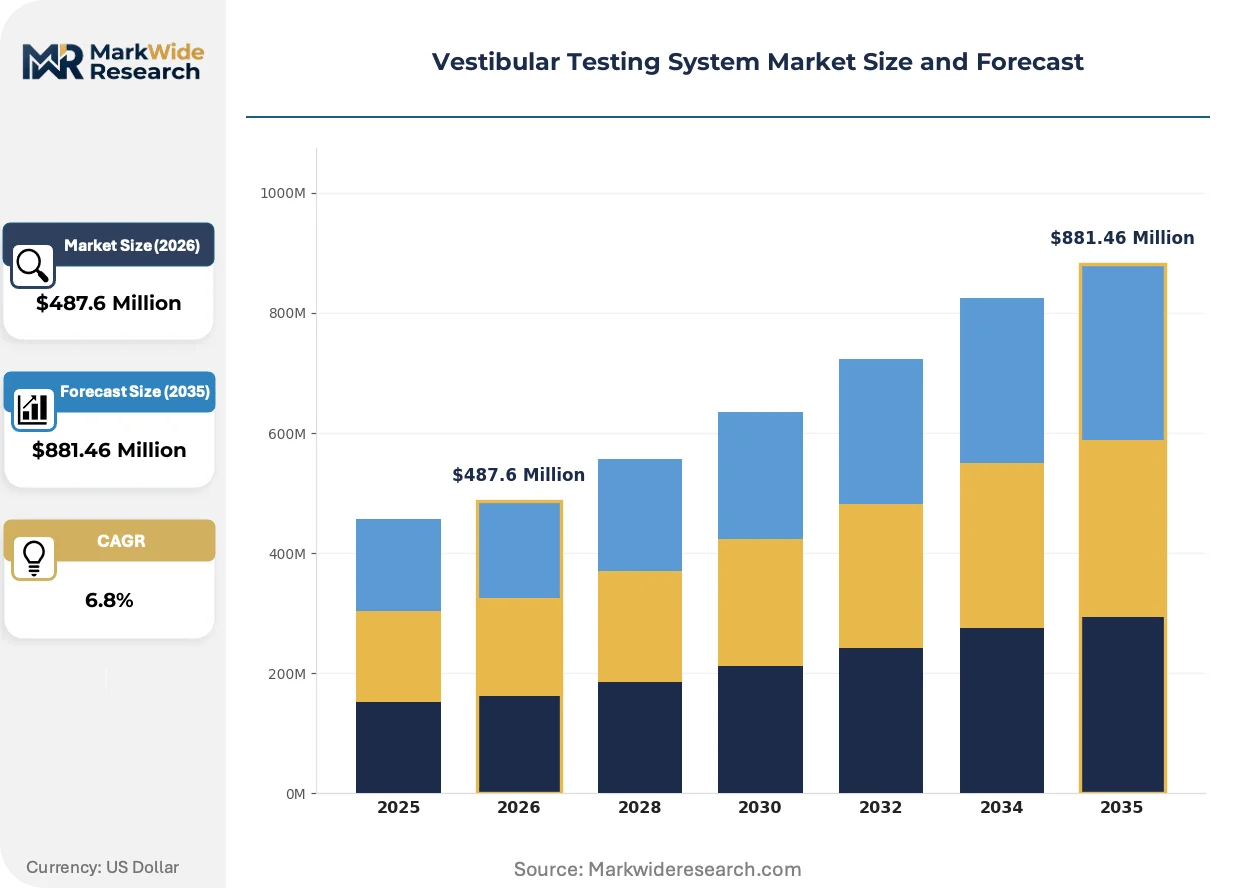
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Nystagmography, Dynamic Posturography, Caloric Testing, Vestibular Evoked Myogenic Potentials End User: Hospitals, Rehabilitation Centers, Audiology Clinics, Research Institutions Technology: Electrodes, Accelerometers, Infrared Cameras, Software Solutions Application: Dizziness Assessment, Balance Evaluation, Motion Sickness Testing, Hearing Disorder Diagnosis |
| Companies Covered | Interacoustics, Natus Medical, Neuro Kinetics, Micromedical Technologies, BioMed Jena, Synapsys, GN Otometrics, Bertec Corporation, Grason-Stadler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vestibular Testing System Market Strategic Shifts
Software bundling strategies are displacing standalone hardware sales across diagnostic equipment categories. Vendors are capturing margin expansion through AI-augmented interpretation modules rather than device markups alone.
Artificial intelligence is unifying vestibular diagnostic workflows by embedding automated nystagmus detection and waveform classification directly into video oculography platforms. Community audiology clinics are adopting these integrated systems faster than academic centers due to staffing constraints. The technology is compressing specialist interpretation bottlenecks while standardizing diagnostic consistency across operator experience levels.
CE marking under the EU Medical Device Regulation is reshaping product development timelines for infrared video goggle and thermal stimulator manufacturers. The framework mandates clinical evidence requirements that previously applied only to higher-risk device categories. European distributors are consolidating vendor relationships to reduce regulatory compliance overhead, favoring manufacturers with established notified body partnerships.
Equipment-as-a-service contracting is displacing capital purchase models among independent dizziness clinics and smaller hospital systems. Monthly subscription arrangements bundle hardware, software updates, and remote technical support, replacing traditional five-year depreciation cycles. This shift is most visible in the United States, where reimbursement pressure and cash flow constraints drive preference for operational expenditure treatment.
Vestibular Testing System Market Segmentation
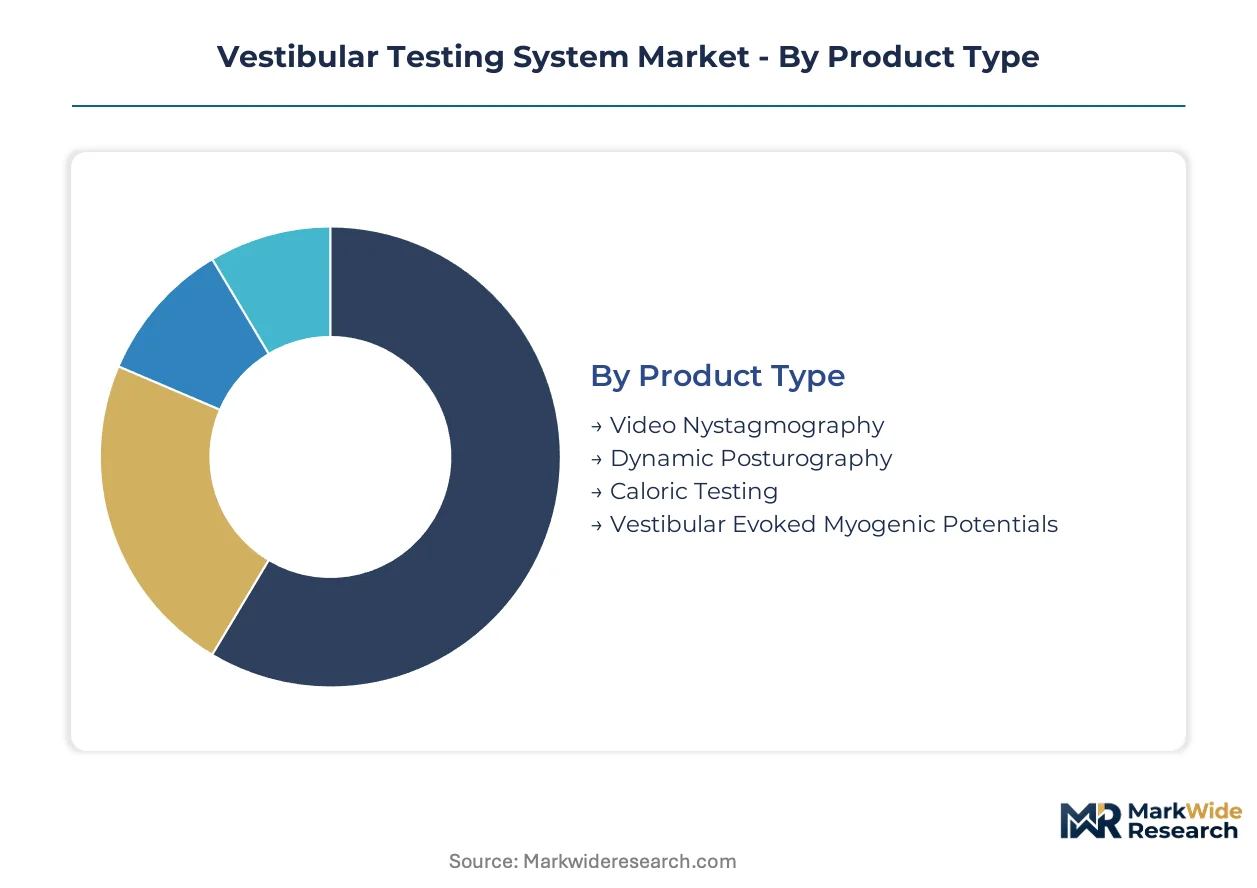
Segmentation reveals how vestibular diagnostics fragment across clinical workflows, procurement budgets, and technical capabilities. Equipment configurations vary sharply between high-throughput hospital settings and resource-constrained community practices.
Product Type:
Standardization dominates high-volume dizziness workups while specialized modalities command premium positioning for otolith and central pathway assessment.
- Video Nystagmography:Infrared video goggles capture spontaneous, positional, and gaze-evoked nystagmus patterns through high-frame-rate oculography. Demand concentrates in German university hospitals and US outpatient balance centers where semicircular canal evaluation anchors diagnostic protocols. AI-assisted waveform interpretation is compressing specialist bottlenecks in these high-throughput environments.
- Vestibular Evoked Myogenic Potentials:Surface electrode arrays record sternocleidomastoid and extraocular muscle responses to air-conducted sound and bone-conducted vibration stimuli. Otology practices in Japan and the United States are extending protocols beyond canal function to otolith dysfunction detection, opening upgrade revenue streams from installed video oculography bases.
- Dynamic Posturography:Force-plate platforms with surround-screen visual environments quantify sensory integration during perturbed stance.
- Caloric Testing:Thermal air or water irrigators induce temperature-gradient endolymph flow for lateral semicircular canal asymmetry measurement.
Growing fastest: Vestibular Evoked Myogenic Potentials. Leading the category by volume: Video Nystagmography.
End User:
Procurement authority and reimbursement pathways diverge sharply across institutional settings, shaping equipment specification and financing preferences.
- Hospitals:Neurology departments and dedicated dizziness centers within academic medical centers deploy comprehensive testing batteries across inpatient and ambulatory settings. Capital allocation is shifting from imaging suites toward outpatient balance clinics, compressing traditional procurement cycles for diagnostic electromedical devices.
- Audiology Clinics:Community-based practices prioritize compact, technician-operable systems with embedded interpretation support. Equipment-as-a-service contracting is displacing capital purchase models among independent operators facing reimbursement pressure and cash flow constraints.
- Rehabilitation Centers:Post-acute facilities integrate balance assessment into fall-risk protocols and vestibular rehabilitation programming.
- Research Institutions:Academic laboratories fund specialized rotary chair and motion platform installations for central vestibular pathway studies.
Procurement volume concentrates in hospitals. Fastest expansion trajectory: audiology clinics adopting telemedicine-integrated remote testing platforms.
Technology:
Hardware commoditization is pushing margin capture toward software and algorithmic interpretation layers.
- Software Solutions:AI-augmented waveform classification and automated nystagmus detection modules bundle with hardware contracts to expand recurring revenue streams. Vendors are capturing margin expansion through interpretation algorithms rather than device markups alone, particularly in the United States where operational expenditure treatment drives subscription preferences.
- Infrared Cameras:High-resolution image sensors with dark-pupil tracking enable sub-pixel gaze position measurement for precise slow-phase velocity calculation.
- Electrodes:Disposable surface electrode arrays for myogenic potential recording face supply standardization under CE marking and FDA 510(k) pathways.
- Accelerometers:MEMS-based inertial sensors enable portable head impulse testing outside laboratory environments.
Software Solutions command expanding margin pools. Infrared Cameras anchor hardware cost structures.
Application:
Clinical indication breadth determines equipment utilization rates and reimbursement coding stability.
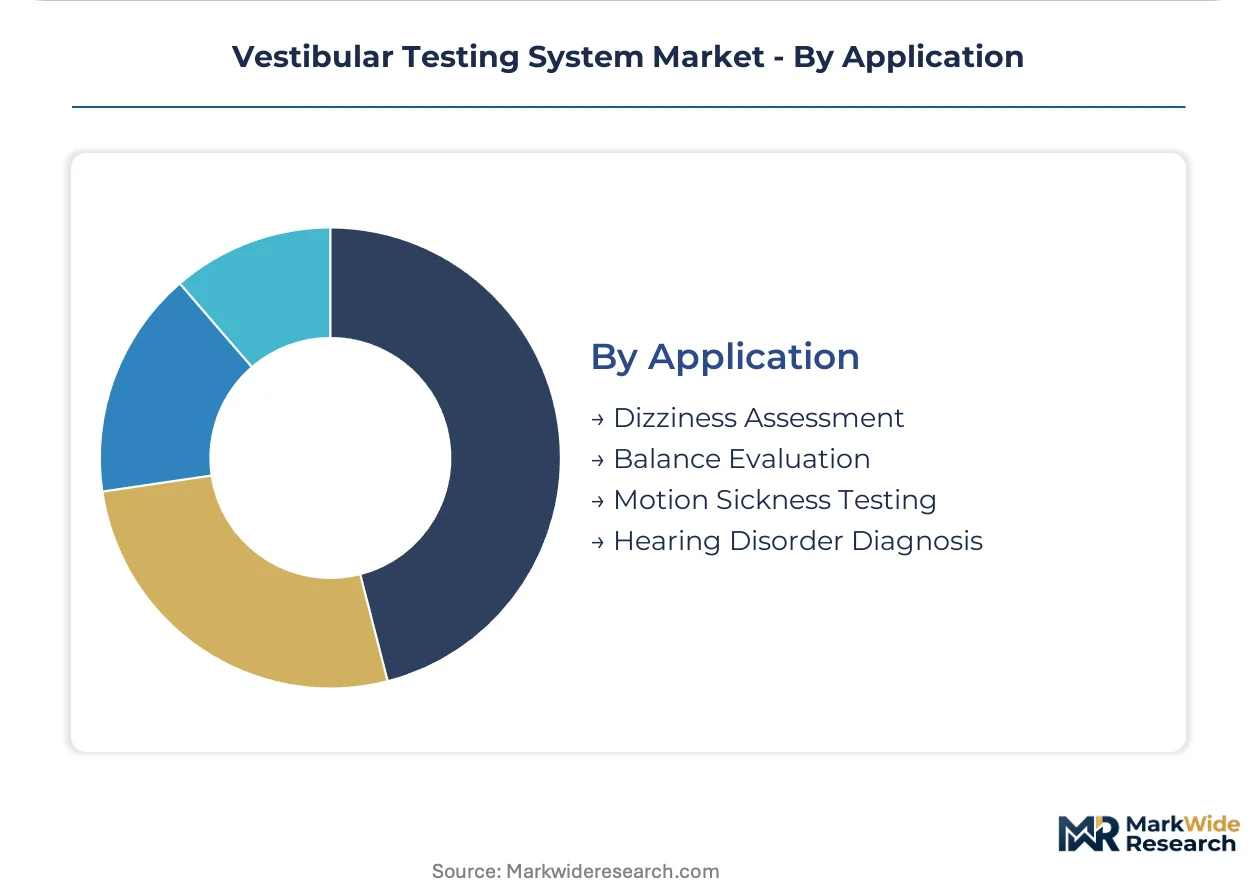
- Dizziness Assessment:Comprehensive evaluation protocols for vertigo and imbalance complaints drive the highest test volume across all end-user settings. CE marking under EU MDR and FDA 510(k) clearance requirements shape product standardization timelines for diagnostic platforms deployed in these high-frequency workflows.
- Balance Evaluation:Quantitative postural stability measurement supports fall-risk stratification in geriatric and neurologic populations.
- Hearing Disorder Diagnosis:Vestibular testing complements audiometric evaluation in suspected Ménière's disease and superior canal dehiscence.
- Motion Sickness Testing:Specialized protocols for aerospace, maritime, and virtual reality applications serve occupational medicine and research markets.
Dizziness Assessment generates dominant test volume. Balance Evaluation is climbing fastest on aging-population screening protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in German and Japanese supplier networks, while diagnostic system deployment concentrates in US and German clinical settings. Consumption patterns diverge sharply between established markets with reimbursement infrastructure and emerging markets where out-of-pocket payment dominates procurement decisions.
United States
Outpatient balance clinics and academic medical centers drive system procurement through equipment-as-a-service contracting models. FDA 510(k) clearance pathways for Class II diagnostic electromedical devices shape product standardization timelines. The Greater Boston and Pacific Northwest clusters anchor research institution procurement for rotary chair installations.
Germany
Specialized dizziness centers at Heidelberg and Munich academic medical centers anchor regional adoption through centralized procurement consortia. CE marking under the EU Medical Device Regulation streamlines conformity assessment for infrared video goggle manufacturers. Bavaria and Baden-Württemberg host precision load cell suppliers serving force-plate platform assembly.
Japan
PMDA clinical data requirements filter market entrants without local trial infrastructure, concentrating procurement among established vendors. The country's national pharmaceutical and medical device regulator imposes additional evidence standards beyond CE marking equivalence. Tokyo and Osaka metropolitan areas concentrate university hospital installations for vestibular evoked myogenic potential research.
United Kingdom
Community audiology clinics prioritize compact technician-operable systems with embedded interpretation support. NHS reimbursement coding revisions for computerized dynamic posturography create procurement timing volatility. London and Southeast England clusters concentrate private clinic investment in telemedicine-integrated remote testing platforms.
India
CDSCO medical device registration requirements for imported diagnostic equipment extend market access timelines for foreign manufacturers. Out-of-pocket payment structures at private ENT hospitals drive demand for lower-capital video nystagmography configurations. Maharashtra and Karnataka urban centers concentrate audiology clinic expansion in tier-1 cities.
Vestibular Testing System Market Competitive Environment
Top-tier vendors anchor comprehensive platform portfolios, while mid-tier specialists concentrate on single-modality excellence. The vendor base stratifies across three tiers: multinational electromedical conglomerates with full diagnostic suites, regional distributors with strong notified body relationships, and niche rotary chair fabricators serving research markets. Strategic archetypes include software-forward bundlers capturing recurring revenue, hardware-lean distributors minimizing regulatory overhead, and research-specialist engineers commanding premium positioning. Dominant competitive moves encompass M&A activity consolidating European distribution channels and strategic partnerships embedding AI interpretation modules into hardware contracts.
Among research-specialist engineers, Neuro Kinetics occupies a position exemplifying rotary chair system concentration for academic medical centers. Within the comprehensive platform tier, Natus Medical and Interacoustics represent archetypal approaches: the former anchoring R&D intensity in video oculography, the latter dominating European distribution channels for caloric irrigators. These three entities collectively illustrate how vendor positioning fragments across clinical workflow depth versus geographic coverage breadth.
| Leading Market Players |
|---|
| Interacoustics |
| Natus Medical |
| Neuro Kinetics |
| Micromedical Technologies |
| BioMed Jena |
| Synapsys |
| GN Otometrics |
| Bertec Corporation |
| Grason-Stadler |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracting preferences among US audiology clinics are compressing capital purchase timelines and forcing manufacturers to restructure hardware-plus-software bundles around operational expenditure treatment. This procurement shift concentrates pricing power with vendors capable of embedding AI interpretation modules into recurring revenue streams rather than transactional device markups.
Pricing Analysis
Short lead-time premiums attach to infrared video goggle systems sourced from German manufacturers with established notified body partnerships under EU MDR. Three-tier pricing structure across premium, standard, and economy levels differentiates systems by AI-augmented interpretation depth and CE marking tier. Cost compression in economy-tier video nystagmography intensifies because independent dizziness clinics face reimbursement pressure and cash flow constraints. Community audiology practices exhibit highest price sensitivity; academic medical centers with centralized procurement consortia show lowest.
Supply Chain Analysis
Japan's PMDA clinical data requirements and India's CDSCO medical device registration rules are reshaping sourcing toward local trial infrastructure and domestic assembly partnerships. Precision load cell manufacturing concentrates in Germany and Japan, exposing force-plate platform assemblers to input bottlenecks. Component dependencies span high-resolution infrared sensors, MEMS-based inertial accelerometers, and disposable surface electrode arrays. Single-source vulnerability runs through Japanese suppliers of precision motion sensors. Distribution runs through regional distributors with strong notified body relationships consolidating vendor portfolios to reduce regulatory compliance overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Force-plate component concentration in Japanese and German supplier networks props pricing for rotary chair and dynamic posturography systems, creating durable margin pools for vendors with captive supply arrangements.
For Market Incumbents: Cement platform dominance by embedding AI-assisted waveform interpretation into video oculography hardware contracts to capture recurring software revenue streams. Deepen backward integration into precision load cell manufacturing to defend against Japanese supplier bottlenecks. Prioritize notified body partnership consolidation in Europe to reduce CE marking timeline exposure from emerging competitors. For New Entrants and Emerging Players: Rural audiology markets in the United States and tier-1 Indian cities present underserved buyer archetypes with minimal specialist-equipped facility penetration. Telemedicine-integrated remote testing platforms offer the most penetrable application segment. Pursue equipment-as-a-service contracting to bypass capital purchase barriers among independent dizziness clinics facing reimbursement pressure. For Investors and Strategic Acquirers: The window for entry favors research-specialist rotary chair fabricators with established academic medical center relationships and software-forward bundlers capturing AI interpretation margin expansion. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volume. Watch PMDA clinical data requirement enforcement in Japan as inflection indicator for regional vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Software Companion Development | Machine learning interpretation modules embedded in video oculography contracts expand recurring revenue at Natus Medical and Interacoustics. |
| CE Marking Pathway Acceleration | Streamlined EU MDR conformity assessment for Class II diagnostic devices compresses product launch timelines for infrared goggle manufacturers. |
| Hospital System Partnership | Centralized procurement consortia at Heidelberg and Munich academic medical centers anchor regional adoption for comprehensive testing platforms. |
| Backward Integration into Load Cells | In-house production of precision force-plate components reduces exposure to Japanese and German supplier concentration risks. |
| Reimbursement Strategy Alignment | Payor recalibration of computerized dynamic posturography coverage policies dictates procurement timing for US outpatient balance clinics. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this vestibular testing system market assessment. Primary interviews with hospital purchasing committees, audiology clinic directors, biomedical engineers, and GPO contracts managers combined with FDA 510(k) clearance databases, PMDA submission records, CE marking registries, and hospital procurement databases. Bottom-up equipment shipment tracking and top-down diagnostic service revenue estimates underwent triangulation validation.
Granularity-level modeling deployed product type, end user, technology, and application dimensions at the country level across the analysis window. CAGRs derived from equipment-as-a-service contract growth trajectories and capital purchase cycle compression patterns. Forecast inputs incorporated AI interpretation module attachment rates and rotary chair research institution funding flows.
Revisions become necessary when PMDA enforcement intensity shifts, EU MDR notified body capacity constraints materialize, or reimbursement coding volatility for computerized dynamic posturography exceeds historical bands. Forecasts reflect documented assumptions around equipment procurement cycle duration and software bundling penetration curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Adiponectin Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Fungal Testing Kits Market
Testing Services
Global Ovulation Test Market
Testing Services
Bimetallic Thermometer Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Creatinine Testing Market
Testing Services
Continuous Tablet Manufacturing At-Line Quality Test Systems Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Diagnostic Shipper Market
Testing Services
Outsourced Testing Services Market