
 Clamshell Labeling Machines Market | 2026-2036
Clamshell Labeling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Clamshell Labeling Machines Market Outlook
Aftermarket service revenue is tilting toward predictive maintenance contracts as OEMs seek recurring income beyond hardware sales. Krones AG leverages its global installed base to anchor long-term service agreements across European beverage lines. SATO Holdings competes in Asia-Pacific through specialized thermal-transfer retrofit programs. Herma GmbH differentiates with modular upgrade paths that extend machine lifecycles without full replacement.
A clamshell labeling machine applies adhesive-backed labels onto pre-formed transparent plastic containers used primarily for retail display of fresh produce, baked goods, and consumer electronics. These systems integrate conveyor-fed applicators with vision-guided alignment to achieve placement tolerances within plus or minus one millimeter at speeds exceeding three hundred units per minute. Fully automatic configurations dominate installed capacity in high-throughput food packaging operations where labor scarcity intensifies. Digital technology represents the fastest-expanding segment as inline variable-data printing replaces static label inventories. Thermal transfer retains margin concentration in pharmaceutical applications where FDA-validated print permanence commands premium pricing.
FDA food-labeling regulations and GS1 barcode standards in the United States compel packagers to deploy traceability-capable equipment with lot-code verification. The EU Green Deal packaging-waste directives and REACH chemical-compliance frameworks in Europe restrict adhesive formulations and mandate recyclability disclosures on clamshell substrates. China's SAMR labeling enforcement and GB standards for pre-packaged food drive replacement cycles among domestic exporters. Stakeholders must weigh regional regulatory divergence against platform standardization when configuring global equipment portfolios.
Market Dynamics
Fresh produce packagers face mounting pressure to deploy traceability-capable equipment as FDA food-labeling rules and GS1 barcode standards tighten lot-code verification requirements across high-throughput operations.
Growth Catalysts
- FDA Food-Labeling Mandates:United States packagers must upgrade to inline variable-data printing systems capable of real-time lot-code verification to maintain compliance with traceability regulations.
- Fresh Produce Automation:Labor scarcity across California and Florida growing regions accelerates conveyor-fed applicator deployment for clamshell containers exceeding three hundred units per minute.
- EU Green Deal Packaging Directives:REACH chemical-compliance frameworks restrict adhesive formulations and mandate recyclability disclosures, forcing equipment retrofits across German and French packaging lines.
Market Restraints
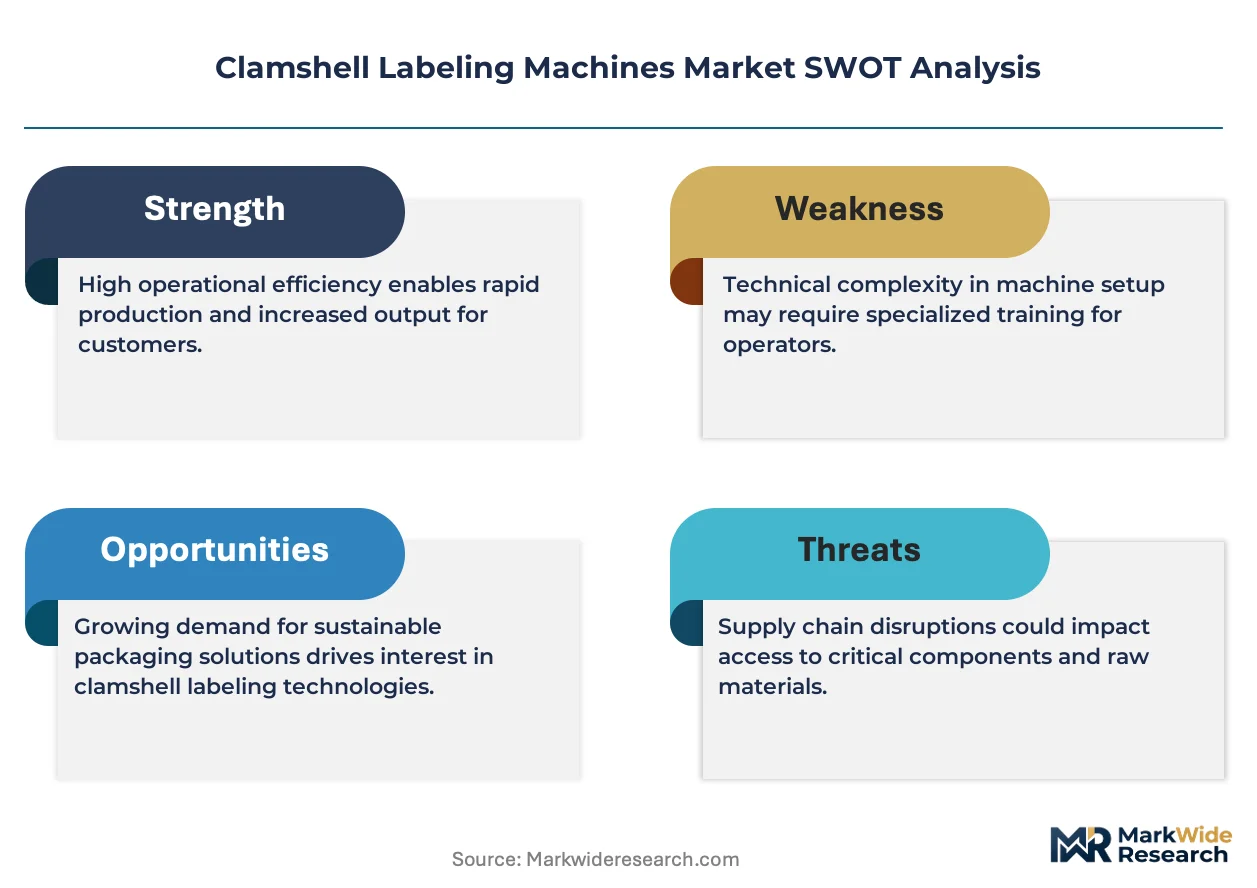
- Adhesive Raw Material Volatility:Petrochemical feedstock price swings compress margins for pressure-sensitive label stock suppliers serving the installed base.
- Component Supply Concentration:Precision servo motors and vision sensors concentrate among Japanese and German component suppliers, creating lead-time vulnerability.
- Thermal Transfer Print Speed Limits:Pharmaceutical-grade FDA-validated print permanence requirements cap throughput below food-sector speeds, segmenting equipment architectures.
Strategic Opportunities
- India Fresh Produce Modernization:FSSAI labeling enforcement and export-oriented cold chain investment create first-mover advantage for traceability-capable system vendors.
- Digital-Electronics Convergence:Inline RFID encoding married to thermal-transfer printheads enables dual-technology labeling for high-value consumer electronics clamshells.
- China SAMR Enforcement Waves:GB standards for pre-packaged food drive replacement cycles among domestic exporters seeking European and North American market access.
Industry Challenges
- Vision Systems Integration Talent:Shortage of technicians capable of calibrating millimeter-placement tolerance alignment extends commissioning timelines.
- Legacy Pneumatic Retrofit Complexity:Existing mechanical label dispensers require extensive conveyor modification to accommodate servo-driven digital print engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clamshell Labeling Machines Market |
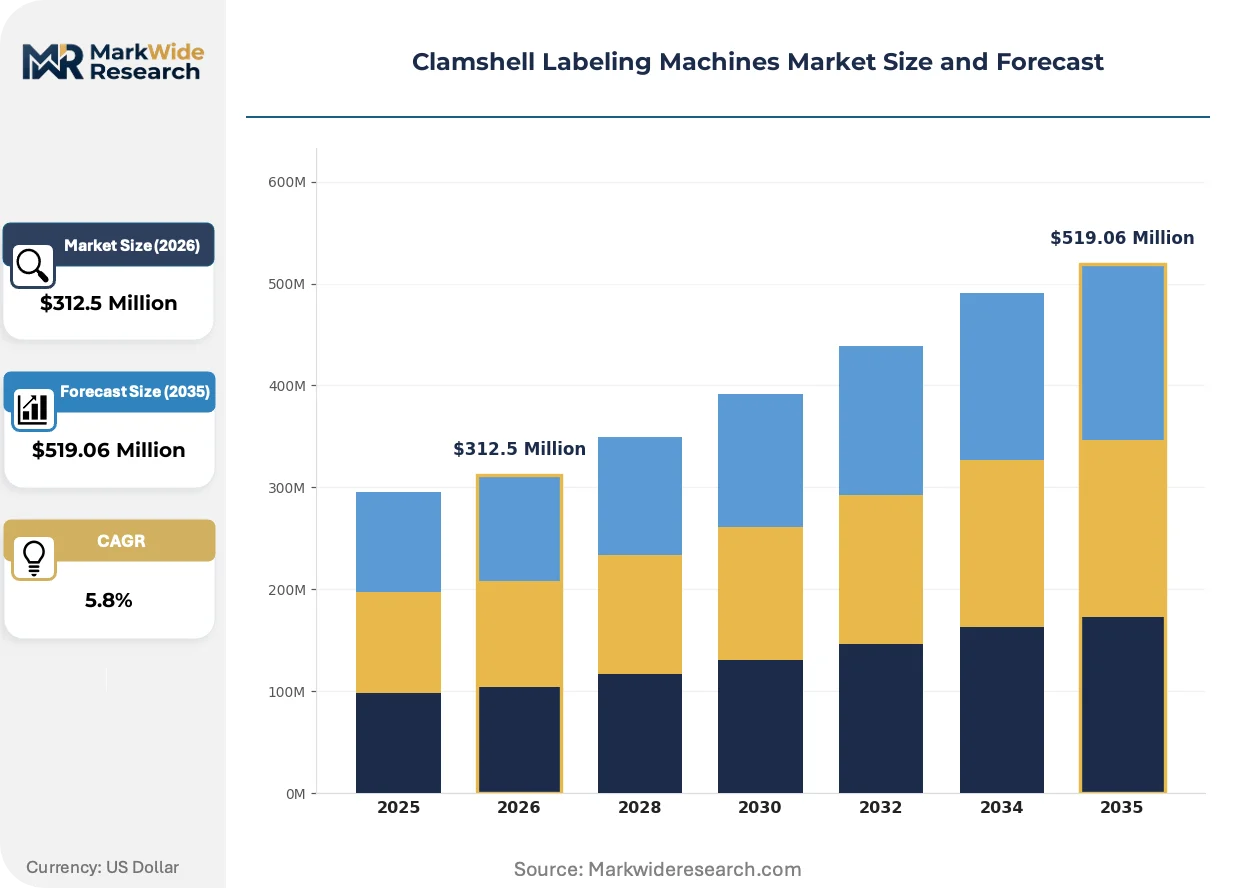
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Digital Application: Food Packaging, Pharmaceutical, Cosmetics, Electronics End User: Manufacturers, Retailers, Distributors, Wholesalers Technology: Laser Printing, Inkjet Printing, Thermal Transfer, Direct Thermal |
| Companies Covered | Avery Dennison, Zebra Technologies, SATO Holdings, Herma GmbH, Krones AG, Pack Leader Machinery, Nita Labeling Systems, Label-Aire, Accent Label Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clamshell Labeling Machines Market Strategic Shifts
Equipment architectures are pivoting from static label inventories to inline digital production, compressing changeover times and enabling batch-size-one economics for fresh produce and pharmaceutical packagers alike.
AI-powered vision-guided alignment systems now achieve sub-millimeter placement consistency without mechanical registration stops. Berry packagers in the United States and salad processors in the Netherlands deploy these systems at line speeds previously requiring pneumatic dispensers. Static mechanical registration is rendering obsolete across mid-volume operations where SKU proliferation demands frequent format changes.
REACH chemical-compliance frameworks in Europe now mandate adhesive formulation disclosure and restrict certain solvent-based chemistries in clamshell substrates. Equipment OEMs must qualify alternative hot-melt and UV-curable adhesive delivery systems to maintain European market access. Pharmaceutical packagers in Germany and Switzerland face the steepest requalification burdens as validated print permanence requirements intersect with new substrate restrictions.
Service contract unbundling is accelerating as packagers separate hardware procurement from aftermarket maintenance. Large United States retail consolidators now negotiate predictive maintenance agreements independently of capital equipment purchases, pressuring OEM pricing transparency. This shift is most pronounced among national produce distributors operating multi-site networks across California, Texas, and Florida.
Clamshell Labeling Machines Market Segmentation
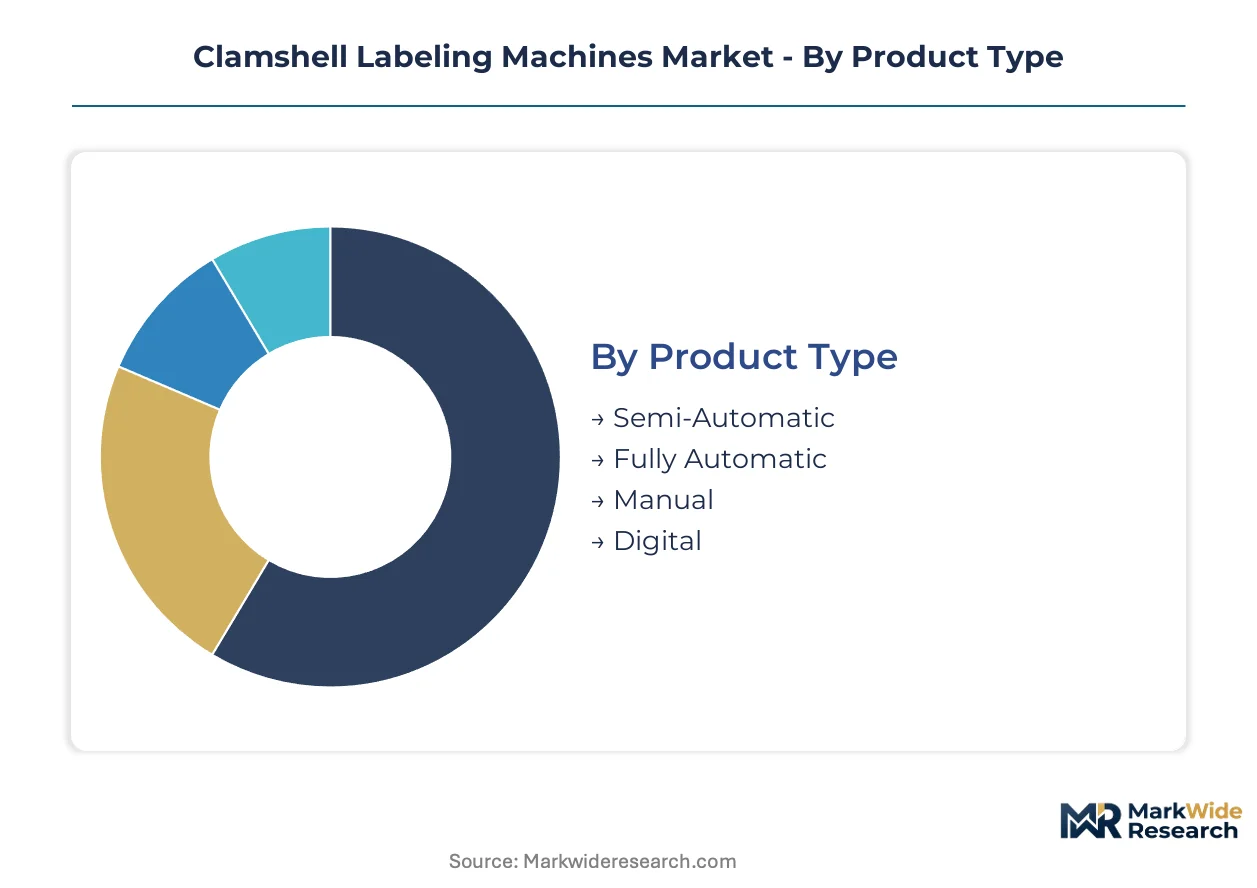
Segmentation in clamshell labeling machines reflects divergent automation thresholds across end-use verticals. Equipment specifications vary sharply between fresh produce packagers demanding high-speed throughput and pharmaceutical operations prioritizing FDA-validated print permanence.
Product Type:
Mature conveyor-fed architectures dominate high-volume food operations while emerging digital configurations reshape changeover economics.
- Fully Automatic:Conveyor-fed systems with vision-guided alignment achieve placement tolerances within plus or minus one millimeter at speeds exceeding three hundred units per minute. California and Florida fresh produce packagers deploy these configurations most intensively as labor scarcity accelerates automation investment.
- Digital:Inline variable-data printing systems enable real-time lot-code verification and batch-size-one economics without static label inventories. Pharmaceutical packagers in Germany and Switzerland adopt these systems fastest where FDA and EMA traceability mandates intersect with SKU proliferation pressures.
- Semi-Automatic:Operator-assisted applicators serve mid-volume bakeries and regional produce distributors seeking upgrade pathways without full automation capital commitment.
- Manual:Hand-held dispensers retain niche presence in artisan food producers and small-batch cosmetics operations with minimal throughput requirements.
Fully Automatic retains volume leadership; Digital holds the steepest expansion curve.
Application:
End-use concentration tilts toward traceability-regulated sectors where label permanence commands compliance premiums.
- Food Packaging:Fresh produce clamshells drive the largest installed base as GS1 barcode standards and FDA food-labeling rules mandate lot-code verification across high-throughput berry and salad packaging lines in the United States and Netherlands.
- Pharmaceutical:FDA-validated thermal transfer systems with permanent print chemistry serve blister packs and unit-dose containers where EMA and FDA regulations demand audit trails and tamper evidence.
- Cosmetics:Premium personal care brands deploy clamshell labeling for retail display differentiation with emphasis on aesthetic precision rather than regulatory traceability.
- Electronics:Consumer electronics packaging combines thermal-transfer print with inline RFID encoding for anti-counterfeiting and supply chain visibility.
Food Packaging retains volume leadership; Electronics holds the steepest expansion curve.
End User:
Procurement authority concentrates with entities controlling multi-site packaging networks and direct retail compliance exposure.
- Manufacturers:Brand-owning packagers in the United States and China drive equipment specification as they bear primary liability for FDA, SAMR, and EU labeling enforcement.
- Retailers:National grocery consolidators increasingly mandate supplier equipment standards to ensure traceability interoperability across private-label produce lines.
- Distributors:Third-party logistics providers serving cold chain networks invest in mobile labeling systems for cross-dock operations and repackaging flexibility.
- Wholesalers:Terminal market operators adopt basic applicator systems for commodity produce sorting and regional redistribution.
Manufacturers retain volume leadership; Retailers hold the steepest expansion curve.
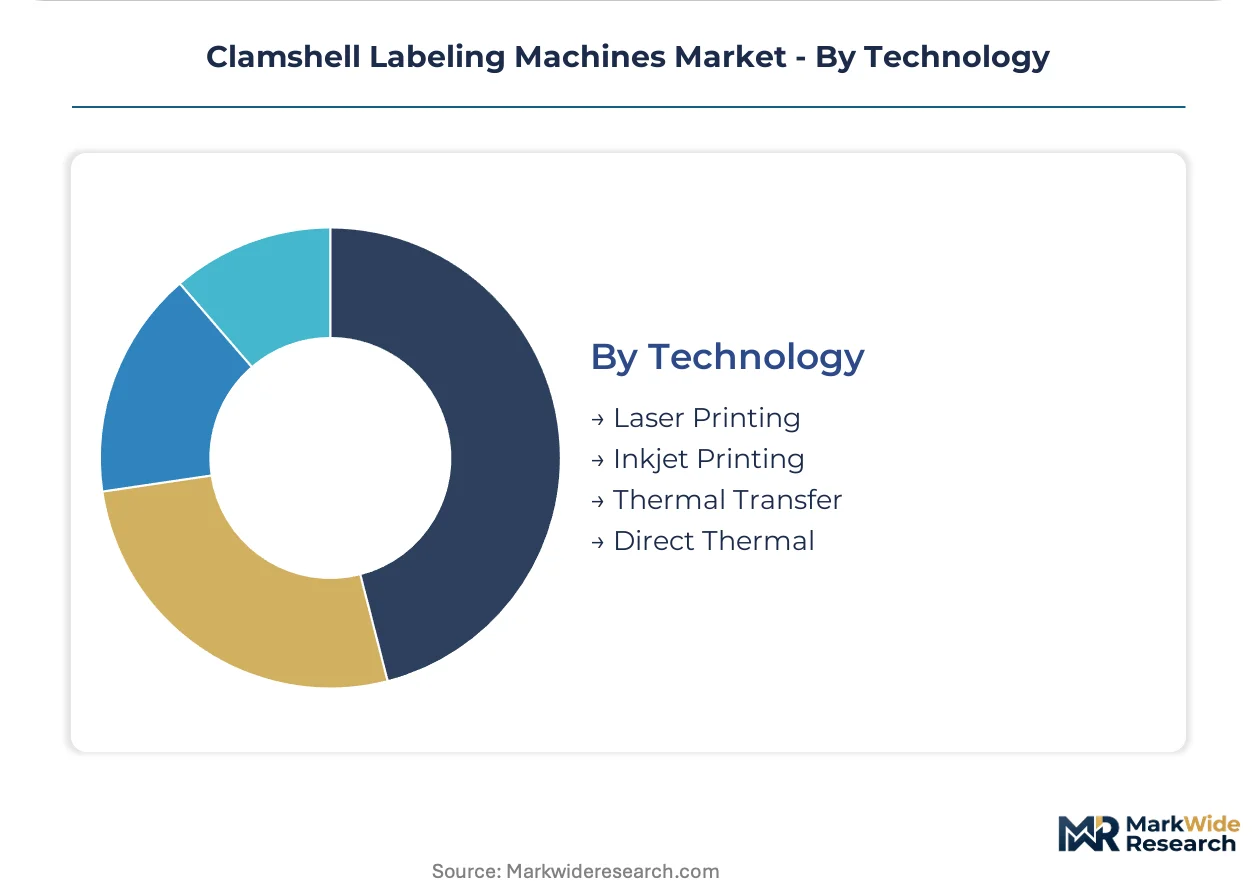
Technology:
Print permanence requirements segment technology selection between food-sector speed priorities and pharmaceutical validation burdens.
- Thermal Transfer:Wax-resin and resin ribbon chemistries deliver FDA-validated print permanence for pharmaceutical applications where EMA and FDA regulations mandate archive-grade legibility. Print speed caps below food-sector rates segment equipment architectures.
- Inkjet Printing:Piezoelectric drop-on-demand systems enable high-resolution variable data at food-packaging line speeds without ribbon consumables. Water-based and UV-curable ink formulations face REACH chemical-compliance scrutiny in European deployments.
- Laser Printing:Ablation and color-change systems etch permanent marks directly onto clamshell substrates for high-value electronics and medical device packaging.
- Direct Thermal:Chemically coated label stock without ribbon serves short-life logistics applications where print fade resistance is not critical.
Thermal Transfer retains volume leadership; Inkjet Printing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States packagers prioritize throughput velocity for fresh produce, while European operators emphasize chemical compliance and German pharmaceutical exporters demand validated print permanence.
United States
California berry packagers and Florida tomato growers deploy fully automatic conveyor-fed systems exceeding three hundred units per minute as labor scarcity intensifies. FDA food-labeling rules and GS1 barcode standards mandate real-time lot-code verification, forcing equipment upgrades across the Salinas Valley and Central Florida growing belts.
Germany
Pharmaceutical contract packagers in Baden-Württemberg and Bavaria drive demand for thermal-transfer systems with FDA and EMA-validated print permanence. REACH chemical-compliance frameworks restrict adhesive formulations, compelling equipment retrofits across Stuttgart and Munich industrial corridors.
China
Domestic exporters targeting European and North American markets accelerate replacement cycles to meet SAMR labeling enforcement and GB standards for pre-packaged food. Yangtze River Delta packaging clusters in Shanghai and Jiangsu province concentrate investment in traceability-capable digital systems.
Netherlands
Salad processors and greenhouse vegetable packagers in Westland and Noord-Brabant adopt AI-powered vision-guided alignment for sub-millimeter placement consistency. EU Green Deal packaging-waste directives mandate recyclability disclosures on clamshell substrates, reshaping equipment specifications.
India
FSSAI labeling enforcement and export-oriented cold chain investment create first-mover openings in Maharashtra and Karnataka. Nashik grape packagers and Bengaluru-area fresh produce exporters represent the fastest-emerging demand cluster for traceability-capable systems.
Clamshell Labeling Machines Market Competitive Environment
Capability concentration sits with specialized component suppliers; scale advantage sits with diversified packaging machinery conglomerates. The vendor base organizes into three tiers: integrated line builders with beverage and pharma heritage, dedicated labeling specialists with modular architectures, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include strategic partnerships between OEMs and vision-system suppliers, plus geographic expansion through distributor networks rather than direct sales infrastructure.
Within the integrated-line-builder tier, Krones AG and SATO Holdings exemplify divergent scale strategies. Krones anchors long-term service agreements across European beverage installations, while SATO Holdings occupies a position in Asia-Pacific thermal-transfer retrofit programs. Among dedicated labeling specialists, Herma GmbH represents the modular-upgrade archetype, extending machine lifecycles without full replacement. These three companies illustrate how competitive positioning fragments across service-contract intensity, geographic coverage depth, and technology-integration breadth.
| Leading Market Players |
|---|
| Avery Dennison |
| Zebra Technologies |
| SATO Holdings |
| Herma GmbH |
| Krones AG |
| Pack Leader Machinery |
| Nita Labeling Systems |
| Label-Aire |
| Accent Label Automation |
| Others |
Value Chain & Pricing Dynamics
Precision servo motor concentration among Japanese and German component suppliers creates lead-time vulnerability that compresses margin buffers across equipment tiers while simultaneously forcing buyers toward predictive maintenance contracts as insurance against supply disruption. This single-source dependency for vision sensors and motion control hardware shapes both the premium commanded by integrated OEM service agreements and the geographic clustering of final assembly capacity.
Pricing Analysis
Long-term service contracts dominate equipment procurement for multi-site fresh produce packagers, with predictive maintenance agreements now unbundled from hardware sales to create recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical configurations from food-sector throughput systems and basic semi-automatic units. Cost compression in standard-tier equipment is intensifying because adhesive raw material volatility and petrochemical feedstock swings squeeze pressure-sensitive label stock suppliers. Regional produce distributors operating single-facility networks exhibit highest price sensitivity, while national retail consolidators prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Export-control restrictions on precision motion control hardware limit flows from Japan and Germany to Chinese equipment fabricators, fragmenting global sourcing strategies for vision-guided alignment systems. Component manufacturing concentrates in Japan, Germany, and South Korea for servo motors, optical sensors, and thermal printheads. Final assembly draws from Chinese Yangtze River Delta clusters for cost-optimized units and German Stuttgart-Munich corridors for pharmaceutical-grade systems. Single-source vulnerability for piezoelectric printhead arrays creates exposure to logistics chokepoints at East Asian port complexes. Distribution runs through OEM-direct channels for validated pharmaceutical equipment and regional distributor networks for emerging-market price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clamshell labeling equipment is transitioning toward platform economics as GS1 barcode interoperability and FDA traceability mandates create winner-take-most dynamics among OEMs controlling installed-base data streams. This ecosystem shift rewards vendors who anchor long-term service relationships ahead of hardware commoditization.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance contracts into initial equipment sales, preventing unbundling by third-party service providers. Krones AG's European beverage-line strategy demonstrates how captive data from vision-system performance creates switching costs that defend against modular-upgrade competitors like Herma GmbH. Priority lever: deepen backward integration into adhesive delivery system manufacturing to offset REACH chemical-compliance cost pass-through. For New Entrants and Emerging Players: India's Maharashtra and Karnataka fresh produce corridors offer the most penetrable geography for traceability-capable system vendors, with FSSAI enforcement creating compliance-driven replacement cycles among Nashik grape packagers and Bengaluru-area exporters. Target mid-volume regional distributors seeking upgrade pathways without full automation capital commitment. Go-to-market angle: mobile labeling systems for cold-chain third-party logistics providers requiring cross-dock flexibility. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive component supply and validated regulatory pathways. Long-term viability over the projection horizon rests on OEMs who control both hardware margins and recurring service income. Acquisition target archetype: dedicated labeling specialists with modular architectures and established distributor networks in underpenetrated geographies. Signal to watch: unbundling of predictive maintenance contracts from hardware procurement among United States retail consolidators.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Anchoring | Creates recurring revenue insulation against hardware commoditization for OEMs serving multi-site produce networks. |
| Modular Upgrade Path Development | Extends machine lifecycles without full replacement, differentiating specialists against integrated line builders in mid-volume segments. |
| Vision System Integration Talent Acquisition | Addresses technician shortage for millimeter-placement calibration, accelerating commissioning timelines for AI-powered alignment deployments. |
| REACH-Compliant Adhesive Qualification | Maintains European market access as ECHA restrictions on solvent-based chemistries force equipment retrofits across German packaging lines. |
| Inline RFID Encoding Capability Addition | Captures electronics sector expansion where dual-technology labeling serves anti-counterfeiting and supply chain visibility requirements. |
Study Parameters
Initial hypotheses were tested against primary input from packaging line engineers, aftermarket service directors, produce procurement managers, and regulatory compliance officers at FDA-registered facilities, then refined against secondary validation from SEC filings of listed packaging machinery OEMs, FDA 510(k) and UDI submission databases, ECHA REACH registration dossiers, and GS1 implementation guideline releases. Bottom-up equipment shipment data triangulated against top-down end-use industry capital expenditure patterns across fresh produce, pharmaceutical, and electronics verticals.
Demand-supply balance modeling anchored volume projections to installed-base replacement cycles, new line automation intensity, and regulatory compliance deadlines without year-specific calibration. Segmentation dimensions included automation tier, print technology, end-use vertical, and geographic regulatory cluster. CAGRs derived from slope-consistency checks against historical equipment adoption curves and elasticity-adjusted price trajectory assumptions. Industry-specific inputs incorporated labor scarcity indices in California and Florida growing regions, plus SAMR enforcement wave timing for Chinese exporter equipment refresh.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported equipment fabricators or accelerated EU Green Deal packaging-waste directive implementation would shift outcomes beyond modeled ranges. Material shifts in adhesive raw material cost trajectories or precision component export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Meter-Mix Dispensing Machine Market