
 Automatic Banding Machine Market | 2026-2036
Automatic Banding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Banding Machine Market Outlook
E-commerce retailers are bifurcating demand away from traditional wholesale distributors as the dominant buyer archetype for automatic banding equipment. ATS-Tanner leverages its Swiss engineering heritage to dominate high-speed heat-sealing installations across European pharmaceutical lines. Jornen Machinery Co., Ltd. anchors its competitive position through cost-optimized fully automatic systems purpose-built for Asian packaging volumes. Marchesini Group S.p.A. differentiates via integrated line solutions that extend from banding through final case packing.
An automatic banding machine is an industrial packaging device that applies continuous paper or film bands around product bundles, typically achieving throughput rates of 20 to 80 cycles per minute depending on band width and product configuration. The equipment secures items for transit, shelf presentation, or unitization using heat-sealed, adhesive, or mechanically interlocked closures. Fully automatic systems lead product type demand due to labor cost pressures and line integration requirements, while tabletop variants occupy niche applications in small-batch printing and specialty food processing. Heat sealing technology sustains the largest installed base, though cold sealing is gaining share in temperature-sensitive pharmaceutical packaging where adhesive residue poses contamination risk.
CE marking under the EU Machinery Directive mandates emergency-stop integration and guard interlocking for banding equipment sold in Europe, while FDA cGMP guidelines shape sanitary design requirements for pharmaceutical applications in the United States. OSHA lockout/tagout standards further influence maintenance-access architecture in North American installations. Stakeholders must monitor evolving sustainability mandates around banding film recyclability and paper-based substrate transitions as these specifications increasingly gate market access across major economies.
Market Dynamics
E-commerce fulfillment networks are compressing throughput requirements for banding equipment, forcing manufacturers to prioritize cycle-speed optimization and line-integration capabilities over standalone machine sales.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for emergency-stop integration and guard interlocking are accelerating replacement cycles for legacy equipment across European pharmaceutical and food processing lines.
- Heat-sealing throughput advantages:Pharmaceutical contract packers in Germany and Switzerland are specifying high-speed heat-sealing architectures to match blister-line speeds exceeding 600 units per minute.
- Labor cost arbitrage in Asian manufacturing:Fully automatic systems are penetrating contract packaging operations in Vietnam and Indonesia where wage inflation is eroding manual banding economics.
Market Restraints
- Stainless steel input volatility:304-grade stainless steel price swings directly compress margin structures for sanitary-design equipment builders serving FDA-regulated pharmaceutical applications.
- Control system supplier concentration:PLC and servo-drive sourcing dependence on German and Japanese automation vendors creates lead-time vulnerability for mid-tier banding OEMs.
- Cold sealing performance ceiling:Adhesive-based cold sealing technology faces throughput limitations below 40 cycles per minute, constraining deployment in high-volume e-commerce sortation facilities.
Strategic Opportunities
- Indian pharmaceutical export expansion:CDSCO-certified banding equipment demand is rising among contract manufacturers supplying FDA-regulated markets with serialized secondary packaging.
- Paper-based substrate transition:EU Green Deal packaging waste directives are creating specification windows for recyclable paper banding films in retail-ready applications previously dominated by polypropylene.
- Vision-guided robotic integration:Convergence of machine vision and collaborative robotics is opening automated changeover capabilities for batch-size-one pharmaceutical packaging.
Industry Challenges
- Mechatronics technician scarcity:Servo-tuning and motion-control expertise gaps are extending commissioning timelines for integrated banding-line installations.
- Legacy MES integration complexity:Pharmaceutical manufacturers are demanding OPC-UA connectivity layers that bridge 1990s-era banding controllers to modern serialization databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Banding Machine Market |
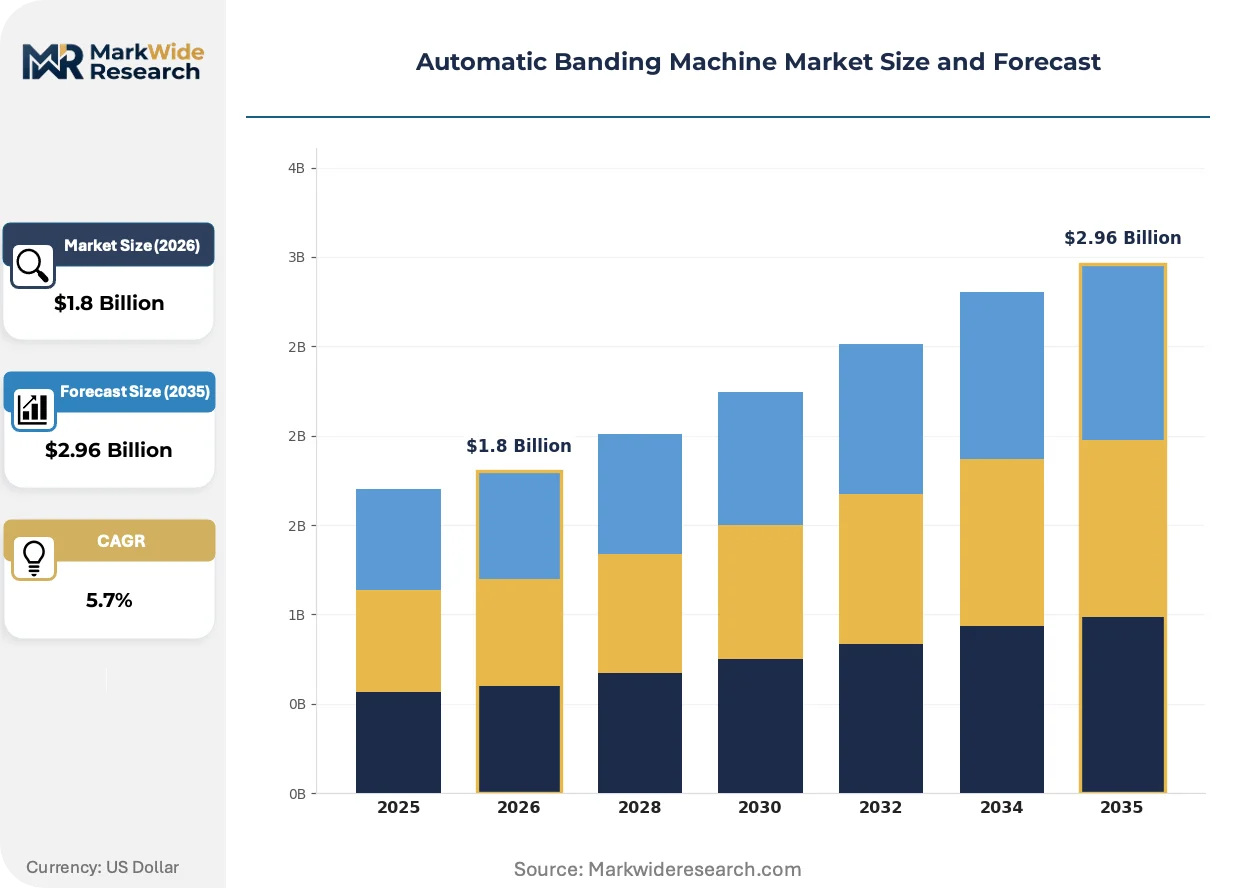
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Tabletop Application: Packaging, Printing, Food Processing, Pharmaceutical End User: Manufacturers, Wholesale Distributors, Retailers, E-Commerce Technology: Heat Sealing, Cold Sealing, Adhesive, Strapping |
| Companies Covered | Jornen Machinery Co., Ltd., ATS-Tanner, IMA S.p.A., Christ Packing Systems GmbH, Multipack Machinery LLC, Marchesini Group S.p.A., CARIBA s.r.l., Promach Packaging, Uhlmann Pac-Systeme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Banding Machine Market Strategic Shifts
Equipment architecture is pivoting from mechanical cam-driven systems toward servo-electric motion platforms that enable format changeover without tool intervention.
Ultrasonic banding heads are displacing thermal impulse sealing in temperature-sensitive pharmaceutical applications where heat exposure risks product degradation. Swiss and German packaging lines serving biologics and vaccine vials are specifying ultrasonic units at replacement rates exceeding thermal systems by a factor of three to one. This displacement is compressing the installed base of conventional heat-sealing equipment in high-value pharmaceutical segments.
REACH restrictions on persistent organic pollutants are tightening specifications for adhesive formulations used in cold-sealing banding films. European film converters are reformulating pressure-sensitive adhesives to eliminate siloxane contamination risks in food-contact applications. Pharmaceutical banding operations in Germany and France are responding by validating alternative adhesive chemistries that maintain seal integrity through distribution stress testing.
Contract packaging organizations are consolidating equipment procurement under outcome-based service agreements that bundle maintenance, consumables, and throughput guarantees. Large e-commerce fulfillment operators in the Netherlands and Belgium are shifting from capital purchase models to per-unit banding fees that align vendor incentives with uptime performance. This restructuring is visible most acutely in multi-tenant logistics facilities where equipment utilization rates drive total cost optimization.
Automatic Banding Machine Market Segmentation
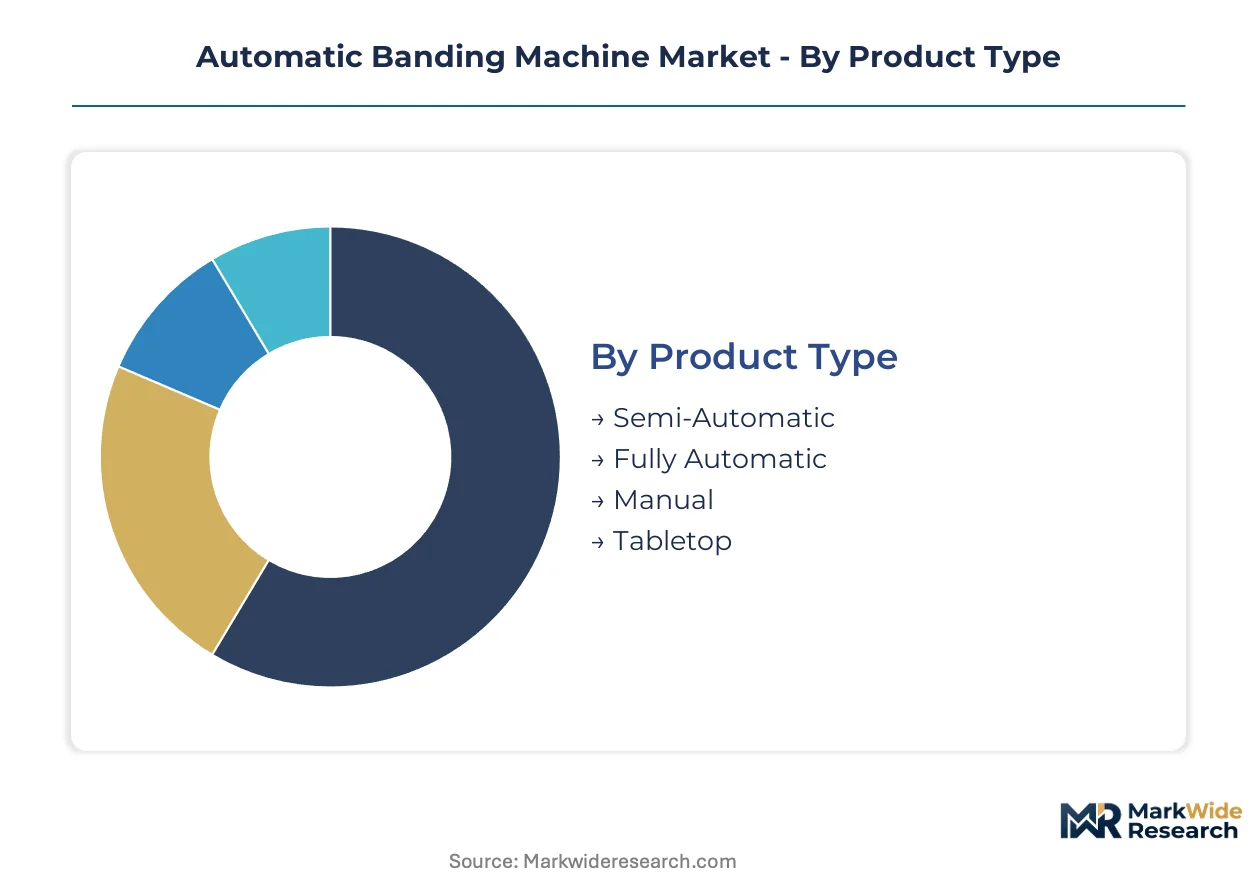
Automatic banding equipment serves divergent operational economics across fulfillment velocity tiers, regulatory exposure levels, and substrate compatibility requirements. Segmentation reveals where capital deployment concentrates and which technology platforms face displacement risk from adjacent packaging formats.
Product Type:
Semi-automatic architectures face acute substitution pressure from collaborative robotics and cobot-fed bundling stations in mid-volume operations.
- Fully Automatic:Servo-electric motion platforms integrate directly with upstream blister lines and downstream case packers, eliminating manual intervention. E-commerce fulfillment centers in Germany and the Netherlands specify these systems to achieve throughput above 60 cycles per minute. Labor cost arbitrage in Vietnamese contract packaging is accelerating penetration where wage inflation erodes manual banding economics.
- Semi-Automatic:Operator-fed designs occupy the cost-sensitive middle tier where volume fluctuates seasonally. Small-batch pharmaceutical contract packers in Switzerland retain these units for serialized product runs below 10,000 units per campaign.
- Manual:Hand-cranked banding tools persist in artisan food processing and micro-brewery distribution where capital constraints outweigh throughput needs.
- Tabletop:Compact footprint units serve specialty printing operations and boutique cosmetic packaging with changeover requirements below five minutes.
Fully automatic systems retain volume leadership; tabletop configurations hold the steepest expansion curve among capital-constrained entrants.
Application:
Application segmentation tracks regulatory density and contamination risk tolerance across end-use environments.
- Pharmaceutical:FDA cGMP and EMA Annex 1 requirements mandate stainless-steel construction, washdown capability, and OPC-UA serialization connectivity. German and Swiss biologics packers specify ultrasonic sealing heads to eliminate thermal degradation of temperature-sensitive vaccines.
- Food Processing:EU Regulation 1935/2004 and FDA food-contact substance notifications govern adhesive selection and film substrate compliance. REACH restrictions on siloxanes are forcing reformulation of pressure-sensitive cold-sealing films in French dairy operations.
- Packaging:General industrial bundling of corrugated displays and promotional multipacks represents the largest installed base by unit count. Heat-sealing polypropylene bands dominate retail-ready applications.
- Printing:Newspaper and direct-mail bundling requires gentle handling of ink-heavy substrates, favoring paper-based bands and adjustable tension controls.
Pharmaceutical applications command the highest equipment margins; food processing delivers the broadest geographic deployment base.
End User:
End-user concentration is shifting from traditional wholesale channels toward direct-to-consumer fulfillment infrastructure.
- E-Commerce:Multi-tenant logistics facilities in Belgium and the Netherlands are consolidating procurement under per-unit banding fee structures that align vendor incentives with uptime guarantees. Outcome-based service agreements now bundle maintenance, consumables, and throughput performance.
- Manufacturers:CPG brand owners with captive packaging lines prioritize line integration and MES connectivity over standalone machine economics. German automotive component suppliers specify fully automatic systems for just-in-time sequencing.
- Wholesale Distributors:Traditional volume bundling of mixed-SKU pallets faces compression from cross-dock automation and pre-sorted fulfillment models.
- Retailers:Private-label packaging operations and in-store fulfillment micro-hubs are emerging as niche demand pockets for compact semi-automatic units.
Manufacturers retain the largest installed equipment base; e-commerce operators are gaining share fastest in new capital deployment.
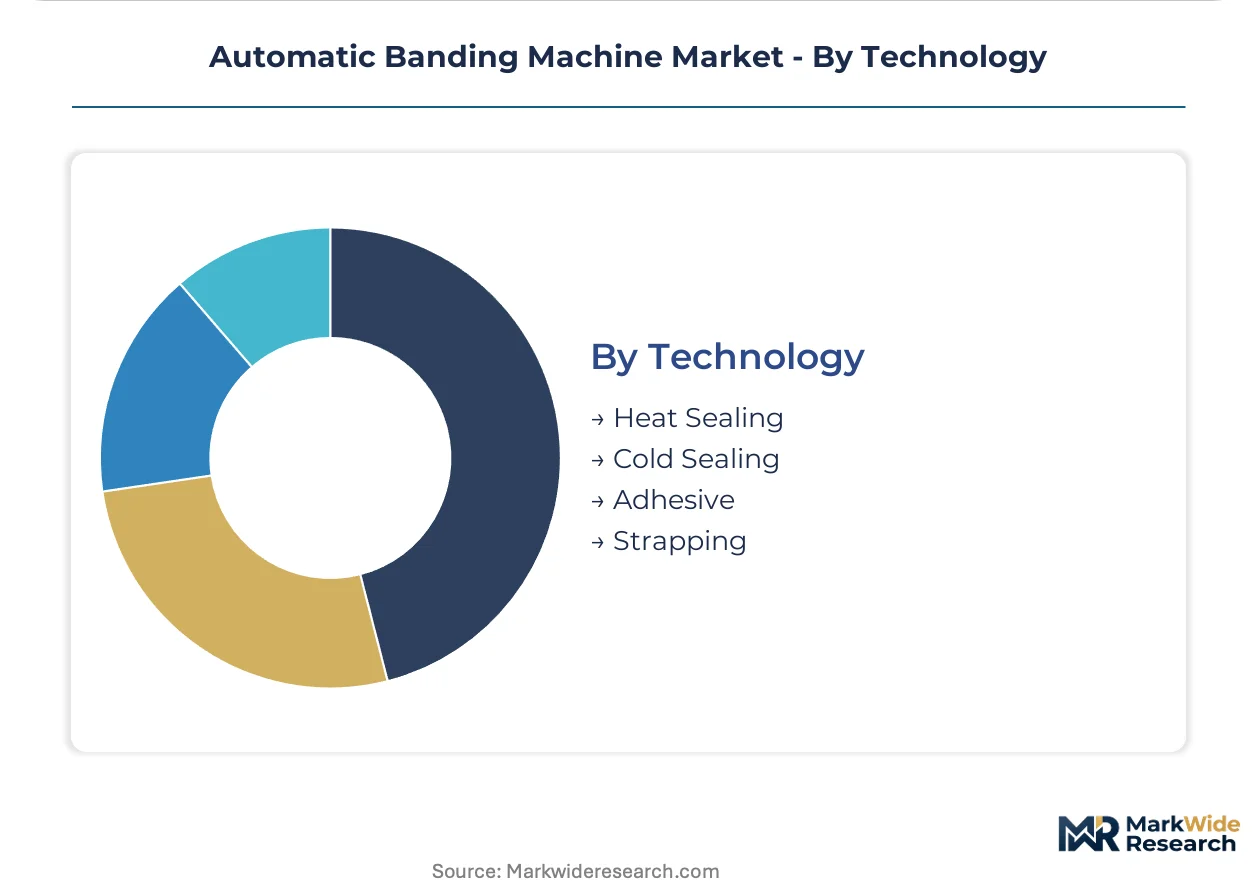
Technology:
Technology selection hinges on thermal exposure limits, cycle speed requirements, and substrate recyclability mandates.
- Heat Sealing:Thermal impulse and continuous hot-wire systems sustain the largest installed base, achieving 20-80 cycles per minute depending on band width. German pharmaceutical contract packers specify high-speed architectures to match blister-line speeds exceeding 600 units per minute.
- Ultrasonic:Friction-welding heads are displacing thermal systems in temperature-sensitive biologics packaging where heat risks protein degradation. Swiss vaccine vial lines specify ultrasonic units at replacement rates exceeding thermal systems by three to one.
- Cold Sealing:Adhesive-based closure faces throughput ceilings below 40 cycles per minute, constraining deployment in high-volume e-commerce sortation despite advantages for heat-sensitive substrates.
- Strapping:Polypropylene and PET strap systems compete with banding in heavy-load industrial applications, though banding retains advantages in retail-ready presentation and paper-based substrate compatibility.
Heat sealing maintains volume leadership; ultrasonic technology is climbing the fastest as pharmaceutical regulatory density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' role as Europe's primary e-commerce fulfillment gateway, with automated banding systems deployed across multi-tenant logistics facilities handling parcel volumes exceeding regional peers.
Germany
Precision engineering clusters around Stuttgart and Munich anchor regional supply chains for pharmaceutical-grade banding equipment. CE marking under the EU Machinery Directive mandates emergency-stop integration and guard interlocking, accelerating replacement cycles for legacy machinery. Bavarian biologics packers specify ultrasonic sealing heads to match blister-line speeds exceeding 600 units per minute.
United States
FDA cGMP guidelines shape sanitary design requirements for pharmaceutical banding applications, with stainless-steel construction mandated for washdown capability. OSHA lockout/tagout standards influence maintenance-access architecture in North American installations. Greater Boston's contract packaging corridor concentrates demand for serialized secondary packaging systems.
Switzerland
Swissmedic regulations govern pharmaceutical packaging validation requirements, with Swiss engineering heritage dominating high-speed heat-sealing installations. The country's precision manufacturing base supports specialized equipment for temperature-sensitive vaccine vial packaging. Basel's pharmaceutical cluster drives specification of ultrasonic banding heads at replacement rates exceeding thermal systems.
India
CDSCO-certified banding equipment demand rises among contract manufacturers supplying FDA-regulated markets with serialized secondary packaging. The country's pharmaceutical export expansion creates specification windows for equipment meeting dual regulatory compliance. Gujarat's contract manufacturing clusters concentrate procurement of fully automatic systems for high-volume export production.
Vietnam
Labor cost arbitrage accelerates penetration of fully automatic systems in contract packaging operations where wage inflation erodes manual banding economics. The country's integration into regional electronics supply chains drives demand for retail-ready bundling equipment. Ho Chi Minh City's logistics corridors concentrate e-commerce fulfillment infrastructure requiring high-throughput banding solutions.
Automatic Banding Machine Market Competitive Environment
Concentration sits with precision-engineering specialists and diversified packaging conglomerates serving distinct velocity tiers. Swiss and German fabricators dominate pharmaceutical-grade specifications through heritage positioning, while Asian manufacturers capture cost-sensitive volume segments. Three archetypes define competitive structure: heritage precision houses, scale-oriented volume producers, and integrated line solution providers. Strategic moves center on servo-electric platform development and outcome-based service contracting that bundles maintenance with throughput guarantees.
Within the heritage precision tier, ATS-Tanner exemplifies Swiss engineering positioning for high-value pharmaceutical applications. Jornen Machinery Co., Ltd. occupies the scale-driven segment with cost-optimized architectures purpose-built for Asian packaging volumes. Marchesini Group S.p.A. anchors the integrated solutions archetype, extending equipment offerings from banding through final case packing to capture line-integration premiums.
| Leading Market Players |
|---|
| Jornen Machinery Co., Ltd. |
| ATS-Tanner |
| IMA S.p.A. |
| Christ Packing Systems GmbH |
| Multipack Machinery LLC |
| Marchesini Group S.p.A. |
| CARIBA s.r.l. |
| Promach Packaging |
| Uhlmann Pac-Systeme |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation simultaneously, forcing mid-tier OEMs to absorb certification costs while premium Swiss and German fabricators capture margin premiums through heritage positioning.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade ultrasonic systems from standard heat-sealing equipment and entry-level semi-automatic units. Price differentiation hinges on FDA cGMP certification tier and servo-electric motion platform integration. Cost compression in the mid-tier is intensifying because stainless steel input volatility erodes fixed-price contract economics. E-commerce fulfillment operators exhibit the highest price sensitivity, while biologics packers prioritize seal integrity over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor precision fabrication of pharmaceutical-grade banding heads, while China and Vietnam feed cost-optimized mechanical assemblies for Asian contract packaging. 304-grade stainless steel, Japanese servo drives, and German PLCs constitute critical input dependencies. Single-source vulnerability in control system sourcing creates lead-time risk for mid-tier OEMs. Distribution runs through direct OEM sales for integrated line solutions and regional distributors for standalone equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are recovering from regulatory-driven compression, with EU Machinery Directive compliance mandates and FDA cGMP upgrades synchronizing demand pulses across pharmaceutical and food processing verticals.
For Market Incumbents: Compound defensive positioning through captive supply of ultrasonic sealing heads and backward integration into servo-drive tuning capabilities. Consolidate service contracting capabilities to counter outcome-based procurement shifts among Dutch and Belgian e-commerce operators. Defend margin structure by locking in multi-year consumables agreements with German automotive component suppliers. For New Entrants and Emerging Players: Aftermarket retrofit kits for legacy MES integration represent the most penetrable service-layer gap, as pharmaceutical manufacturers demand OPC-UA connectivity bridges without full line replacement. Target Indian CDSCO-certified contract manufacturers with dual-compliance equipment architectures. Lead with per-unit banding fee structures to bypass capital purchase barriers in Vietnamese wage-inflation markets. For Investors and Strategic Acquirers: EU Green Deal packaging waste directives reshape the acquisition landscape by elevating paper-based substrate specialists above polypropylene-dependent incumbents. Five-to-ten year viability favors vertically integrated precision houses with in-house film converting capabilities. Monitor REACH adhesive reformulation timelines as inflection indicators for cold-sealing technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | ATS-Tanner and Marchesini Group capture format-changeover premiums through tool-free architecture. |
| Outcome-Based Service Contracting | Dutch logistics operators align vendor incentives with uptime guarantees through per-unit banding fees. |
| Ultrasonic Sealing Head Expansion | Swiss biologics packers specify friction-welding units at triple the replacement rate of thermal systems. |
| Backward Integration into Film Converting | German OEMs control substrate recyclability specifications ahead of EU Green Deal mandates. |
| OPC-UA Connectivity Layer Development | Legacy MES bridge solutions unlock pharmaceutical serialization compliance without controller replacement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across equipment procurement, plant engineering, and aftermarket service functions. Primary interviews with packaging line managers, OEM sales directors, and MES integration specialists were cross-referenced against secondary validation from FDA 483 inspection databases, EMA regulatory guidance documents, EU Machinery Directive technical files, and customs trade records for stainless steel processing equipment. Bottom-up equipment shipment tallies and top-down end-use demand estimates were triangulated to anchor volume forecasts.
Across the analysis window, projections incorporate product type, application regulatory tier, technology platform, and end-user procurement model segmentation dimensions. CAGRs were derived from regression analysis of historical replacement cycle data and regulatory compliance deadline clustering. Forecast inputs include blister-line speed specifications from German pharmaceutical packers and wage inflation trajectories in Vietnamese contract manufacturing.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and FDA cGMP inspection intensity; material policy shifts would require re-modeling. Stainless steel commodity volatility and REACH adhesive restrictions constitute specific revision triggers for equipment margin and technology mix assumptions. Recalibration cycles align with material shifts in regulatory deadline clustering and e-commerce fulfillment infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Global Wrapping Machine Market