
 Angel Funds Market | 2026-2036
Angel Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Angel Funds Market Analysis
Institutional-grade due diligence standards is bifurcating the angel funds landscape into professionalized and amateur pools. 500 Global leverages structured accelerator-to-fund pipelines across multiple geographies. Y Combinator sustains unmatched dealflow density through its batch selection model. Techstars anchors regional innovation ecosystems with localized fund-deployment strategies.
Angel funds represent pooled capital vehicles through which accredited individuals and small groups invest equity in pre-revenue or early-revenue private companies, typically deploying rounds between $50K and $1M with governance rights structured through simple agreements for future equity or preferred share instruments. Seed-stage deployment leads transaction volume as founders seek capital before institutional venture capital thresholds. Individual angels and syndicate structures capture the fastest growth trajectory as platform-enabled co-investment tools reduce administrative friction. Technology and fintech verticals concentrate margin pools where valuation multiples and exit liquidity exceed healthcare and consumer goods benchmarks.
SEC registration requirements under Rule 506(b) and 506(c) of Regulation D shape market access by defining accredited investor thresholds and general solicitation permissions for fund managers in the United States. SEBI's AIF regulations in India mandate fund size minimums and lock-in periods that filter participant quality. The EU's MiFID II framework and national angel tax incentives across Germany, France, and the Netherlands influence cross-border capital formation. Stakeholders must monitor evolving definitions of accredited investor status and platform-based syndication compliance as regulatory technology automates disclosure obligations.
Market Dynamics
Platform-enabled syndication infrastructure is fragmenting capital deployment authority, shifting deal origination from concentrated fund managers toward distributed networks of accredited individuals operating through SPV structures.
Growth Catalysts
- SEBI AIF Regulations:India's streamlined registration framework for Category I alternative investment funds reduces compliance overhead for emerging managers, accelerating domestic capital formation into seed-stage ventures.
- Blockchain-based cap table management:Distributed ledger infrastructure automates equity tracking and governance rights execution, reducing administrative friction for cross-border syndicates.
- Singapore's Variable Capital Company framework:The jurisdiction's flexible fund structuring vehicle attracts Asia-Pacific fund managers seeking operational agility for multi-currency deployment.
Market Restraints
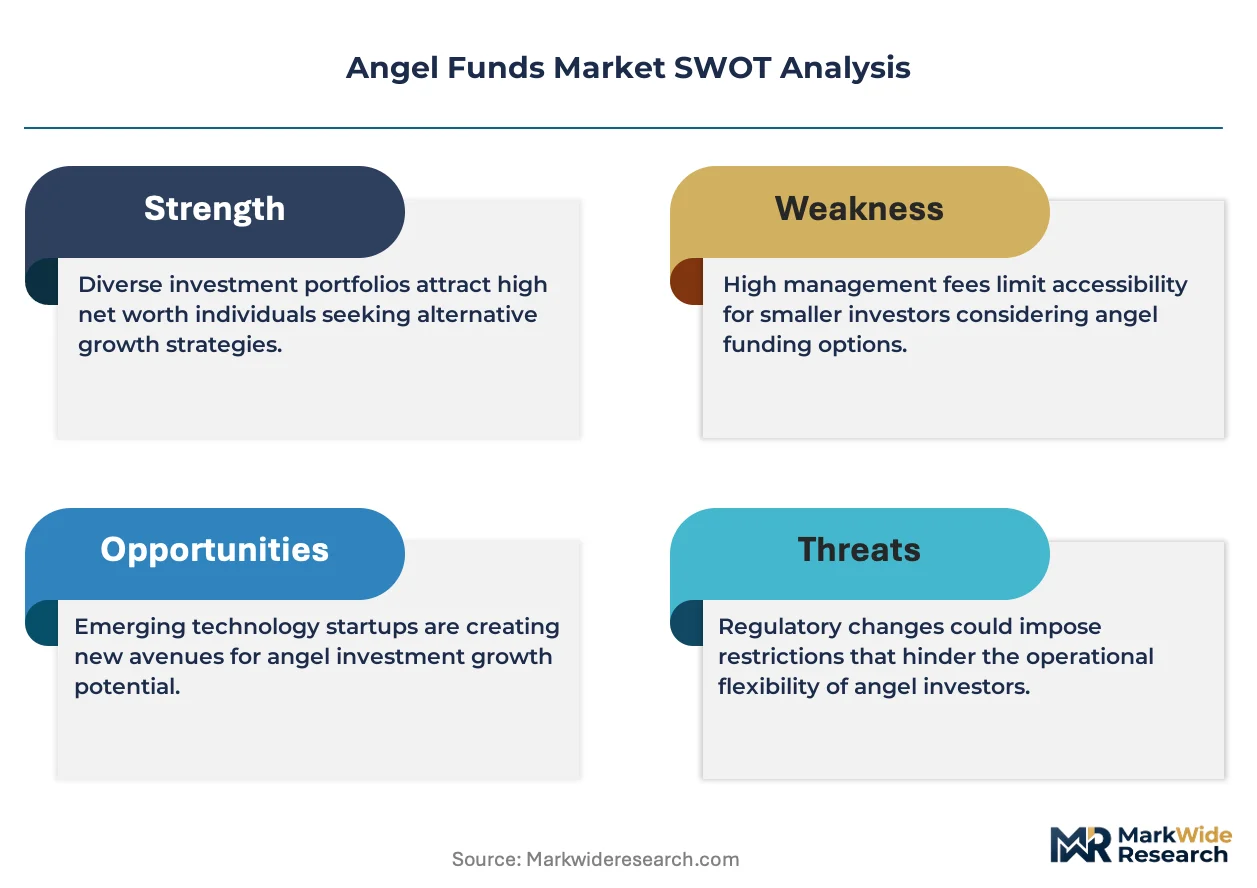
- Accredited investor threshold rigidity:SEC Rule 501 definitions restrict participation pools, excluding sophisticated non-accredited individuals from high-quality dealflow despite sufficient risk capacity.
- Valuation information asymmetry:Pre-revenue startups lack standardized benchmarking methodologies, creating adverse selection risks for incoming limited partners.
- Carried interest taxation uncertainty:Pending legislative proposals in multiple jurisdictions threaten after-tax returns for general partners, dampening fund formation incentives.
Strategic Opportunities
- Climate-tech vertical specialization:IRA-aligned deployment into clean energy startups captures policy-mandated capital flows unavailable to generalist funds.
- Secondary market infrastructure:Platform-enabled LP interest trading addresses the traditional ten-year lock-in constraint, unlocking liquidity for early-stage fund participants.
- University endowment co-investment:Institutional limited partners are direct co-investment rights alongside established managers, reducing fee drag on educational institution portfolios.
Industry Challenges
- Due diligence talent scarcity:Technical assessment capabilities for deep-tech startups concentrate in venture capital firms, leaving angel syndicates dependent on outsourced expertise.
- Cross-border securities compliance:Multi-jurisdictional SPV structures trigger overlapping disclosure obligations under SEC Regulation S and national prospectus requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angel Funds Market |
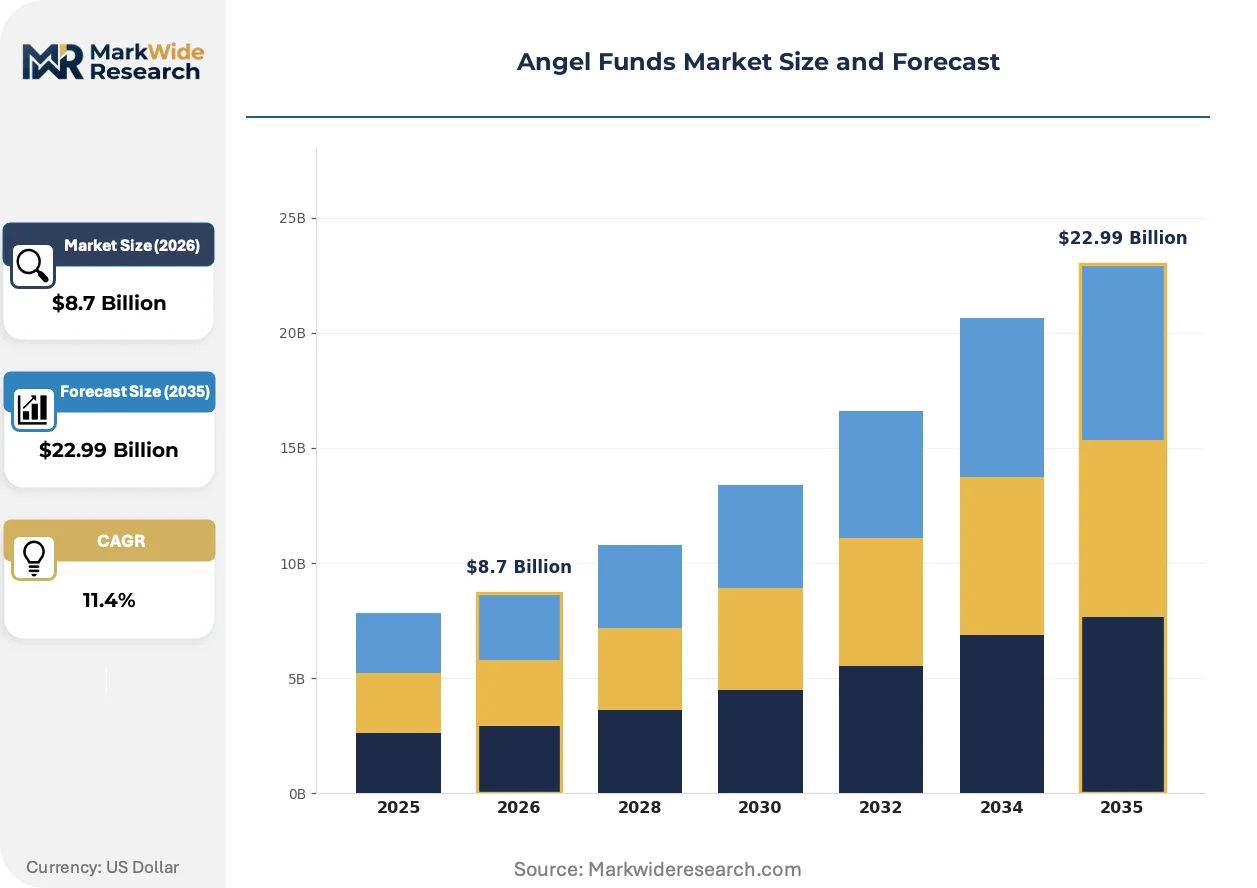
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Stage, Expansion, Bridge Investor Type: Individual Angels, Angel Groups, Syndicates, Venture Capitalists Funding Size: Under $50K, $50K-$250K, $250K-$1M, Over $1M Industry Vertical: Technology, Healthcare, Consumer Goods, Fintech |
| Companies Covered | Aussie Angels, Icarus Ventures, AngelList, 500 Global, Techstars, COREangels, Sangatna Angels Venture, Y Combinator, aVenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angel Funds Market Emerging Trajectories
Automated investment infrastructure is compressing the traditional fund formation timeline, enabling capital deployment within weeks rather than quarters through modular legal architecture and pre-negotiated term templates.
Special purpose vehicle administration software is fragmenting the market for fund management services, allowing individual angels to launch compliant investment vehicles without traditional administrator relationships. Early adopters include former operators with sector expertise seeking direct deployment control. The technology is compressing minimum viable fund sizes and expanding participant pools beyond established financial centers.
EU's proposed European Single Access Point for financial data will standardize disclosure formats across member states, reducing cross-border fundraising friction for fund managers operating under national AIFM implementations. The industrial consequence involves harmonized reporting that lowers compliance duplication. France, Germany, and Netherlands-based managers are pre-positioning data infrastructure to capture first-mover advantages.
LP preference is rotating toward concentrated exposure models, with limited partners bypassing diversified fund structures to build direct portfolios of 8-12 high-conviction positions. This behavior disrupts traditional fund-of-funds intermediaries and fee structures. The shift is most visible among family offices in Switzerland and Singapore seeking governance control over underlying assets.
Angel Funds Market Segmentation
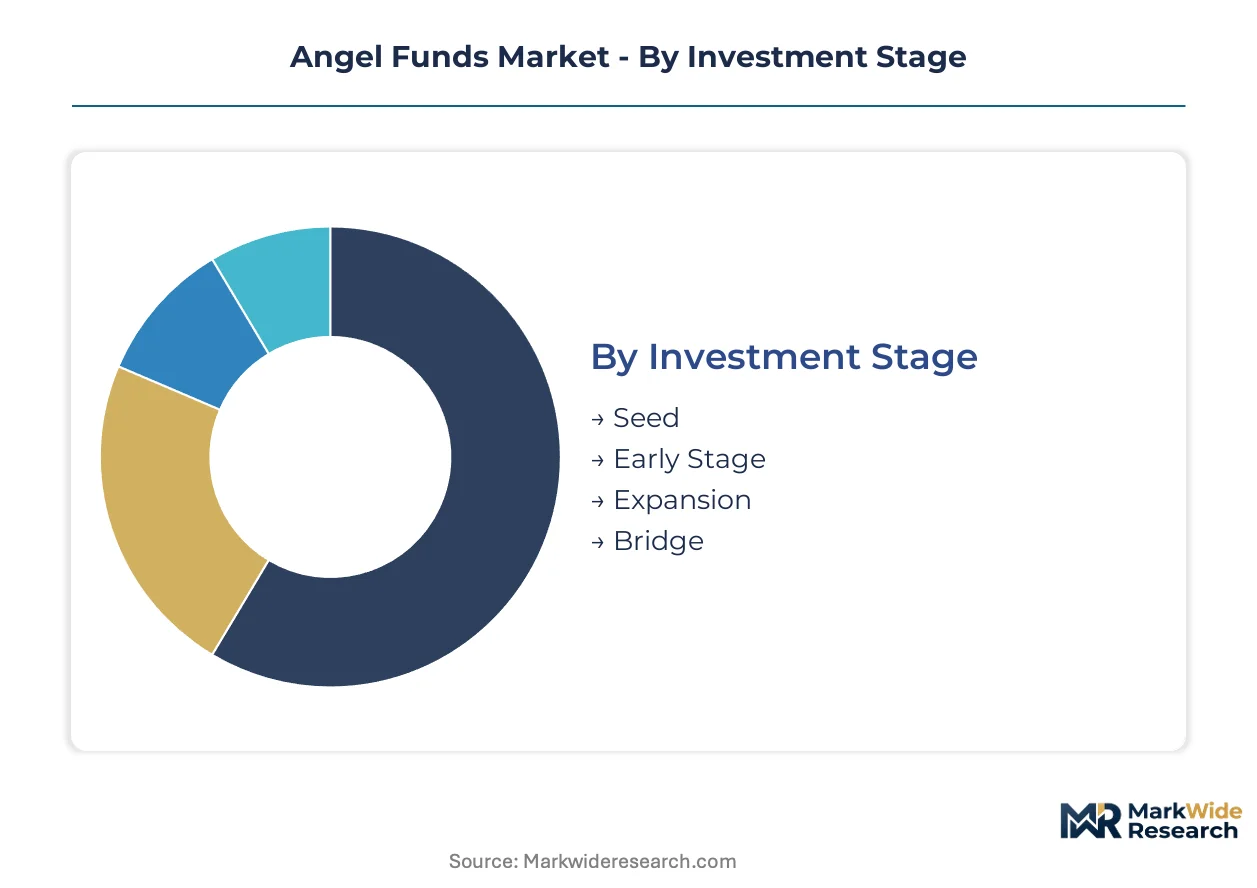
Angel funds deploy through distinct capital channels shaped by investor sophistication thresholds and regulatory access tiers. Each segmentation dimension reveals how deal flow concentrates across funding mechanisms and governance structures.
Investment Stage:
Capital channel mix varies sharply across stages, with platform-enabled syndicates dominating seed deployment while institutional vehicles capture later rounds.
- Seed:First institutional capital into pre-revenue ventures, typically structured through simple agreements for future equity. Demand concentrates in India where SEBI-registered Category I AIF vehicles channel domestic capital into founder teams before revenue proof points.
- Early Stage:Post-revenue deployment into product-market fit validation, often syndicated across multiple angel groups. Expansion concentrates in technology clusters where 500 Global and Techstars accelerator pipelines feed qualified dealflow to participating investors.
- Expansion:Follow-on rounds supporting customer acquisition and team scaling. Bridge financing for ventures approaching Series A thresholds.
- Bridge:Short-term capital extending runway to priced equity rounds, typically structured as convertible notes.
Seed dominates installed base. Early Stage is where expansion concentrates.
Investor Type:
Cost tier stratification separates high-touch individual participation from scalable platform infrastructure.
- Individual Angels:Solo accredited investors deploying personal capital through direct relationships or platform-enabled access. Former operators with sector expertise in fintech and enterprise software represent the fastest-climbing participant pool as SPV administration software reduces formation friction.
- Angel Groups:Organized networks pooling due diligence resources and negotiating leverage through structured membership. Demand clusters in metropolitan innovation corridors where monthly pitch events sustain dealflow velocity.
- Syndicates:Lead investors sourcing opportunities and inviting backer participation through platform-mediated SPVs. Carry structures align incentives while reducing administrative burden for participants.
- Venture Capitalists:Institutional funds co-investing or leading rounds above typical angel thresholds, often bridging to traditional Series A.
Syndicates are gaining share fastest. Individual Angels retain the deepest penetration in first-check markets.
Funding Size:
Volume distribution skews toward smaller checks, though margin pools concentrate in larger structured rounds.
- Under $50K:Friends-and-family extensions and first-check testing rounds, often undocumented or structured as convertible notes.
- $50K-$250K:Standard seed participation tier where platform syndicates aggregate multiple backers into single SPVs. This tier captures the steepest expansion trajectory as automated investment infrastructure compresses formation timelines.
- $250K-$1M:Lead investor rounds establishing governance rights and board observation. Institutional angels and micro-VCs concentrate here.
- Over $1M:Pre-angel fund or solo GP structures approaching traditional venture thresholds, requiring SEC Rule 506(c) compliance for general solicitation.
$50K-$250K dominates transaction count. $250K-$1M is where fee efficiency and governance rights justify structural complexity.
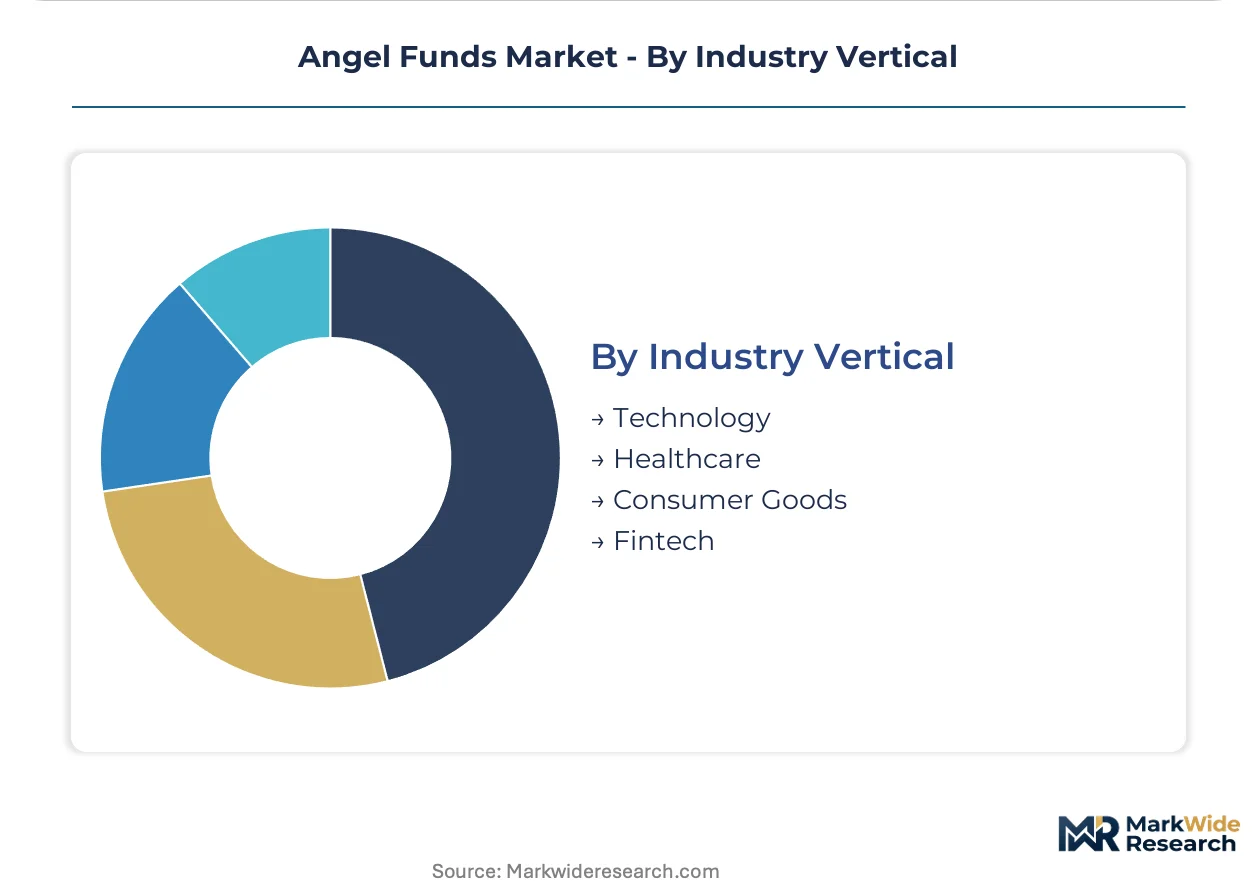
Industry Vertical:
Margin differentiation separates technology-enabled models from capital-intensive sectors.
- Technology:Software and infrastructure startups with near-zero marginal distribution costs. SaaS and developer tools concentrate dealflow in Y Combinator and Techstars pipelines.
- Fintech:Embedded finance and B2B payments platforms benefiting from regulatory sandbox access. Singapore's Variable Capital Company framework attracts Asia-Pacific managers targeting this vertical.
- Healthcare:Regulatory complexity and longer development timelines filter participant quality, concentrating capital among specialized angels with clinical or biotech operating backgrounds.
- Consumer Goods:Physical product development requiring inventory capital and supply chain expertise, attracting fewer pure financial investors.
Technology anchors deployment volume. Fintech is climbing the fastest on policy-mandated capital flow capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital export-import dynamics reshape angel fund deployment patterns as managers seek regulatory arbitrage and dealflow density. Jurisdictions with streamlined fund formation attract foreign manager registration while domestic capital pools concentrate in innovation clusters.
United States
SEC Rule 506(c) general solicitation permissions unlock broader capital pools for emerging managers, while Rule 506(b) maintains traditional private placement pathways. The IRA's clean energy tax credits channel policy-mandated capital toward climate-tech verticals. San Francisco and New York anchor dealflow velocity through accelerator-to-fund pipelines feeding qualified opportunities to accredited networks.
India
SEBI-registered Category I AIF vehicles accelerate domestic capital formation into seed-stage ventures as emerging managers exploit streamlined compliance frameworks. The central bank's payment infrastructure modernization supports fintech startup proliferation. Bangalore and Mumbai concentrate fund manager registration activity alongside founder density in enterprise software and embedded finance.
Singapore
The Variable Capital Company framework attracts Asia-Pacific fund managers seeking operational agility for multi-currency deployment across Southeast Asian dealflow. The Monetary Authority of Singapore's regulatory sandbox reduces friction for fintech-focused fund vehicles. The city-state's fund administration ecosystem supports cross-border syndicate structures serving Indonesian and Vietnamese startup markets.
Germany
EU-wide MiFID II harmonization combines with national angel tax incentives to structure cross-border capital formation for early-stage ventures. The country's national financial regulator supervises AIFM implementations that standardize disclosure obligations. Berlin's startup cluster concentrates dealflow in B2B software and climate-tech verticals as Munich anchors deep-tech assessment capabilities.
United Kingdom
Seed Enterprise Investment Scheme tax reliefs sustain individual angel participation rates despite post-Brexit regulatory divergence from EU frameworks. The Financial Conduct Authority's alternative investment fund rules shape manager registration requirements. London's fintech corridor concentrates syndicate lead investors sourcing opportunities across European time zones.
Angel Funds Market Vendor Landscape
Listed fund-of-funds platforms compete with private specialist managers across dealflow access and fee compression vectors. Market structure fragments across accelerator-linked vehicles, platform-enabled syndicates, and traditional angel networks. Three archetypes dominate: batch-selection accelerators with embedded fund capacity, software-mediated syndication platforms, and sector-specialized operator-led vehicles. Competitive moves concentrate on geographic expansion through localized accelerator licensing and secondary market infrastructure development.
Within the accelerator-linked tier, Y Combinator and Techstars exemplify dealflow density models, while AngelList occupies a position in platform-enabled syndication infrastructure. These entities represent distinct approaches to capital deployment authority fragmentation.
| Leading Market Players |
|---|
| Aussie Angels |
| Icarus Ventures |
| AngelList |
| 500 Global |
| Techstars |
| COREangels |
| Sangatna Angels Venture |
| Y Combinator |
| aVenture |
| Others |
Supply Flow & Price Mechanics
Carried interest waterfall structures lock in general partner compensation visibility while anchoring limited partner return expectations across multi-year fund lifecycles. These contractual frameworks tie management fee schedules to deployment velocity and distribution timing, creating pricing rigidity that resists short-term fee compression despite platform-enabled alternatives entering the market.
Pricing Analysis
Institutional limited partners anchor pricing structures through negotiated fee schedules that stratify across fund size tiers and track record premiums. Pricing models center on the classic two-and-twenty framework, with emerging managers accepting compressed management fees below 2% to secure initial capital commitments. Price differentiation hinges on fund manager pedigree and sector specialization depth, with climate-tech and fintech verticals commanding premium carry structures due to policy-mandated capital flow density. Pricing pressure stems from platform-enabled syndicates offering zero-management-fee access to curated dealflow, forcing traditional funds toward performance-only compensation models. Family offices and university endowments exhibit highest price sensitivity, while sovereign wealth vehicles prioritize access over fee minimization.
Supply Chain Analysis
The United States and India anchor fund formation infrastructure, with Delaware limited partnerships and SEBI-registered Category I AIF vehicles serving as dominant structuring vehicles for capital deployment. The supply chain draws from legal administration services in Singapore and the Cayman Islands for cross-border SPV formation, alongside compliance technology providers automating accredited investor verification and regulatory disclosure. Single-source vulnerability concentrates in platform-dependent dealflow access, where AngelList and syndicate lead networks control origination pipelines for non-institutional capital. Distribution runs through registered investment advisors and multi-family offices serving as gatekeepers to qualified purchaser networks, with direct-to-investor channels expanding through automated subscription documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-enabled syndication infrastructure threatens traditional fund-of-funds intermediation, substituting direct LP access to curated dealflow for layered fee structures that erode net returns.
For Market Incumbents: Secure exclusive accelerator pipeline partnerships with Y Combinator and Techstars to lock in proprietary dealflow before platform syndicates fragment origination authority. Build captive due diligence capabilities for deep-tech verticals rather than outsourcing technical assessment to venture capital firms. Vertical integration into secondary market infrastructure addresses the ten-year lock-in constraint that drives LP preference toward direct co-investment structures. For New Entrants and Emerging Players: SEBI's streamlined Category I AIF registration fast-tracks market entry for managers targeting India's seed-stage capital formation acceleration. White-space concentrates in climate-tech vertical specialization where IRA-aligned deployment captures policy-mandated capital flows unavailable to generalist competitors. Target university endowment direct co-investment rights as the most penetrable LP segment, offering governance transparency and fee reduction that fund-of-funds structures cannot match. For Investors and Strategic Acquirers: Capital is best deployed toward sector-specialized operator-led vehicles with demonstrated technical assessment capabilities for deep-tech startups. Long-term viability across the analysis window favors managers with embedded accelerator relationships and automated investment infrastructure compressing formation timelines. The signal to watch is regulatory technology adoption velocity, as automated disclosure obligations reshape compliance cost structures and competitive moats for emerging managers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | AngelList's syndicate infrastructure fragments capital deployment authority toward distributed accredited networks. |
| Geographic Expansion | Localized accelerator licensing in Bangalore and Singapore captures Asia-Pacific dealflow density. |
| Acquisition of Specialist Firm | SPV administration software targets reduce minimum viable fund sizes below traditional administrator thresholds. |
| Strategic Partnership | University endowment co-investment rights reduce fee drag while securing governance control for institutional LPs. |
| Product Launch | Secondary market infrastructure addresses ten-year lock-in constraints unlocking liquidity for early-stage participants. |
Methodological Framework
Cross-validation between primary interviews with fund managers, limited partners, and regulatory technology providers anchors the qualitative findings alongside secondary validation through SEBI registration databases, SEC Form D filings, and accelerator pipeline disclosures. The analysis combines bottom-up triangulation of individual fund vehicles with top-down assessment of capital formation trends across jurisdictions. Stakeholder roles engaged include general partners at SEBI-registered AIFs, family office investment officers, platform syndicate leads, and compliance technology vendors automating accredited investor verification.
Sensitivity analysis around regulatory threshold adjustments and platform adoption velocity shapes the forecast framework across the projection horizon. Segmentation dimensions modeled include investment stage, investor type, funding size tier, and industry vertical with geographic regulatory cluster overlay. CAGRs derive from installed base expansion rates and capital commitment velocity by fund vehicle type, with inputs incorporating SEBI registration trajectories and Rule 506(c) general solicitation filing patterns.
Decision-makers should treat outputs as directional under sustained accredited investor threshold rigidity and platform infrastructure adoption assumptions; material deviation in either driver would warrant model refresh. Specific risk factors include pending carried interest taxation legislation and evolving definitions of qualified purchaser status. Recalibration cycles align with material shifts in regulatory technology automation and cross-border securities compliance harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Crowdfunding Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Business Incubator Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
North America Venture Capital Market
Venture Capital
Micro VC Funds Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
United States Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Europe Venture Capital Market
Venture Capital
US Venture Capital Investment Market