
 Vending Software Market | 2026-2036
Vending Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vending Software Market Insights
Modular software bundling is hardening as the dominant procurement pattern, with operators favoring subscription stacks that combine telemetry, cashless payments, and remote management rather than standalone modules. Nayax leverages its integrated hardware-software ecosystem to control the payment-processing layer across Europe and North America. Cantaloupe Systems anchors its position through deep vertical integration into device management and DEX data parsing. VendSoft competes on price-accessibility for small and mid-sized operators with lean cloud-native architectures.
Vending software comprises embedded and cloud-hosted applications that manage machine telemetry, transaction routing, inventory replenishment, and consumer engagement through protocols such as DEX/UCS and MDB interfaces. These systems enable operators to minimize stockouts, optimize route scheduling, and capture granular sales data across distributed machine networks. Cloud-based deployment leads in new installations due to lower upfront capital requirements and faster feature iteration, while API-based integration is displacing standalone configurations as enterprise buyers demand connectivity with ERP and warehouse management systems. Inventory management functionality sustains the largest user base, though analytics modules are capturing disproportionate margin expansion as operators monetize consumer behavior data.
FCC certification governs wireless communication modules in US-deployed vending devices, while PCI DSS Level 1 compliance shapes payment software architecture and vendor qualification. The EU AI Act introduces emerging obligations for algorithmic consumer engagement features such as dynamic pricing and personalized product recommendations. Stakeholders must weigh interoperability investments against the risk of stranded assets as regulatory fragmentation between EMVCo, GDPR, and emerging state-level privacy laws intensifies.
Market Dynamics
PCI DSS Level 1 certification mandates are compressing vendor qualification timelines while forcing hardware-software co-development cycles that favor integrated platform providers over point solutions.
Growth Catalysts
- EMVCo contactless mandates:Payment terminal certification requirements in the United States are accelerating cashless retrofit programs across convenience retail networks and workplace foodservice operators.
- Cloud telemetry architectures:Real-time DEX data streaming enables predictive replenishment algorithms that cut stockout rates and optimize route density for vending fleet operators.
- Workplace foodservice modernization:Corporate campus operators are replacing legacy mechanical machines with connected systems to support hybrid work schedules and 24/7 access demands.
Market Restraints
- Certification cost concentration:FCC wireless module validation and PCI DSS audit expenses create fixed cost barriers that disproportionately burden operators with sub-500 machine fleets.
- Hardware-software lock-in:Proprietary MDB interface implementations by dominant payment hardware suppliers create switching friction and limit multi-vendor software deployments.
- Cellular connectivity dependency:Recurring data plan costs for 4G/LTE modules erode margins in low-transaction-density locations such as rural corridors and secondary education campuses.
Strategic Opportunities
- EU AI Act algorithmic transparency:Early compliance with emerging European Union requirements for dynamic pricing and personalized recommendation engines creates first-mover positioning in automated retail.
- API-first integration demand:Enterprise buyers are unbundling vending management from ERP and warehouse management systems, opening white space for middleware specialists.
- Micro-fulfillment convergence:Locker-style pickup integration with last-mile delivery networks is expanding addressable machine formats beyond traditional snack and beverage configurations.
Industry Challenges
- DEX protocol fragmentation:Inconsistent data field implementations across machine OEMs force software vendors to maintain expensive device-specific parsing libraries.
- Legacy route management system integration:Established vending operators face multi-year migration timelines to reconcile decades-old dispatch software with cloud-native telemetry platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vending Software Market |
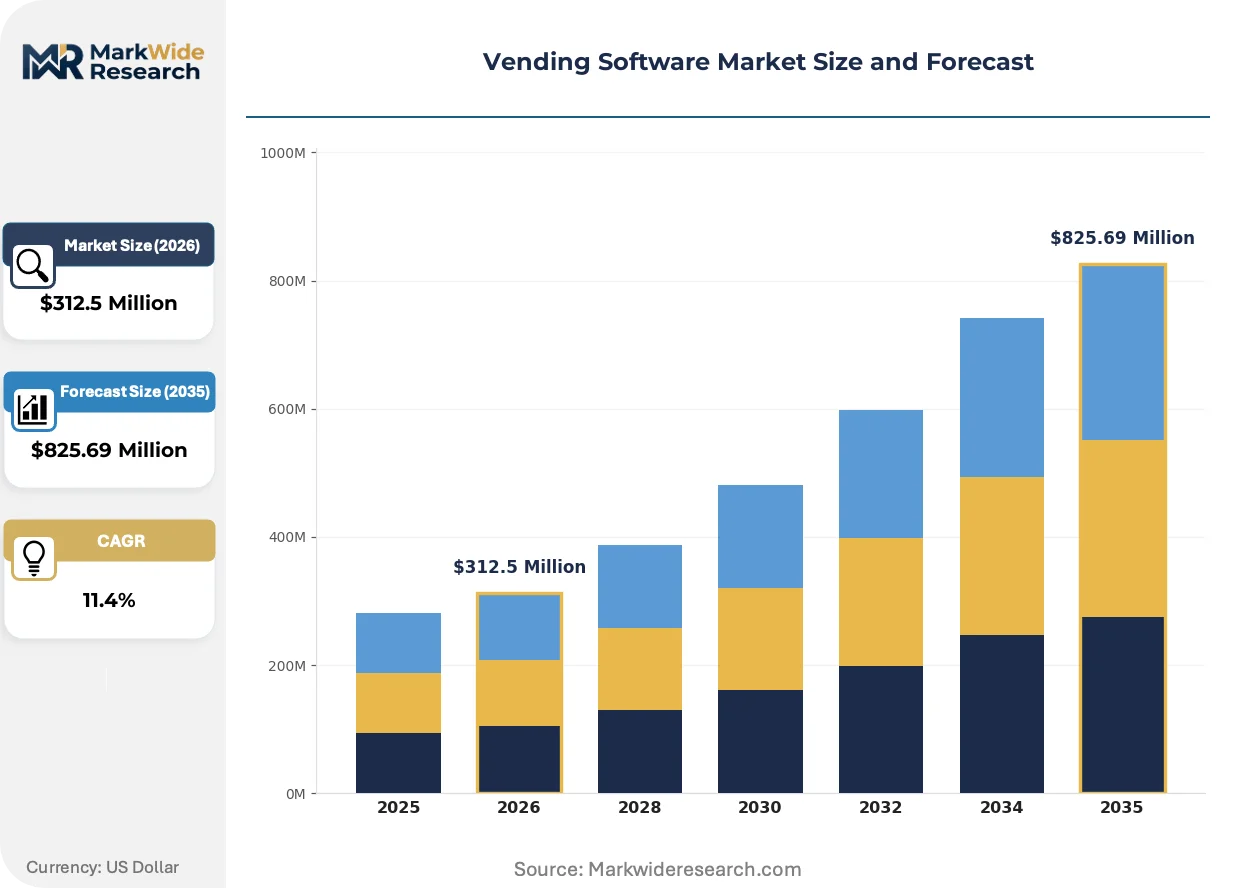
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Customer Type: Retailers, Operators, Manufacturers, Wholesalers Functionality: Inventory Management, Payment Processing, Analytics, Reporting Integration Level: Standalone, API-Based, ERP Integration, Third-Party Tools |
| Companies Covered | Nayax, Cantaloupe Systems, VendSoft, Parlevel Systems, VendingTrack, Crane Payment Innovations, USA Technologies, Vendon, Televend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vending Software Market Trends and Innovations
Software architecture choices are compressing competitive differentiation cycles as buyers prioritize interoperability over proprietary feature depth. Vendors are responding with open API strategies and modular deployment options.
Edge computing middleware is modularizing transaction processing workflows by pushing payment authorization and inventory logic closer to the machine controller. Mid-sized operators with 200-800 unit fleets are adopting these distributed architectures fastest, seeking to reduce cloud latency for high-frequency locations while maintaining centralized oversight. This topology is compressing the traditional distinction between embedded firmware and cloud-hosted management layers.
The EU AI Act is reshaping algorithmic consumer engagement by imposing documentation and audit requirements on dynamic pricing engines. Vending software vendors serving European Union deployments must now maintain explainability logs for recommendation systems that adjust product assortments based on time-of-day or weather patterns. Operators in Germany and France are front-loading compliance investments to avoid retrofit obligations when enforcement timelines crystallize.
Subscription bundling is displacing perpetual licensing across buyer segments as operators seek to convert capital expenditure into operational expenditure for financial reporting purposes. Large convenience retail networks are driving this transition, negotiating enterprise-wide telemetry and payment processing stacks rather than machine-by-machine procurement. This pattern is most pronounced in the United States, where private equity-backed vending consolidators are standardizing software estates across acquired regional operators.
Vending Software Market Segmentation
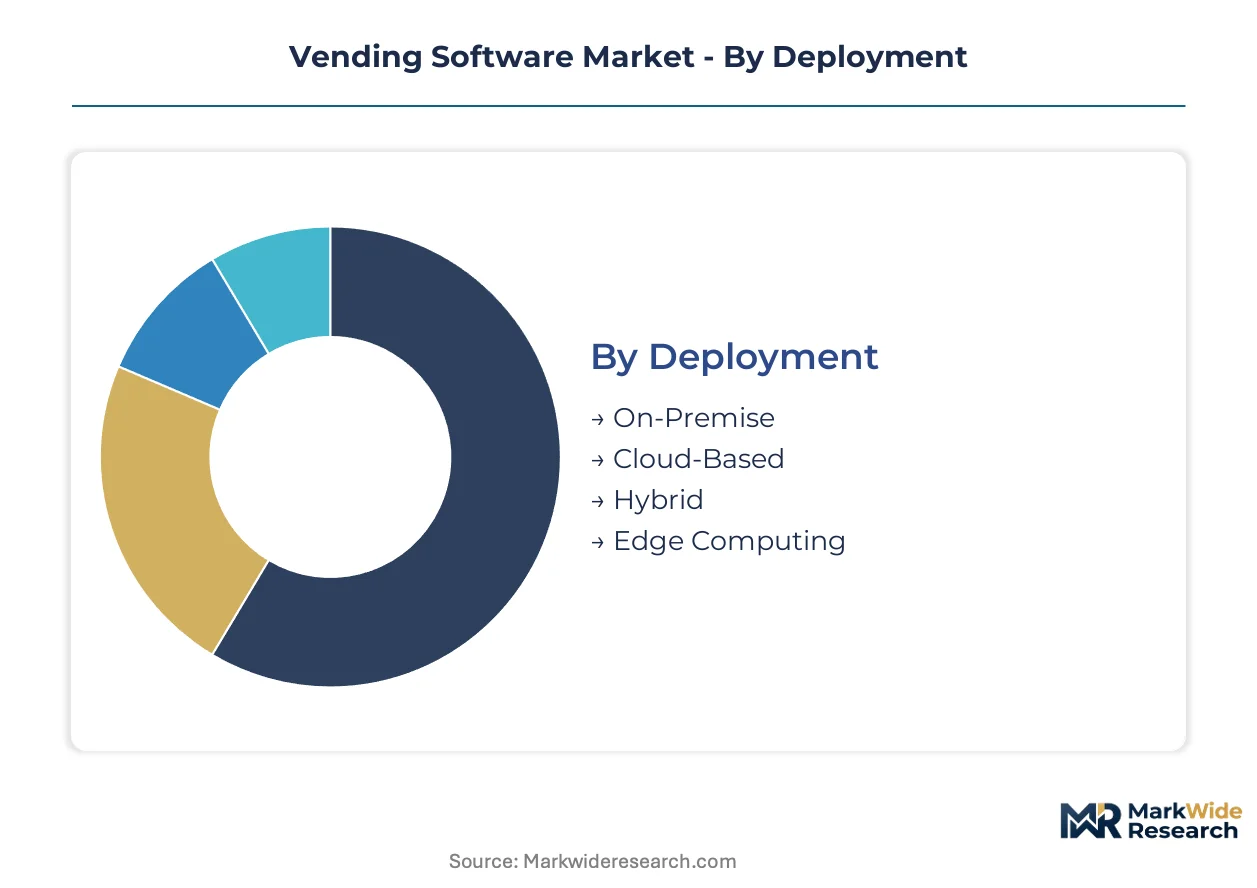
Vending software procurement patterns diverge sharply across deployment architectures and buyer sophistication. Operators with legacy machine fleets prioritize integration pathways over feature depth, while greenfield deployments favor modular cloud stacks.
Deployment:
Capital intensity and connectivity infrastructure separate buyers in this dimension.
- Cloud-Based:Centralized telemetry platforms stream DEX data through 4G/LTE or Wi-Fi to hosted dashboards. Demand concentrates among United States convenience retail networks seeking to consolidate multi-state machine visibility without on-site server maintenance. PCI DSS Level 1 certification burdens fall on vendors rather than operators.
- On-Premise:Local server installations retain transaction data within operator facilities, appealing to defense contractors and financial institutions with restricted-network mandates. Germany's Federal Office for Information Security guidelines reinforce this preference among European critical infrastructure operators.
- Hybrid:Split architectures process payments locally while pushing analytics to cloud repositories.
- Edge Computing:Distributed processing modules embed payment authorization and inventory logic at machine controllers.
Volume sits with Cloud-Based deployments; growth tilts toward Edge Computing.
Customer Type:
Technical staff depth and fleet scale drive purchasing authority differences.
- Operators:Route-based vending companies managing 200-10,000 machines represent the core revenue base. These buyers prioritize telemetry accuracy and route optimization algorithms over consumer-facing features. United States workplace foodservice contractors are consolidating vendor relationships to reduce integration overhead.
- Retailers:Convenience store chains and big-box retailers treat vending as ancillary revenue, demanding ERP connectivity and unified reporting across POS systems. API-first architectures gain traction here.
- Manufacturers:Machine OEMs embed software as bundled firmware or white-label management platforms.
- Wholesalers:Product distributors seek inventory visibility across consignment machines at client locations.
Operator spending dominates current bookings; retailer expansion offers the steepest trajectory.
Functionality:
Margin capture potential varies dramatically across module types.
- Inventory Management:Stock-level monitoring and automated replenishment triggers constitute the most-deployed capability. United States operators with dense urban routes leverage predictive algorithms to cut stockout rates. DEX protocol parsing remains the technical bottleneck.
- Analytics:Consumer behavior dashboards and assortment optimization tools command premium subscription tiers. France's CNIL guidelines on algorithmic transparency are reshaping feature roadmaps for EU deployments.
- Payment Processing:Cashless transaction routing and EMVCo certification management.
- Reporting:Compliance documentation and financial reconciliation exports.
Inventory Management anchors installed base; Analytics climbs the fastest.
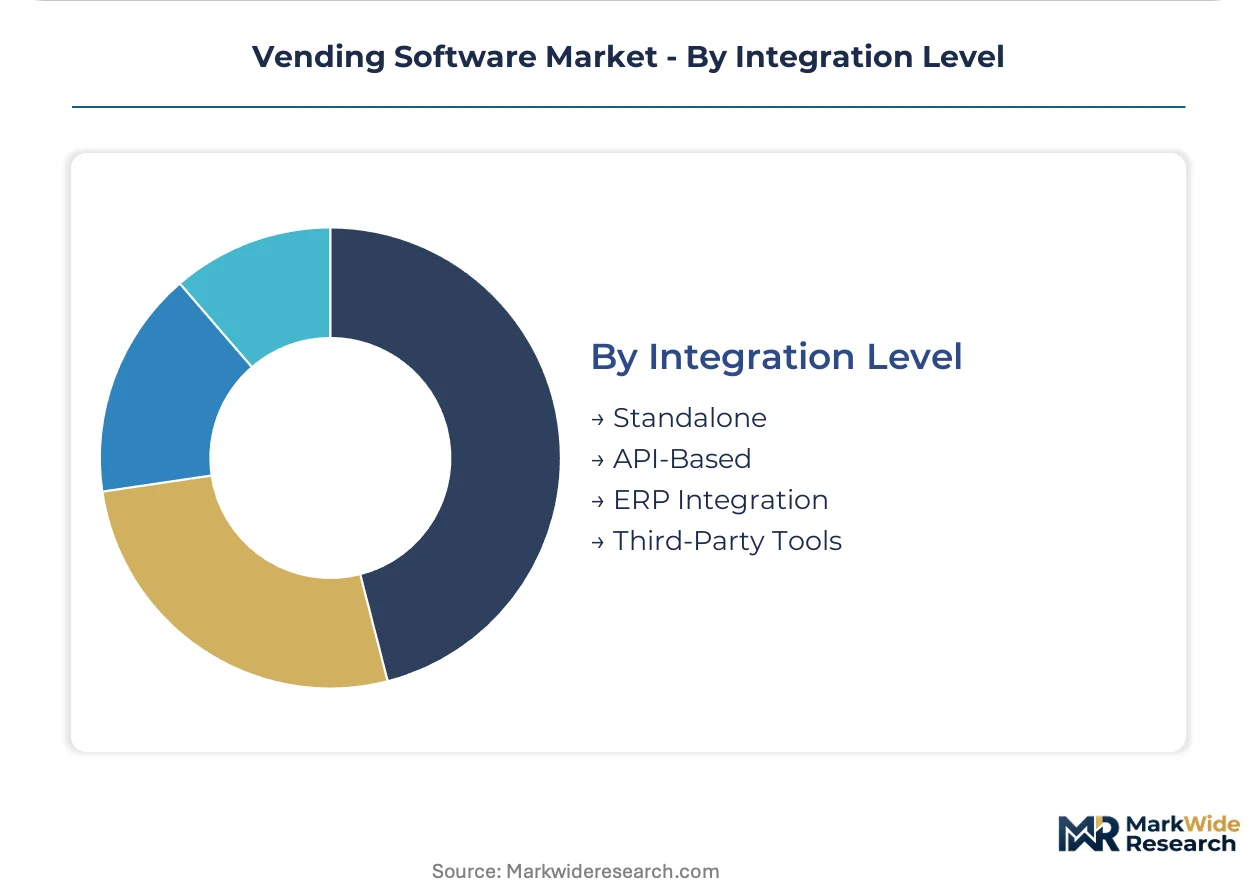
Integration Level:
Enterprise IT maturity dictates architectural complexity tolerance.
- API-Based:RESTful interfaces enable vending data flows into warehouse management and enterprise resource planning systems. Large United States convenience retail networks mandate this capability for vendor qualification. OAuth 2.0 and webhook architectures are becoming standard.
- ERP Integration:Pre-built connectors for SAP, Oracle, and Microsoft Dynamics serve Fortune 500 foodservice operators. These deployments require six-to-twelve-month implementation timelines but lock in multi-year contracts.
- Standalone:Closed-system deployments without external data exchange.
- Third-Party Tools:Marketplace ecosystems for loyalty programs and dynamic pricing engines.
Standalone retains legacy footprint; API-Based configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vending software production concentrates among cloud-native developers in the United States and Israel, while consumption spreads across convenience retail networks and workplace foodservice operators in developed economies seeking telemetry modernization.
United States
Convenience retail networks and workplace foodservice operators drive demand as PCI DSS Level 1 mandates accelerate cashless retrofits. FCC certification governs wireless modules in connected machines. Chicago and Dallas-Fort Worth clusters host dense deployments of corporate campus vending fleets upgrading legacy mechanical systems.
Germany
Industrial workplace operators and railway station concessionaires prioritize predictive replenishment algorithms for high-traffic locations. The Federal Office for Information Security guidelines reinforce on-premise preferences among critical infrastructure buyers. Bavaria's manufacturing belt leads adoption of hybrid edge-cloud architectures for factory-floor vending.
United Kingdom
Transport hub operators and hospital trusts seek real-time inventory visibility across distributed machine estates. GDPR compliance requirements shape consumer data handling in loyalty program integrations. London's financial district drives demand for restricted-network deployments among defense contractors and banking headquarters.
Japan
High-density urban vending fleets and aging operator workforces push automation of route scheduling and restocking. METI guidelines on IoT security influence procurement specifications for connected devices. Tokyo-Osaka corridor operators pioneer dynamic pricing engines responsive to weather and event data.
France
Corporate campus operators and motorway service area concessionaires modernize fleets to support 24/7 access demands. CNIL guidelines on algorithmic transparency reshape feature roadmaps for recommendation systems. Paris-Saclay cluster leads EU AI Act pre-compliance investments in explainable pricing documentation.
Vending Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the vending software landscape. The vendor base stratifies into three tiers: integrated hardware-software platforms controlling payment processing layers, cloud-native telemetry specialists, and legacy route management system providers. Two dominant competitive moves define current positioning: backward integration into payment terminal manufacturing and API-first partnerships with ERP vendors.
Within the integrated platform tier, Nayax and Cantaloupe Systems exemplify hardware-software convergence strategies. VendSoft occupies a position among lean cloud-native specialists competing on accessibility for mid-sized operators. These three anchors represent divergent architectural bets on where value capture concentrates in the vending technology stack.
| Leading Market Players |
|---|
| Nayax |
| Cantaloupe Systems |
| VendSoft |
| Parlevel Systems |
| VendingTrack |
| Crane Payment Innovations |
| USA Technologies |
| Vendon |
| Televend |
| Others |
Pricing and Supply Chain Analysis
PCI DSS Level 1 certification requirements gate both qualified supply and premium-tier pricing access, compressing vendor qualification timelines while forcing operators toward integrated platform providers capable of absorbing compliance costs. This environmental mandate reshapes procurement authority across convenience retail networks and workplace foodservice operators seeking cashless retrofit capabilities.
Pricing Analysis
Cost-down pressure on mid-sized operators accelerates because FCC wireless module validation and recurring cellular data plans erode margins in sub-500 machine fleets. Pricing stratifies across premium, standard, and economy tiers, with certification grade and volume scale driving differentiation. Small operators exhibit highest price sensitivity, while enterprise convenience retail networks prioritize API connectivity over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in United States defense and financial institution procurement reshape sourcing toward on-premise server installations compliant with restricted-network policies. Component supply concentrates in United States, Israel, and Germany, drawing from embedded systems chipsets, 4G/LTE modules, and DEX protocol parsing libraries. Single-source vulnerability in proprietary MDB interface implementations creates switching friction, while distribution runs through direct vendor relationships and channel partners serving operator fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCI DSS Level 1 certification capacity constraints prop pricing power toward integrated hardware-software platforms, constraining supply elasticity for operators seeking qualified vendors.
For Market Incumbents: Extend payment processing layer control through backward integration into terminal manufacturing, defending against pure-play cloud telemetry specialists. Deepen EMVCo certification moats to lock in enterprise convenience retail networks consolidating vendor relationships. Prioritize API-first partnerships with SAP and Oracle to capture ERP integration timelines. For New Entrants and Emerging Players: Launch via white-label middleware serving retailers unbundling vending management from legacy ERP systems. Target workplace foodservice operators with 200-800 unit fleets adopting edge computing architectures fastest. Penetrate through lean cloud-native stacks emphasizing subscription accessibility over feature depth. For Investors and Strategic Acquirers: EMVCo mandate acceleration across United States convenience retail networks is the leading indicator that payment-processing integration depth determines long-term viability. Acquire telemetry specialists with proven DEX parsing libraries and established cellular carrier relationships. Watch for EU AI Act enforcement timeline crystallization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable ERP connectivity demanded by Fortune 500 foodservice operators. |
| Payment Terminal Manufacturing | Backward integration into EMVCo-certified hardware captures transaction routing revenue streams. |
| Edge Computing Deployment | Distributed processing modules reduce cloud latency for high-frequency vending locations. |
| Regulatory Compliance Investment | EU AI Act pre-compliance creates first-mover positioning in explainable pricing documentation. |
| Geographic Expansion | German industrial workplace operators prioritize predictive replenishment for factory-floor vending. |
Research Methodology
SEC filings, FCC equipment authorization databases, and EMVCo certification registries formed the secondary backbone, supplemented by trade data from cellular module suppliers and DEX protocol documentation. Primary interviews with vending fleet operators, convenience retail network procurement officers, and payment hardware engineering directors combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated machine-level telemetry adoption rates and subscription pricing tiers, while top-down analysis tracked convenience retail consolidation patterns and workplace foodservice modernization budgets across the projection horizon. Deployment architecture, fleet scale, and integration complexity anchored segmentation dimensions, with CAGRs derived from installed base expansion and module attach rate trajectories.
The model assumes a particular technology adoption path; alternative pathways for edge computing middleware would alter the outlook if cloud latency reductions fail to justify distributed hardware costs. Forecasts reflect assumptions around PCI DSS enforcement timelines and cellular carrier pricing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Content Moderation Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
ITSM Market
Software & Services
DevOps Market
Software & Services
Global Municipal Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Global App Design Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Tag Management Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Global Ad Server Software Market