
 Architecture, Engineering, and Construction (AEC) Software Market | 2026-2036
Architecture, Engineering, and Construction (AEC) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Architecture, Engineering, and Construction (AEC) Software Market Insights
ISO 19650 certification for BIM information management is bifurcating the competitive landscape into qualified platform providers and legacy vendors. Autodesk leverages its vertical integration across design-to-construction workflows to sustain premium positioning. Bentley Systems anchors its dominance in heavy civil infrastructure through deep interoperability with geospatial systems. Trimble differentiates by controlling field hardware-to-software linkages that competitors cannot replicate.
Architecture, Engineering, and Construction software encompasses digital platforms that manage spatial design, structural calculation, project scheduling, and asset lifecycle data through parametric modeling engines and cloud-native collaboration protocols. These systems enable multi-stakeholder coordination across distributed teams by enforcing version control and clash detection in real time. Building Information Modeling solutions capture the dominant margin pool as owners mandate federated digital twins for operational handover. Cloud-Based deployment is expanding fastest where hybrid work policies require remote access to large model files without local workstation dependency. Project Management modules remain mature with consolidation around vendors bundling scheduling, cost control, and document management into unified environments.
ISO 19650 adoption, the EU Green Deal operational building performance standards, and the US National BIM Standard are reshaping procurement specifications and platform compliance requirements. Regulators in Europe enforce ESG disclosure through CSRD while the US General Services Administration mandates BIM deliverables for federal projects, directly conditioning software selection criteria. Stakeholders must monitor how emerging AI code-checking capabilities interact with existing qualification frameworks before committing to long-term platform contracts.
Market Dynamics
Cloud-native collaboration protocols are compressing deployment cycles for federated Building Information Modeling environments as owners mandate real-time clash detection across distributed project teams. This infrastructure shift forces legacy vendors to rearchitect monolithic platforms or cede share to API-first competitors.
Growth Catalysts
- US National BIM Standard:Federal project mandates in the United States require digital deliverables for infrastructure procurement, conditioning software selection criteria toward certified platforms.
- AI code-checking engines:Automated structural validation reduces engineering review cycles, accelerating adoption among mid-sized architecture firms seeking labor efficiency.
- EU Green Deal operational standards:Energy performance disclosure requirements in Europe are forcing asset owners to upgrade lifecycle data management capabilities.
Market Restraints
- High switching costs:Proprietary data formats in incumbent platforms create lock-in effects that delay multi-year replacement decisions.
- Geographic supply concentration:Cloud infrastructure dependencies on hyperscale providers in limited jurisdictions create data sovereignty compliance friction.
- Interoperability gaps:Incomplete openBIM implementation leaves federated model exchange vulnerable to version control failures.
Strategic Opportunities
- India infrastructure digitization:National highway and smart city programs lack mature BIM penetration, creating first-mover positioning for cloud-native entrants.
- Digital twin convergence:Integration between operational technology sensor networks and design-phase parametric models opens new subscription revenue pools.
- CSRD-aligned ESG reporting:Mandatory sustainability disclosures in Europe create demand for embedded carbon calculation modules within project management suites.
Industry Challenges
- ISO 19650 certification timelines:Information management qualification requires 12-18 month implementation cycles that strain mid-market vendor resources.
- Legacy CAD migration complexity:Decades of 2D drawing archives resist automated parametric conversion, delaying full BIM adoption in renovation-heavy markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architecture, Engineering, and Construction (AEC) Software Market |
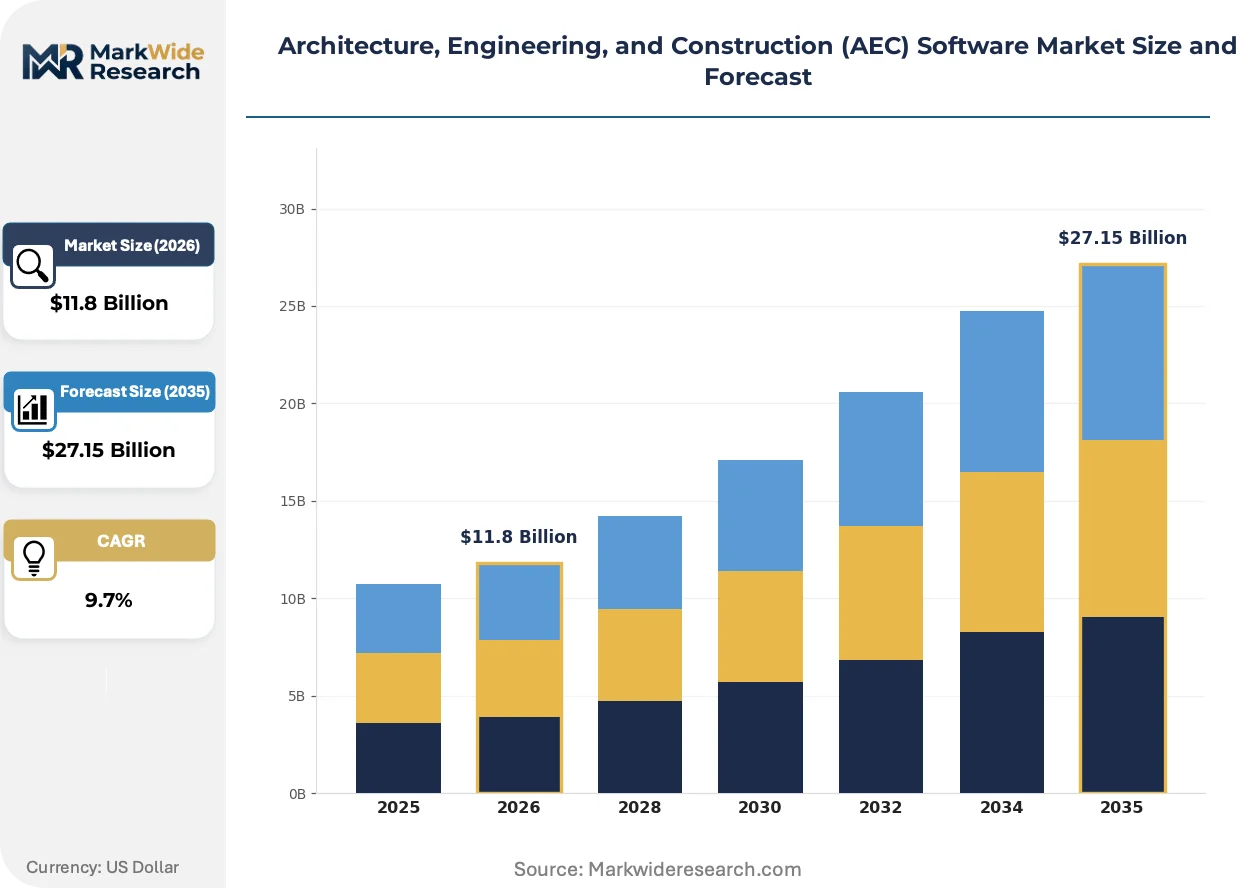
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $27.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Building Information Modeling, Project Management, Estimation, Cost Control, Scheduling, Document Management Application: Urban Planning, Structural Design, Infrastructure Development, Landscape Architecture, Facility Management End User: Construction Firms, Design Studios, Civil Engineering Units, Project Consultants, Contractors |
| Companies Covered | Autodesk, Trimble, AECOM, Bentley Systems, Schneider Electric SE, Oracle, HEXAGON, Stantec, AVEVA Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architecture, Engineering, and Construction (AEC) Software Market Trends and Innovations
Generative design algorithms and edge-compute field hardware are compressing the feedback loop between digital models and physical construction sites. These capabilities are redefining competitive differentiation away from feature breadth toward workflow velocity.
Neural network-based structural optimization is supplanting rule-of-thumb engineering heuristics in early-stage schematic design. European architecture firms are deploying these tools for massing studies, reducing iteration cycles from weeks to hours. This compression is enabling smaller practices to compete for complex projects previously reserved for large multidisciplinary offices.
CSRD disclosure mandates in Europe now require embodied carbon tracking across construction supply chains. Project owners in Germany and France are embedding these requirements into tender specifications, forcing software vendors to integrate environmental product declaration databases. Heavy civil infrastructure segments face the steepest compliance curves given material intensity.
Subscription unbundling is fragmenting traditional suite pricing as specialized vendors attack vertical workflows. Owners and general contractors in the United States are assembling best-of-breed toolchains rather than accepting bundled limitations. This pattern concentrates in commercial building sectors where capital project complexity justifies integration overhead.
Architecture, Engineering, and Construction (AEC) Software Market Segmentation
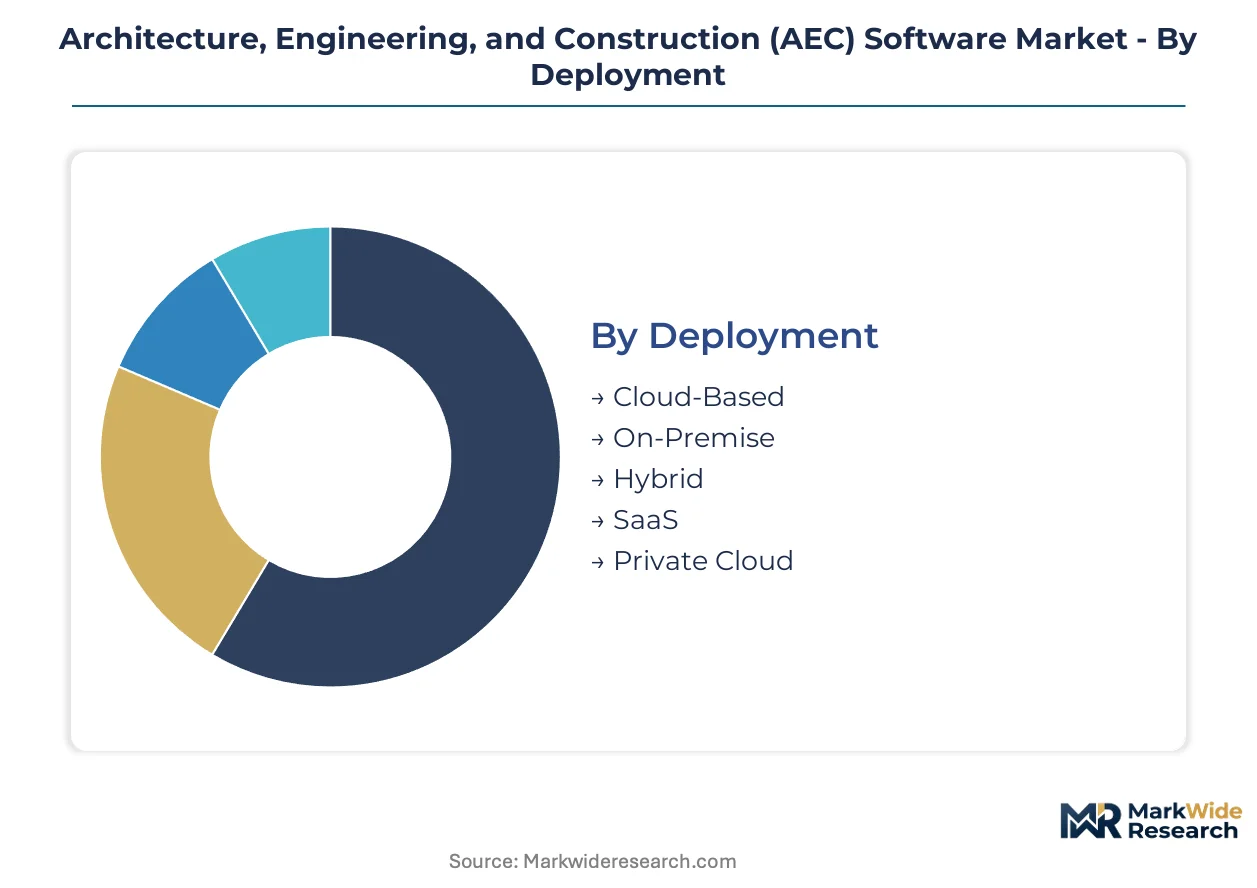
Segmentation in the AEC software market reveals how procurement specifications diverge across regulatory environments and project complexity tiers. Buyers select deployment architectures and solution bundles based on ISO 19650 certification requirements, federal mandate compliance, and multi-stakeholder coordination needs.
Deployment:
Regulatory data sovereignty requirements in Germany, France, and China are fragmenting cloud architecture preferences across jurisdictions.
- Cloud-Based:Federated hosting enables real-time clash detection across distributed project teams without local workstation dependency. Demand concentrates among large construction firms managing multi-site infrastructure projects in the United States and Germany, where hybrid work policies require remote access to large model files.
- On-Premise:Local server installations retain dominance where data residency laws or security classifications prohibit external hosting. Chinese state-owned infrastructure developers and German federal contractors favor this architecture to satisfy national cybersecurity frameworks.
- Hybrid:Split architectures balance sensitive design data on local servers with collaborative workflows in public cloud environments.
- SaaS:Subscription-native delivery eliminates capital expenditure barriers for mid-sized architecture practices.
- Private Cloud:Dedicated infrastructure serves owners with bespoke compliance requirements or dedicated security protocols.
Cloud-Based deployments handle the majority of new procurement volume; Hybrid architectures are gaining share fastest as owners navigate mixed regulatory environments.
Solution Type:
Cost tier differentiation separates premium certified platforms from commodity workflow tools.
- Building Information Modeling:Parametric modeling engines enforce version control and federated digital twin handover. Owners in the United States, Germany, and China mandate BIM deliverables for public infrastructure procurement, concentrating margin capture with certified platform providers.
- Project Management:Unified scheduling, cost control, and document management modules dominate mature procurement categories. Consolidation around bundled vendors reflects procurement efficiency priorities among general contractors managing commercial building portfolios.
- Estimation:Quantity take-off automation reduces bid preparation labor for specialty trade contractors.
- Cost Control:Earned value tracking integrates with ERP systems for capital project financial oversight.
- Scheduling:Critical path optimization remains foundational to construction timeline management.
- Document Management:Version-controlled drawing repositories support audit trails for dispute resolution.
Building Information Modeling commands the dominant margin pool; Estimation tools are climbing fastest as contractors automate bid workflows.
Application:
Volume concentration follows public infrastructure digitization mandates and urban densification patterns.
- Infrastructure Development:Heavy civil projects—highways, bridges, rail networks—require deep interoperability with geospatial systems and sensor networks. Demand clusters in China, the United States, and India where national programs lack mature BIM penetration.
- Urban Planning:Massing studies and zoning compliance tools compress iteration cycles from weeks to hours. European architecture firms deploy generative algorithms for schematic design, enabling smaller practices to compete for complex projects.
- Structural Design:Load calculation and code-checking modules serve engineering consultancies.
- Landscape Architecture:Terrain modeling and hydrological simulation support environmental integration.
- Facility Management:Operational handover data bridges construction-phase digital twins with asset lifecycle management.
Infrastructure Development absorbs the largest procurement volume; Urban Planning is expanding most quickly as generative design tools democratize complex project access.
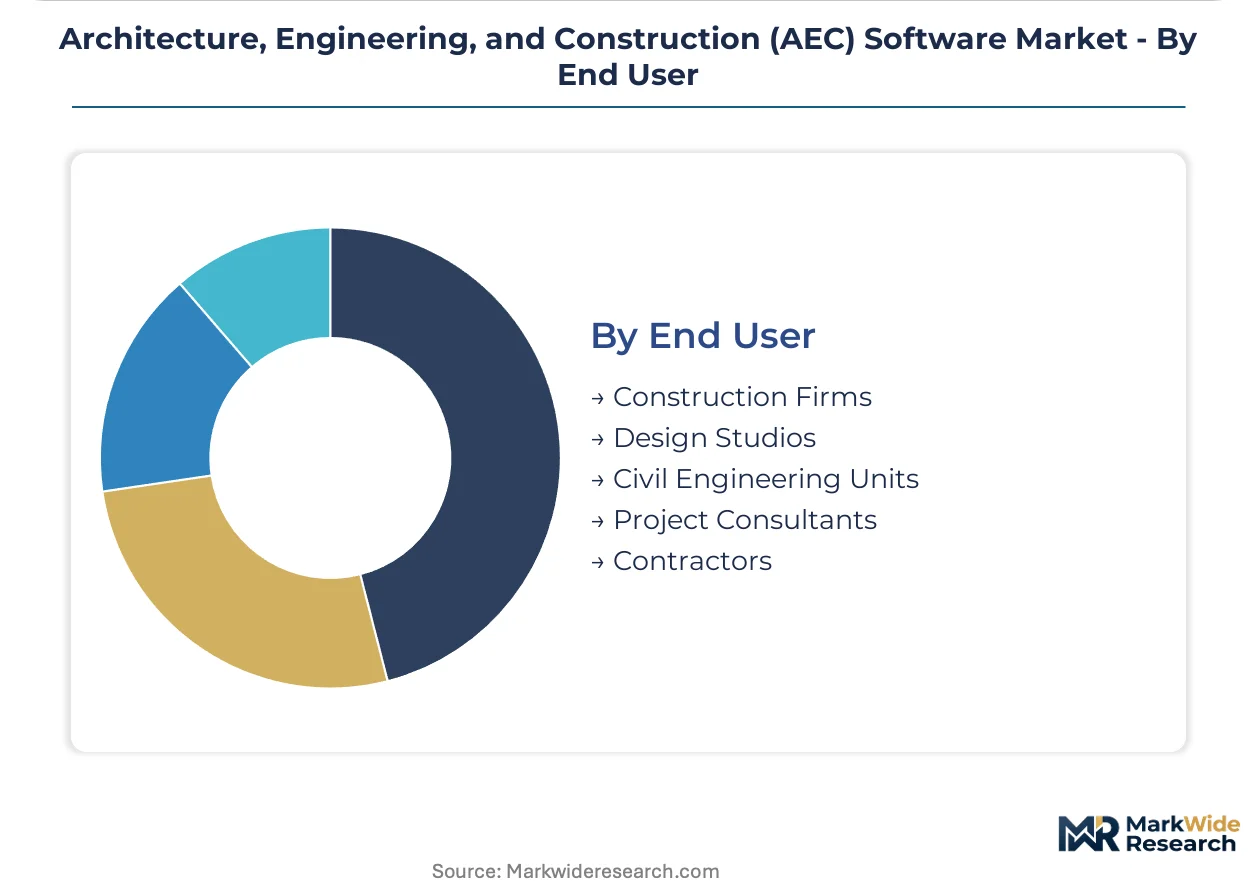
End User:
Customer type determines integration depth and subscription tier selection.
- Construction Firms:General contractors and specialty trades require field-to-office synchronization across distributed sites. Large firms managing multi-site projects in the United States and Germany drive Cloud-Based deployment adoption.
- Design Studios:Architecture practices prioritize schematic design velocity and rendering quality for competition submissions.
- Civil Engineering Units:Structural and geotechnical consultants demand calculation engine accuracy and code compliance automation.
- Project Consultants:Owner representatives and program managers coordinate multi-stakeholder information flows.
- Contractors:Trade-specific subcontractors focus on estimation and fabrication detailing modules.
Construction Firms represent the largest addressable base; Design Studios are adopting AI-assisted tools at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters around federal infrastructure mandates, with procurement specifications conditioning software selection toward certified platforms in the United States, Germany, and China.
United States
The General Services Administration mandates BIM deliverables for federal projects, conditioning software selection toward ISO 19650-certified platforms. Large construction firms in Texas and California drive Cloud-Based deployment adoption for multi-site infrastructure coordination. The Pacific Northwest corridor hosts specialist vendors targeting hybrid work policies requiring remote model access.
Germany
Federal contractors favor On-Premise architectures to satisfy national cybersecurity frameworks under BSI requirements. The EU Green Deal operational standards force asset owners in Bavaria and North Rhine-Westphalia to upgrade lifecycle data management capabilities. Stuttgart's engineering cluster concentrates demand for geospatial interoperability in heavy civil applications.
China
State-owned infrastructure developers retain On-Premise dominance to satisfy data residency laws under MIIT cybersecurity classifications. National highway and smart city programs in the Yangtze River Delta lack mature BIM penetration, creating first-mover positioning for cloud-native entrants. Beijing-Tianjin-Hebei corridor projects mandate federated digital twins for operational handover.
India
National highway digitization and smart city initiatives generate procurement volume without established incumbent lock-in. The Ministry of Road Transport and Highways accelerates tender specifications requiring clash detection capabilities. Mumbai and Delhi-NCR construction markets concentrate demand for estimation automation among specialty trade contractors.
United Kingdom
Central government construction contracts mandate BIM Level 2 compliance, filtering vendor qualification toward certified information management platforms. London's commercial building sector drives subscription unbundling as owners assemble best-of-breed toolchains. The Midlands engineering corridor concentrates mid-sized architecture practices adopting AI-assisted schematic design tools.
Architecture, Engineering, and Construction (AEC) Software Market Competitive Landscape
Player mix skews toward vertically integrated platform providers with design-to-construction workflow control. Market structure concentrates margin capture with three certified incumbents commanding federal and infrastructure procurement channels. Strategic archetypes include: full-stack platform owners with parametric modeling engines, field hardware-software integrators with edge-compute capabilities, and geospatial interoperability specialists with sensor network linkages. Dominant competitive moves include API-first rearchitecture to compress deployment cycles and carbon calculation module integration to satisfy CSRD disclosure mandates.
Within the certified-platform tier, Autodesk and Bentley Systems occupy positions as archetype anchors for design-phase and heavy-civil infrastructure segments respectively. Trimble exemplifies the field-integrated archetype through hardware-to-software linkages that competitors cannot replicate. Oracle represents the enterprise software entrant bundling project management modules into unified environments. These three named companies collectively illustrate how competitive differentiation is compressing toward workflow velocity rather than feature breadth.
| Leading Market Players |
|---|
| Autodesk |
| Trimble |
| AECOM |
| Bentley Systems |
| Schneider Electric SE |
| Oracle |
| HEXAGON |
| Stantec |
| AVEVA Group Plc |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation cycles for ISO 19650 certification concentrate pricing power with qualified platform providers while compressing margins for mid-market vendors unable to absorb qualification overhead. This lead-time dynamic reinforces tiered subscription structures that separate certified incumbents from commodity workflow tools.
Pricing Analysis
Cost-plus contract patterns with consumer price indexation dominate enterprise procurement for multi-year platform commitments. Three-tier pricing structure across premium, standard, and economy levels separates Autodesk's design-suite bundles from Bentley's heavy-civil specializations and Trimble's field-integrated hardware-software packages. Cost compression in the standard tier is intensifying because cloud-native entrants are unbundling scheduling and document management modules. Small-to-mid-sized architecture practices exhibit highest price sensitivity, while federal contractors face mandated certification requirements that override procurement cost considerations.
Supply Chain Analysis
Inbound logistics costs for edge-compute field hardware face persistent pressure from container availability constraints on Asia-Pacific trade lanes. Software development centers in the United States, Germany, and India anchor platform engineering, while cloud infrastructure draws from hyperscale provider networks concentrated in Virginia, Frankfurt, and Singapore. Single-source vulnerability in geospatial data licensing creates procurement risk for heavy civil infrastructure segments. Distribution runs through direct enterprise sales teams supplemented by specialized systems integrators serving owner-operator accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
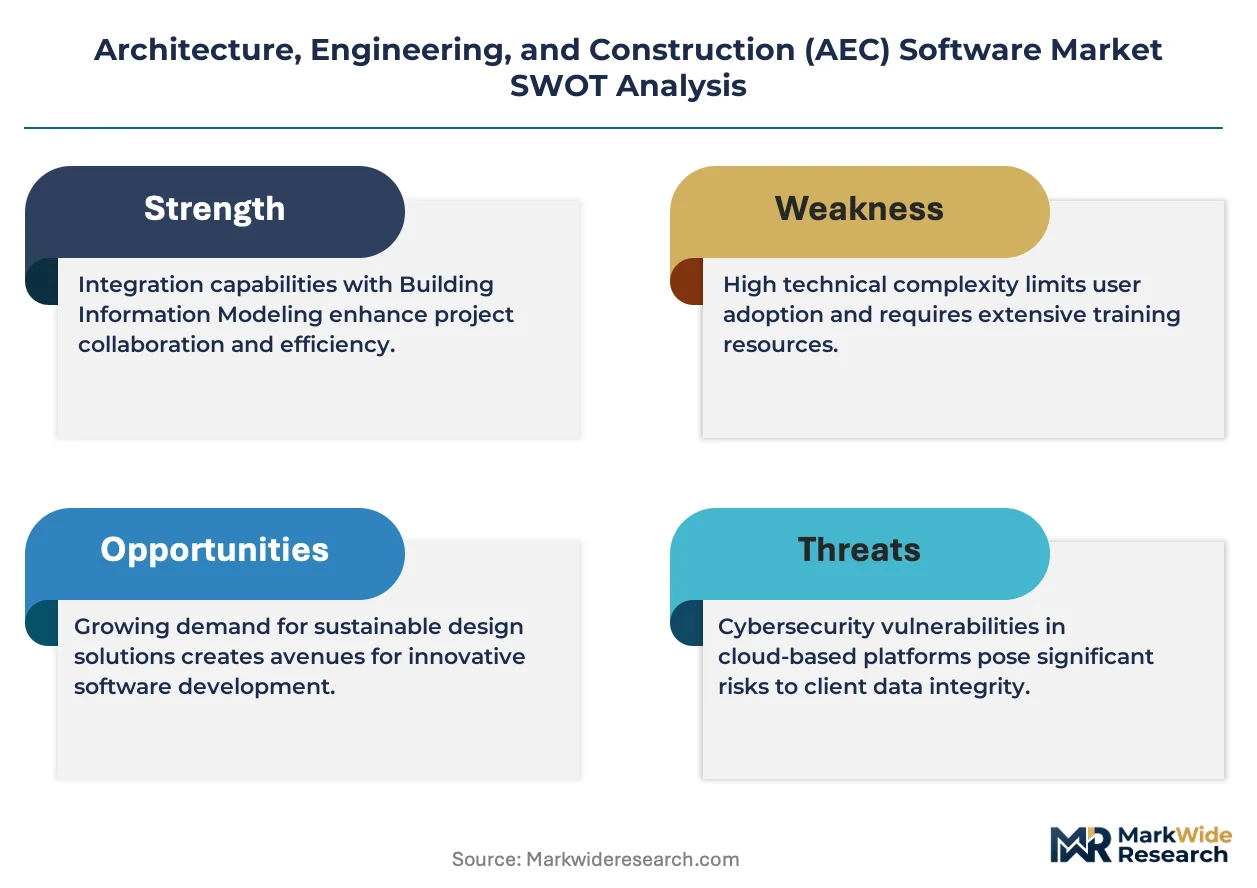
The AEC software market sits at a platform-economics inflection where API-first rearchitecture and openBIM interoperability are displacing monolithic vendor lock-in. This ecosystem shift rewards workflow velocity over feature breadth.
For Market Incumbents: Compound platform stickiness through backward integration into carbon calculation modules that satisfy CSRD disclosure mandates. Deepen field hardware-to-software linkages that cloud-native competitors cannot replicate. Prioritize ISO 19650 certification maintenance as emerging AI code-checking capabilities threaten to bypass traditional engineering review workflows. For New Entrants and Emerging Players: Lead with estimation automation targeting specialty trade contractors in India's national highway digitization programs. The Ministry of Road Transport and Highways' clash detection tender specifications create first-mover positioning without established incumbent lock-in. Deploy SaaS-native delivery to eliminate capital expenditure barriers for mid-sized practices. For Investors and Strategic Acquirers: Long-term, this sits as a vertical-integration play because field hardware-software linkages generate defensive moats that pure software vendors cannot replicate. Target acquisition profiles should emphasize geospatial interoperability specialists with sensor network capabilities. Monitor AI-assisted schematic design adoption rates among European architecture firms as inflection signal for generative design market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rearchitecture | Compresses deployment cycles for federated BIM environments against monolithic legacy vendors. |
| Carbon Calculation Module Integration | Aligns project management suites with CSRD disclosure mandates in Germany and France. |
| Field Hardware-Software Linkage Expansion | Replicates Trimble's edge-compute capabilities that cloud-native entrants cannot match. |
| ISO 19650 Certification Investment | Qualifies platforms for US General Services Administration federal project mandates. |
| Geospatial Interoperability Acquisition | Captures heavy civil infrastructure demand concentrated in Stuttgart's engineering cluster. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with chief technology officers at general contractors, platform engineers at software vendors, IT procurement officers at federal agencies, and integration specialists at systems integrators. Secondary validation drew from SEC filings of publicly traded platform providers, hyperscaler capex disclosures, US General Services Administration procurement databases, and EU Green Deal implementation tracking reports. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Across the analysis window, forecasts modeled deployment architecture preferences, solution type bundling patterns, application complexity tiers, and end-user integration depth requirements. CAGRs were derived from segment-level growth trajectory analysis incorporating federal mandate compliance timelines and cloud-native adoption curves. Industry-specific inputs included ISO 19650 certification penetration rates and AI code-checking capability maturation indices.
Forecasts assume regulatory continuity in US federal BIM mandates, EU Green Deal operational standards, and Chinese MIIT data residency frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Performing Arts Software Market
Software & Services
Illustration Software Market
Software & Services
Global Document Management Software Market
Software & Services
Data Integration Software Market
Software & Services
Deck Design Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Global Distribution Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
Architectural Rendering Software Market
Software & Services
Global Data Mining Software Market
Software & Services
3D Modeling Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Global Application Release Automation Market
Software & Services
Enterprise Resource Planning (ERP) Software Market