
 Global Customer Journey Mapping Software Market | 2026-2036
Global Customer Journey Mapping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Journey Mapping Software Market Foresight
Cloud-native architecture is consolidating as the dominant substrate for customer journey mapping platforms, displacing legacy on-premise installations that carry heavier integration costs. Miro leverages its collaborative canvas technology to anchor product development and marketing strategy workflows for distributed teams. Glassbox competes through real-time analytics capabilities that capture behavioral signals across web and mobile interfaces. UXPressia specializes in template-driven visualization tools that lower deployment friction for mid-market retailers and travel agencies.
Customer journey mapping software encompasses platforms that diagram, analyze, and optimize sequential interactions between consumers and brands across digital and physical touchpoints, typically incorporating behavioral data ingestion, persona modeling, and path visualization with response-time thresholds under 200 milliseconds for real-time decision support. The primary commercial purpose is reducing churn and improving conversion rates by exposing friction points in purchase, onboarding, and support flows. Cloud-based deployment leads in adoption velocity due to elastic scaling and API ecosystem connectivity, while on-premise solutions retain presence among financial institutions with stringent data residency requirements. Multi-channel integration represents the fastest-expanding solution type as enterprises unify siloed CRM, POS, and contact center data streams into coherent journey records.
The EU AI Act and GDPR constrain how automated mapping engines process personal behavioral data, compelling vendors to implement explainable analytics and explicit consent architectures. The Federal Trade Commission in the United States is intensifying scrutiny of dark-pattern detection in journey optimization tools, elevating compliance costs for campaign management modules. India's Digital Personal Data Protection Act is creating localization obligations that favor hybrid deployment models with private cloud components. Stakeholders must weigh regulatory fragmentation against the technical efficiency of centralized SaaS architectures when selecting platform partners.
Market Dynamics
Cloud-native architecture is consolidating as the dominant substrate for customer journey mapping platforms, displacing legacy on-premise installations that carry heavier integration costs and slower deployment cycles across enterprise IT environments.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European enterprises are procuring platforms with embedded explainable analytics and consent architectures to satisfy automated decision-making transparency requirements, accelerating replacement of opaque legacy systems.
- Real-time behavioral data ingestion:Retailers and financial services firms are deploying sub-200 millisecond response-time engines to capture friction points during purchase and onboarding flows, converting analytical latency into competitive disadvantage.
- India's Digital Personal Data Protection Act:Localization obligations are driving hybrid deployment models with private cloud components, creating demand for vendors offering sovereign data residency alongside elastic scaling capabilities.
Market Restraints
- API ecosystem fragmentation:Enterprise CRM, POS, and contact center systems lack standardized data schemas, forcing costly custom integration work before journey unification becomes operational.
- Data residency compliance costs:Financial institutions in Germany and Switzerland maintain on-premise installations to satisfy national banking secrecy laws, sacrificing the cost advantages of centralized SaaS architectures.
- Behavioral analytics talent scarcity:The specialized skill set combining journey design, data engineering, and privacy law interpretation commands premium compensation, inflating total cost of ownership for mid-market deployments.
Strategic Opportunities
- Underpenetrated SME segment in Brazil:Local travel agencies and regional retail chains lack dedicated journey mapping capabilities, presenting whitespace for template-driven visualization tools with Portuguese-language support and simplified onboarding workflows.
- Convergence of journey mapping and voice-of-customer platforms:Integration between path visualization engines and real-time feedback collection systems enables closed-loop optimization, compressing the iteration cycle between insight generation and experience redesign.
- FTC dark-pattern enforcement:Intensified scrutiny of manipulative interface design in the United States creates demand for audit modules that flag potentially deceptive journey elements before regulatory action.
Industry Challenges
- Legacy system integration complexity:Enterprises with decades-old mainframe-based CRM architectures face protracted migration timelines, delaying realization of unified customer view benefits and extending payback periods.
- Cross-functional alignment friction:Marketing, product, and customer success teams maintain competing definitions of journey stages and success metrics, undermining platform adoption and data governance consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Journey Mapping Software Market |
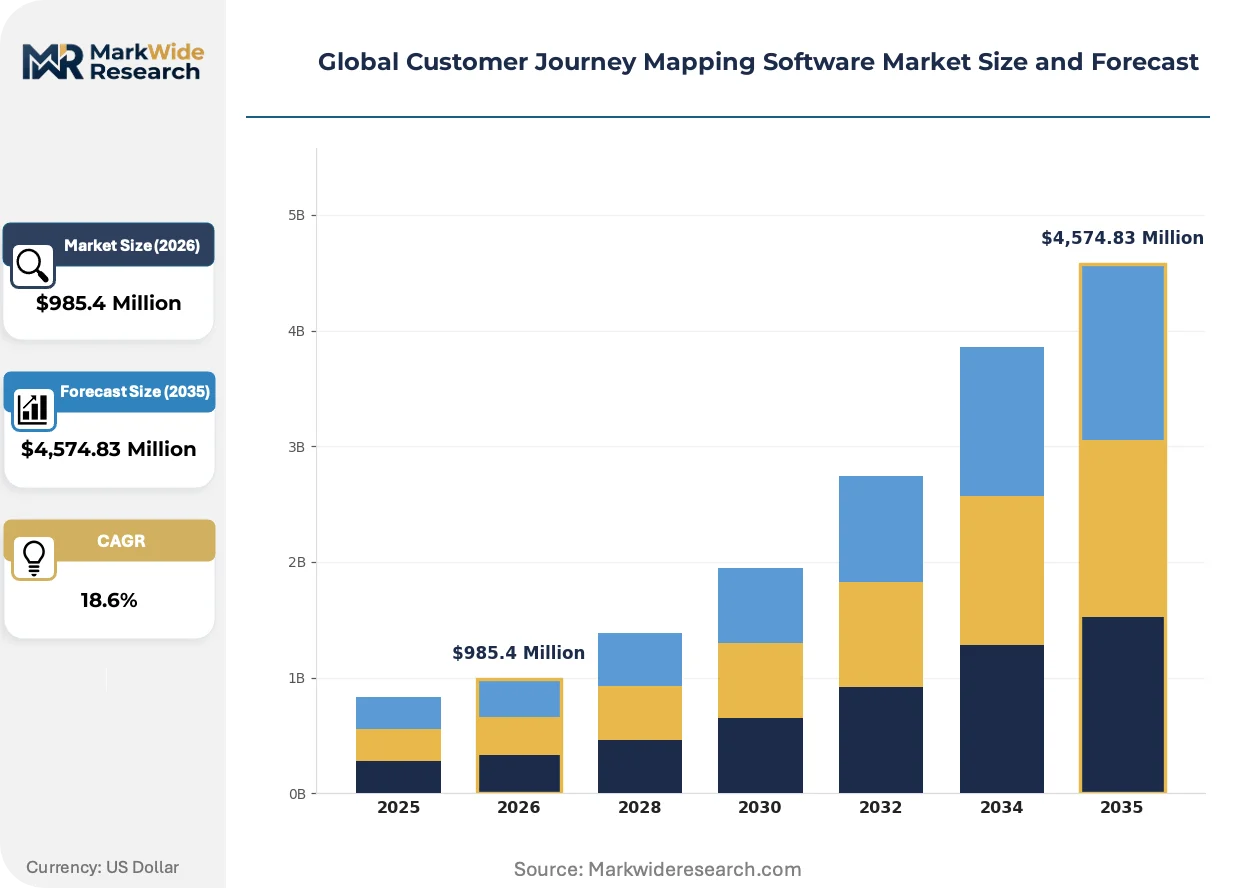
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $4,574.83 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Automated Mapping, Real-Time Analytics, Multi-Channel Integration, Personalization Tools, Campaign Management Use Case: Customer Experience Optimization, Marketing Strategy, Product Development, Customer Support, User Behavior Analysis End User: Retailers, Telecommunications Providers, Financial Institutions, Travel Agencies, Media Companies |
| Companies Covered | Lucidchart, Figjam, UXPressia, MoEngage, TheyDo, Miro, Smaply, Glassbox, Mural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Journey Mapping Software Market Shifts & Advancements
Artificial intelligence is actively reshaping how journey mapping platforms process behavioral signals, shifting competitive advantage toward vendors capable of predictive path modeling rather than retrospective visualization alone.
Real-time session replay technology is expanding into enterprise security and fraud detection workflows, capturing granular interaction data across web and mobile interfaces. Financial institutions in the United States and Germany are adopting these capabilities at accelerated pace to satisfy audit requirements for digital transaction integrity. The structural consequence is that journey mapping vendors are expanding into adjacent security analytics markets, compressing the boundary between customer experience and risk management software categories.
The EU AI Act's transparency requirements for automated profiling are compelling vendors to deploy interpretable machine learning architectures that expose decision logic behind journey optimization recommendations. This regulatory pressure is elevating engineering costs for black-box neural network approaches while favoring simpler, auditable models. SaaS providers serving European retail and insurance verticals are responding by publishing model cards and establishing human-in-the-loop review protocols for high-stakes journey interventions.
Enterprise procurement of journey mapping capabilities is consolidating under centralized customer experience functions, displacing the previous pattern of departmental point solutions. Marketing teams previously owning standalone tools are ceding budget authority to newly created CX centers of excellence with cross-silo mandates. This concentration is most visible in United States-based Fortune 500 enterprises, where platform standardization is reducing vendor fragmentation and elevating contract values for integrated suite providers.
Global Customer Journey Mapping Software Market Segmentation

Customer journey mapping software segments diverge sharply by infrastructure investment requirements and data sovereignty obligations. Procurement decisions hinge on balancing elastic scaling needs against compliance architectures that vary by end-user industry and geographic jurisdiction.
Deployment:
Capital intensity peaks with private cloud installations requiring dedicated hardware stacks and sovereign data residency configurations.
- Cloud-Based:Elastic compute resources provisioned through hyperscaler infrastructure eliminate upfront server procurement. Retailers in the United States and Germany dominate consumption, driven by seasonal demand spikes and API ecosystem connectivity requirements.
- On-Premise:Self-managed server installations within enterprise data centers impose heavy capital expenditure for hardware, cooling, and dedicated IT staffing. Swiss and German financial institutions absorb this burden to satisfy national banking secrecy laws and GDPR data localization mandates.
- Hybrid:Split architectures route sensitive data through private infrastructure while leveraging public cloud burst capacity. Indian enterprises favor this model under Digital Personal Data Protection Act localization obligations.
- SaaS:Subscription-based access to vendor-managed multi-tenant platforms minimizes technical deployment friction. Mid-market travel agencies and media companies prioritize this lowest-barrier entry point.
- Private Cloud:Single-tenant environments hosted by third-party providers deliver isolation without full on-premise capital burden. Telecommunications providers in regulated European markets select this for subscriber data protection.
Cloud-Based deployments absorb the bulk of installed capacity; Hybrid configurations are expanding most quickly under India's localization regime.
Solution Type:
Application complexity determines vendor pricing tiers, with real-time processing engines commanding premium positioning against template-driven alternatives.
- Automated Mapping:Machine learning engines generate journey diagrams from raw behavioral telemetry without manual intervention. EU AI Act transparency requirements are elevating engineering costs for explainable model architectures.
- Real-Time Analytics:Sub-200 millisecond response engines capture friction points during active sessions. Financial institutions in the United States deploy these for fraud detection alongside experience optimization.
- Multi-Channel Integration:Unified ingestion pipelines consolidate CRM, POS, and contact center data streams into coherent journey records. Retailers pursuing omnichannel strategies drive demand concentration.
- Personalization Tools:Dynamic content adaptation modules triggered by journey stage detection. Media companies leverage these for subscription conversion optimization.
- Campaign Management:Journey-aware orchestration platforms coordinating email, SMS, and push notification timing. FTC dark-pattern scrutiny is elevating compliance audit requirements for this segment.
Multi-Channel Integration carries the steepest expansion trajectory as enterprises dismantle data silos; Automated Mapping faces margin pressure from regulatory engineering mandates.
Use Case:
Customer maturity and cross-functional coordination depth separate high-investment implementations from departmental point solutions.
- Customer Experience Optimization:Enterprise-wide programs unifying touchpoint design across marketing, product, and support functions. Fortune 500 CX centers of excellence in the United States centralize procurement for this comprehensive scope.
- Marketing Strategy:Campaign-centric journey design focused on acquisition funnel efficiency. Retailers and travel agencies dominate this historically largest segment.
- Product Development:Integration of usage telemetry into feature prioritization and onboarding redesign workflows. Telecommunications providers apply this for reducing service activation abandonment.
- Customer Support:Journey visualization for contact center routing and self-service escalation path optimization. Financial institutions prioritize this for compliance documentation.
- User Behavior Analysis:Research-oriented session analysis for UX teams without operational journey intervention. Media companies and smaller retailers staff this as entry-level capability.
Marketing Strategy retains the largest installed base; Customer Experience Optimization is climbing fastest as organizational maturity advances.
End User:
Regulatory exposure and transaction value density create tiered willingness-to-pay across verticals.
- Retailers:Omnichannel sellers unifying online and physical touchpoint data for conversion optimization. United States and German enterprises lead adoption velocity.
- Telecommunications Providers:Subscription lifecycle management spanning acquisition through churn prevention. Indian and Brazilian markets show rising investment under competitive pricing pressure.
- Financial Institutions:Banks and insurers with stringent audit trails for digital transaction integrity. German, Swiss, and United States regulatory environments mandate capabilities here.
- Travel Agencies:Booking path optimization with complex multi-product bundling considerations. Regional chains in Brazil represent underpenetrated whitespace.
- Media Companies:Content consumption pattern analysis for subscription and advertising revenue optimization. Streaming services drive technology requirements.
Retailers command the greatest deployment volume; Financial Institutions are gaining share fastest under security and compliance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in the United States, Germany, and India as organizations prioritize digital-first customer engagement infrastructure and unified touchpoint analytics.
United States
Fortune 500 retailers and financial institutions drive demand for real-time journey analytics with sub-200 millisecond response thresholds. FTC intensifies scrutiny of dark-pattern detection in journey optimization tools, elevating compliance audit requirements for campaign management modules. Silicon Valley and New York Metro anchor the highest density of CX centers of excellence consolidating platform procurement authority.
Germany
Automotive manufacturers and omnichannel retailers deploy multi-channel integration solutions to unify CRM, POS, and contact center data streams. GDPR and EU AI Act mandates compel vendors to embed explainable analytics and explicit consent architectures into automated mapping engines. Bavaria and Baden-Württemberg concentrate the largest enterprise implementations serving export-oriented industrial clusters.
India
Telecommunications providers and regional retail chains adopt hybrid deployment models to manage subscription lifecycle complexity. Digital Personal Data Protection Act localization obligations favor private cloud components alongside elastic public cloud burst capacity. Bengaluru and Mumbai host the primary vendor delivery centers and enterprise pilot programs for journey mapping platforms.
Brazil
Regional travel agencies and mid-market retail chains represent underpenetrated whitespace for template-driven visualization tools with Portuguese-language support. ANVISA and consumer protection frameworks impose disclosure requirements on automated customer communications. São Paulo anchors the concentrated demand for simplified onboarding workflows among emerging enterprise adopters.
Switzerland
Private banking and wealth management institutions maintain on-premise installations to satisfy national banking secrecy laws and stringent data residency requirements. Swissmedic and financial regulator oversight extends to digital transaction integrity documentation for audit trails. Zurich and Geneva concentrate the highest-value deployments sacrificing SaaS cost advantages for sovereign data control.
Global Customer Journey Mapping Software Market Competitive Landscape
Platform consolidation dominates the current landscape as specialized point solutions yield to integrated suites under centralized customer experience functions. The vendor base separates into three tiers: collaborative canvas providers anchoring distributed team workflows, real-time analytics engines capturing behavioral signals, and template-driven visualization tools lowering deployment friction for mid-market segments. Strategic archetypes include cloud-native specialists competing on API ecosystem connectivity and hybrid-deployment vendors capturing regulated industry demand. M&A activity and geographic expansion represent the dominant competitive vectors as scale advantages compound in enterprise procurement.
Within the collaborative canvas tier, Miro and Mural exemplify platforms that anchor product development and marketing strategy workflows for distributed teams. Glassbox occupies a position among real-time analytics specialists capturing behavioral signals across web and mobile interfaces. UXPressia represents the template-driven archetype serving mid-market retailers and travel agencies with lowered deployment friction.
| Leading Market Players |
|---|
| Lucidchart |
| Figjam |
| UXPressia |
| MoEngage |
| TheyDo |
| Miro |
| Smaply |
| Glassbox |
| Mural |
| Others |
Supply & Pricing Matrix
Fortune 500 CX centers of excellence in the United States anchor procurement volume, concentrating buyer power around subscription-based SaaS tiers with elastic scaling clauses. This buyer concentration tilts pricing power toward vendors offering unified suites over point solutions, compressing margins for specialized players while rewarding integrated platform providers with annual contract value expansion.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margin pools in customized enterprise deployments with dedicated support and compliance modules. Pricing stratifies across premium real-time analytics engines, standard multi-channel integration suites, and economy template-driven visualization tools. Cost compression in the standard tier intensifies as hyperscaler infrastructure commoditizes compute resources. Mid-market retailers and regional travel agencies exhibit highest price sensitivity, while German financial institutions and Swiss private banks absorb premium positioning for sovereign data residency configurations.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke delivery patterns for cloud-native platform deployment. Vendor engineering talent concentrates in Bengaluru, Berlin, and San Francisco Bay Area clusters. Raw material dependencies include hyperscaler compute capacity from AWS, Azure, and GCP; open-source analytics frameworks; and specialized behavioral data ingestion pipelines. Single-source vulnerability in AI model training data creates concentration risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex hybrid implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration momentum separates winners from marginal players, with upstream control over real-time behavioral data pipelines and downstream ownership of customer success functions emerging as decisive levers.
For Market Incumbents: Acquire specialist real-time analytics engines to close capability gaps against Glassbox-style competitors. Consolidate API ecosystem partnerships to reduce integration friction for enterprise buyers. The threat of emergent collaborative canvas platforms from Miro and Mural expanding into journey mapping demands preemptive feature parity investment. Channel control through certified implementation partner networks protects pricing power against pure-play SaaS disintermediation. For New Entrants and Emerging Players: Regional travel agencies in Brazil and mid-market telecommunications providers in India represent underserved buyer archetypes with limited incumbent penetration. Portuguese-language localization and simplified onboarding workflows unlock Brazilian whitespace. Indian hybrid deployment expertise satisfies Digital Personal Data Protection Act compliance requirements that global vendors struggle to address. A partner-led go-to-market through regional systems integrators accelerates trust formation in compliance-sensitive procurement environments. For Investors and Strategic Acquirers: The window for entry favors vendors with explainable AI architectures already deployed under EU AI Act transparency mandates. Long-term viability hinges on regulatory engineering capabilities that black-box neural network approaches cannot retrofit. Acquisition target archetypes include mid-market visualization specialists with vertical-specific template libraries. The signal to watch is FTC enforcement velocity against dark-pattern detection violations, which will elevate compliance module valuations in campaign management segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies collaborative canvas, real-time analytics, and voice-of-customer modules into coherent suites for CX centers of excellence. |
| Acquisition of Specialist Firm | Captures explainable AI engineering talent and EU AI Act-compliant model architectures ahead of regulatory enforcement waves. |
| Strategic Partnership | Secures hyperscaler co-selling relationships and sovereign cloud certifications for German and Indian data residency requirements. |
| Geographic Expansion | Establishes Portuguese-language delivery centers and ANVISA-aligned audit protocols for Brazilian travel agency penetration. |
| Product Launch | Introduces dark-pattern detection audit modules anticipating FTC enforcement and elevating campaign management compliance premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at retailers, financial institutions, and telecommunications providers supplied operational validation. SEC filings, hyperscaler capex disclosures, and EU AI Act implementation guidance documents supplemented quantitative foundations. Bottom-up deployment estimates triangulated against top-down market sizing from vendor revenue disclosures and channel partner feedback.
Data-stream reconciliation across deployment model, organization size, vertical, integration complexity, and regional adoption pattern dimensions shaped the analytical framework. CAGRs derived from elasticity-adjusted adoption curves and replacement cycle assumptions across the analysis window. Real-time response threshold requirements and GDPR consent architecture compliance costs entered as segment-specific forecast modifiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and FTC dark-pattern litigation velocity. Forecasts reflect documented assumptions around regulatory implementation timelines and enterprise cloud migration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Permit Management Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Photo Editing Software Market
Software & Services
Library Management Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Projector Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Lead Mining Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Deck Software Market
Software & Services
Electronic Design Automation Software Market