
 PLM and Engineering Software Market | 2026-2036
PLM and Engineering Software Market Size, Share, and Industry Trends Forecast 2026-2036
PLM and Engineering Software Market Insights
Aerospace is expanding its share of PLM and engineering software procurement as defense programs and commercial aviation drive digital twin investments. Siemens Digital Industries Software leverages its Teamcenter platform to anchor multi-domain integration across airframe and propulsion programs. Dassault Systèmes sustains dominance in 3D experience platforms through deep verticalization in aerostructures. Ansys competes on physics fidelity, extending its electromagnetic and thermal solver portfolio into supersonic vehicle development cycles.
Product lifecycle management and engineering software encompasses computer-aided design, simulation, data management, and collaborative workflow tools that govern a product's conception, validation, manufacturing, and service phases. Core systems integrate geometric modeling kernels with finite element analysis engines to predict structural, thermal, and fluid behavior before physical prototyping. Simulation solutions lead margin pools due to specialized solver licensing and high switching costs in semiconductor and automotive validation chains. Cloud-based deployments are outpacing on-premise installations as original equipment manufacturers seek elastic compute for generative design workloads and distributed supplier collaboration.
The US Federal Aviation Administration imposes digital traceability requirements on type certification documentation, forcing vendors to embed audit-ready data lineage into PLM architectures. The European Union's Cyber Resilience Act and CE marking directives for machinery safety are pressuring engineering software suppliers to harden API security and validate toolchain interoperability. China's GB standards and MIIT cloud localization mandates restrict cross-border data flows for defense-adjacent manufacturing clients. Stakeholders must decide whether to architect regionally partitioned instances or pursue unified platforms with jurisdictional compliance modules.
Market Dynamics
Defense programs and commercial aviation are compressing digital twin development cycles, forcing engineering software vendors to embed real-time physics solvers directly into collaborative PLM workflows.
Growth Catalysts
- EU Cyber Resilience Act:Machinery safety mandates are hardening API security requirements, expanding addressable market for validated toolchain interoperability modules.
- Generative design workloads:Elastic cloud compute demand from automotive OEMs is displacing on-premise finite element preprocessing clusters.
- Stuttgart-Munich corridor:Germany's automotive engineering concentration is anchoring multi-domain simulation procurement for electric powertrain development.
Market Restraints
- Specialized solver licensing:Per-core pricing for electromagnetic and thermal analysis creates cost barriers for mid-tier semiconductor validation houses.
- MIIT cloud localization:China's cross-border data flow restrictions force redundant infrastructure deployment for defense-adjacent manufacturing clients.
- High switching costs:Decades of accumulated simulation data in proprietary formats locks automotive validation chains into incumbent platforms.
Strategic Opportunities
- Supersonic vehicle development:Hypersonics programs are creating demand for coupled aerothermal-structural solvers with flight-test correlation capabilities.
- India's PLI scheme:Production-linked incentives for automotive and electronics manufacturing are stimulating first-time PLM adoption among domestic component suppliers.
- Digital thread unbundling:Modular API-first architectures are enabling point-solution vendors to penetrate previously integrated enterprise accounts.
Industry Challenges
- Multiphysics expertise scarcity:Converged thermal-fluid-structural simulation requires cross-trained engineers that outpace university pipeline output.
- FAA type certification timelines:Audit-ready data lineage requirements extend software validation cycles by 18-24 months for aerospace deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PLM and Engineering Software Market |
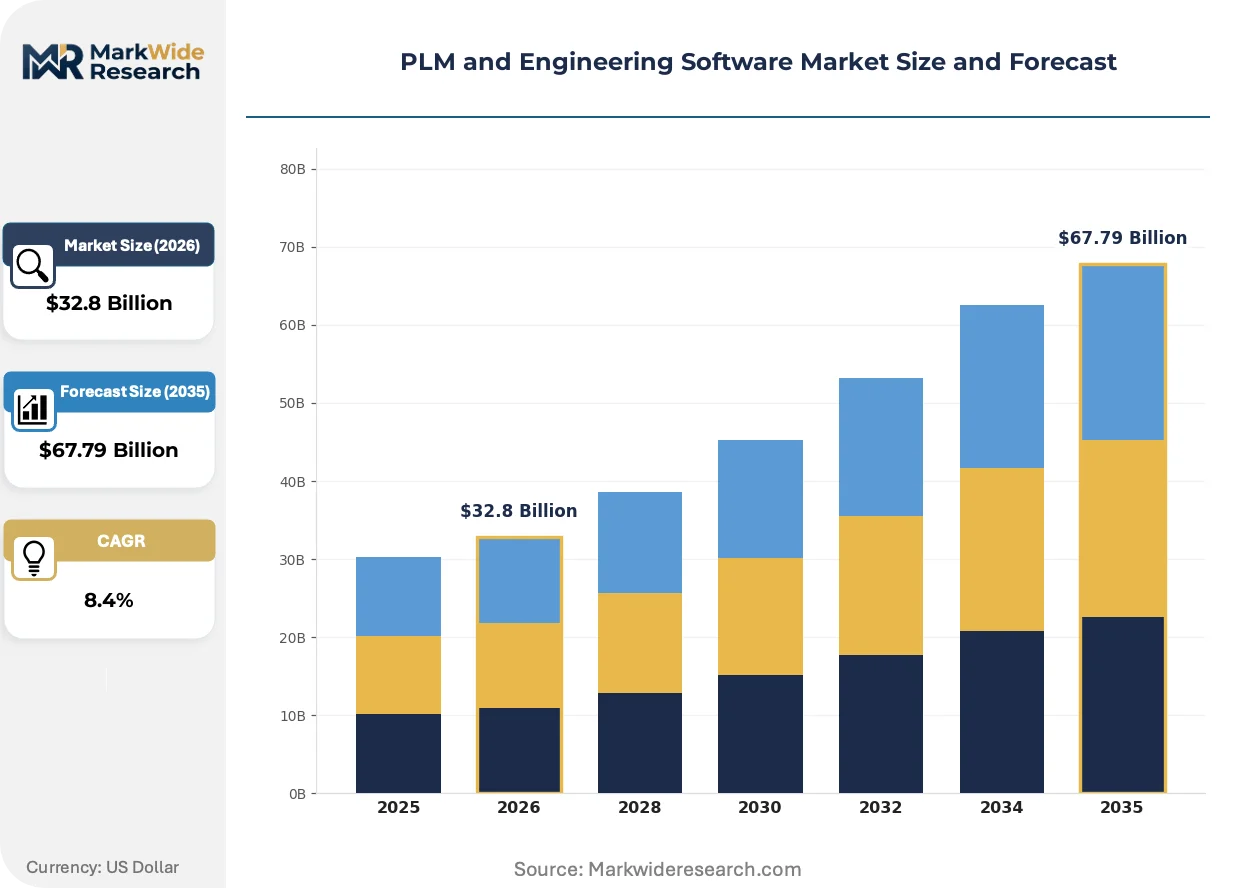
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D CAD, Simulation, Project Management, Data Management Technology: Cloud-Based, On-Premise, SaaS, Desktop End User: Aerospace, Automotive OEMs, Electronics, Consumer Goods Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Dassault Systèmes, Siemens Digital Industries Software, Autodesk, PTC, Synopsys, Cadence Design Systems, Ansys, Hexagon, Bentley Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PLM and Engineering Software Market Trends and Innovations
Physics fidelity demands from hypersonics and electrification programs are compressing the boundary between design and validation phases, eroding traditional sequential engineering handoffs.
AI-accelerated surrogate modeling is integrating reduced-order physics approximations into real-time design exploration loops. Automotive thermal management teams at battery and powertrain OEMs are deploying these models for pack cooling optimization. The technology is integrating generative geometry constraints with conjugate heat transfer predictions, collapsing weeks of simulation into hours.
REACH substance restrictions and F-Gas Regulation phase-downs are mandating material database updates across simulation platforms. Engineering software suppliers must validate new refrigerant thermophysical property models against empirical test data. Aerospace HVAC and thermal control system designers face the steepest compliance curve, retrofitting existing digital twin architectures.
Subscription consumption models are displacing perpetual license structures for mid-market mechanical design houses. Value-added resellers in Central European manufacturing clusters now lead with cloud-hosted simulation bundles rather than on-premise server sales. The shift is most pronounced among German Mittelstand automotive suppliers consolidating distributed engineering sites.
PLM and Engineering Software Market Segmentation
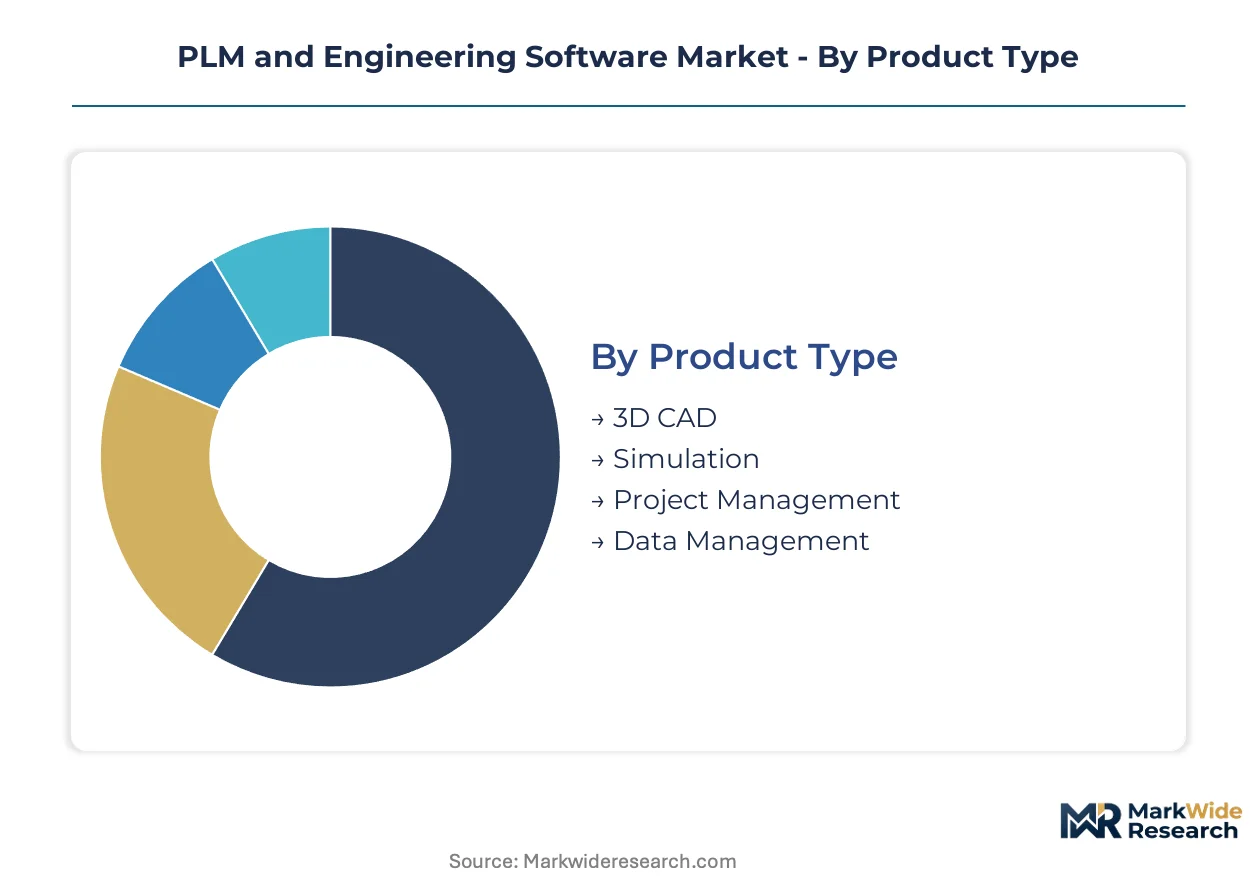
Segmentation in PLM and engineering software reveals how procurement priorities diverge across technical sophistication, infrastructure maturity, and regulatory exposure. Vendors must calibrate packaging, pricing, and compliance modules to match these distinct buyer profiles rather than pursuing uniform platform sales.
Product Type:
Standardization dominates at the core modeling layer while customization intensity rises toward simulation and data governance functions.
- 3D CAD:Geometric modeling kernels with parametric constraint engines form the foundational design layer. German automotive OEMs in the Stuttgart-Munich corridor anchor procurement volume for electric vehicle platform development. Siemens and Dassault Systèmes compete on direct modeling speed and large assembly performance.
- Simulation:Multiphysics solver suites combining finite element, computational fluid dynamics, and electromagnetic analysis command premium licensing structures. Aerospace type certification requirements from the FAA and EASA drive validation chain integration. Thermal and structural correlation with flight test data creates switching cost moats.
- Project Management:Workflow orchestration tools governing milestone tracking and resource allocation across distributed engineering teams.
- Data Management:Vaulting systems with version control and access governance for proprietary geometry and simulation file formats.
Most installed capacity flows through 3D CAD. Expansion is steepest in Simulation.
Technology:
Cost tier stratification separates enterprise-grade elastic compute from perpetual license desktop installations.
- Cloud-Based:Elastic infrastructure provisioning generative design compute pools without capital expenditure. EU data sovereignty mandates under GDPR and Cyber Resilience Act are reshaping procurement criteria toward regionally partitioned instances. Automotive OEMs displaced on-premise clusters first.
- SaaS:Subscription consumption models with API-first architectures enabling modular toolchain assembly. Mid-market mechanical design houses in Central European manufacturing clusters lead adoption.
- On-Premise:Perpetual license structures with captive server infrastructure for classified defense programs and ITAR-controlled workflows.
- Desktop:Single-workstation installations retaining relevance for standalone design validation and supplier tier collaboration.
On-Premise retains the largest installed base. SaaS is climbing the fastest as value-added resellers pivot from server sales to cloud-hosted bundles.
End User:
Application criticality varies from safety-of-flight systems requiring audit-ready data lineage to consumer-facing products prioritizing speed-to-market.
- Aerospace:Defense programs and commercial aviation drive digital twin investments with real-time physics solver integration. FAA type certification documentation mandates embedded data lineage. Hypersonics development creates demand for coupled aerothermal-structural analysis.
- Automotive OEMs:Battery thermal management and electric powertrain development concentrate procurement in Germany's engineering corridor. REACH substance restrictions and F-Gas Regulation phase-downs mandate refrigerant thermophysical property model updates.
- Electronics:Semiconductor validation chains with specialized electromagnetic and thermal solver requirements.
- Consumer Goods:Accelerated design exploration cycles with reduced-order physics approximations and generative geometry constraints.
Aerospace commands the highest per-seat licensing values. Automotive OEMs represent the largest aggregate procurement volume.
Deployment:
Customer type and security classification determine infrastructure architecture selection.
- Private Cloud:Dedicated tenant environments for defense-adjacent manufacturing with controlled data residency. China's MIIT cloud localization mandates force redundant infrastructure deployment for cross-border programs.
- Public Cloud:Shared infrastructure with consumption-based pricing for elastic generative design workloads. EU Cyber Resilience Act machinery safety directives are hardening API security requirements.
- Hybrid Cloud:Partitioned architectures separating classified design data from collaborative supplier workflows. Germany's automotive engineering clusters favor this model for IP protection.
- On-Premises:Air-gapped installations for ITAR-controlled aerospace programs and sovereign defense requirements.
Hybrid Cloud carries the most complex integration overhead. Public Cloud is gaining share fastest among first-time PLM adopters in India's PLI-stimulated automotive component sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich engineering corridor anchors procurement concentration for electric powertrain simulation suites. Cloud migration mandates from EU data sovereignty rules are reshaping vendor selection criteria. Defense hypersonics programs and commercial aviation type certification requirements are redistributing demand across three continents.
United States
FAA type certification documentation requirements and defense hypersonics investments drive digital twin procurement. The Cybersecurity and Infrastructure Security Agency hardens API security standards for machinery safety tooling. Seattle-Tacoma aerospace clusters anchor multi-domain solver integration for airframe and propulsion programs.
Germany
REACH substance restrictions and F-Gas Regulation phase-downs mandate refrigerant thermophysical property model updates. The EU Cyber Resilience Act hardens machinery safety API requirements, expanding validated toolchain interoperability markets. Stuttgart-Munich automotive engineering corridors concentrate electric powertrain multiphysics simulation procurement.
China
MIIT cloud localization mandates and GB standards restrict cross-border data flows for defense-adjacent manufacturing. Dual carbon goals accelerate electrification simulation demand across battery and powertrain development. Yangtze River Delta manufacturing hubs deploy regionally partitioned PLM instances for supplier collaboration.
India
Production-linked incentive schemes for automotive and electronics manufacturing stimulate first-time PLM adoption among domestic component suppliers. BIS standards alignment pressures simulation data governance upgrades. Tamil Nadu and Karnataka automotive clusters anchor cloud-hosted simulation bundle procurement from value-added resellers.
Japan
METI industrial digitalization roadmaps prioritize digital thread integration for precision manufacturing supply chains. JIS standards compliance requirements shape engineering software validation protocols. Nagoya-Tokyo automotive and electronics corridors sustain premium solver licensing demand for semiconductor thermal validation.
PLM and Engineering Software Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent platforms absorb adjacent simulation domains. The vendor base stratifies into three tiers: integrated enterprise suites anchoring aerospace certification chains, modular API-first specialists penetrating mid-market accounts, and point-solution vendors unbundling digital thread components. Strategic archetypes include physics fidelity specialists, cloud-native challengers, and verticalized industry platforms. M&A activity and technology licensing agreements constitute the primary competitive vectors as vendors race to embed real-time solvers into collaborative workflows.
Among the integrated platform tier, Dassault Systèmes and Siemens Digital Industries Software exemplify enterprise-grade digital thread anchoring. Ansys occupies a position within the physics fidelity specialist archetype, representing premium solver licensing structures that create switching cost moats in semiconductor and automotive validation chains. Autodesk sits within the cloud-native challenger segment, exemplifying subscription consumption models displacing perpetual licenses among mid-market mechanical design houses.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Siemens Digital Industries Software |
| Autodesk |
| PTC |
| Synopsys |
| Cadence Design Systems |
| Ansys |
| Hexagon |
| Bentley Systems |
| Others |
Pricing and Supply Chain Analysis
Cloud compute spot pricing indices cascade through engineering software value chains, compressing margins for on-premise perpetual license vendors while expanding addressable markets for consumption-based SaaS providers serving mid-tier automotive suppliers.
Pricing Analysis
Input-cost pass-through from elastic infrastructure provisioning reshapes licensing economics across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade solver fidelity from mid-market mechanical design bundles. Certification-grade electromagnetic and thermal analysis commands per-core premiums, while subscription consumption models displace perpetual licenses among German Mittelstand automotive suppliers. Price differentiation stems from validation chain integration depth and API security hardening under EU Cyber Resilience Act mandates. Cost compression in standard-tier simulation bundles intensifies as value-added resellers pivot from server sales to cloud-hosted offerings. Mid-market semiconductor validation houses exhibit highest price sensitivity; defense-hypersonics programs demonstrate lowest sensitivity due to audit-ready data lineage requirements.
Supply Chain Analysis
High-performance computing infrastructure rests on Taiwanese semiconductor foundries, US hyperscaler data center operators, and German precision manufacturing equipment producers. Solver licensing revenue draws from proprietary geometric modeling kernels, finite element analysis engines, and electromagnetic simulation libraries. Cloud orchestration platforms hinge on API-first architecture development concentrated in US West Coast technology corridors and Indian software engineering hubs. Single-source vulnerability concentrates in specialized multiphysics solver expertise pools that outpace university pipeline output. Distribution runs through value-added resellers in Central European manufacturing clusters and direct enterprise sales teams anchoring aerospace certification chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Cyber Resilience Act compliance costs and India's PLI-stimulated first-time adoption creates margin expansion opportunities for modular platform vendors.
For Market Incumbents: Anchor multi-domain integration dominance through captive solver development in aerothermal-structural analysis, countering modular API-first specialists penetrating previously integrated enterprise accounts. Deepen certification investment for FAA type documentation lineage to extend 18-24 month validation cycle moats. Vertical integration into real-time physics engines hardens switching costs against cloud-native challengers displacing perpetual license structures. For New Entrants and Emerging Players: Value-added resellers in India's Tamil Nadu and Karnataka automotive clusters represent the most penetrable channel for cloud-hosted simulation bundles targeting PLI-stimulated component suppliers. White-space targets include mid-tier semiconductor validation houses constrained by per-core pricing barriers and first-time PLM adopters in production-linked incentive corridors. Go-to-market execution should lead with API-first architectures enabling point-solution penetration of hybrid cloud deployments. For Investors and Strategic Acquirers: Asymmetric upside sits with physics fidelity specialists commanding premium solver licensing in automotive and semiconductor validation chains. Long-term viability across the projection horizon favors platforms embedding AI-accelerated surrogate modeling for real-time design exploration. Acquisition target archetype: modular multiphysics vendors with flight-test correlation capabilities in hypersonics development. Signal to watch: FAA audit-ready data lineage mandate expansion into commercial aviation sub-tier supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Teamcenter anchoring across Siemens airframe programs collapses multi-domain handoff latency. |
| Acquisition of Specialist Firm | Real-time physics solver targets compress digital twin development cycles for defense hypersonics. |
| Strategic Partnership | Hyperscaler alliances provision elastic compute pools for generative design workloads in Stuttgart corridor. |
| Product Launch | AI-accelerated surrogate modeling collapses weeks of conjugate heat transfer simulation into hours. |
| Geographic Expansion | Regionally partitioned instances address MIIT cloud localization mandates for Yangtze River Delta manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with PLM procurement officers at automotive OEMs, simulation directors at aerospace Tier 1 suppliers, cloud infrastructure architects, value-added reseller channel heads, and regulatory compliance leads with secondary validation. Primary sources included CTOs at German engineering corridor manufacturers, IT procurement officers at battery powertrain developers, platform integration specialists, and aftermarket service heads. Secondary data drew from FAA type certification documentation databases, EASA validation protocols, EU Cyber Resilience Act implementation guidance, SEC software vendor filings, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Historical reference periods anchored the projection horizon through multivariate regression against solver licensing trends, cloud migration velocity indices, and regulatory compliance investment cycles. Segmentation dimensions modeled encompass deployment architecture, organization scale, vertical application criticality, integration complexity tier, and regional data sovereignty pattern. CAGRs derived from elasticity-adjusted adoption curves incorporating generative design workload growth and digital thread unbundling velocity. Industry-specific forecast inputs included electric powertrain development timelines and REACH substance restriction implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multiphysics expertise scarcity, FAA audit timeline extensions, and MIIT cross-border data flow policy evolution. Forecasts reflect documented assumptions regarding cloud infrastructure cost trajectories and regulatory harmonization pace. A small set of named triggers warrants ongoing watch: EU Cyber Resilience Act enforcement intensity, India PLI scheme renewal terms, and hypersonics program budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
India HR Payroll Software Market
Software & Services
Application Virtualization Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Website Translation Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Global Data Governance Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Attendance Management Software Market
Software & Services
Global Log Management Software Market
Software & Services
North America IT Services Market
Software & Services
Global Client Portal Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Embedded Hypervisor Software Market