
 Employee Advocacy Software Market | 2026-2036
Employee Advocacy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Advocacy Software Market Analysis
Subscription-based financing and asset-light SaaS procurement is fragmenting competitive dynamics in employee advocacy software, allowing mid-tier vendors to challenge incumbents without heavy infrastructure investments. GaggleAMP leverages channel partner networks to extend its reach among distributed sales teams. Haiilo anchors its position through deep integration with European workplace communication stacks. EveryoneSocial specializes in vertical-specific content templates that differentiate its offering for regulated industries.
Employee advocacy software comprises platforms that curate, distribute, and measure branded content shared through employees' personal social networks, typically operating via API connections to LinkedIn, X, and Meta services with real-time engagement analytics. The primary commercial purpose is converting workforce social graphs into measurable brand impressions and lead generation channels at lower customer acquisition cost than paid media. Cloud-based deployment dominates structural segment economics due to lower onboarding friction and recurring revenue predictability, while on-premises solutions occupy niche positions in financial services with stringent data residency requirements. Large corporations represent the deepest margin pool in end-user segmentation, though small businesses show the fastest expansion trajectory as self-service onboarding tools mature.
GDPR enforcement by European data protection authorities shapes content tracking architectures, requiring explicit consent mechanisms for employee social data collection. The EU AI Act introduces compliance layers for automated content recommendation engines embedded in advocacy platforms. ISO 27001 certification has become a baseline market-access requirement for enterprise procurement evaluations. Stakeholders must monitor how emerging state-level privacy statutes in the United States fragment compliance obligations beyond federal frameworks.
Market Dynamics
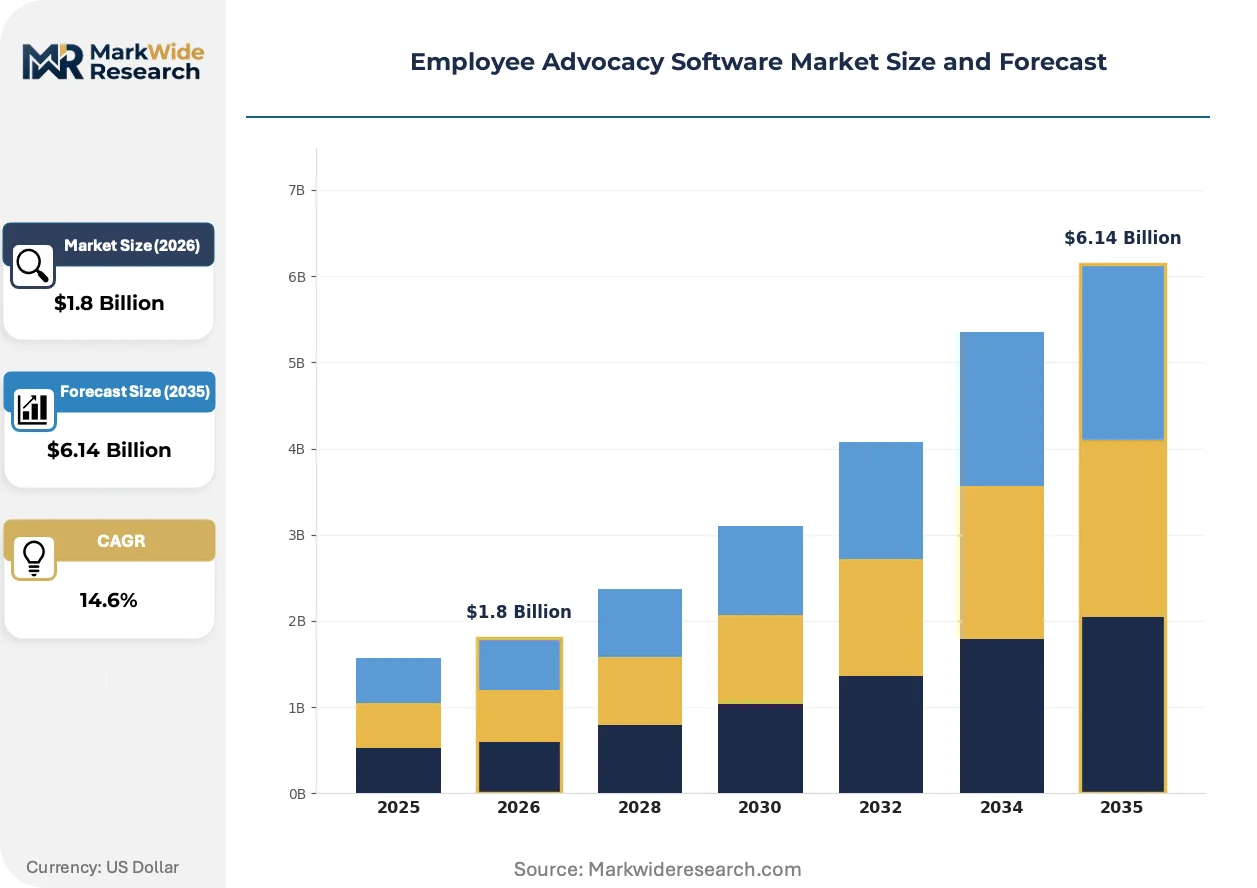
GDPR enforcement and the EU AI Act are compressing content tracking architectures, forcing vendors to rebuild consent mechanisms and automated recommendation engines from the ground up.
Growth Catalysts
- SaaS-centric enterprises in California and New York:Technology sector buyers are expanding platform adoption to amplify organic reach through workforce social graphs.
- GDPR consent frameworks:European data protection authorities are mandating explicit opt-in mechanisms, creating upgrade cycles for compliant architectures.
- Self-service onboarding tools:Small businesses show the fastest expansion trajectory as simplified deployment reduces friction for resource-constrained buyers.
Market Restraints
- ISO 27001 certification requirements:Enterprise procurement evaluations now demand baseline security credentials that mid-tier vendors struggle to fund.
- State-level privacy statutes in the United States:Fragmenting compliance obligations beyond federal frameworks multiplies legal engineering costs for multi-state deployments.
- API dependency on LinkedIn, X, and Meta:Platform policy changes or rate limit adjustments can sever core distribution channels without warning.
Strategic Opportunities
- Financial services niche:On-premises solutions for stringent data residency requirements remain underpenetrated relative to cloud saturation.
- Vertical-specific content templates:Regulated industries demand pre-approved compliance frameworks that generalist platforms cannot easily replicate.
- AI governance convergence:Automated content moderation combined with explainable recommendation engines opens differentiation for European workplace communication stacks.
Industry Challenges
- Consent engineering talent scarcity:Vendors face acute shortages of privacy engineers capable of building GDPR-compliant social data collection pipelines.
- Legacy HR system integration:Enterprise buyers require seamless connection to existing workforce directories, extending implementation timelines.
- Cross-border data flow friction:Divergent national implementations of adequacy decisions complicate multi-territory deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Advocacy Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Solution: Content Creation, Social Media Management, Analytics, Training Tools Industry Vertical: Technology, Healthcare, Retail, Finance |
| Companies Covered | DSMN8, Octopost, Sociabble, Ambassify, PostBeyond, EveryoneSocial, Haiilo, GaggleAMP, Supergrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Advocacy Software Market Emerging Trajectories
Generative content engines and real-time engagement analytics are compressing the cycle between content curation and employee distribution, reshaping how brands orchestrate workforce advocacy.
Automated content personalization engines are collapsing the distinction between corporate messaging and employee voice by dynamically adapting brand assets to individual social graph characteristics. Mid-market SaaS buyers are adopting these tools fastest, driven by pressure to match enterprise-scale reach without proportional media spend. The structural consequence is collapsing margins for traditional social media management platforms that lack workforce distribution layers.
The EU AI Act's risk-based classification system is mandating human oversight interfaces for automated content recommendation engines deployed in European workplaces. Vendors must now document decision logic and maintain audit trails for algorithmic content suggestions. Large corporations with cross-border operations are responding by bifurcating their tech stacks—European instances with enhanced governance, simplified architectures elsewhere.
Outcome-based engagement contracts are displacing seat-based subscriptions in enterprise renewals, with buyers demanding guaranteed impression or lead-generation thresholds. Channel partners and direct sales teams face compressed compensation cycles tied to provable advocacy metrics rather than deployment milestones. This shift is most visible in California and New York, where SaaS procurement teams have pioneered performance-linked software agreements.
Employee Advocacy Software Market Segmentation
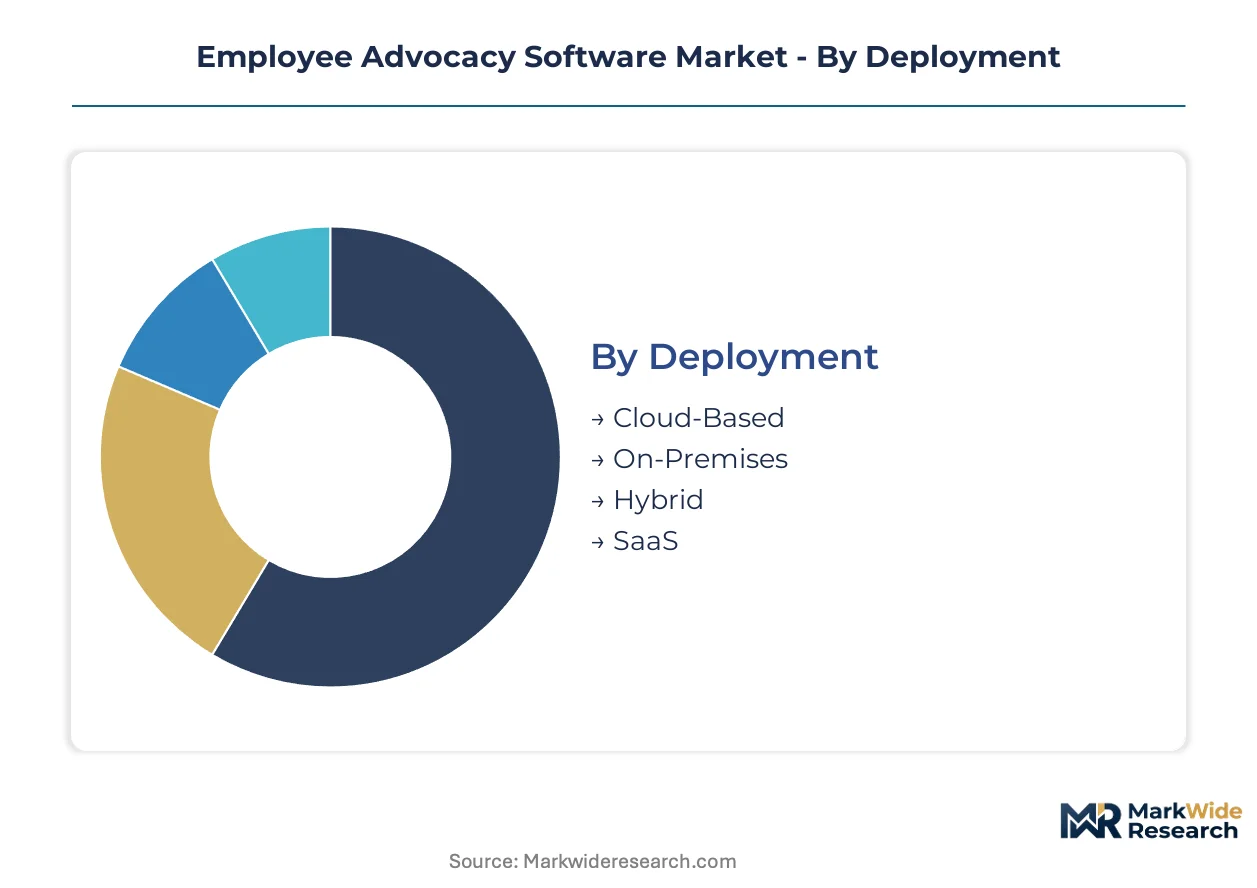
Segmentation in employee advocacy software reveals how deployment architecture, customer scale, and industry compliance requirements create distinct competitive arenas with diverging margin structures and vendor specialization patterns.
Deployment:
Post-implementation service intensity varies dramatically across deployment modes, with on-premises installations demanding sustained engineering support while cloud configurations shift burdens to automated monitoring.
- Cloud-Based:Multi-tenant architectures with API-native connectivity to LinkedIn, X, and Meta reduce onboarding friction for distributed workforces. Demand concentrates among SaaS-centric enterprises in California and New York seeking rapid deployment without infrastructure capital. The subscription model aligns vendor incentives with ongoing platform optimization.
- SaaS:Purpose-built software-as-a-service layers abstract infrastructure complexity through pre-configured integrations with European workplace communication stacks. Small businesses show the fastest expansion trajectory as self-service onboarding tools mature and procurement cycles compress.
- On-Premises:Single-tenant installations with stringent data residency controls serve financial services institutions facing GDPR enforcement and national adequacy decision constraints.
- Hybrid:Split architectures bifurcate processing between cloud curation and on-premises storage, responding to cross-border data flow friction in multi-territory deployments.
By volume, Cloud-Based leads. By growth pace, SaaS is ahead.
End User:
Customer scale determines feature complexity and sales motion economics, with procurement patterns diverging between self-service velocity and enterprise negotiation cycles.
- Large Corporations:Complex workforce directories with legacy HR system integration requirements extend implementation timelines but yield the deepest margin pools through multi-year contracts. ISO 27001 certification has become a baseline market-access requirement for this segment.
- Medium Enterprises:Mid-market buyers adopt automated content personalization engines fastest, driven by pressure to match enterprise-scale reach without proportional media spend. Channel partner networks extend vendor reach among distributed sales teams.
- Small Businesses:Resource-constrained buyers prioritize simplified deployment and outcome-based engagement contracts with guaranteed impression thresholds.
- Non-Profits:Mission-driven organizations leverage workforce advocacy for donor cultivation and volunteer recruitment with constrained technology budgets.
Revenue concentration favors Large Corporations. Expansion velocity belongs to Small Businesses.
Solution:
Functional module selection reflects organizational maturity in social advocacy, with integrated suites displacing point solutions as measurement sophistication increases.
- Content Creation:Generative engines and pre-approved compliance frameworks for regulated industries collapse the distinction between corporate messaging and employee voice. Vertical-specific templates differentiate offerings for healthcare and finance sectors.
- Analytics:Real-time engagement tracking with provable advocacy metrics enables performance-linked software agreements in California and New York procurement teams.
- Social Media Management:API-dependent distribution layers face platform policy change risks from LinkedIn, X, and Meta rate limit adjustments.
- Training Tools:Onboarding modules address consent engineering talent scarcity by building internal GDPR-compliant social data collection capabilities.
Platform stickiness originates in Analytics. Training Tools show the steepest expansion trajectory as compliance complexity deepens.
Industry Vertical:
Sector-specific regulatory exposure shapes content moderation requirements and integration priorities, creating defended positions for vendors with vertical expertise.
- Technology:SaaS-centric enterprises in California and New York anchor platform adoption to amplify organic reach through workforce social graphs. API-native architectures align with existing cloud infrastructure investments.
- Finance:Stringent data residency requirements and GDPR enforcement by European data protection authorities sustain demand for on-premises solutions with enhanced governance interfaces.
- Healthcare:HIPAA compliance overlays and patient privacy constraints limit social sharing scope, favoring training tools that educate workforce on permissible content boundaries.
- Retail:Seasonal demand fluctuations and distributed store networks prioritize self-service onboarding tools with rapid deployment capabilities.
Technology commands the largest addressable base. Finance sustains the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives and data protection mandates are redrawing territorial competitive boundaries. National implementations of adequacy decisions and sector-specific compliance layers now determine vendor market access more than feature parity.
United States
California and New York anchor SaaS-centric enterprise adoption, with procurement teams pioneering performance-linked software agreements. State-level privacy statutes in Virginia, Colorado, and Utah fragment compliance obligations beyond federal frameworks. San Francisco Bay Area technology clusters concentrate platform deployment for workforce social graph amplification.
Germany
Industrial Mittelstand firms drive demand for ISO 27001-certified architectures with legacy HR system integration. GDPR enforcement by regional data protection authorities mandates explicit consent mechanisms for employee social data collection. Frankfurt and Munich financial services hubs sustain on-premises solutions with stringent data residency controls.
United Kingdom
Post-Brexit adequacy negotiations complicate cross-border data flows for multi-territory deployments. Financial Conduct Authority guidelines overlay sector-specific governance on automated content recommendation engines. London fintech clusters adopt hybrid architectures bifurcating European instances with enhanced oversight from simplified global stacks.
France
CNIL regulatory guidance shapes consent engineering requirements for workplace communication stack integrations. AI governance convergence around explainable recommendation engines opens differentiation for vendors with documented decision logic. Paris-based enterprise software buyers prioritize human oversight interfaces for algorithmic content suggestions.
India
IT and business process outsourcing sectors expand platform adoption for distributed sales team enablement. RBI data localization guidelines influence financial services procurement evaluations. Bangalore and Hyderabad technology corridors concentrate mid-market SaaS buyers adopting automated content personalization engines.
Employee Advocacy Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability layers: cloud-native distribution engines, compliance-heavy European stacks, and vertical-specific content frameworks. Strategic archetypes include API-first challengers, GDPR-specialized regionalists, and template-driven verticalists. Dominant competitive moves encompass channel partner network expansion and outcome-based contract structuring.
Within the European specialization tier, Haiilo and Sociabble occupy positions anchored through deep integration with workplace communication stacks. GaggleAMP exemplifies the channel-centric archetype, leveraging partner networks to extend reach among distributed sales teams. EveryoneSocial represents the vertical-focused approach, with specialization in pre-approved compliance frameworks for regulated industries distinguishing its market position.
| Leading Market Players |
|---|
| DSMN8 |
| Octopost |
| Sociabble |
| Ambassify |
| PostBeyond |
| EveryoneSocial |
| Haiilo |
| GaggleAMP |
| Supergrow |
| Others |
Supply Flow & Price Mechanics
Undercapacity in GDPR-compliant consent engineering across European data protection authorities is driving premium pricing for certified architectures while compressing margins for non-compliant vendors. SaaS-centric enterprises in California and New York exploit this bifurcation to negotiate outcome-based contracts with guaranteed impression thresholds.
Pricing Analysis
Certification level creates the primary spread between ISO 27001-certified enterprise tiers and uncertified mid-market offerings. The dominant pricing structure is subscription-based SaaS with seat-based tiers, though outcome-based engagement contracts are displacing traditional renewals in large corporations. Price differentiation hinges on compliance grade and integration complexity with legacy HR systems. Pricing pressure intensifies downward in the small business segment as self-service onboarding tools commoditize basic distribution features. Large corporations show least price sensitivity due to procurement teams prioritizing security credentials over unit cost.
Supply Chain Analysis
Extended payment terms from enterprise buyers in the United States and Germany are squeezing working capital for API-dependent platform vendors. Engineering talent concentrates in India, the United Kingdom, and Germany, with Bangalore and Hyderabad technology corridors feeding development pipelines. Raw material dependencies center on cloud infrastructure from hyperscalers, consent management middleware, and real-time analytics engines. Single-source vulnerability looms in API access to LinkedIn, X, and Meta, where platform policy changes can sever distribution channels without notice. Distribution runs through direct sales teams for enterprise accounts and channel partner networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among SaaS-centric enterprises in California and New York, with procurement teams consolidating vendor relationships around performance-linked agreements that shift risk to suppliers.
For Market Incumbents: Harden compliance architectures against EU AI Act risk-based classification requirements by embedding human oversight interfaces into automated content recommendation engines. Deepen integration with European workplace communication stacks to defend against GDPR-specialized regionalists. Prioritize ISO 27001 certification maintenance as enterprise procurement evaluations now demand baseline security credentials that mid-tier vendors struggle to fund. For New Entrants and Emerging Players: Build out vertical-specific content templates for regulated industries where pre-approved compliance frameworks create defended positions generalist platforms cannot easily replicate. Target financial services on-premises solutions for stringent data residency requirements, a niche underpenetrated relative to cloud saturation. Lead with self-service onboarding tools to compress procurement cycles for resource-constrained small businesses. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment tiers as multi-tenant architectures reduce infrastructure capital requirements. Long-term viability favors vendors with explainable AI governance interfaces and documented decision logic for algorithmic content suggestions. Watch for API policy changes at LinkedIn, X, and Meta as inflection indicators that could sever core distribution channels and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Haiilo-style embedding with European workplace communication stacks locks in switching costs. |
| Compliance Architecture Upgrade | EU AI Act human oversight interfaces differentiate vendors in GDPR enforcement zones. |
| Channel Partner Expansion | GaggleAMP-style networks extend reach among distributed sales teams without direct sales overhead. |
| Vertical Template Development | EveryoneSocial-style pre-approved frameworks defend positions in regulated healthcare and finance sectors. |
| Outcome-Based Contract Structuring | Performance-linked agreements pioneered by California and New York procurement teams shift vendor risk. |
Methodological Framework
The analysis maps cloud-based deployment, on-premises solutions, SaaS layers, and hybrid architectures, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie/Sensor Tower data, and GDPR enforcement records. Bottom-up sizing of vendor deployments triangulates against top-down estimates of workforce social graph monetization across the analysis window.
Assumptions held fixed include continued API access to LinkedIn, X, and Meta, steady-state GDPR enforcement intensity, and persistent demand concentration among SaaS-centric enterprises in California and New York. Variables modeled across deployment model, organization size, vertical compliance exposure, integration complexity, and regional adoption pattern. CAGRs derive from segmented growth trajectory analysis incorporating self-service onboarding tool maturity, consent engineering talent scarcity, and state-level privacy statute proliferation as industry-specific inputs.
Stress conditions across API policy disruption, adequacy decision fragmentation, and AI governance enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and boundary conditions. Macroeconomic contraction, regulatory acceleration, or generative content engine breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Procure to Pay Software Market
Software & Services
Global Portal Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Employee Referral Software Market
Software & Services
India Sports Management Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Winery Management Software Market
Software & Services
Global PEO Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Business Card Software Market
Software & Services
Global Data Recovery Software Market
Software & Services
Global Driving School Software Market
Software & Services
Patent Management Software Market
Software & Services
North America IT Services Market