
 Canada Nutraceuticals Market | 2026-2036
Canada Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Nutraceuticals Market Analysis
Market Overview
Registered dietitian shortages across Prairie provinces and Atlantic Canada are redrawing regional distribution strategies for nutraceutical brands. Jamieson Wellness Inc. leverages its domestic manufacturing footprint to sustain shelf presence in national pharmacy chains. Natural Factors Nutritional Products Ltd. anchors its supply chain through British Columbia-based botanical extraction facilities. Organika Health Products differentiates via direct-to-consumer subscription models targeting urban millennials.
Product and Application Segments
Nutraceuticals comprise bioactive compounds, fortified foods, and dietary supplements formulated to deliver physiological benefits beyond basic nutrition, typically standardized to contain defined concentrations of active markers such as polyphenols, omega-3 fatty acids, or colony-forming units of live cultures. Vitamins and probiotics command the largest revenue share within product type classification, reflecting chronic disease prevention positioning and gut-brain axis research proliferation. Immune support applications outpace weight management in growth velocity, though heart health formulations retain the most mature consumer loyalty base among application categories.
Regulatory Environment and Outlook
Health Canada's NHPD, the Canadian Food Inspection Agency, and provincial pharmacy regulatory colleges collectively govern product licensing, label claims, and retail channel access for nutraceutical distribution. NHPD's site licensing and good manufacturing practice requirements filter smaller importers while rewarding domestic producers with established quality management systems. Stakeholders must monitor pending changes to natural health product cost recovery frameworks and provincial scope-of-practice expansions for naturopathic prescribing rights.
Market Dynamics
Health Canada's NHPD licensing backlog is compressing product launch timelines, forcing brands to front-load clinical substantiation costs and restructure regulatory affairs teams around pre-submission dossier quality.
Growth Catalysts
- Immune Support Positioning:Post-pandemic consumer retention of preventive health habits sustains demand for zinc, vitamin D, and elderberry formulations in Ontario and British Columbia retail channels.
- Provincial Scope-of-Practice Expansion:Alberta and British Columbia naturopathic prescribing rights extension opens pharmacy reimbursement pathways previously restricted to allopathic practitioners.
- Clean-Label Certification:NSF International and Informed Sport third-party verification programs command shelf placement premiums in sports nutrition aisles of national pharmacy chains.
Market Restraints
- Botanical Raw Material Concentration:Over 60% of standardized herbal extracts originate from Chinese and Indian contract manufacturers, exposing margin compression from ocean freight volatility and customs inspection delays.
- NHPD Site Licensing Compliance Costs:Good manufacturing practice audit requirements and annual license maintenance fees disproportionately burden importers lacking domestic manufacturing infrastructure.
- Probiotic Stability Limitations:Refrigeration-dependent live culture formulations face distribution bottlenecks in northern territories and rural Prairie regions with cold-chain gaps.
Strategic Opportunities
- Atlantic Canada Underpenetration:Newfoundland and Labrador plus Prince Edward Island exhibit per-capita supplement consumption 40% below Ontario levels, creating whitespace for direct-to-consumer subscription models.
- Personalized Nutrition Convergence:At-home microbiome testing kits paired with algorithm-driven probiotic recommendations are attracting venture capital into Toronto-based health technology startups.
- Senior Nutrition Channel Innovation:Long-term care facility group purchasing organizations in Quebec and Ontario are consolidating vendor lists, favoring suppliers with formulary compliance and bedside delivery capabilities.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Experienced NHPD dossier preparers command premium salaries in Toronto and Vancouver, constraining mid-market brand expansion timelines.
- Legacy ERP Integration Friction:Batch record digitization and electronic quality management system adoption strain family-owned manufacturers with decades-old paper-based documentation workflows.
- Certificate of Analysis Verification Burden:Retailer mandates for identity testing documentation at receiving docks extend procurement cycle times and strain supplier quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Nutraceuticals Market |
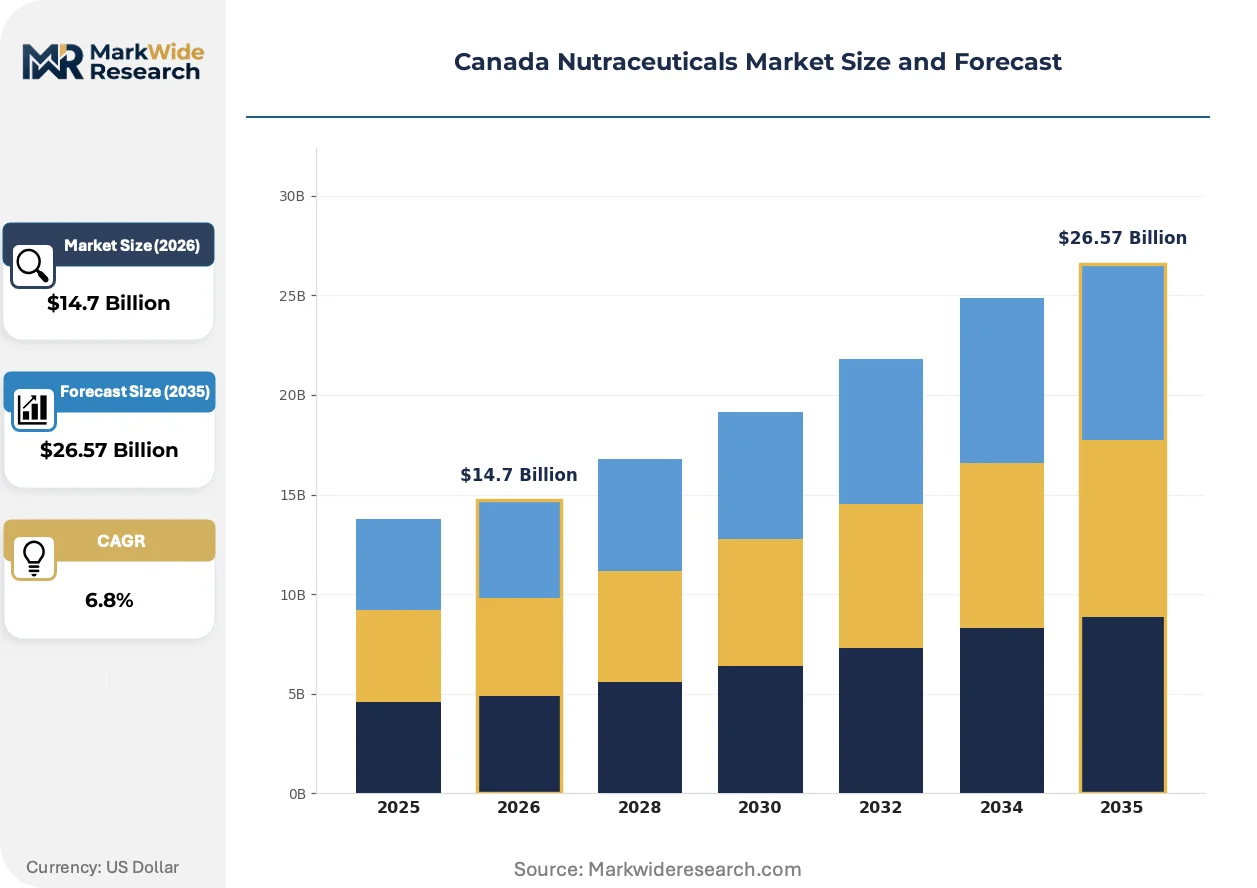
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Vitamins, Minerals, Probiotics Application: Weight Management, Immune Support, Digestive Health, Heart Health End User: Adults, Seniors, Athletes, Pregnant Women Sales Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | SISU Inc., Prairie Naturals, Jamieson Wellness Inc., PNP Pharmaceuticals, ENZ Pharmtech, Natural Factors Nutritional Products Ltd., Genuine Health, CSN Pharma, Organika Health Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Nutraceuticals Market Emerging Trajectories
Biotechnology and regulatory science are converging to compress development cycles while fragmenting consumer touchpoints across clinical, retail, and digital channels.
Precision fermentation is decomposing traditional botanical extraction economics. Startups in Montreal and Vancouver are engineering yeast strains to biosynthesize rare cannabinoids and alkaloids previously harvested from agricultural crops. Pharmaceutical-grade purity standards from these facilities attract brands seeking to bypass agricultural supply constraints and pesticide residue testing requirements.
Health Canada's pending natural health product cost recovery framework amendment is reallocating regulatory risk. Proposed annual license fees scaled to product portfolio size would accelerate consolidation among micro-brands while rewarding established domestic manufacturers with amortized compliance infrastructure. British Columbia-based botanical extractors are preemptively expanding in-house stability testing laboratories to reduce third-party dependency.
Subscription-based replenishment models are displacing pharmacy aisle browsing among urban millennials. Toronto and Vancouver direct-to-consumer brands leverage microbiome test results and AI-curated regimen recommendations to secure 12-month commitments. This channel shift concentrates customer acquisition spending on digital performance marketing while eroding traditional wholesale margin structures.
Canada Nutraceuticals Market Segmentation
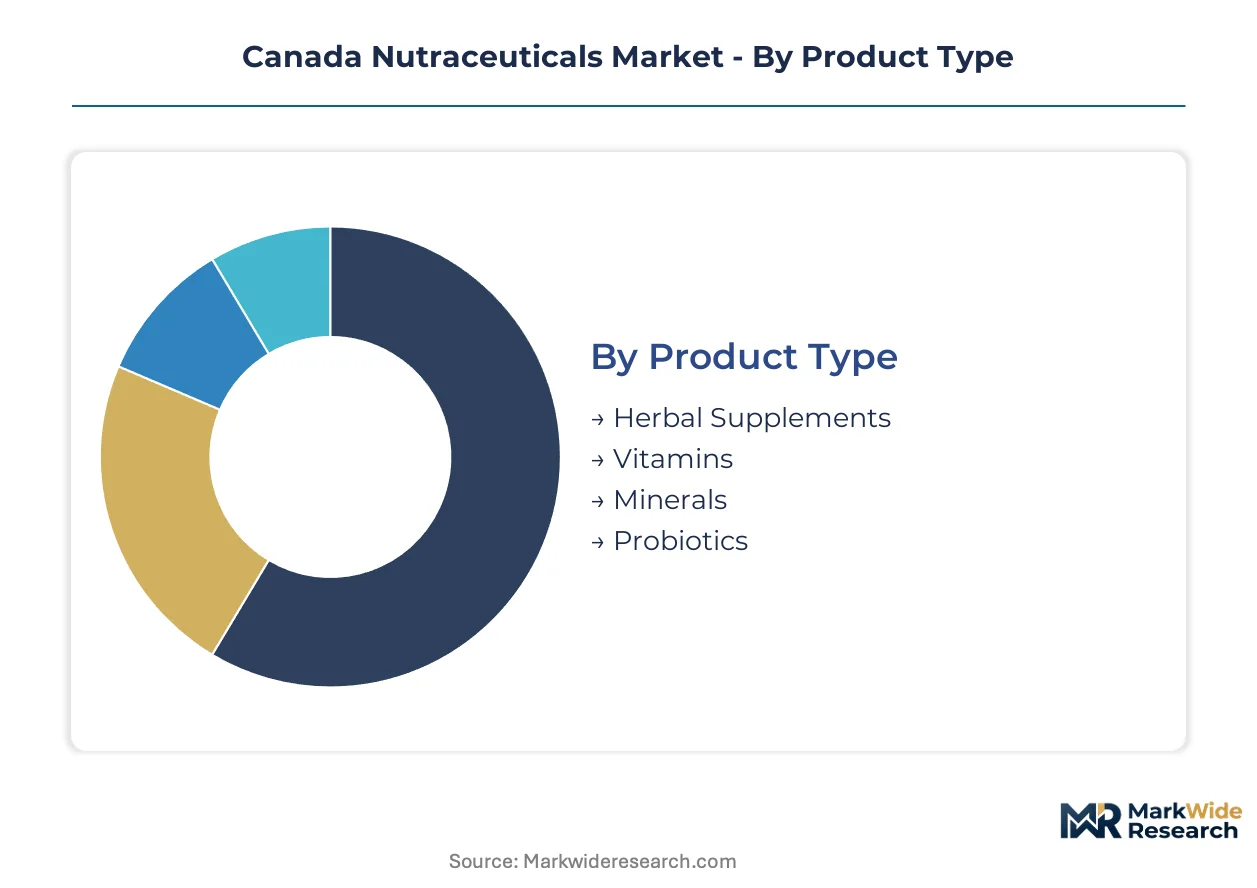
Segmentation in the Canada nutraceuticals market reflects divergent regulatory pathways and channel economics. Health Canada's NHPD dossier requirements favor standardized formulations over complex botanical matrices, concentrating investment toward segments with clearer safety profiles and faster approval timelines.
Product Type:
Regulatory differentiation separates probiotics and vitamins from herbal supplements through divergent stability testing requirements and site licensing thresholds.
- Vitamins:Synthetic and natural isolates standardized to USP or FCC monographs dominate pharmacy shelf space. Ontario and British Columbia health-conscious aging adults drive demand for vitamin D and B-complex formulations, supported by provincial preventive health guidelines and reimbursement dialogues.
- Probiotics:Live culture formulations require refrigerated supply chains and CFU count verification at expiry. Distribution bottlenecks in northern territories and rural Prairie regions constrain penetration, though British Columbia-based manufacturers leverage domestic fermentation capacity to bypass import cold-chain gaps.
- Minerals:Chelated and inorganic salt forms face bioavailability competition from food-matrix alternatives.
- Herbal Supplements:Standardized extracts from Chinese and Indian contract manufacturers expose brands to customs inspection delays and pesticide residue testing burdens.
Established volume favors vitamins; emerging adoption favors probiotics.
Application:
Cost tier stratification separates premium-positioned immune formulations from commoditized weight management products competing on price per serving.
- Immune Support:Zinc, vitamin D, and elderberry combinations command shelf placement premiums in national pharmacy chains. Post-pandemic consumer retention of preventive health habits sustains demand across Ontario and British Columbia retail channels, with Toronto and Vancouver serving as primary distribution hubs.
- Digestive Health:Prebiotic-probiotic synbiotics and fiber supplements target gut-brain axis positioning. Alberta and British Columbia naturopathic prescribing rights extension opens pharmacy reimbursement pathways previously restricted to allopathic practitioners.
- Heart Health:Omega-3 fatty acids and plant sterol formulations retain the most mature consumer loyalty base among application categories.
- Weight Management:Meal replacement and thermogenic ingredients face margin compression from functional food competition and skeptical regulatory scrutiny of metabolic claims.
Mature positioning favors heart health; steepest expansion trajectory belongs to immune support.
End User:
Customer type concentration reflects demographic purchasing power and channel access patterns across provincial healthcare systems.
- Seniors:Long-term care facility group purchasing organizations in Quebec and Ontario consolidate vendor lists, favoring suppliers with formulary compliance and bedside delivery capabilities. Chronic disease prevention positioning drives calcium, vitamin D, and protein supplementation protocols.
- Adults:Urban millennials in Toronto and Vancouver subscribe to direct-to-consumer replenishment models curated by microbiome test results. Workplace wellness programs in Ontario expand employer-subsidized supplement allowances.
- Athletes:NSF International and Informed Sport third-party verification programs command shelf placement premiums in sports nutrition aisles.
- Pregnant Women:Folic acid and DHA formulations require prenatal-specific labeling and healthcare practitioner endorsement channels.
Volume concentration favors adults; emerging channel innovation targets seniors.
Sales Channel:
Margin structure divergence separates high-touch pharmacy consultation models from low-margin supermarket self-service and digital direct-to-consumer acquisition economics.
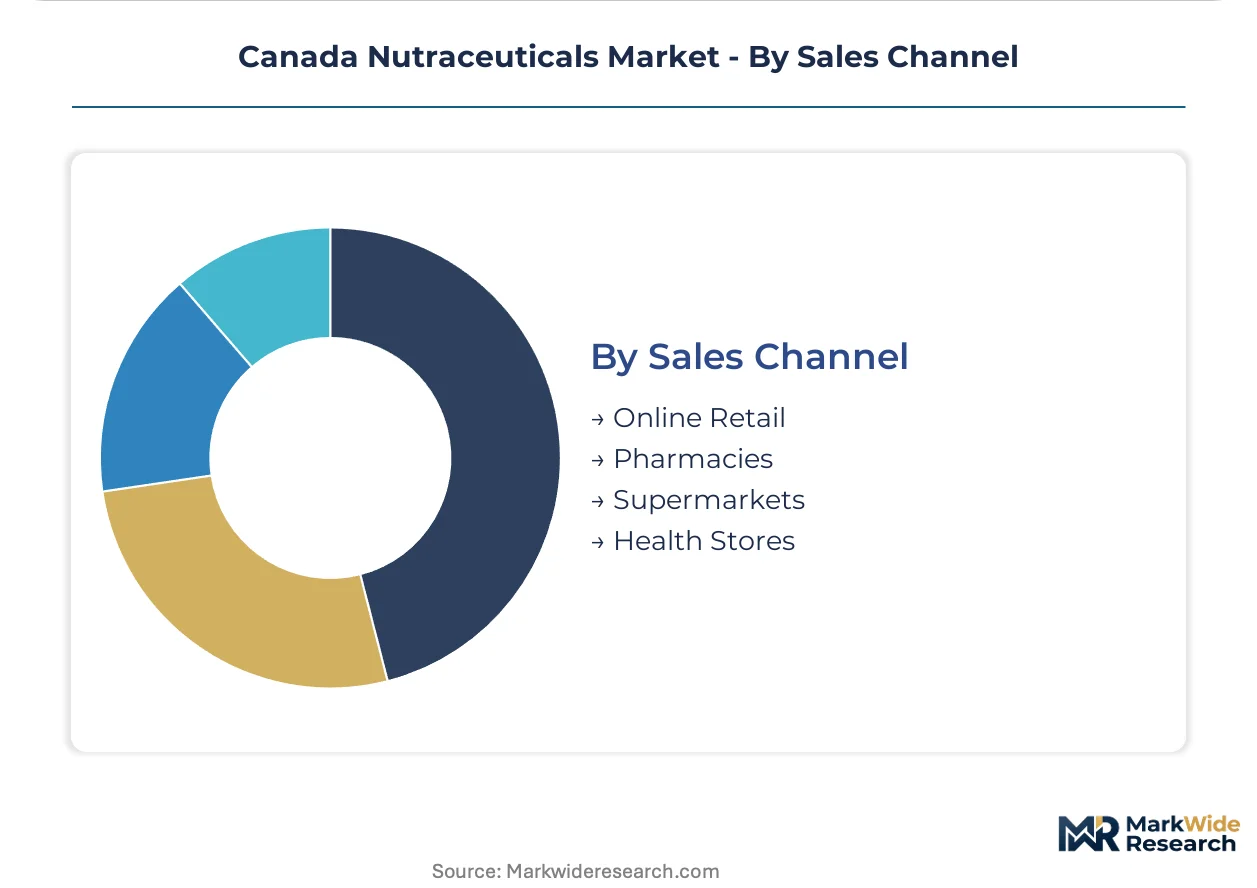
- Pharmacies:National chains leverage registered dietitian shortages across Prairie provinces and Atlantic Canada to consolidate category management authority. Jamieson Wellness Inc. sustains shelf presence through domestic manufacturing footprint and NHPD compliance infrastructure.
- Online Retail:Subscription-based replenishment models displace aisle browsing among urban millennials. Organika Health Products differentiates via algorithm-driven regimen recommendations securing 12-month customer commitments.
- Health Stores:Independent retailers emphasize practitioner-grade lines and personalized consultation services.
- Supermarkets:Mass-market positioning prioritizes price-per-unit competitiveness and impulse purchase visibility.
Channel maturity favors pharmacies; digital acquisition spending is concentrating fastest in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands shelf placement premiums that Atlantic Canada cannot match, creating a pricing-power asymmetry that reshapes distribution economics for domestic nutraceutical brands.
Ontario
Toronto's concentration of health-conscious aging adults drives probiotic and immune support formulation purchases through national pharmacy chains. Health Canada's NHPD site licensing requirements filter smaller importers while rewarding established domestic producers with quality management infrastructure. The Greater Toronto Area anchors direct-to-consumer subscription models targeting urban millennials with algorithm-curated regimen recommendations.
British Columbia
Vancouver serves as the primary West Coast distribution hub for botanical extraction facilities supplying standardized herbal ingredients. Naturopathic prescribing rights extension opens pharmacy reimbursement pathways previously restricted to allopathic practitioners. Vancouver-based manufacturers leverage domestic fermentation capacity to bypass import cold-chain gaps for live culture formulations.
Quebec
Long-term care facility group purchasing organizations consolidate vendor lists, favoring suppliers with formulary compliance and bedside delivery capabilities. Provincial preventive health guidelines support vitamin D and calcium supplementation protocols for chronic disease prevention. Montreal hosts precision fermentation startups engineering yeast strains to biosynthesize rare bioactive compounds.
Alberta
Naturopathic scope-of-practice expansion creates reimbursement pathways for digestive health formulations through extended practitioner authority. Workplace wellness programs in Calgary and Edmonton expand employer-subsidized supplement allowances for adult demographics. Prairie distribution strategies adapt to registered dietitian shortages that redraw regional category management approaches.
Atlantic Canada
Newfoundland and Labrador plus Prince Edward Island exhibit per-capita supplement consumption significantly below Ontario levels, creating whitespace for market development. Cold-chain gaps in northern territories and rural regions constrain probiotic distribution for refrigeration-dependent live culture products. Halifax anchors Atlantic distribution infrastructure for brands seeking to penetrate underpenetrated maritime markets.
Canada Nutraceuticals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canada nutraceuticals market, with domestic manufacturers leveraging NHPD compliance infrastructure against import-dependent competitors facing site licensing burdens. The vendor base clusters around three strategic tiers: established domestic producers with captive manufacturing, direct-to-consumer digital natives with subscription retention models, and regional specialists serving practitioner-grade channels. Consolidation pressure is accelerating through pending natural health product cost recovery framework amendments that would scale annual license fees to portfolio size. Strategic moves concentrate on preemptive laboratory capacity expansion and algorithm-driven personalization platform development.
Within the domestic manufacturing tier, Jamieson Wellness Inc., Natural Factors Nutritional Products Ltd., and Organika Health Products occupy positions that exemplify divergent channel strategies. Jamieson anchors shelf presence in national pharmacy chains through its domestic manufacturing footprint. Natural Factors represents the botanical extraction specialist archetype with British Columbia-based supply chain control. Organika sits within the direct-to-consumer digital native category, leveraging subscription models to secure extended customer commitments.
| Leading Market Players |
|---|
| SISU Inc. |
| Prairie Naturals |
| Jamieson Wellness Inc. |
| PNP Pharmaceuticals |
| ENZ Pharmtech |
| Natural Factors Nutritional Products Ltd. |
| Genuine Health |
| CSN Pharma |
| Organika Health Products |
| Others |
Supply Flow & Price Mechanics
Health Canada's NHPD site licensing requirements gate both supplier qualification and shelf placement premiums simultaneously, compressing margins for import-dependent brands while rewarding domestic manufacturers with amortized compliance infrastructure. This regulatory filter concentrates pricing power among established producers with captive manufacturing, forcing smaller competitors toward direct-to-consumer channels where subscription retention models offset wholesale margin erosion.
Pricing Analysis
The customization-premium spread separates practitioner-grade formulations commanding consultation fees from mass-market SKUs competing on price-per-capsule. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—NSF International verification commands pharmacy placement premiums while uncertified alternatives face supermarket margin compression. Pricing pressure stems from botanical raw material concentration in Asian contract manufacturers exposing brands to freight volatility. Price-sensitive supermarket shoppers drive commoditization in vitamins and minerals, while least-sensitive seniors in long-term care facilities accept formulary premiums for bedside delivery bundling.
Supply Chain Analysis
Inventory lead times for standardized herbal extracts stretch due to customs inspection bottlenecks at Vancouver and Toronto ports. Geographic supply concentration centers on China and India for botanical raw materials, with domestic British Columbia extraction facilities serving as regional hedges. Raw material dependencies include polyphenol-rich plant matrices, omega-3 marine oils, and live culture fermentation substrates. Single-source vulnerability in probiotic strains creates formulation continuity risks when supplier quality incidents trigger NHPD compliance reviews. Distribution runs through Toronto and Vancouver as primary hubs, with Halifax anchoring Atlantic penetration attempts into underconsumed maritime markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada nutraceuticals market fragments across regulatory compliance tiers, channel economics, and provincial healthcare system variations, creating niches for specialized players as direct-to-consumer models displace traditional pharmacy browsing among urban millennials.
For Market Incumbents: Consolidate manufacturing footprint advantages by preemptively expanding in-house stability testing laboratories before Health Canada's pending cost recovery framework amendments scale license fees to portfolio size. Deepen backward integration into botanical extraction through British Columbia facility investments to bypass agricultural supply constraints and pesticide residue testing burdens from Chinese contract manufacturers. Channel control through long-term care group purchasing organization relationships in Quebec and Ontario defends against subscription-model erosion. For New Entrants and Emerging Players: Lead with microbiome testing integration paired with algorithm-driven probiotic curation to secure 12-month customer commitments in Toronto and Vancouver urban millennial segments. Target Atlantic Canada whitespace where Newfoundland and Labrador per-capita consumption trails Ontario levels by substantial margins, exploiting cold-chain gaps that constrain incumbent probiotic distribution. Go-to-market angle should emphasize direct-to-consumer digital acquisition over pharmacy shelf slotting fees that favor established domestic manufacturers. For Investors and Strategic Acquirers: Health Canada's pending natural health product cost recovery framework amendment reshapes the acquisition landscape by accelerating consolidation pressure on micro-brands lacking amortized compliance infrastructure. Long-term viability over the projection horizon favors targets with captive manufacturing, established NHPD dossier teams, and subscription retention platform capabilities. Watch naturopathic prescribing rights expansion across additional provinces as signal for pharmacy reimbursement pathway proliferation favoring digestive health and immune support formulations.| Strategic Initiative | Industry Significance |
|---|---|
| In-House Laboratory Expansion | Preemptive stability testing capacity reduces third-party dependency and NHPD compliance costs. |
| Subscription Platform Development | Algorithm-curated regimen recommendations secure 12-month commitments from urban millennials. |
| Atlantic Distribution Infrastructure | Halifax anchoring penetrates underconsumed maritime markets with 40% consumption gaps. |
| Precision Fermentation Investment | Montreal and Vancouver startups engineer yeast strains bypassing agricultural supply constraints. |
| Long-Term Care GPO Relationships | Quebec and Ontario formulary compliance secures vendor list consolidation advantages. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NHPD licensing databases, Health Canada regulatory filings, and provincial pharmacy procurement records, combining interviews with regulatory affairs directors, natural health product formulators, and pharmacy category managers with customs trade data and industry association reports. Bottom-up triangulation across product-level volume estimates and top-down validation against national health expenditure patterns ensures consistency across the analysis window.
Segmentation dimensions modeled span product type classification, application positioning, end-user demographic concentration, and sales channel economics across provincial regulatory clusters. CAGRs derive from regression analysis of historical consumption patterns adjusted for demographic shift projections and regulatory timeline impacts. Industry-specific forecast inputs include naturopathic prescribing rights expansion trajectories and precision fermentation technology adoption curves.
Underlying assumptions cover stable NHPD licensing processing timelines, with deviation risk concentrated in pending cost recovery framework amendments and ocean freight volatility affecting botanical raw material flows. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Vitamins and Minerals Market