
 North America Collagen Supplements Market | 2026-2036
North America Collagen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Collagen Supplements Market Insights
Marine collagen is rebalancing raw-material economics as land-based sources face feedstock cost pressure. GELITA AG leverages its bovine-hide processing infrastructure to sustain supply continuity across the United States and Canada. Vital Proteins anchors its position through direct-to-consumer channel control and premium branding. Sports Research Corporation differentiates via third-party certification programs that resonate with performance-oriented buyers.
North America collagen supplements comprise hydrolyzed collagen peptides, gelatin derivatives, and liquid concentrates formulated for oral consumption, typically standardized to specific molecular weights between 2,000 and 5,000 Daltons for optimal bioavailability. These products serve dermatological, musculoskeletal, and sports-recovery applications across consumer wellness and clinical nutrition contexts. Hydrolyzed collagen and collagen peptides occupy the dominant volume share due to superior dissolution properties and broader formulation compatibility. The aging population segment generates premium pricing power, while gummies and liquid forms are capturing faster growth among younger demographics seeking convenience-driven delivery systems.
FDA cGMP regulations and FTC advertising substantiation requirements shape product claims, labeling accuracy, and market access thresholds across the United States. Health Canada's Natural and Non-prescription Health Products Directorate imposes comparable purity and safety standards for Canadian market entry. Stakeholders must monitor evolving NDI notification pathways and state-level Prop 65 enforcement in California, as these frameworks will determine which formulations achieve scalable distribution without regulatory friction.
Market Dynamics
FDA cGMP enforcement is compressing supplier margins while simultaneously elevating quality thresholds, forcing smaller formulators to exit or consolidate as certification costs concentrate market power among scaled processors.
Growth Catalysts
- Sports nutrition demand:Amateur and professional athletes are deepening consumption of hydrolyzed collagen peptides for joint recovery and tendon resilience, particularly in competitive cycling and CrossFit training communities.
- California wellness economy:The state's Prop 65 compliance infrastructure has created a de facto national quality benchmark, with West Coast retailers demanding third-party testing documentation that propagates eastward.
- Marine collagen processing:Alaskan and North Atlantic fishery byproduct utilization is reducing raw-material dependence on Brazilian and Argentine bovine hide supplies subject to feedstock volatility.
Market Restraints
- Bovine hide cost volatility:Cattle herd contraction in the US Midwest and Canadian prairies is elevating gelatin precursor prices, compressing margin structures for land-sourced collagen processors.
- Supply concentration risk:Three integrated processors control approximately two-thirds of North American hydrolyzed peptide capacity, creating vulnerability to single-site disruption or coordinated pricing.
- Prop 65 litigation exposure:California's private attorney general enforcement mechanism generates settlement costs and label reformulation expenses that disproportionately burden mid-tier brands without captive legal resources.
Strategic Opportunities
- Canadian natural health product registration:Health Canada's Natural and Non-prescription Health Products Directorate pathway offers differentiated positioning for US manufacturers willing to invest in NHP-number acquisition and bilingual labeling compliance.
- Liquid concentrate formats:Ready-to-drink collagen shots are capturing convenience-oriented consumers in urban California and New York metro corridors who reject powder-mixing rituals.
- Clinical nutrition partnerships:Hospital outpatient and long-term care formulary placement represents underpenetrated volume for wound-healing and sarcopenia applications, requiring USP verification and Medicare billing code alignment.
Industry Challenges
- Analytical chemistry talent scarcity:Molecular weight verification and amino acid profiling require specialized HPLC-MS expertise that commands premium compensation in biotech-competitive labor markets.
- Clean-label certification timelines:Non-GMO Project verification and NSF Certified for Sport accreditation each require 12-18 month validation cycles that delay product launch windows and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Collagen Supplements Market |
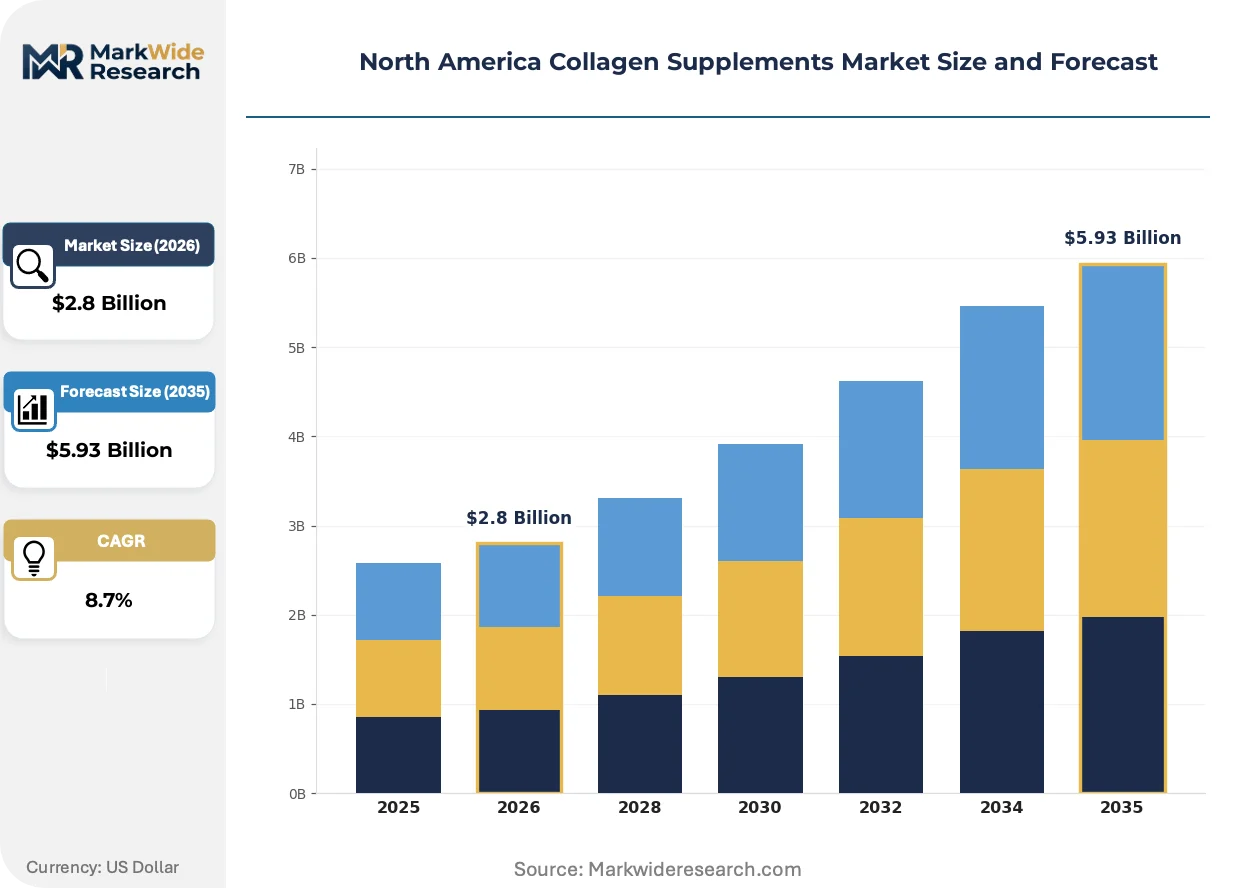
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Peptides, Gelatin, Liquid Collagen End User: Athletes, Fitness Enthusiasts, Aging Population, General Wellness Consumers Form: Powder, Capsules, Liquid, Gummies Distribution Channel: Online Retailers, Health Food Stores, Pharmacies, Supermarkets |
| Companies Covered | GELITA AG, Nestlé SA, Nitta Gelatin Inc., Rousselot, Vital Proteins, Amway Corp., Nordic Naturals, Sports Research Corporation, BUBS Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Collagen Supplements Market Trends and Innovations
Enzymatic hydrolysis protocols are compressing production cycles while marine-sourced inputs are rebalancing raw-material portfolios away from land-based dependencies. These shifts are reshaping competitive positioning around bioavailability claims and sustainability credentials.
Marine collagen peptide extraction from North Atlantic cod and Alaskan pollock processing waste is overtaking bovine-derived alternatives in premium positioning. Clean beauty and athletic recovery brands are adopting marine sources at accelerated pace to differentiate from commodity gelatin derivatives. This technology is overtaking legacy hide-processing economics by decoupling supply from cattle cycle volatility and enabling carbon-footprint narratives that command shelf price premiums.
FDA's 2023 updated guidance on New Dietary Ingredient notifications is tightening substantiation requirements for novel collagen delivery formats. Manufacturers must now demonstrate safety profiles for molecular weight distributions below 1,000 Daltons previously exempt from formal NDIN pathways. Powder and capsule segments are responding by reverting to established 2,000-5,000 Dalton specifications while liquid innovators absorb extended FDA pre-market consultation timelines.
Direct-to-consumer subscription models are displacing mass retail velocity as the primary growth channel for established collagen brands. Amazon's Subscribe & Save and proprietary Shopify storefronts are capturing recurring revenue from millennial and Gen-X buyers who prioritize convenience over in-store discovery. This behavioral shift is most visible in California's wellness corridor and Pacific Northwest urban markets, where digital-native brands bypass traditional wholesale markups entirely.
North America Collagen Supplements Market Segmentation
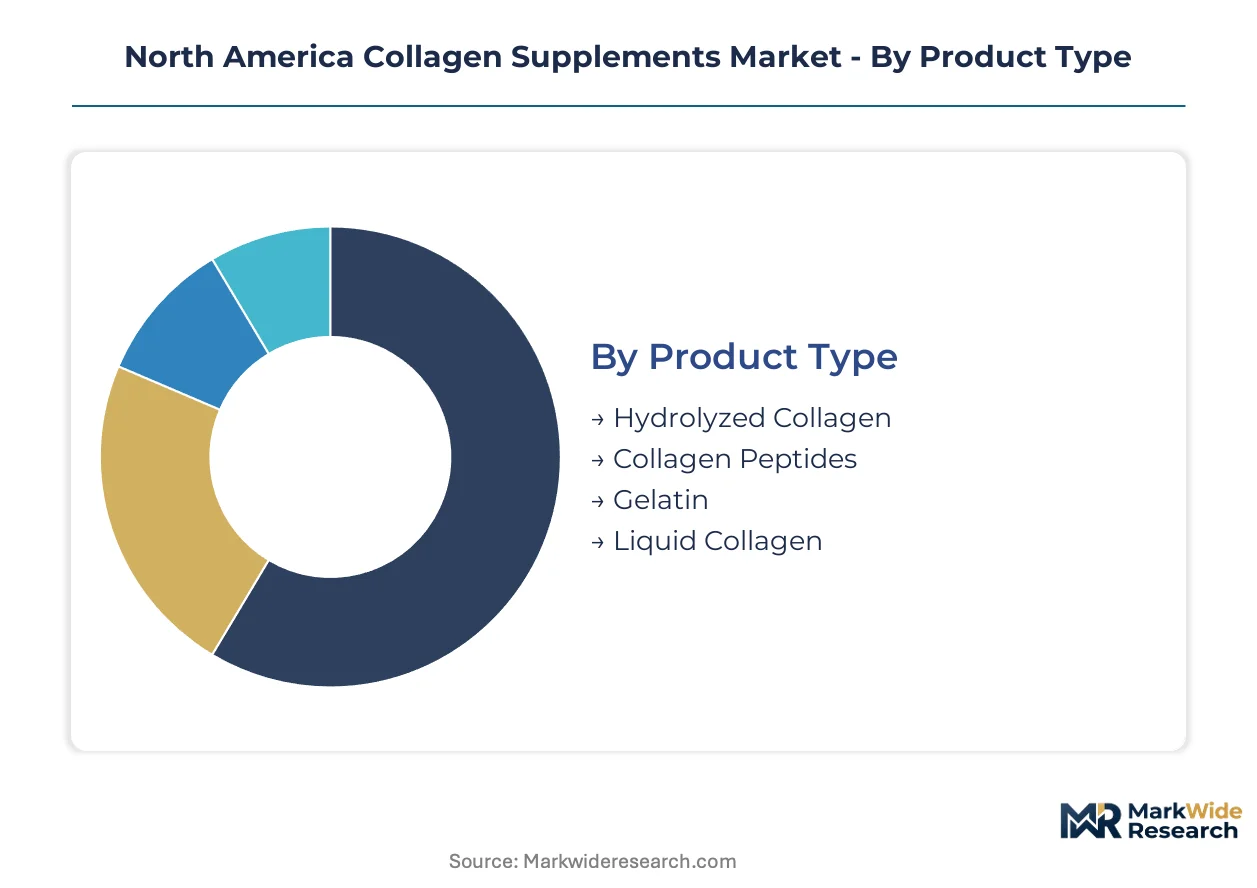
Collagen supplement buyers in North America exhibit sharply divergent technical preferences across molecular weight specifications, delivery format convenience, and channel access patterns. Segmentation reveals how formulation chemistry and purchasing behavior intersect to create distinct profit pools.
Product Type:
Buyers differentiate primarily by bioavailability requirements and dissolution speed rather than source origin alone.
- Hydrolyzed Collagen:Enzymatically cleaved proteins standardized to 2,000-5,000 Dalton molecular weights deliver superior intestinal absorption. Demand concentrates among CrossFit athletes and competitive cyclists in California who prioritize rapid tendon recovery post-training.
- Collagen Peptides:Fractionated short-chain amino acid sequences optimized for solubility in cold liquids without clumping. Sports nutrition brands in the US West Coast corridor favor this grade for ready-to-mix powder formulations targeting morning routine integration.
- Gelatin:Partially hydrolyzed collagen with gelling properties retains utility in functional food applications and clinical nutrition settings requiring texture modification.
- Liquid Collagen:Pre-dissolved concentrates eliminate preparation friction for convenience-seeking urban consumers in New York and Los Angeles metro areas.
Volume sits with hydrolyzed collagen; growth tilts toward liquid concentrates.
End User:
Performance demands and physiological aging create four distinct purchasing motivations with little overlap in brand loyalty.
- Athletes:Professional and amateur competitors in cycling, CrossFit, and endurance sports drive peptide-grade consumption for connective tissue resilience. NCAA and masters-level competitors generate recurring bulk purchases through team procurement channels.
- Fitness Enthusiasts:Recreational gym-goers prioritize cost-per-serving efficiency over molecular specification, responding to influencer marketing and subscription pricing models.
- Aging Population:Consumers over 55 seeking dermatological and joint health benefits command premium pricing tolerance. This segment generates the highest per-unit margins for clinically positioned brands with USP verification.
- General Wellness Consumers:Occasional purchasers motivated by beauty and lifestyle trends exhibit high churn and channel-hopping behavior across Amazon and Costco.
Margin concentration favors the aging population; customer acquisition costs climb fastest among general wellness buyers.
Form:
Preparation time and portability requirements split the market between ritual-based and on-the-go consumption occasions.
- Powder:Bulk containers dominate household pantry stocking among established users who blend into coffee or smoothies. This format retains cost efficiency but faces churn among younger demographics rejecting mixing steps.
- Capsules:Pre-measured dosing appeals to supplement-stackers combining collagen with multivitamins and omega-3s. Pharmacy and health food store placement drives trial among 35-50 year old buyers.
- Liquid:Single-serve shots capture urban professionals in California and Pacific Northwest corridors who prioritize consumption speed over price optimization.
- Gummies:Palatability-driven formats expand the addressable market to younger consumers and those with powder aversion, though gelatin content limits vegan positioning.
Distribution economics favor powder; format innovation concentrates in gummies and liquid.
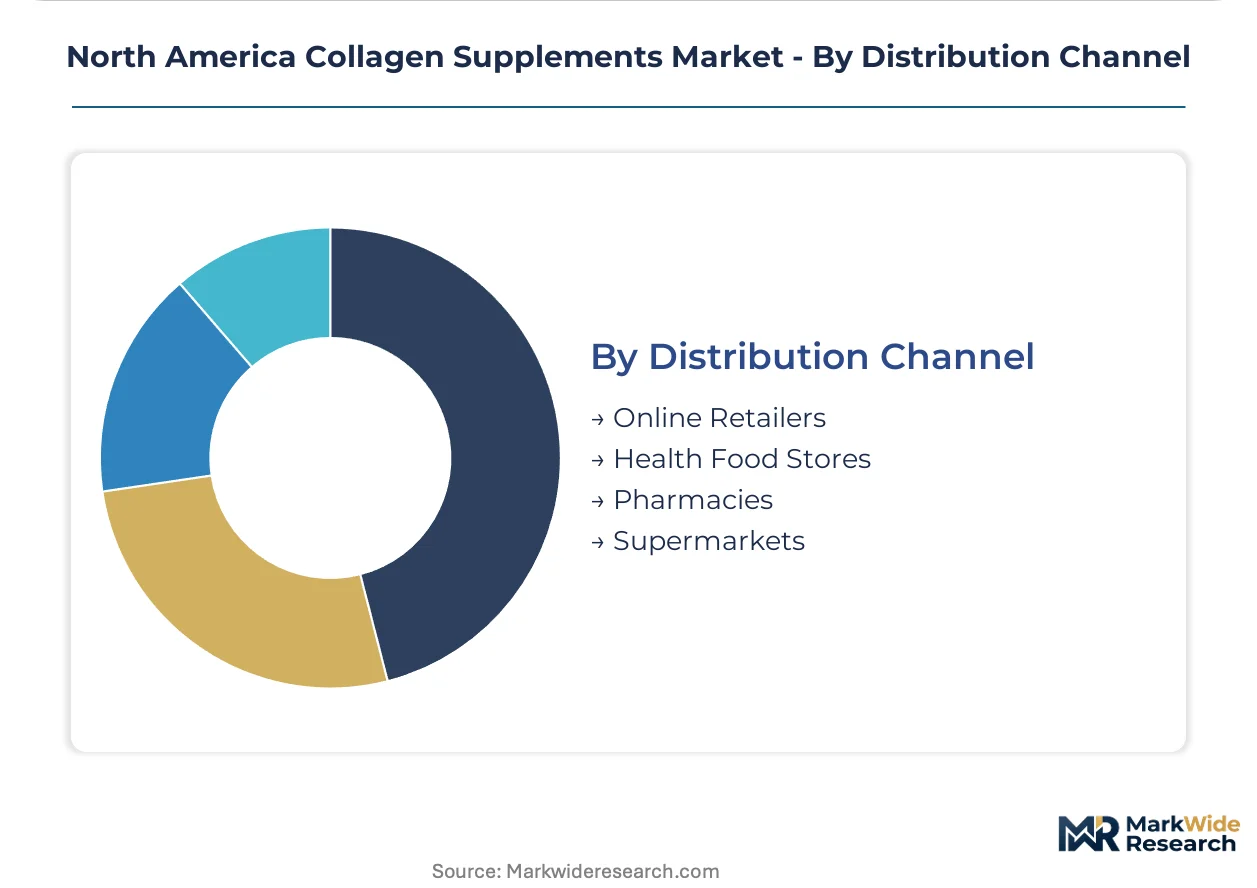
Distribution Channel:
Channel selection reflects buyer urgency, price sensitivity, and desire for tactile product evaluation before purchase.
- Online Retailers:Amazon Subscribe and Save and direct-to-consumer Shopify storefronts capture recurring revenue from digitally native millennial and Gen-X buyers. This channel enables subscription lock-in that mass retail cannot replicate.
- Health Food Stores:Specialty retailers like Whole Foods and Sprouts provide curated shelf space for third-party certified and marine-sourced premium lines. Staff consultation drives conversion for first-time buyers seeking sourcing transparency.
- Pharmacies:CVS and Walgreens placement signals clinical credibility for aging consumers and those with physician recommendations. This channel underperforms for lifestyle-positioned brands lacking USP or NSF certification.
- Supermarkets:Costco and Target mass placement achieves price-driven volume but compresses margins and dilutes premium positioning for established brands.
Recurring revenue flows through online; new customer acquisition depends on health food store presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along the US West Coast wellness corridor, with California's Prop 65 compliance infrastructure propagating quality benchmarks eastward. Canada offers differentiated positioning through Health Canada's Natural and Non-prescription Health Products Directorate pathway.
United States
California's wellness economy drives premium collagen consumption through direct-to-consumer subscription models and third-party certification requirements. FDA cGMP enforcement elevates quality thresholds nationwide, compressing margins for smaller formulators. Los Angeles and San Francisco anchor marine-sourced product innovation, with Alaskan fishery byproduct utilization reducing dependence on volatile bovine hide supplies.
Canada
Health Canada's NHP registration pathway attracts US manufacturers seeking bilingual labeling compliance and differentiated market positioning. Toronto and Vancouver concentrate distribution infrastructure for cross-border wellness brands. The Natural and Non-prescription Health Products Directorate imposes purity standards comparable to FDA requirements, creating regulatory alignment for scaled processors.
Mexico
Mexico City Metro generates emerging demand for convenience-driven liquid collagen formats among urban professionals. COFEPRIS pharmaceutical regulations govern supplement importation and labeling, though enforcement granularity trails US and Canadian frameworks. Monterrey and Guadalajara industrial clusters support contract manufacturing for brands seeking nearshore production alternatives.
North America Collagen Supplements Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with three integrated processors controlling approximately two-thirds of North American hydrolyzed peptide capacity. The vendor base concentrates around enzymatic hydrolysis expertise and marine-sourced raw material access, creating tiered competitive positions based on certification depth and channel control. Strategic archetypes include direct-to-consumer brand builders, bovine-hide infrastructure legacy players, and marine-collagen processing specialists. Dominant competitive moves encompass M&A-driven capacity consolidation and backward integration into Alaskan and North Atlantic fishery supply chains.
Within the infrastructure-anchored tier, GELITA AG exemplifies scaled bovine-hide processing continuity across the United States and Canada, while Vital Proteins occupies a position as the direct-to-consumer archetype with subscription-driven channel control. Sports Research Corporation represents the certification-forward specialist model, leveraging third-party validation to capture performance-oriented buyer segments.
| Leading Market Players |
|---|
| GELITA AG |
| Nestlé SA |
| Nitta Gelatin Inc. |
| Rousselot |
| Vital Proteins |
| Amway Corp. |
| Nordic Naturals |
| Sports Research Corporation |
| BUBS Naturals |
| Others |
Pricing and Supply Chain Analysis
HPLC-MS analytical chemist scarcity in Boston and San Diego biotech corridors widens spreads between USP-verified premium tiers and uncertified economy alternatives, as specialized labor costs propagate through molecular weight verification requirements.
Pricing Analysis
Volume concentrates in powder formats while margins accrue to liquid concentrates and third-party certified lines. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport products from basic hydrolyzed grades, with certification tier and molecular weight specification as primary differentiation drivers. Cost compression in economy powder segments is intensifying because Brazilian and Argentine bovine hide feedstock volatility transmits directly to landed costs. Fitness enthusiasts exhibit highest price sensitivity, while aging consumers seeking dermatological and joint health benefits demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Alaskan and North Atlantic fishery byproduct processors who supply marine collagen inputs. Raw material sourcing draws from Brazil, Argentina, and Alaskan fisheries, with enzymatic hydrolysis capacity concentrated among three integrated North American processors. Tariff exposure on South American bovine hides creates margin volatility for land-sourced collagen lines. Distribution runs through direct-to-consumer subscription platforms and health food specialty retailers, with mass retail channels capturing volume at compressed margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine collagen peptide extraction technology is displacing legacy bovine-hide processing economics, decoupling supply from cattle cycle volatility and enabling carbon-footprint narratives that command shelf price premiums.
For Market Incumbents: Acquire Alaskan and North Atlantic fishery processing assets to secure marine collagen raw material access and reduce dependence on Brazilian and Argentine bovine hide supplies subject to feedstock volatility. Invest in enzymatic hydrolysis capacity expansion to maintain quality thresholds as FDA cGMP enforcement compresses smaller formulator margins. Certification investment in NSF Certified for Sport and USP verification creates defensive moats against private-label entrants.
For New Entrants and Emerging Players: Price-point gaps between premium marine-sourced and economy bovine-derived tiers create entry space for mid-market hybrid formulations. Target clinical nutrition partnerships with hospital outpatient and long-term care facilities for wound-healing and sarcopenia applications, as this segment remains underpenetrated relative to sports nutrition. Launch with liquid concentrate formats in urban California and New York metro corridors where convenience-driven consumers reject powder-mixing rituals.
For Investors and Strategic Acquirers: Re-rating potential sits with marine-collagen processing specialists given accelerating clean beauty and athletic recovery brand adoption that decouples from commodity gelatin economics. Five-to-ten year viability favors processors with backward integration into fishery supply chains and captive enzymatic hydrolysis expertise. Watch for FDA New Dietary Ingredient notification enforcement patterns as inflection indicator for novel delivery format commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Supply Chains | Alaskan and North Atlantic byproduct access reduces Brazilian hide dependence and enables marine collagen premium positioning. |
| Third-Party Certification Investment | NSF Certified for Sport and USP verification unlock pharmacy placement and clinical nutrition partnerships. |
| Liquid Concentrate Format Development | Ready-to-drink collagen shots capture convenience-oriented urban professionals in California and New York corridors. |
| Direct-to-Consumer Subscription Platform Buildout | Proprietary Shopify storefronts and Amazon Subscribe and Save capture recurring revenue from millennial and Gen-X buyers. |
| Clinical Nutrition Partnership Establishment | Hospital outpatient and long-term care formulary placement opens underpenetrated volume for wound-healing applications. |
Research Methodology
Document review covered FDA cGMP guidance documents, Health Canada NHP registration pathways, and FTC advertising substantiation requirements, complemented by interviews with supplement brand managers, enzymatic hydrolysis plant engineers, health food store category buyers, and clinical nutrition procurement directors. Secondary validation drew from SEC 10-K filings of listed processors, customs and trade data on bovine hide imports, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, form, and distribution channel dimensions.
Segment-level projections across the analysis window incorporated molecular weight specification tiers, delivery format adoption curves, and channel shift dynamics. Modeled dimensions included hydrolyzed collagen versus collagen peptides versus gelatin versus liquid concentrates, athlete versus aging population versus general wellness buyer archetypes, and online retailer versus health food store versus pharmacy versus supermarket channel splits. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement intensity and raw material cost volatility.
Inputs from FDA enforcement action databases and Health Canada NHP registration timelines were available through the study window; gaps in proprietary subscription revenue data and clinical nutrition contract values introduce uncertainty bands around channel-specific forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Lipid Nutrition Market