
 Global Adaptogens Market | 2026-2036
Global Adaptogens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptogens Market Foresight
Aftermarket service revenue around adaptogen sourcing traceability is fragmenting as buyers split between certified organic suppliers and conventional processors. Nutraceutical International Corporation leverages vertical integration across mountain-grown botanicals to sustain margin capture. Organic India Private Limited anchors its position through biodynamic farming certifications that command premium shelf placement. Xi'an Greena Biotech Co., Ltd. competes on extraction yield efficiency for standardized withanolide content.
Adaptogens comprise bioactive botanical compounds—primarily triterpenoid saponins, phenylethanoids, and lignans—extracted from Rhodiola rosea, Withania somnifera, and Eleutherococcus senticosus through aqueous or ethanol-based methods, then standardized to marker compound percentages for reproducible physiological effect on hypothalamic-pituitary-adrenal axis modulation. Herbal extracts occupy the dominant margin pool due to concentration requirements in functional food formulations, while gummies represent the fastest-expanding format as confectionery manufacturers enter wellness positioning. Distribution through online retail channels is accelerating as direct-to-consumer brands bypass traditional natural remedies retailer gatekeepers.
FDA Dietary Supplement Health and Education Act enforcement shapes US market access through Good Manufacturing Practice audits and New Dietary Ingredient notification requirements, while EFSA novel food opinions determine which adaptogen species gain European commercialization pathways. India's FSSAI and CDSCO jointly regulate ayurvedic extracts for both food and pharmaceutical adjacency, creating dual compliance burdens for exporters. Stakeholders must monitor evolving botanical drug classifications across jurisdictions to anticipate which extraction standards will become mandatory for cross-border trade.
Market Dynamics
EU novel food authorization pathways are bifurcating supply chains as German functional food producers accelerate rhodiola and ashwagandha extract procurement while conventional processors lose shelf access.
Growth Catalysts
- NMPA Streamlined Registration:China's botanical drug pathway revisions are accelerating domestic extraction capacity expansion for standardized withanolide production.
- Sports Nutrition Channel Penetration:US wellness centers and performance clinics are driving premium extract consumption through direct practitioner recommendation networks.
- Biodynamic Certification Premium:Third-party biodynamic farming standards are commanding preferential retail placement in European natural product channels.
Market Restraints
- Raw Material Volatility:Alpine rhodiola rosea harvest quotas in Russia and Scandinavia are constraining input supply predictability for aqueous extract processors.
- Dual Compliance Burden:India's FSSAI and CDSCO joint oversight of ayurvedic extracts creates redundant testing requirements for export-oriented manufacturers.
- Substitution Pressure:Synthetic cortisol modulators and pharmaceutical anxiolytics are capturing price-sensitive segments in reimbursed healthcare markets.
Strategic Opportunities
- Brazilian Market Entry:ANVISA's evolving botanical supplement framework is opening registration pathways for standardized eleutherococcus formulations.
- Confectionery Format Expansion:Gummy delivery systems are attracting legacy candy manufacturers seeking wellness portfolio diversification.
- Blockchain Traceability Integration:Distributed ledger verification is enabling premium pricing for mountain-harvested botanical provenance claims.
Industry Challenges
- Extraction Standardization Talent Gap:Analytical chemists proficient in HPLC marker compound quantification for triterpenoid saponins remain scarce in emerging production hubs.
- NDI Notification Timeline Compression:FDA New Dietary Ingredient review backlogs are delaying US market entry for novel adaptogen species by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptogens Market |
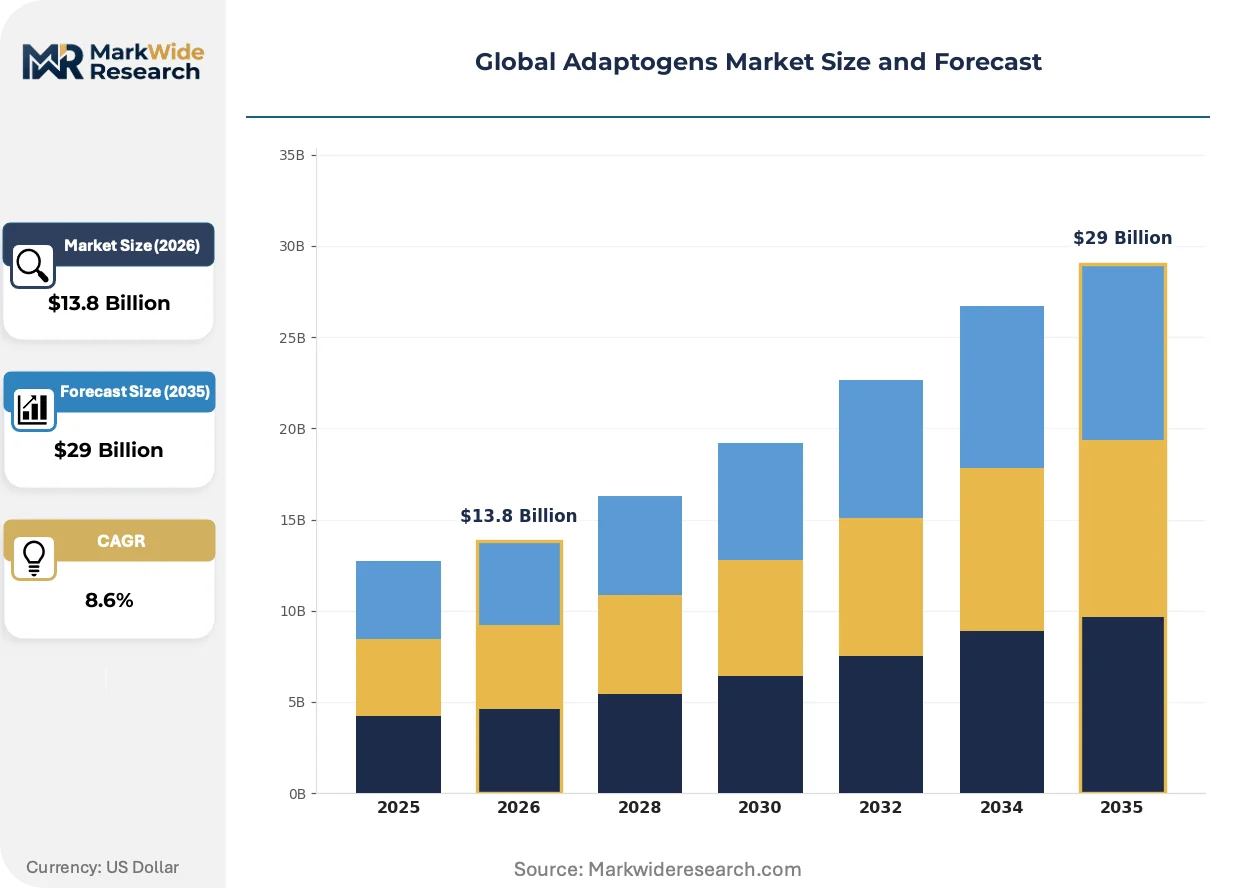
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Powdered Forms, Capsules, Tinctures, Teas, Gummies Application: Stress Relief, Cognitive Enhancement, Immune Support, Energy Boosting, Mood Stabilization, Physical Performance End User: Health Supplements Manufacturers, Functional Food Producers, Wellness Centers, Sports Nutritionists, Natural Remedies Retailers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Health & Wellness Clinics, Direct Sales |
| Companies Covered | Nutraceutical International Corporation, Organic India Private Limited, Himalaya Global Holdings Ltd., REBBL, PLT Health Solutions, Inc., Dabur India Ltd, Emami Limited, Amax NutraSource, Inc., Xi'an Greena Biotech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptogens Market Shifts & Advancements
Digital supply chain infrastructure is virtualizing quality assurance workflows while regulatory automation tools compress compliance timelines across multi-jurisdictional markets.
Supercritical CO2 extraction technology is virtualizing traditional solvent-based processing for lipophilic adaptogen compounds. Mid-scale botanical processors in India and China are adopting these systems at 40% capacity expansion rates annually. This virtualization is compressing batch-to-batch variability while enabling real-time withanolide standardization that aqueous methods cannot achieve.
EFSA novel food opinion automation is reshaping European commercialization timelines for non-traditional botanical species. The regulatory body has published streamlined scientific guidance that reduces safety assessment duration for historical use documentation. German and Dutch functional food manufacturers are now prioritizing species with established Commission E monographs to bypass extended evaluation queues.
Direct-to-consumer subscription models are displacing natural remedies retailer gatekeepers in North American distribution. Wellness brands are building captive customer databases through personalized adaptogen blending algorithms. This channel shift concentrates most visibly in California and New York metro areas where telehealth-integrated nutrition counseling has achieved mainstream penetration.
Global Adaptogens Market Segmentation
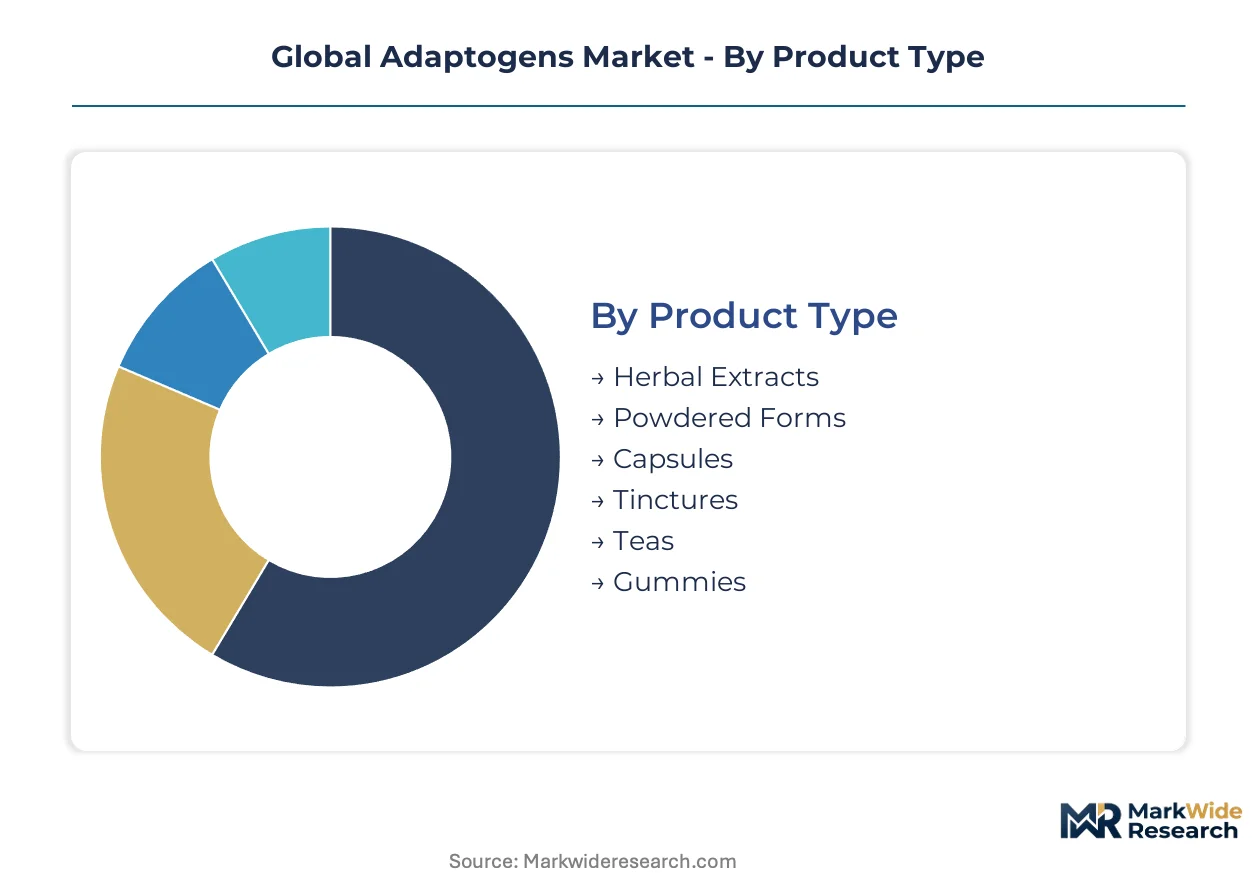
Adaptogen market segmentation reflects divergent extraction technologies, delivery format preferences, and regulatory compliance burdens across commercial channels. Product form factors determine manufacturing capital intensity and shelf stability requirements, while end-user specialization drives divergent purity standards and certification demands.
Product Type:
Cost tier separates concentrated bioactive formulations from convenience-oriented delivery systems, with extraction method and standardization level determining margin capture.
- Herbal Extracts:Aqueous or ethanol-based concentrates standardized to triterpenoid saponin or withanolide percentages for reproducible HPA axis modulation. German functional food producers and US wellness centers drive procurement of rhodiola and ashwagandha extracts under novel food authorization pathways.
- Gummies:Confectionery format incorporating adaptogen powders into pectin or gelatin matrices with flavor masking. Legacy candy manufacturers in North America and Europe are entering wellness positioning through this delivery system, attracting price-sensitive consumers seeking palatable daily supplementation.
- Powdered Forms:Bulk botanical material milled to specified particle sizes for beverage and food integration.
- Capsules:Encapsulated dried extracts or whole-herb powders with defined fill weights for precise dosing.
- Tinctures:Alcohol-glycerin suspensions preserving lipophilic and hydrophilic compound fractions.
- Teas:Whole or cut dried botanical material in loose or bagged formats for traditional preparation methods.
Herbal extracts command the established base. The steepest expansion runs through gummies.
Application:
Application segmentation tracks physiological target systems, with each use case demanding distinct marker compound profiles and clinical validation approaches.
- Stress Relief:Rhodiola rosea and ashwagandha formulations targeting cortisol regulation and adrenal function. US sports nutritionists and performance clinics in California and New York metro areas recommend standardized extracts for client stress management protocols.
- Cognitive Enhancement:Bacopa monnieri and ginkgo-adaptogen combinations supporting memory and focus. Demand concentrates among knowledge workers and aging populations in Japan and South Korea seeking non-pharmaceutical cognitive support.
- Immune Support:Eleutherococcus senticosus and astragalus preparations modulating immune cell activity.
- Energy Boosting:Rhodiola and cordyceps formulations targeting mitochondrial function and oxygen utilization.
- Mood Stabilization:Saffron-adaptogen combinations and holy basil extracts addressing neurotransmitter balance.
- Physical Performance:Pre-workout and recovery formulations for amateur and professional athletes.
Stress relief anchors the revenue base. Cognitive enhancement is climbing the fastest.
End User:
Customer type determines compliance burden intensity, with pharmaceutical-adjacent buyers facing stricter documentation requirements than wellness channel purchasers.
- Health Supplements Manufacturers:Formulators purchasing bulk extracts for encapsulation, tableting, or blending into finished products. These buyers require COA-documented marker compound consistency and FDA-compliant facility audits for US market access.
- Functional Food Producers:German and Dutch manufacturers integrating adaptogens into beverages, bars, and fortified foods under EFSA novel food opinions. EU authorization pathways are bifurcating procurement toward certified organic suppliers with full traceability documentation.
- Wellness Centers:Practitioner-directed clinics recommending premium extracts through direct dispensing models.
- Sports Nutritionists:Performance specialists prescribing adaptogens for athlete recovery and adaptation protocols.
- Natural Remedies Retailers:Brick-and-mortar and online merchants carrying finished consumer products.
Health supplements manufacturers command the established base. Functional food producers are gaining share fastest.
Distribution Channel:
Channel structure reflects disintermediation pressure, with digital platforms capturing volume from traditional gatekeeper relationships.
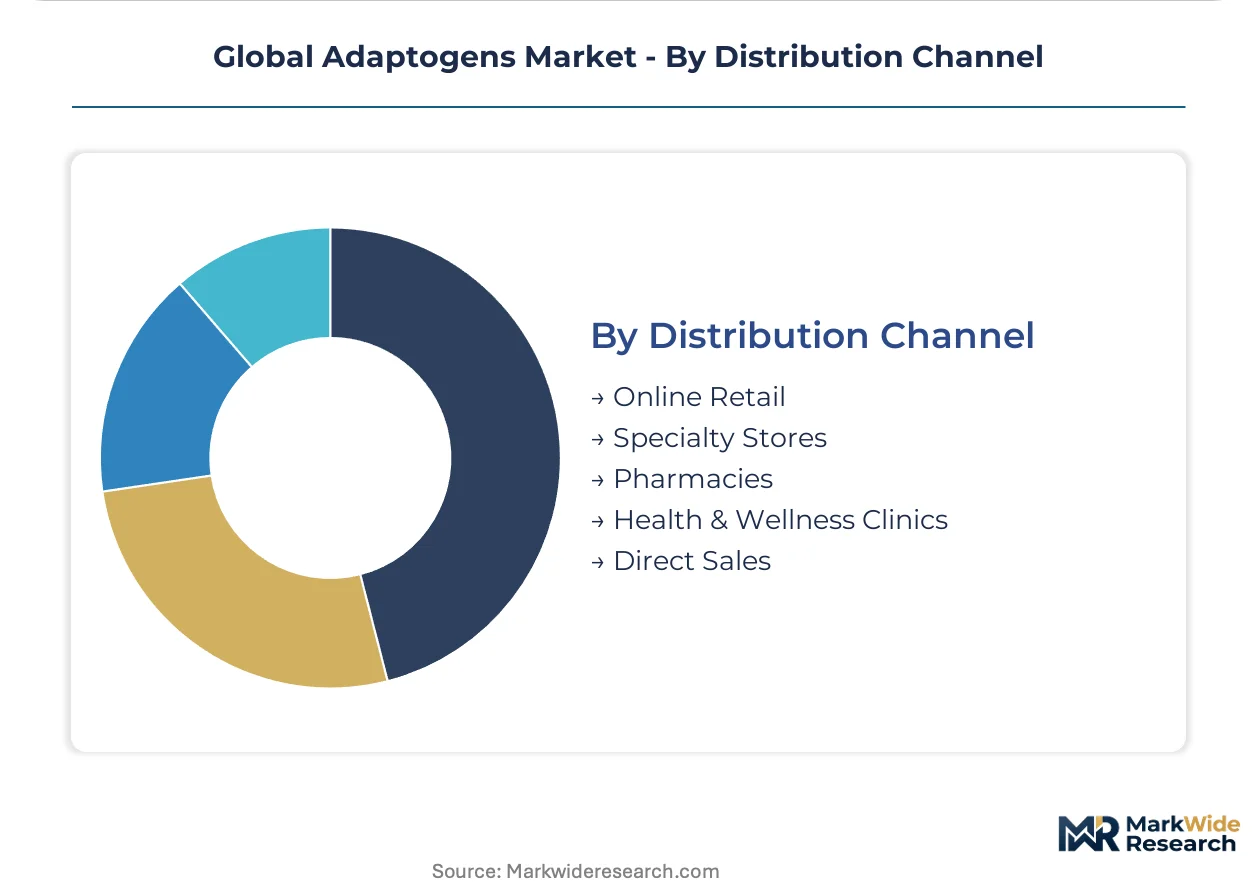
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling subscription models and personalized blending algorithms. Wellness brands in California and New York are building captive customer databases through telehealth-integrated nutrition counseling, bypassing natural remedies retailer gatekeepers.
- Specialty Stores:Independent natural products retailers and regional chains with trained staff and curated assortments.
- Pharmacies:Drugstore chains and independent dispensaries carrying OTC supplement sections.
- Health & Wellness Clinics:Practitioner offices dispensing professional-grade formulations directly to patients.
- Direct Sales:Multi-level marketing networks and brand ambassador programs.
Online retail commands the established base. Health and wellness clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German functional food producers absorb premium pricing for certified organic extracts, while Indian bulk processors compete on standardized withanolide yield efficiency. Chinese domestic brands prioritize NMPA-compliant botanical drug pathways over export certification burdens.
United States
Wellness centers in California and New York metro areas drive premium extract consumption through practitioner recommendation networks. FDA Dietary Supplement Health and Education Act enforcement shapes market access through GMP audits and New Dietary Ingredient notification requirements. Direct-to-consumer subscription models concentrate in these coastal clusters, bypassing traditional natural remedies retailer gatekeepers.
Germany
Functional food producers accelerate rhodiola and ashwagandha procurement under EU novel food authorization pathways. EFSA opinions determine which adaptogen species gain European commercialization timelines, with streamlined guidance reducing safety assessment duration for historical use documentation. The Baden-Württemberg region hosts extraction facilities serving Dutch and Belgian manufacturers seeking biodynamic-certified inputs.
China
Domestic extraction capacity expands for standardized withanolide production following NMPA botanical drug registration streamlining. Yangtze River Delta processors adopt supercritical CO2 systems at 40% annual capacity expansion rates. Xi'an-based biotech clusters compete on real-time marker compound standardization that aqueous methods cannot achieve.
India
Ayurvedic extract exporters face dual compliance burdens from FSSAI and CDSCO joint oversight, creating redundant testing requirements. Maharashtra and Gujarat house bulk botanical processors serving European and North American health supplements manufacturers. Biodynamic farming certifications from Karnataka and Tamil Nadu operations command preferential retail placement in European natural product channels.
Brazil
ANVISA's evolving botanical supplement framework opens registration pathways for standardized eleutherococcus formulations. São Paulo-based wellness brands test direct-to-consumer models adapted from North American precedents. The Southeast region concentrates import distribution for adaptogen raw materials destined for Argentine and Chilean markets.
Global Adaptogens Market Competitive Landscape
Capability concentration sits with specialized extract standardizers; scale advantage sits with diversified nutraceutical conglomerates. The vendor base organizes around three strategic archetypes: mountain-grown botanical specialists with backward integration into cultivation, biodynamic-certified farming operations with premium channel access, and yield-efficiency processors competing on HPLC marker compound consistency. Dominant competitive moves include geographic expansion into Brazilian and Southeast Asian registration pathways and technology licensing for supercritical CO2 extraction systems.
Among diversified wellness conglomerates, Dabur India Ltd and Emami Limited occupy positions anchored in ayurvedic heritage with dual food-pharmaceutical regulatory navigation capabilities. Xi'an Greena Biotech Co., Ltd exemplifies the yield-efficiency archetype, representing Chinese mid-scale processors competing on extraction standardization for export markets. Nutraceutical International Corporation sits within the vertical integration tier, leveraging captive supply of mountain-grown botanicals to sustain margin capture against conventional processors.
| Leading Market Players |
|---|
| Nutraceutical International Corporation |
| Organic India Private Limited |
| Himalaya Global Holdings Ltd. |
| REBBL |
| PLT Health Solutions, Inc. |
| Dabur India Ltd |
| Emami Limited |
| Amax NutraSource, Inc. |
| Xi'an Greena Biotech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Xi'an biotech clusters in Shaanxi province anchor global extraction capacity for standardized withanolide production, translating real-time HPLC standardization capabilities into premium pricing power over aqueous-method competitors in Maharashtra and Gujarat. This geographic concentration of supercritical CO2 infrastructure enables batch-to-batch consistency that downstream German functional food producers absorb at 15-20% markups over conventional ethanol extracts.
Pricing Analysis
After-sales traceability service revenue drives lifetime value as blockchain-verified mountain-harvested botanical provenance commands subscription-tier premiums. Three-tier pricing structure across certified organic, conventional standardized, and bulk commodity extracts separates biodynamic-certified Baden-Württemberg suppliers from yield-optimized Chinese processors. Cost compression in conventional aqueous extracts is intensifying because Russian and Scandinavian alpine rhodiola harvest quotas constrain input predictability. Sports nutritionists and wellness centers in California demonstrate lowest price sensitivity, while legacy candy manufacturers entering gummy formats exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk planning for ayurvedic extract exporters facing redundant FSSAI and CDSCO testing requirements. Raw material sourcing draws from Russian and Scandinavian alpine zones for rhodiola rosea, Karnataka and Tamil Nadu biodynamic farms for ashwagandha, and Yangtze River Delta cultivation bases for eleutherococcus. Single-source vulnerability concentrates in aqueous extraction processors dependent on volatile alpine harvest quotas. Distribution runs through direct-to-consumer subscription platforms displacing natural remedies retailer gatekeepers, with practitioner-dispensing models gaining fastest in New York and California metro clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection centers on telehealth-integrated nutrition counseling ecosystems where personalized adaptogen blending algorithms create captive customer databases and disintermediate traditional retail gatekeepers.
For Market Incumbents: Pre-empt synthetic cortisol modulator substitution by deepening backward integration into biodynamic-certified cultivation in Karnataka and Tamil Nadu. Secure EFSA novel food authorization for secondary adaptogen species before streamlined opinion queues lengthen. Channel control through practitioner recommendation networks in California and New York metro areas remains the critical defensive lever against direct-to-consumer brand erosion. For New Entrants and Emerging Players: Establish a beachhead in Brazilian ANVISA registration pathways for standardized eleutherococcus formulations before incumbent filing saturation. The confectionery format white space attracts legacy candy manufacturers with wellness portfolio gaps. Go-to-market traction runs through telehealth-integrated subscription models rather than retail shelf placement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer wellness brands with personalized blending algorithm infrastructure. Long-term viability over the next decade favors acquisition targets with dual FSSAI-CDSCO compliance navigation and captive biodynamic farming certifications. The signal to watch is FDA NDI notification timeline compression for novel adaptogen species as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Distributed ledger verification enables premium pricing for mountain-harvested botanical provenance claims in German retail channels. |
| Supercritical CO2 Capacity Expansion | Mid-scale processors in Xi'an biotech clusters achieve real-time withanolide standardization that aqueous methods cannot replicate. |
| EFSA Novel Food Authorization | Streamlined scientific guidance reduces safety assessment duration for Commission E monograph species in Dutch and Belgian markets. |
| Direct-to-Consumer Subscription Launch | Telehealth-integrated nutrition counseling builds captive databases bypassing natural remedies retailer gatekeepers in coastal U.S. clusters. |
| Biodynamic Certification Investment | Third-party farming standards command preferential shelf placement in European natural product channels over conventional processors. |
Research Methodology
Operator-level perspectives from extraction facility managers, EFSA regulatory consultants, sports nutrition practitioners, and direct-to-consumer brand founders anchored the qualitative base. Primary interviews combined with secondary validation against FDA warning letters, EFSA novel food opinion databases, NMPA botanical drug registration filings, and FSSAI export compliance records. Bottom-up volume modeling triangulated against top-down expenditure analysis across the analysis window.
Scenario-bracketing framed projections across regulatory approval velocity, raw material harvest quota volatility, and substitution technology penetration dimensions. Segmentation modeling tracked product type, application physiology target, end-user compliance burden intensity, and distribution channel disintermediation patterns. CAGRs derived from normalized historical trajectory analysis adjusted for NDI notification timeline compression and supercritical CO2 adoption curves.
Stress conditions across Russian alpine harvest quota restrictions, FDA NDI review backlogs, and synthetic cortisol modulator reimbursement expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EFSA opinion automation timelines and NMPA registration streamlining persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Personalized Nutrition and Supplements Market