
 Food Supplement OEM and ODM Market | 2026-2036
Food Supplement OEM and ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Food Supplement OEM and ODM Market Insights
Asset-light contract manufacturing is tilting competitive dynamics toward firms that can fund capacity without heavy balance sheets. Cosmax leverages its integrated R&D and production campuses in South Korea to attract global brand clients. Kolmar Korea anchors its position through decades of formulation expertise in beauty and nutrition convergence. Nutricare Co., Ltd specializes in small-batch, high-mix production that serves emerging direct-to-consumer labels.
Food Supplement OEM and ODM encompasses third-party manufacturing of dietary supplements where OEMs produce client-branded formulas and ODMs develop proprietary formulations for private-label sale, with production governed by cGMP, ISO 22000, and HACCP protocols to ensure batch consistency and contaminant control. The primary commercial purpose is enabling brand owners to commercialize products without owning manufacturing infrastructure or regulatory filing capabilities. Vitamins and protein powders occupy the largest volume pools due to repeat-purchase consumer behavior and established supply chains for bulk actives. Herbal extracts represent the fastest-expanding category as adaptogen and botanical demand spreads from Asia-Pacific into North American and European markets. Sachet packaging is gaining share among travel-format and subscription-box brands seeking differentiation at lower per-unit entry points.
FDA cGMP enforcement and EFSA health claim substantiation requirements shape product development timelines and limit which formulations reach market. China's SAMR registration pathway for imported supplements creates a dual-track system where domestic OEM partners often handle regulatory navigation for foreign brands. Stakeholders must monitor evolving novel food ingredient classifications across jurisdictions, as reclassification risk can strand inventory or invalidate existing label claims without warning.
Market Dynamics
Contract manufacturing economics now favor asset-light brand owners who externalize cGMP compliance costs while Korean and Chinese production clusters absorb capacity expansion risk.
Growth Catalysts
- Sports nutrition outsourcing:Direct-to-consumer fitness brands in North America and Europe now commission turnkey protein and pre-workout manufacturing to compress launch timelines without building in-house facilities.
- FDA cGMP enforcement:Stricter facility inspection protocols since 2022 have pushed mid-tier supplement brands toward established OEM partners with proven quality systems rather than self-manufacturing.
- Adaptogen demand migration:Botanical ingredient pull from North American functional food startups is accelerating sachet-format production runs for ashwagandha and rhodiola complexes.
Market Restraints
- Active ingredient concentration:Bulk vitamin and mineral premix supply concentrates among three Chinese chemical conglomerates, creating input price volatility during logistics disruptions.
- SAMR registration friction:China's dual-track import system forces foreign brands to partner with domestic OEMs for blue-hat certification, adding 18-24 month market entry delays.
- Plant protein functionality gaps:Pea and rice protein isolates still exhibit solubility and taste limitations versus whey, constraining premium positioning in ready-to-drink applications.
Strategic Opportunities
- Southeast Asia contract penetration:Vietnam and Indonesia's emerging middle-class supplement consumption remains underserved by local cGMP-capable manufacturers, opening white space for Korean OEMs to establish satellite facilities.
- Beauty-nutrition convergence:Collagen peptide and ceramide formulations for ingestible skincare represent a cross-category expansion path for traditional cosmetic ODMs entering supplement manufacturing.
- Subscription-box channel optimization:Direct-to-consumer brands now demand 30-day sachet assortments with variable SKUs per shipment, rewarding OEMs with flexible small-batch production lines.
Industry Challenges
- Formulation chemist scarcity:Experienced professionals capable of stability-testing novel botanical combinations command premium salaries in South Korea's competitive labor market.
- Legacy equipment retrofit costs:Converting tablet press lines for clean-label gummy production requires seven-figure capital outlays that strain mid-size contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Supplement OEM and ODM Market |
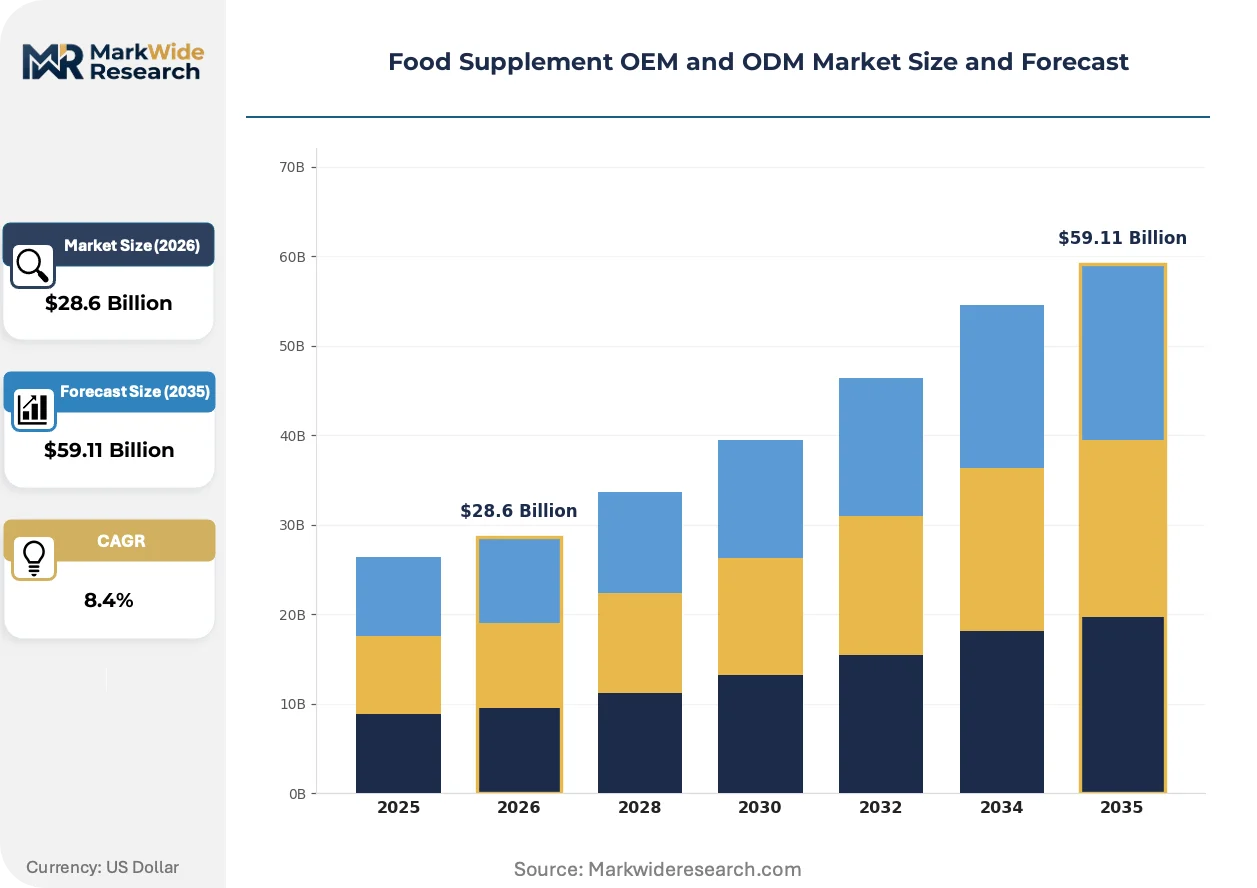
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Protein Powders End User: Health Enthusiasts, Athletes, Elderly, Children Packaging Type: Bottles, Sachets, Blisters, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Health Sources Nutrition, API Co., Ltd., Cosmax, Nutricare Co., Ltd, Syngen Biotech, Kolmar Korea, Goerlich Pharma GmbH, NOVAREX Co., Ltd, Japan Supplement Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Supplement OEM and ODM Market Trends and Innovations
Production technology and regulatory positioning now separate scalable OEM platforms from stranded capacity as brand owners demand faster formulation iteration and multi-jurisdiction compliance.
Continuous manufacturing equipment is migrating from pharmaceutical applications into high-volume supplement OEM facilities. Korean contract manufacturers now adopt powder-blending and direct-compression systems that cut batch cycle times from eight hours to ninety minutes. This compression of production economics enables same-week turnaround on repeat orders for fast-moving sports nutrition SKUs.
EFSA health claim substantiation requirements now demand randomized controlled trial data for botanical immunity positioning. European brand owners reformulate away from implied disease-prevention language toward structure-function claims backed by systematic reviews. The herbal extracts segment bears the highest compliance burden as legacy ashwagandha and elderberry SKUs face label revision.
Direct procurement from OEMs is displacing traditional distributor intermediaries for mid-size supplement brands. North American e-commerce-native companies now negotiate master service agreements directly with Korean and Chinese contract manufacturers, collapsing margin layers. This channel compression concentrates volume among OEMs with English-language regulatory affairs teams and US-based warehousing partnerships.
Food Supplement OEM and ODM Market Segmentation
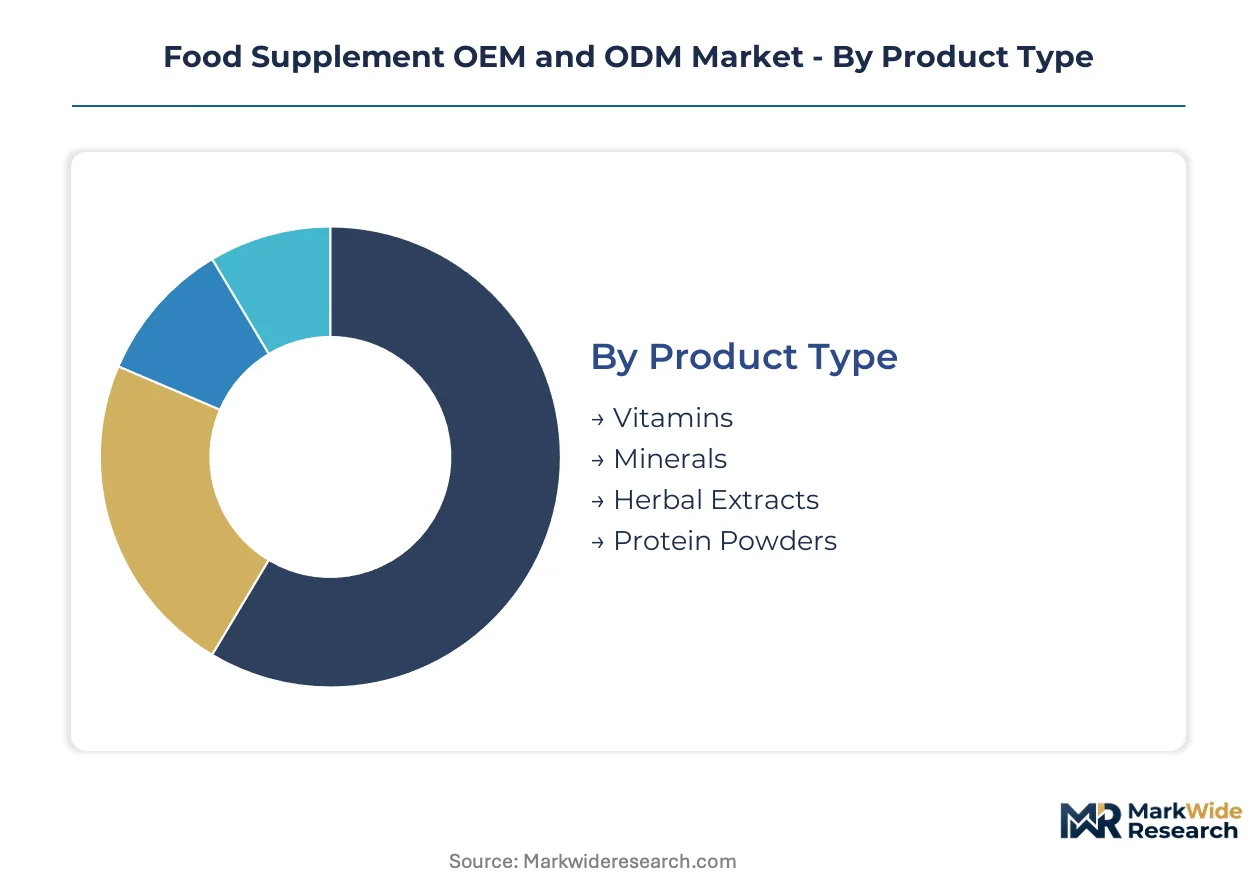
Segmentation in food supplement OEM and ODM manufacturing reveals how contract manufacturers align production capabilities with distinct formulation complexities, regulatory pathways, and packaging automation requirements. Each dimension shapes capital deployment decisions and margin structures differently.
Product Type:
Mature categories dominate volume throughput while emerging botanical formats command premium positioning and faster share expansion.
- Vitamins:Standardized premix formulations with established USP monograph testing protocols. Demand concentrates among mass-market private-label brands in the United States seeking turnkey tablet and capsule production with validated dissolution profiles.
- Herbal Extracts:Standardized botanical concentrates requiring HPLC fingerprinting for marker compound verification. Pull from North American functional food startups accelerates sachet-format production runs for ashwagandha and rhodiola complexes, though EFSA health claim substantiation creates regulatory friction.
- Minerals:Chelated and inorganic salt forms with documented bioavailability studies.
- Protein Powders:Whey isolate, concentrate, and plant-based alternatives with flavor masking challenges.
Vitamins handle the majority of throughput; herbal extracts is the fastest mover on share.
End User:
Application intensity varies sharply across user groups, with performance-oriented segments demanding specialized delivery formats and clinical substantiation.
- Athletes:NSF Certified for Sport and Informed Sport verification requirements dominate procurement criteria. Pre-workout powders and recovery formulations concentrate demand among North American direct-to-consumer fitness brands outsourcing to Korean OEMs with dedicated sports nutrition production suites.
- Elderly:Swallowability-optimized formats including chewable tablets and liquid concentrates. Japan's aging demographic drives sustained contract volume for MFDS-registered Korean manufacturers with geriatric formulation expertise.
- Health Enthusiasts:General wellness positioning with broad demographic targeting.
- Children:Gummy and liquid formats with strict heavy metal and contaminant thresholds.
Athletes commands the highest per-unit margins; elderly exhibits the steadiest contract renewal rates.
Packaging Type:
Format selection directly determines line changeover frequency, inventory carrying costs, and brand differentiation potential in crowded retail environments.
- Sachets:Single-serve powder and liquid stick packs with high-speed form-fill-seal automation. Subscription-box brands in North America now demand 30-day assortments with variable SKUs per shipment, rewarding OEMs with flexible small-batch production lines.
- Bottles:HDPE and PET containers with desiccant integration for moisture-sensitive actives. Established brands in Germany and France maintain volume concentration here due to pharmacy channel packaging conventions.
- Blisters:Cold-form and thermoformed cavities with child-resistant features.
- Bulk Containers:Multi-kilogram canisters for club and B2B channels.
Bottles handles the majority of throughput; sachets is expanding most quickly on format share.
Distribution Channel:
Channel mix is reshaping how contract manufacturers configure regulatory affairs capabilities and geographic warehousing partnerships.
- Online Retail:Direct-to-consumer fulfillment with lot-level traceability and Amazon-compliant labeling. North American e-commerce-native companies now negotiate master service agreements directly with Korean and Chinese contract manufacturers, collapsing traditional distributor margin layers.
- Pharmacies:Professional recommendation-dependent sales with pharmacy-specific SKU requirements. Germany's pharmacy channel maintains strict documentation standards that favor OEMs with ISO 13485 medical device quality systems.
- Supermarkets:Mass-market placement with high-volume, low-SKU-count production economics.
- Specialty Stores:Curated assortments with premium positioning and educated staff.
Supermarkets moves the highest absolute volume; online retail is climbing the fastest on channel share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's tax incentives for functional food R&D clusters have redirected contract manufacturing investment toward Seoul's satellite production zones. National regulators in key manufacturing hubs now tie facility licensing to demonstrated export capacity.
South Korea
Domestic brands seeking turnkey formulation partners drive contract volume through Seoul Capital Area facilities. MFDS registration requirements for functional health claims push foreign brands toward established OEMs with in-house regulatory affairs teams. Songdo's biotech corridor hosts integrated R&D and production campuses serving North American direct-to-consumer labels.
China
Domestic supplement consumption concentrates demand for cGMP-capable manufacturers in Yangtze River Delta cities. SAMR's blue-hat certification pathway for imported products forces 18-24 month market entry timelines that favor local OEM partners. Suzhou and Hangzhou production clusters absorb capacity expansion for both export and domestic brand clients.
United States
Direct-to-consumer fitness brands commission turnkey protein manufacturing to compress launch timelines without in-house facilities. FDA cGMP enforcement since 2022 redirects mid-tier brands toward contract partners with proven quality systems. Utah's supplement manufacturing corridor maintains concentration of NSF Certified for Sport production lines.
Germany
Pharmacy channel packaging conventions sustain demand for HDPE bottle formats with desiccant integration. EFSA health claim substantiation requirements reshape formulation away from implied disease-prevention language. Bavaria's contract manufacturing base specializes in ISO 13485 medical device quality systems for professional recommendation-dependent sales.
Japan
Aging demographic sustains contract volume for swallowability-optimized formats including chewable tablets. MFDS-registered Korean manufacturers with geriatric formulation expertise capture cross-border production agreements. Osaka-Kobe production zone concentrates beauty-nutrition convergence manufacturing for collagen peptide formulations.
Food Supplement OEM and ODM Market Competitive Landscape
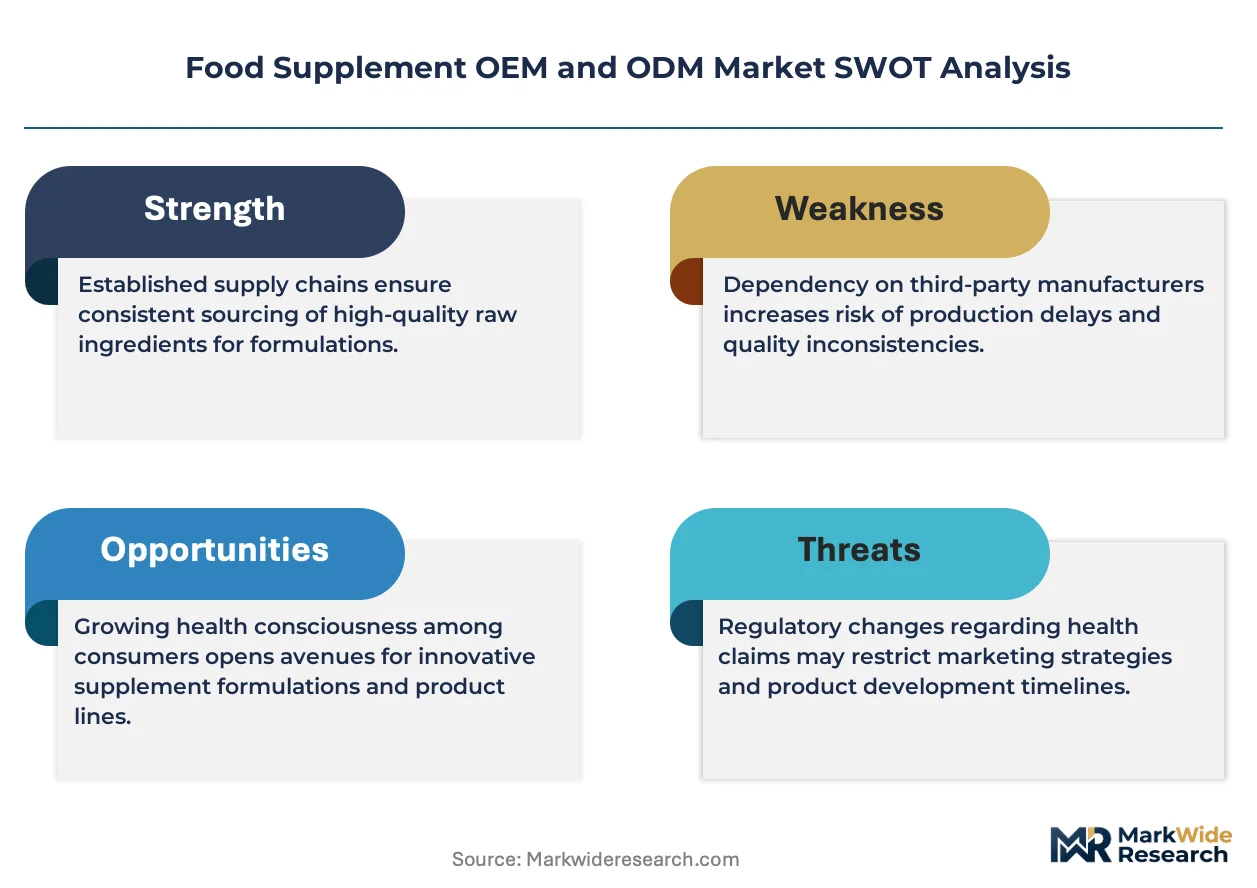
On the supply side, the industry is consolidating around integrated R&D-production platforms that absorb regulatory filing burdens for brand clients. Tiered competitive positioning separates asset-light specialists from vertically integrated conglomerates with captive raw material sourcing. Three archetypes dominate: Korean full-service platforms with regulatory navigation capabilities, German precision manufacturers serving pharmacy channels, and Chinese scale operators with domestic registration expertise. Competitive moves concentrate on geographic satellite facility establishment and beauty-nutrition convergence portfolio expansion.
Among Korea-based integrated platforms, Cosmax and Kolmar Korea exemplify the full-service archetype that combines formulation development with multi-jurisdiction compliance infrastructure. Nutricare Co., Ltd occupies a specialist position within the small-batch, high-mix production tier serving emerging direct-to-consumer labels. Goerlich Pharma GmbH represents the precision manufacturing anchor for European pharmacy channel requirements. These three company structures illustrate how geographic origin and organizational suffix signal strategic positioning without requiring operational specificity.
| Leading Market Players |
|---|
| Health Sources Nutrition |
| API Co., Ltd. |
| Cosmax |
| Nutricare Co., Ltd |
| Syngen Biotech |
| Kolmar Korea |
| Goerlich Pharma GmbH |
| NOVAREX Co., Ltd |
| Japan Supplement Foods |
| Others |
Pricing and Supply Chain Analysis
Underutilized capacity in China's Yangtze River Delta contract manufacturing corridor is pressuring Korean OEMs to absorb cGMP compliance costs rather than pass them through, compressing margins for mid-tier producers while concentrating pricing power among integrated platforms with captive R&D campuses.
Pricing Analysis
Certification level creates the primary spread between contract manufacturing tiers, with FDA-registered facilities commanding 15-25% premiums over ISO-only competitors for sports nutrition SKUs. Pricing stratifies across premium, standard, and economy tiers based on batch size flexibility and regulatory navigation bundling. Cost compression in standard-tier tablet production is intensifying because Chinese conglomerates are absorbing cGMP upgrade investments to secure anchor brand contracts. Direct-to-consumer startups exhibit highest price sensitivity, while pharmacy-channel brands in Germany prioritize quality systems over unit economics.
Supply Chain Analysis
Extended payment terms from North American direct-to-consumer brands now stretch Korean OEM working capital cycles, forcing supply-chain finance facilities at major production campuses. Bulk vitamin and mineral premix supply concentrates in China, South Korea, and India, with HPLC-grade botanical actives sourcing primarily from Yunnan and Sichuan provinces. Single-source vulnerability in ashwagandha root extract supply creates inventory risk during monsoon logistics disruptions. Distribution runs through direct procurement channels that displace traditional distributor intermediaries for mid-volume supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity in Seoul's production corridor is constraining OEM capacity expansion, creating acquisition premiums for contract manufacturers with captive stability-testing laboratories and multi-jurisdiction regulatory filing capabilities.
For Market Incumbents: Insulate margin position by deepening backward integration into botanical extraction and securing exclusive supply agreements with Yunnan-based ashwagandha cultivators. Acquire satellite facilities in Vietnam or Indonesia before Korean competitors establish regional cGMP beachheads. The priority lever rests on locking in multi-year master service agreements with fast-scaling direct-to-consumer brands before formulation talent scarcity worsens. For New Entrants and Emerging Players: Southeast Asia's cGMP-capable manufacturing base remains thin relative to supplement consumption growth, presenting white-space entry for Korean or Chinese OEMs willing to absorb 18-month facility licensing timelines. Target Vietnam's emerging fitness brand ecosystem with turnkey sports nutrition production suites. Lead with sachet-format flexibility and English-language regulatory affairs support to differentiate from established bottle-focused competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with embedded regulatory navigation services and multi-year brand contracts, suggesting durable cash flow quality in integrated platforms versus commodity tablet manufacturers. Long-term viability favors asset-light specialists with beauty-nutrition convergence capabilities or geriatric formulation expertise. Watch for SAMR registration backlog clearance as an inflection signal for China-exposed contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Beauty-Nutrition Convergence Portfolio Expansion | Collagen peptide and ceramide formulations capture cross-category demand from cosmetic ODMs entering supplement manufacturing. |
| Southeast Asia Satellite Facility Establishment | Vietnam and Indonesia production campuses address cGMP-capable manufacturing gaps for regional supplement consumption growth. |
| Continuous Manufacturing Technology Adoption | Ninety-minute batch cycles from Korean powder-blending systems compress turnaround economics for sports nutrition SKUs. |
| Regulatory Affairs Team Localization | English-language compliance specialists enable direct procurement relationships with North American e-commerce-native brands. |
| Small-Batch Sachet Production Line Investment | Flexible form-fill-seal automation serves subscription-box brands demanding variable 30-day SKU assortments. |
Research Methodology
Initial hypotheses were tested against primary input from contract manufacturing executives, regulatory affairs directors at supplement brands, cGMP facility auditors, and procurement leads at direct-to-consumer fitness companies and refined through secondary validation against FDA inspection databases, MFDS functional health claim registries, SAMR blue-hat certification records, and customs trade data for bulk botanical imports. Bottom-up volume estimates from individual OEM capacity disclosures were triangulated against top-down category spending patterns.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, end-user application, packaging format, and distribution channel, with formulation complexity and regulatory pathway intensity as cross-cutting dimensions. CAGRs were derived from fitted growth curves calibrated to historical capacity utilization and brand outsourcing penetration rates, incorporating EFSA health claim substantiation timelines and SAMR registration friction as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical conglomerates into downstream cGMP manufacturing would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
North America Protein Market