
 Whey Protein Market | 2026-2036
Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Protein Market Analysis
The split between premium isolate grades and commodity concentrate streams is repositioning how manufacturers allocate processing capacity. Glanbia PLC leverages its Irish and US fractionation assets to sustain supply of high-purity isolates for sports nutrition brands. FrieslandCampina dominates European whey ingredient sourcing through its cooperative dairy network, while Saputo anchors North American supply with integrated cheese and whey processing operations.
Whey protein comprises the soluble protein fraction separated during cheese manufacturing, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing intensity; it serves primarily as a functional ingredient in sports nutrition, clinical nutrition, and food fortification applications. Whey Protein Isolate commands the highest margin pool due to its superior protein density and lower lactose content, while Hydrolyzed Whey Protein represents the fastest-growing product type as pre-digested formulations gain traction among consumers with digestive sensitivities. Powder form still occupies the largest volume share, though bar and ready-to-drink formats are capturing incremental growth through convenience-oriented distribution channels.
FDA nutrition labeling requirements and GRAS self-affirmation processes govern US whey protein market access, while EFSA health claim regulations shape how European brands communicate muscle recovery and satiety benefits to consumers. BIS quality standards in India and evolving FSSAI protein content verification protocols are tightening import specifications for whey concentrates entering Asian markets. Stakeholders must monitor how divergent allergen disclosure rules across FDA, EFSA, and national Asian regulators reshape formulation strategies and label architectures.
Market Dynamics
Fractionation capacity allocation between isolate and concentrate grades is the dominant structural force reshaping whey protein manufacturing, as sports nutrition brands outbid commodity food processors for high-purity streams.
Growth Catalysts
- School Nutrition Protein Mandates:USDA school meal fortification requirements in the United States are institutionalizing whey protein as a standard ingredient in child nutrition programs, creating baseline offtake volumes independent of consumer discretionary spending.
- EFSA Health Claim Pathways:The European Food Safety Authority's authorized claims for muscle maintenance and satiety are enabling premium positioning for whey isolate products in European functional foods, justifying formulation investments by brands.
- Membrane Filtration Advances:Ceramic microfiltration systems are improving beta-lactoglobulin separation efficiency, allowing processors to recover higher-value protein fractions from the same milk volume.
Market Restraints
- Cheese-Whey Coupling:Whey supply remains structurally tethered to cheddar and mozzarella production cycles in Wisconsin and California, creating volume mismatches when cheese demand diverges from protein ingredient needs.
- Lactose Intolerance Prevalence:Undiagnosed lactose sensitivity in Asian populations limits addressable market expansion for concentrate grades, forcing reliance on costlier isolate forms for export.
- GRAS Self-Affirmation Burden:FDA notification requirements for novel hydrolyzed peptide fractions impose documentation costs that disproportionately constrain smaller ingredient innovators.
Strategic Opportunities
- Clinical Nutrition Expansion:Hospital and long-term care facilities are adopting whey-based medical foods for sarcopenia management, opening institutional procurement channels with multi-year supply contracts.
- India FSSAI Alignment:Evolving protein content verification protocols under India's Food Safety and Standards Authority are creating first-mover advantages for exporters who pre-certify against tightened specifications.
- Precision Fermentation Convergence:Integration of recombinant protein expression with traditional dairy fractionation is enabling hybrid ingredient portfolios that blend animal-derived and bio-identical whey fractions.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of dairy processing science and sports nutrition formulation expertise remains thinly staffed, lengthening product development timelines for hybrid R&D teams.
- Allergen Label Complexity:Divergent disclosure thresholds across FDA, EFSA, and Health Canada requirements force multi-jurisdictional packaging runs that inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Protein Market |
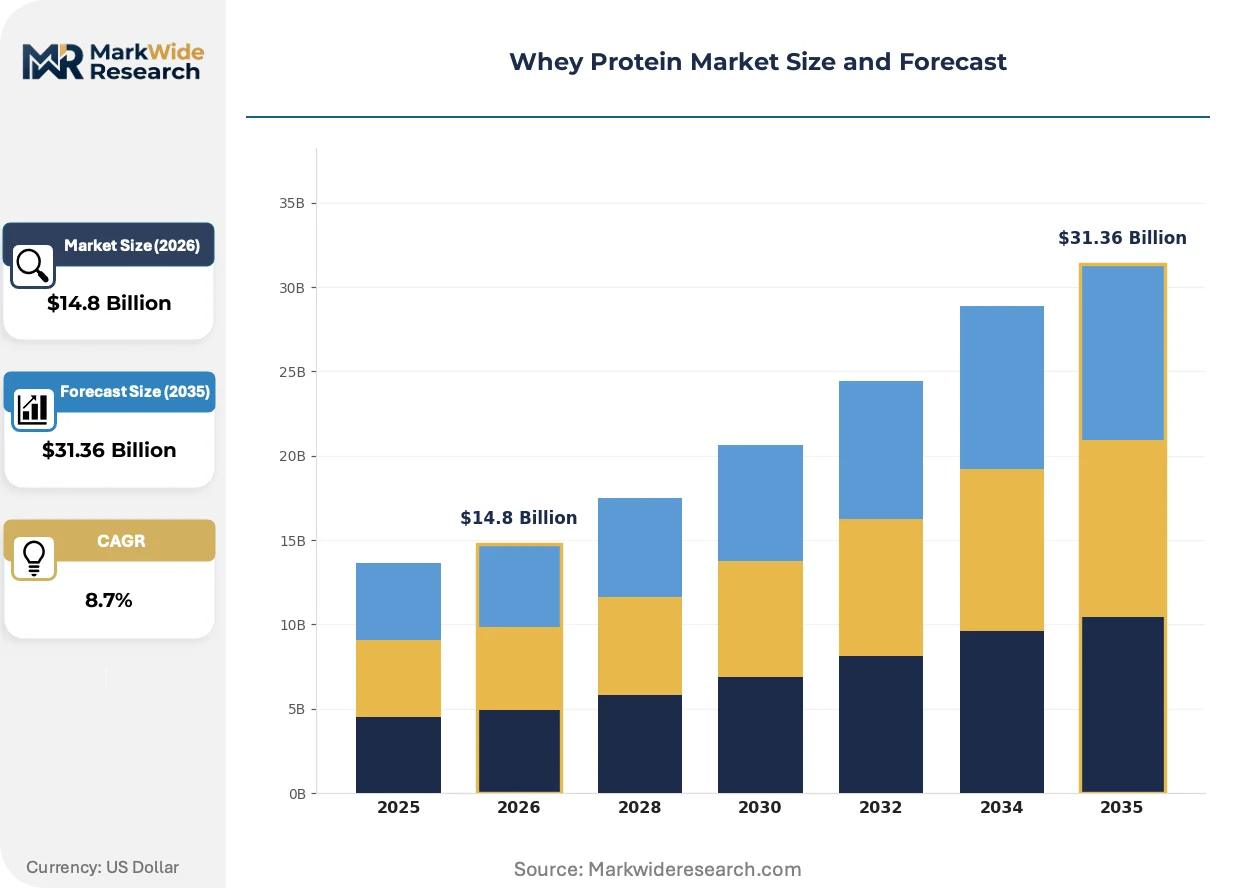
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Undenatured Whey Protein Form: Powder, Liquid, Bars, Supplements End User: Athletes, Bodybuilders, Health-Conscious Consumers, Dieters Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Koninklijke FrieslandCampina N.V., Saputo Inc, Glanbia PLC, Agropur Dairy Cooperative, Milk Specialties Global, Arla Foods AMBA, Hilmar Cheese Company Inc., Leprino Foods Company, Fonterra Co-operative Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Protein Market Emerging Trajectories
Processing automation and regulatory claim substantiation are converging to redefine how whey protein manufacturers compete on purity verification and traceability assurance.
Membrane filtration robotics is automating real-time protein fraction monitoring in Irish and Dutch processing plants, allowing continuous adjustment of cut points between isolate and concentrate streams. Sports nutrition contract manufacturers are adopting these systems fastest, compressing batch-to-batch variability to under 2% protein content deviation. This precision is automating the displacement of manual quality control roles while enabling just-in-time inventory models for brand customers.
EFSA's updated guidance on protein digestibility-corrected amino acid scores is tightening evidentiary standards for muscle recovery claims in European markets. Brands must now submit clinical trial data rather than rely on compositional analysis alone, raising barriers for commodity suppliers. German and French functional food producers are responding by consolidating supplier relationships to those with dedicated clinical research budgets.
Direct-to-brand procurement is bypassing traditional ingredient distributors as vertically integrated sports nutrition companies build captive sourcing teams. This disintermediation concentrates purchasing power with fewer buyers, pressuring mid-tier processors to accept price transparency tools that expose margin structures. The United States exhibits this pattern most acutely, where CrossFit-affiliated nutrition brands and functional beverage startups negotiate isolate contracts directly with Glanbia and Saputo rather than through regional distributors.
Whey Protein Market Segmentation
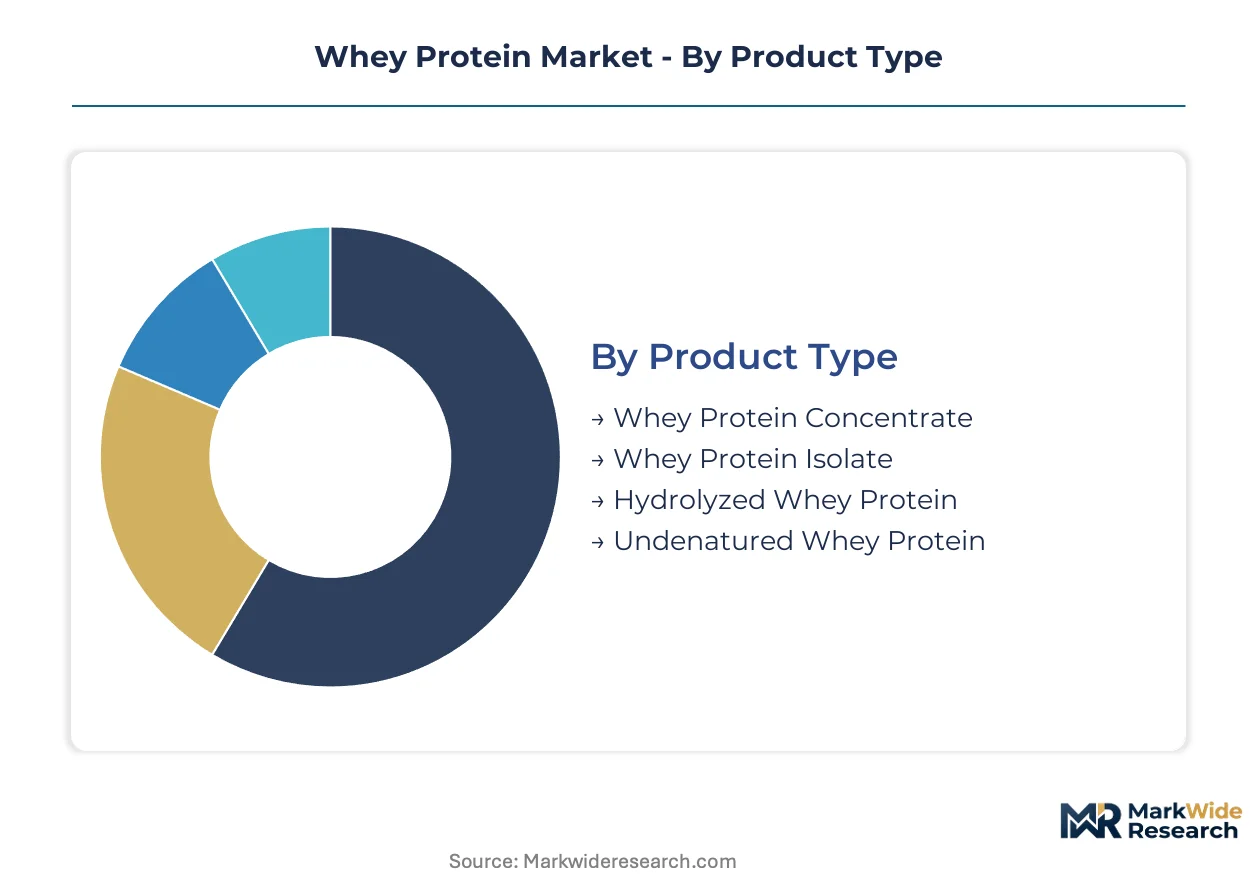
Whey protein manufacturers allocate fractionation capacity across grades that command vastly different margin pools. Segmentation reveals where sports nutrition brands outbid commodity food processors and which distribution channels capture premium pricing.
Product Type:
Volume concentrates in commodity grades while premium isolates extract disproportionate value from sports nutrition formulations.
- Whey Protein Concentrate:Contains 34-80% protein with higher lactose and fat retention. Demand concentrates in US school nutrition programs where USDA fortification mandates institutionalize baseline offtake regardless of consumer discretionary trends.
- Whey Protein Isolate:Achieves 90%+ protein density through additional microfiltration and ion exchange steps. Sports nutrition brands in the United States negotiate direct supply contracts with Irish and North American processors, bypassing traditional distributors to secure purity certifications.
- Hydrolyzed Whey Protein:Pre-digested peptide fractions address digestive sensitivities through enzymatic hydrolysis. Clinical nutrition applications in European hospital systems are climbing the fastest as sarcopenia management protocols expand.
- Undenatured Whey Protein:Cold-processed to preserve immunoglobulins and native protein structures. Premium functional food positioning in German and French markets leverages EFSA muscle maintenance claims.
Today's leader: Whey Protein Concentrate. Tomorrow's challenger: Hydrolyzed Whey Protein.
Form:
Processing intensity and convenience trade-offs reshape how brands configure manufacturing partnerships and shelf placement strategies.
- Powder:Dominates bulk ingredient procurement with established blending infrastructure across contract manufacturers. Volume concentration in US and European sports nutrition supply chains reflects decades of formulation familiarity and cost efficiency at scale.
- Liquid:Ready-to-drink formats demand aseptic filling capabilities and shorter shelf-life logistics. Functional beverage startups in California and New York are gaining share fastest through direct-to-consumer subscription models.
- Bars:Extrusion and coating technologies integrate whey with carbohydrate matrices for meal replacement positioning. Convenience-oriented distribution through gym channels and airport retail commands packaging premiums.
- Supplements:Capsule and tablet formats target clinical nutrition and precise dosing requirements. Hospital procurement specifications favor isolates with documented amino acid profiles.
Powder retains manufacturing dominance. Liquid formats show steepest expansion trajectory through beverage innovation.
End User:
Performance demands versus general wellness positioning split formulation specifications and marketing investment.
- Athletes:Competitive and recreational sports participants drive isolate demand for post-workout recovery windows. NCAA and professional team nutrition programs in the United States specify third-party tested products with banned substance certifications.
- Bodybuilders:High-frequency training protocols require 1.6-2.2g protein per kg bodyweight daily. Contest preparation cycles in North American and European markets prioritize zero-carb isolate grades for macro precision.
- Health-Conscious Consumers:Aging populations and wellness-oriented demographics seek protein fortification without elite performance positioning. European functional food integration leverages EFSA satiety claims for weight management applications.
- Dieters:Calorie-controlled meal replacement programs specify high-protein, low-fat formulations. Clinical obesity management protocols in hospital systems are expanding institutional procurement channels.
Athletes anchor current premium volume. Health-conscious consumers represent the broadest expansion opportunity as aging demographics institutionalize protein supplementation.
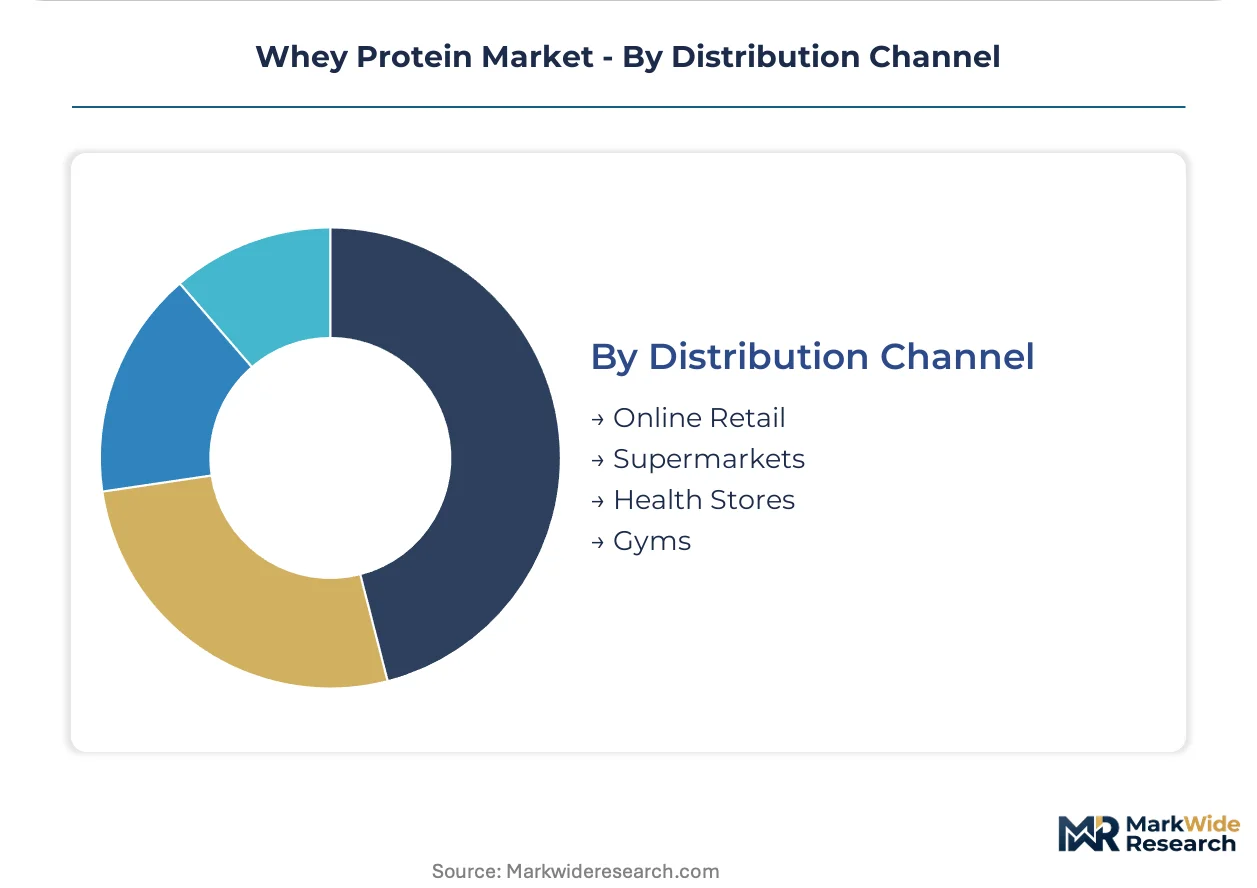
Distribution Channel:
Channel control determines margin capture and consumer data access for repeat purchase engineering.
- Online Retail:Direct-to-consumer platforms enable subscription models and flavor customization. Amazon and specialized sports nutrition sites in the United States concentrate purchasing power with fewer buyers, forcing price transparency on mid-tier processors.
- Supermarkets:Mass-market placement requires formulation compromises on taste and solubility for mainstream palates. European retail consolidation in Germany and France limits shelf access to brands with clinical research budgets.
- Health Stores:Specialty retailers staff trained personnel who influence isolate versus concentrate recommendations. GNC and Vitamin Shoppe locations in US suburban markets capture premium pricing through consultative selling.
- Gyms:Point-of-consumption placement captures impulse purchases during training sessions. CrossFit-affiliated boxes and boutique fitness studios negotiate exclusive brand partnerships for captive member bases.
Online retail commands growth investment. Gym channels defend the highest per-unit margins through contextual relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fractionation chemists and dairy process engineers concentrate in the United States, Ireland, and the Netherlands, anchoring the technical workforce that separates whey protein grades. These talent clusters determine where high-purity isolate production scales fastest and where membrane filtration advances diffuse first.
United States
USDA school nutrition mandates institutionalize whey protein in child feeding programs, creating baseline offtake independent of consumer trends. FDA GRAS self-affirmation requirements govern novel hydrolyzed peptide introductions, favoring established processors with regulatory documentation capacity. Wisconsin and California cheese-whey coupling dominates supply, though volume mismatches emerge when cheddar cycles diverge from protein ingredient demand.
Ireland
Irish processors leverage EFSA muscle maintenance claims to command premium positioning for isolate exports into German and French functional food markets. The country's national dairy regulator enforces clean label specifications that exceed baseline EU requirements, tightening lactose thresholds for concentrate grades. Cork and Limerick processing clusters host ceramic microfiltration installations that automate real-time protein fraction monitoring.
Germany
German functional food producers consolidate supplier relationships around clinical research budgets required by EFSA's tightened protein digestibility-corrected amino acid score standards. The Federal Institute for Risk Assessment oversees allergen disclosure thresholds that diverge from FDA and Health Canada requirements, forcing multi-jurisdictional packaging runs. Bavaria anchors sports nutrition brand headquarters that negotiate direct isolate procurement, bypassing traditional ingredient distributors.
India
FSSAI protein content verification protocols are tightening import specifications for whey concentrates entering Mumbai and Delhi distribution channels. The Bureau of Indian Standards quality standards create first-mover certification advantages for exporters who pre-validate against evolving specifications. Maharashtra and Gujarat dairy cooperatives are investing in fractionation capacity to reduce dependence on imported isolate for domestic sports nutrition formulation.
China
SAMR dairy ingredient import regulations and GB standards for protein fortification reshape how international processors configure export-grade specifications. Undiagnosed lactose sensitivity in inland populations limits addressable market expansion for concentrate grades, forcing reliance on costlier isolate forms. Yangtze River Delta functional beverage startups are climbing fastest through direct-to-consumer subscription models that bypass traditional retail consolidation.
Whey Protein Market Vendor Landscape
Top-tier vendors anchor integrated dairy processing, while mid-tier specialists and regional cooperatives occupy differentiated positions. The vendor base stratifies across three archetypes: multinational nutrition ingredient platforms with clinical research budgets, cooperative dairy networks with captive milk supply, and contract manufacturers serving direct-to-brand procurement channels. Competitive moves concentrate on membrane filtration capacity expansion and strategic partnerships that secure multi-year isolate supply contracts with sports nutrition brands.
Within the multinational platform tier, Glanbia PLC and FrieslandCampina exemplify processors with fractionation assets spanning Irish, Dutch, and North American locations. Saputo Inc anchors North American supply through integrated cheese and whey processing operations. These three occupy positions that enable direct negotiation with CrossFit-affiliated nutrition brands and functional beverage startups, bypassing traditional regional distributors that once intermediated isolate procurement.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina N.V. |
| Saputo Inc |
| Glanbia PLC |
| Agropur Dairy Cooperative |
| Milk Specialties Global |
| Arla Foods AMBA |
| Hilmar Cheese Company Inc. |
| Leprino Foods Company |
| Fonterra Co-operative Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Fractionation chemists and dairy process engineers concentrate in Wisconsin, California, and Ireland, creating labor-cost differentials that widen pricing-tier spreads between commodity concentrate and premium isolate grades. Sports nutrition brands absorb these spreads through direct procurement contracts that bypass traditional distributor markups.
Pricing Analysis
The bundled certification-and-testing service versus unbundled raw ingredient split defines how whey protein pricing stratifies across premium, standard, and economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects protein density certification and third-party banned-substance testing protocols. Price differentiation hinges on EFSA muscle maintenance claim substantiation and FDA GRAS documentation depth. Pricing pressure stems from sports nutrition brands demanding price transparency tools that expose processor margin structures. Health-conscious consumers in European functional food channels show lowest price sensitivity; US school nutrition programs exhibit highest sensitivity due to fixed USDA meal reimbursement rates.
Supply Chain Analysis
Workforce availability constraints in Irish and Dutch membrane filtration clusters limit how quickly ceramic microfiltration capacity scales to meet isolate demand. Supply concentrates in the United States, Ireland, and the Netherlands, with Wisconsin and California cheese-whey coupling anchoring North American volume. Raw material dependencies rest on fluid milk supply from cooperative dairy networks, ceramic membrane filtration equipment, and enzymatic hydrolysis agents. Single-source vulnerability runs through cheddar and mozzarella production cycles that structurally tether whey supply to cheese demand fluctuations. Distribution runs through direct-to-brand procurement channels that disintermediate traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration automation delivers cost-down trajectories that expand margin pools for processors who achieve sub-2% batch-to-batch protein deviation. Premium isolate grades capture disproportionate value as sports nutrition brands prioritize purity certifications over commodity concentrate sourcing.
For Market Incumbents: To counter direct-to-brand procurement disintermediation, anchor customer relationships through captive clinical research budgets that satisfy EFSA tightened protein digestibility-corrected amino acid score standards. Expand ceramic microfiltration capacity in Cork and Limerick processing clusters to automate real-time protein fraction monitoring. Backward integration into cooperative dairy networks secures fluid milk supply commitments that insulate against cheese-whey volume mismatches.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier route for functional beverage startups to bypass retail consolidation and capture recurring revenue. Target clinical nutrition applications in European hospital systems where sarcopenia management protocols expand institutional procurement channels. Leverage precision fermentation convergence to develop hybrid ingredient portfolios that blend animal-derived and bio-identical whey fractions.
For Investors and Strategic Acquirers: Sports nutrition contract manufacturers with automated membrane filtration systems are the most active acquirer category in this space, consolidating mid-tier processors who lack clinical research infrastructure. Five-to-ten year viability favors integrated dairy processors with fractionation assets spanning multiple geographies. Watch for FSSAI protein content verification protocol finalization as the signal indicating which exporters capture first-mover certification advantages in Indian distribution channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Microfiltration Capacity Expansion | Automated real-time protein fraction monitoring in Irish and Dutch plants compresses batch variability below 2% deviation. |
| Clinical Research Budget Investment | EFSA muscle maintenance claim substantiation requires trial data rather than compositional analysis alone. |
| Direct-to-Brand Procurement Channel | CrossFit-affiliated nutrition brands negotiate isolate contracts directly with Glanbia and Saputo. |
| Precision Fermentation Integration | Hybrid ingredient portfolios blend animal-derived and bio-identical whey fractions for differentiated positioning. |
| Cooperative Dairy Network Backward Integration | FrieslandCampina's captive milk supply insulates against cheese-whey volume mismatches. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing executives, sports nutrition brand formulation directors, clinical nutrition procurement managers, and membrane filtration equipment specialists with secondary validation. Secondary sources included FDA GRAS notification databases, EFSA health claim submissions, USDA school meal program procurement records, and BIS quality standard filings. Bottom-up volume modeling across isolate, concentrate, and hydrolyzed grades triangulated against top-down dairy industry production data.
Segment-weighting approaches distributed value and volume across product type, form, end user, and distribution channel dimensions throughout the forecast period. CAGRs derived from protein fortification mandate expansion rates, sports nutrition brand formulation budget trajectories, and clinical nutrition institutional procurement growth patterns. Forecast inputs incorporated membrane filtration automation diffusion curves and precision fermentation technology readiness levels.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation recombinant protein expression would alter the outlook. Forecasts reflect assumptions regarding EFSA claim substantiation timelines, FSSAI protocol finalization, and USDA school nutrition mandate continuity. Material deviation in regulatory trigger implementation or lactose intolerance diagnosis rates in Asian populations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Pregnenolone Supplements Market