
 Europe Collagen Supplements Market | 2026-2036
Europe Collagen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Collagen Supplements Market Foresight
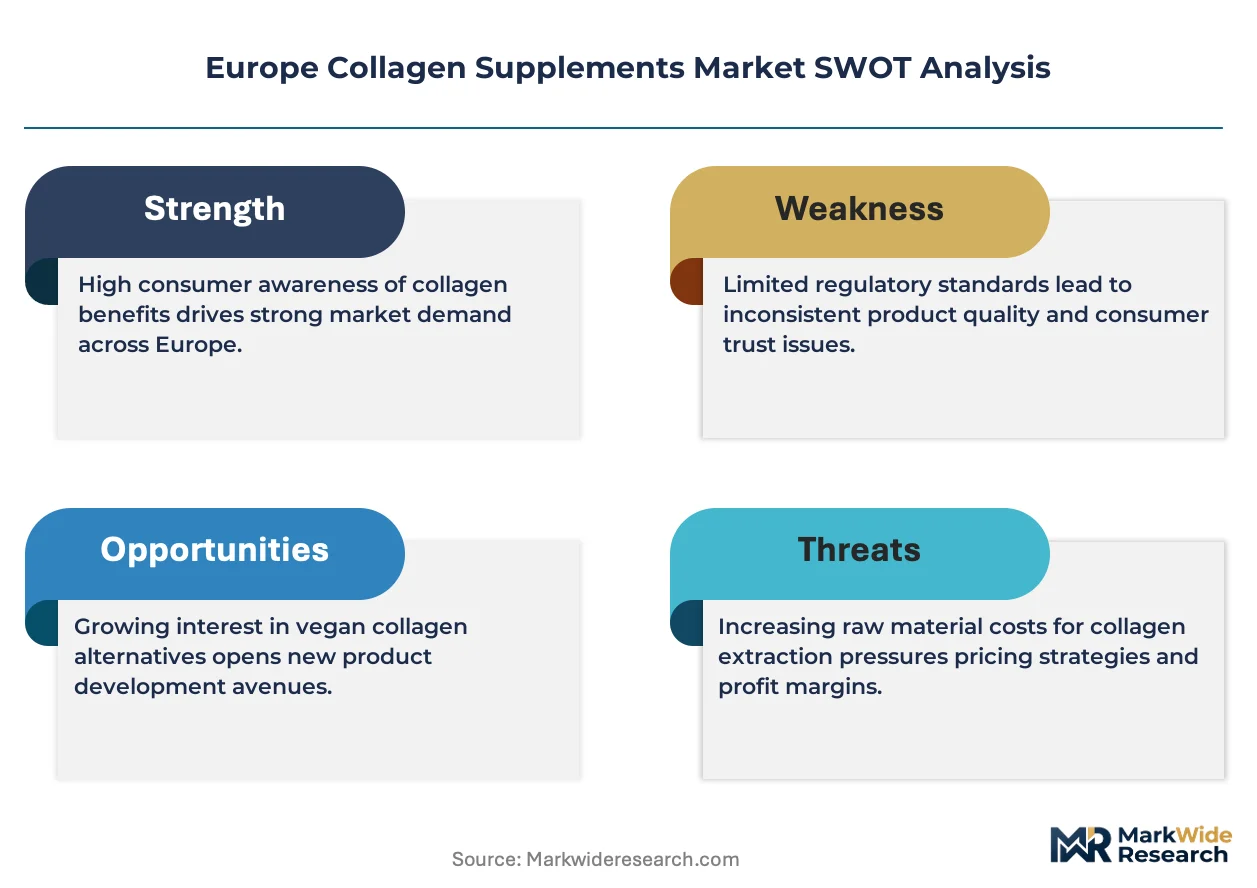
Pharmaceutical-grade collagen certification is unwinding new margin pools for European manufacturers. Gelita AG leverages its century-long gelatin heritage to sustain premium positioning in hydrolyzed collagen supply. Rousselot dominates bovine-sourced peptide production through backward integration into hide processing across France and Belgium. PB Leiner anchors marine collagen extraction with specialized operations in the North Sea coastal zone.
Collagen supplements comprise denatured or partially hydrolyzed collagen proteins, typically extracted from bovine hides, porcine skins, or fish scales through enzymatic hydrolysis yielding peptides with molecular weights below 10 kDa for enhanced bioavailability. These formulations serve commercial purposes spanning joint mobility support, dermal elasticity maintenance, and post-exercise tissue repair. Hydrolyzed collagen occupies the largest volume share due to its neutral organoleptic profile and rapid dissolution in beverages. Liquid collagen emerges as the fastest-growing form segment as convenience-seeking consumers bypass powder-mixing rituals. Gummies capture disproportionate margin attention among beauty-focused demographics willing to pay formulation premiums.
EMA guidelines on novel food ingredient assessments shape market access timelines for emerging collagen sources including genetically modified yeast fermentation. EFSA health claim evaluations under NHCR Article 13 constrain permissible marketing language for joint and skin benefits, forcing reformulation toward substantiated structural claims. The EU Green Deal's circular economy directives are pressuring tannery-waste valorization chains that feed raw material supply. Stakeholders must monitor evolving ECHA classifications for collagen-derived substances under REACH registration renewal cycles.
Market Dynamics
The EU Green Deal's circular economy directives are forcing tannery-waste valorization chains to restructure raw material flows, while EFSA health claim evaluations under NHCR Article 13 constrain permissible marketing language and compress formulation timelines for new entrants.
Growth Catalysts
- Sports nutrition integration:Protein-aware consumers in Germany and France are incorporating hydrolyzed collagen peptides into post-exercise recovery routines, expanding addressable demand beyond traditional beauty and joint health segments.
- EMA novel food pathways:Accelerated assessment frameworks for genetically modified yeast fermentation are shortening market access timelines for alternative collagen sources, diversifying supplier bases beyond animal-derived inputs.
- Pharmacy channel expansion:Germany's pharmacy-led distribution networks are creating concentrated consumption clusters through professional recommendation systems that validate premium positioning.
Market Restraints
- Bovine hide supply concentration:Backward-integrated processors in France and Belgium control critical raw material flows, creating dependency risks for non-integrated formulators.
- EFSA substantiation barriers:NHCR Article 13 evaluations require clinical trial investments that exclude smaller competitors from joint and skin benefit claims, limiting competitive diversity.
- Marine collagen input volatility:North Sea fishery quotas and seasonal catch variations generate price instability for fish scale and skin-derived peptide suppliers.
Strategic Opportunities
- Poland and Romania penetration:Underdeveloped professional sports nutrition infrastructure in Eastern European markets offers first-mover positioning for collagen-integrated recovery products.
- Liquid format convenience:Ready-to-drink collagen beverages bypass powder-mixing rituals, capturing time-constrained urban consumers in Benelux metropolitan corridors.
- CSRD sustainability reporting:Mandatory corporate disclosure requirements are creating procurement preference for tannery-waste valorization chains with verified circular economy credentials.
Industry Challenges
- Peptide characterization expertise:Molecular weight distribution analysis and bioavailability validation require specialized analytical chemistry capabilities that outpace current talent pipelines in European contract research organizations.
- REACH registration renewal complexity:ECHA classification updates for collagen-derived substances are extending compliance timelines and diverting technical resources from product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Collagen Supplements Market |
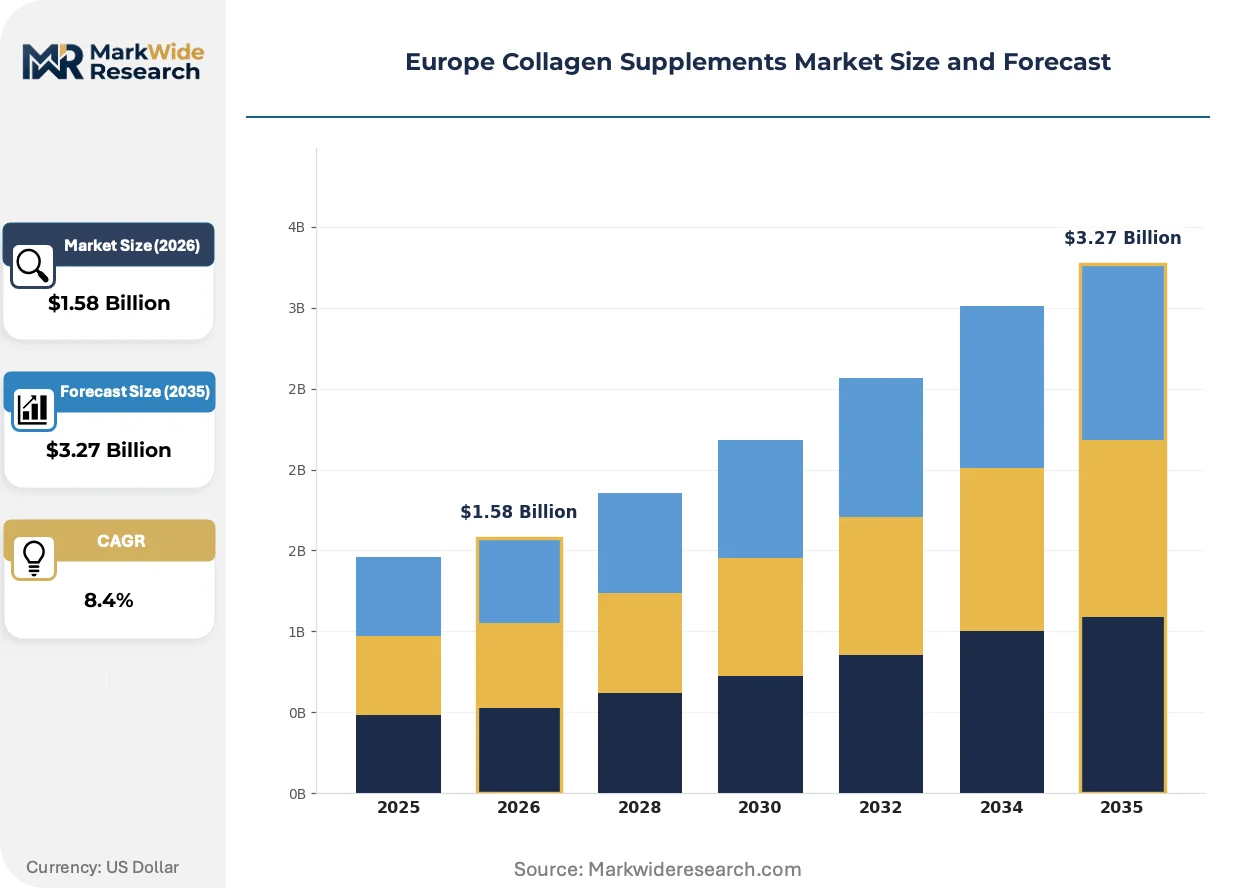
| Market Size in 2026 | $1.58 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Peptides, Gelatin, Liquid Collagen Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets End User: Sports Enthusiasts, Aging Population, Beauty Consumers, Medical Patients Form: Pills, Powder, Liquid, Gummies |
| Companies Covered | Weishardt Group, Nestlé S.A., Gelita AG, Bayer AG, Shiseido Co. Ltd, Rousselot, PB Leiner, Vital Proteins LLC, Nitta Gelatin Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Collagen Supplements Market Shifts & Advancements
Enzymatic processing advances and regulatory disclosure mandates are compressing traditional competitive advantages while opening new formulation and positioning territories for agile manufacturers.
Precision fermentation of recombinant collagen proteins is supplanting conventional animal extraction methods for cosmetic-grade applications. Beauty-focused formulators in France are adopting these inputs to bypass tannery supply constraints. The technology is enabling vegan-positioned product lines that command shelf-space premiums in German drugstore channels.
EFSA's evolving interpretation of NHCR Article 13.5 health claims is constraining joint mobility marketing language while permitting structural protein claims for skin elasticity. Manufacturers are reformulating toward dermal benefit substantiation with clinical endpoint investments. German and Italian brands with existing dermatological study portfolios are capturing displaced positioning from joint-focused competitors.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for powder and liquid collagen formats. Direct-to-consumer platforms in the UK and Netherlands are capturing recurring revenue through personalized dosing protocols. Urban professionals aged 35-50 in metropolitan France and Germany represent the highest conversion cohorts for these auto-ship arrangements.
Europe Collagen Supplements Market Segmentation
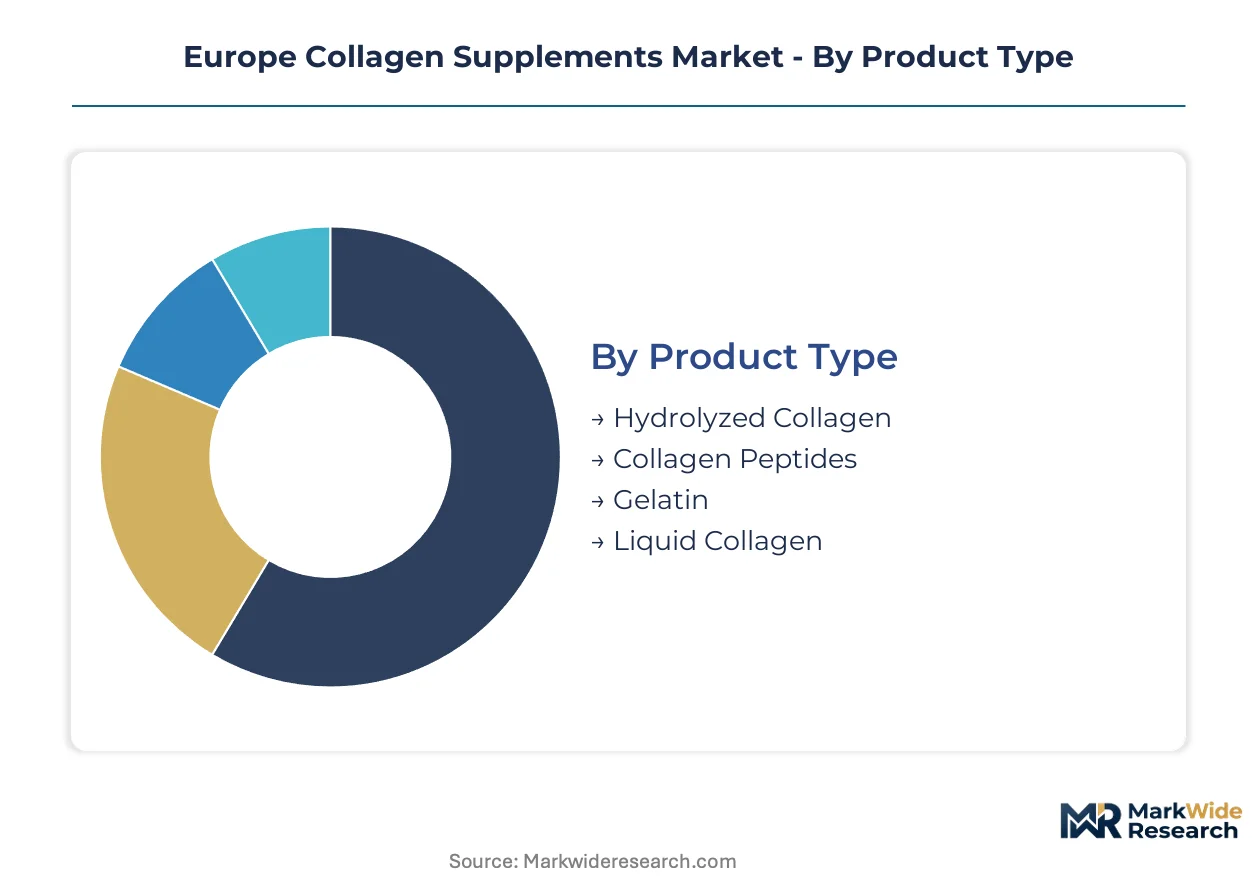
Collagen supplement segmentation in Europe reflects divergent regulatory pathways and channel economics. Product type and form decisions determine EFSA substantiation requirements, while distribution channel selection shapes margin capture and brand positioning across member states.
Product Type:
German and French manufacturers dominate hydrolyzed collagen production for domestic pharmacy distribution, while marine-sourced variants from North Sea operations serve export markets into Benelux and Scandinavia.
- Hydrolyzed Collagen:Enzymatically cleaved peptides below 10 kDa molecular weight deliver neutral taste and rapid dissolution. German pharmacy networks concentrate demand through professional recommendation systems that validate premium pricing for dermal and joint applications.
- Liquid Collagen:Pre-dissolved formulations eliminate powder-mixing rituals for time-constrained urban consumers. Benelux metropolitan corridors show steepest adoption curves as convenience-seeking professionals bypass traditional preparation methods.
- Collagen Peptides:Bioactive di- and tri-peptide fractions command formulation premiums in sports nutrition applications across France and Italy.
- Gelatin:Partially hydrolyzed collagen with gelling properties serves food fortification and encapsulation needs in Central European manufacturing hubs.
Hydrolyzed collagen holds the largest share; momentum sits with liquid formats.
Distribution Channel:
Channel economics stratify across credential intensity, with professional recommendation systems commanding margin premiums versus self-service retail.
- Pharmacies:Germany's Apotheke network validates therapeutic positioning through pharmacist consultation, creating concentrated consumption clusters for joint and skin health formulations. NHCR compliance requirements exclude mass-market competitors from professional channel access.
- Online Retail:Direct-to-consumer platforms in the UK and Netherlands bypass traditional wholesale markups through subscription-based replenishment models. Auto-ship arrangements capture recurring revenue from urban professionals aged 35-50.
- Specialty Stores:Sports nutrition retailers in France and Italy curate peptide formulations for protein-aware recovery segments.
- Supermarkets:Mass-market penetration remains limited by shelf-space competition and price compression in private-label dominated categories.
Pharmacies dominate value capture; online retail is climbing the fastest.
End User:
User segmentation tracks demographic aging curves and lifestyle protein integration patterns across European metropolitan centers.
- Sports Enthusiasts:Protein-aware consumers in Germany and France incorporate hydrolyzed peptides into post-exercise recovery routines, expanding addressable demand beyond traditional therapeutic applications. EFSA health claim constraints favor structural protein positioning over performance marketing.
- Aging Population:Joint mobility and dermal elasticity maintenance drive pharmacy-led purchasing in Germany's concentrated demographic clusters. Clinical substantiation investments create competitive moats against mass-market entrants.
- Beauty Consumers:French and Italian formulators target dermal benefit substantiation with dermatological study portfolios, capturing premium positioning in drugstore and specialty channels.
- Medical Patients:Wound healing and surgical recovery applications require pharmaceutical-grade certification, opening margin pools for GMP-compliant manufacturers.
Aging population holds the largest share; sports enthusiasts are gaining share fastest.
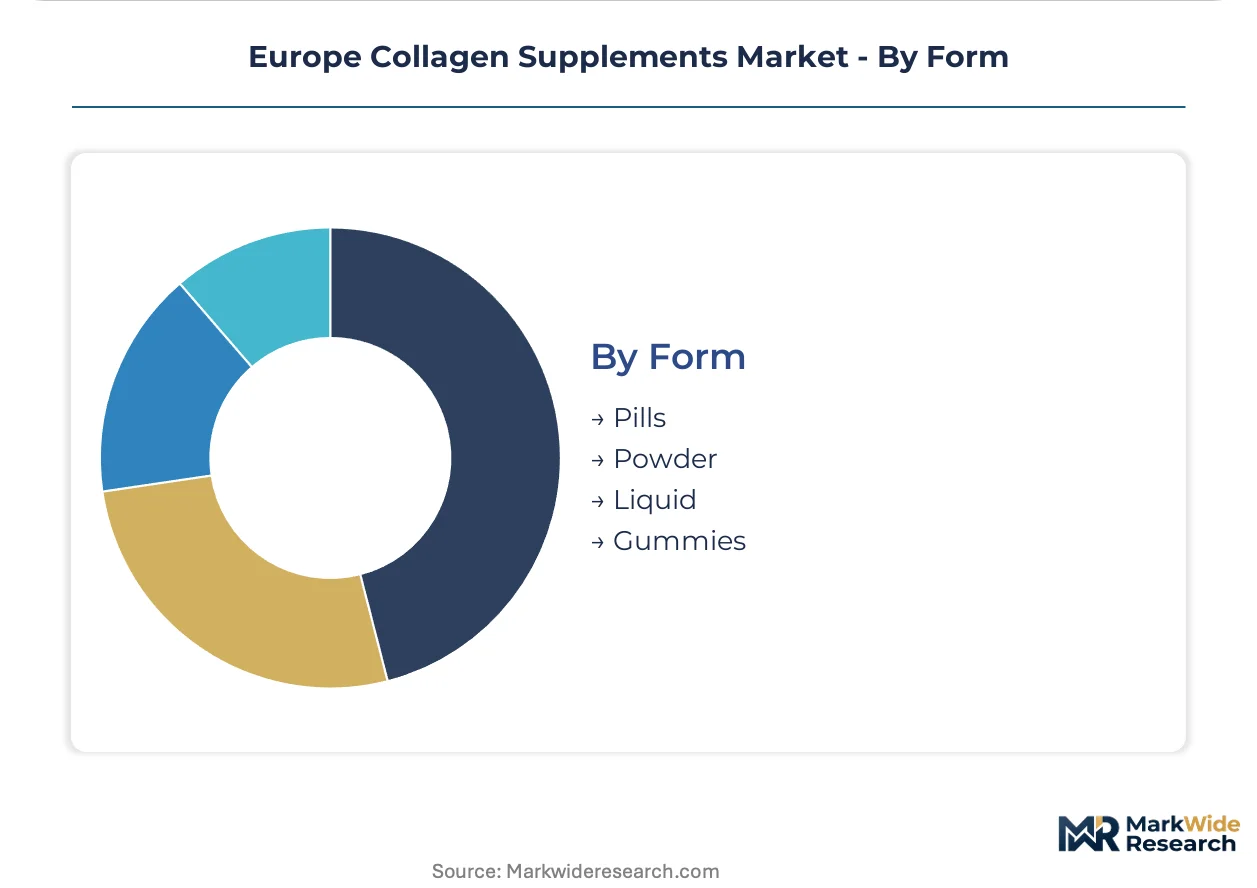
Form:
Format selection determines manufacturing complexity, bioavailability validation requirements, and convenience premiums in urban consumption patterns.
- Powder:Bulk hydrolyzed collagen serves cost-conscious consumers and foodservice integration across Central European markets. Neutral organoleptic profile enables beverage fortification without flavor masking.
- Liquid:Ready-to-drink formulations command shelf-space premiums in German drugstore channels and Benelux convenience retail. Precision dosing and portability drive adoption among metropolitan professionals.
- Gummies:Beauty-focused demographics in France pay formulation premiums for palatable delivery systems, though sugar content constraints limit therapeutic positioning.
- Pills:Encapsulated formats serve medical patient segments requiring precise dosing compliance and travel portability.
Powder holds the largest share; liquid formats show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backward-integrated processors in France and Belgium control critical raw material flows for bovine-sourced peptides, while German pharmacy networks concentrate value capture through professional recommendation systems. Marine extraction operations along the North Sea coastal zone anchor supply diversity for export markets.
Germany
Pharmacy-led distribution through the Apotheke network validates therapeutic positioning for joint and skin health formulations. EFSA health claim evaluations under NHCR Article 13 constrain permissible marketing language, forcing clinical substantiation investments. Berlin and Munich metropolitan corridors show concentrated consumption clusters among aging demographics seeking dermal elasticity maintenance.
France
Beauty-focused formulators target dermal benefit substantiation with dermatological study portfolios, capturing premium positioning in drugstore channels. The country's national pharmaceutical regulator enforces stringent novel food ingredient assessments for emerging collagen sources. Rousselot maintains backward integration into hide processing operations across the northern industrial belt.
United Kingdom
Direct-to-consumer platforms bypass traditional wholesale markups through subscription-based replenishment models for powder and liquid formats. CSRD sustainability reporting mandates create procurement preference for circular economy credentials. London and Manchester urban professionals aged 35-50 represent the highest conversion cohorts for auto-ship arrangements.
Netherlands
Benelux metropolitan corridors show steepest adoption curves for ready-to-drink collagen beverages among convenience-seeking professionals. REACH registration renewal cycles through ECHA extend compliance timelines for collagen-derived substances. Rotterdam and Amsterdam serve as distribution hubs for marine-sourced peptide exports into Scandinavia.
Italy
Sports nutrition retailers curate peptide formulations for protein-aware recovery segments expanding beyond traditional therapeutic applications. EMA guidelines on novel food ingredient assessments shape market access timelines for precision fermentation inputs. Lombardy and Emilia-Romagna manufacturing hubs concentrate encapsulation and liquid formulation capabilities.
Europe Collagen Supplements Market Competitive Landscape
Concentration sits with backward-integrated gelatin heritage processors and specialized marine extraction operators. The vendor base stratifies across three tiers: pharmaceutical-grade certified manufacturers, cosmetic-grade formulators, and mass-market private-label suppliers. Two dominant competitive moves define current positioning: capacity expansion into precision fermentation capabilities and geographic penetration into underdeveloped Eastern European pharmacy channels.
Among heritage-integrated processors, Gelita AG exemplifies the century-long gelatin-to-peptide transition archetype, while Rousselot occupies a position within the bovine-sourced backward integration tier. PB Leiner anchors the marine extraction specialization vector with North Sea coastal operations. These three entities represent distinct supply-side configurations: hide processing integration, fishery-waste valorization, and pharmaceutical-grade certification pathways.
| Leading Market Players |
|---|
| Weishardt Group |
| Nestlé S.A. |
| Gelita AG |
| Bayer AG |
| Shiseido Co. Ltd |
| Rousselot |
| PB Leiner |
| Vital Proteins LLC |
| Nitta Gelatin Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between French hide processors and German pharmacy distributors lock in both bovine collagen supply access and price visibility across multi-year contracting cycles. These arrangements insulate integrated manufacturers from North Sea fishery volatility while anchoring premium tier positioning through guaranteed volume commitments.
Pricing Analysis
EFSA's NHCR Article 13 dictates the pricing tier structure by forcing clinical substantiation investments that separate pharmaceutical-grade certified products from mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and pharmacist recommendation intensity. Cost compression in economy tiers is intensifying because private-label competitors bypass professional channel validation. Sports nutrition buyers in France show highest price sensitivity, while German aging demographics seeking dermal elasticity maintenance demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Inventory buffers for marine collagen inputs stretch to six months due to North Sea seasonal catch variations and fishery quota allocations. Raw material flows concentrate in France, Belgium, and Germany, with hide processing integration feeding bovine peptide production and coastal extraction operations anchoring marine sourcing. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade certification pathways. Distribution runs through pharmacy networks in Germany, direct-to-consumer platforms in the UK and Netherlands, and sports nutrition specialty channels in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe collagen supplements market is emerging from a cyclical trough driven by post-pandemic sports nutrition normalization and EFSA regulatory clarification cycles. Recovery momentum hinges on precision fermentation scale-up and Eastern European pharmacy channel development.
For Market Incumbents: Shield premium positioning by accelerating backward integration into hide processing assets across France and Belgium before REACH registration renewal cycles divert competitor technical resources. Deepen pharmacist recommendation system penetration in Germany's Apotheke network to lock out mass-market entrants lacking NHCR compliance infrastructure. Prioritize GMP certification investments for wound healing applications where pharmaceutical-grade margins resist price erosion. For New Entrants and Emerging Players: Lead with liquid format convenience in Poland and Romania where professional sports nutrition infrastructure remains underdeveloped and pharmacy channel concentration is lower. Capture urban professionals aged 35-50 through subscription-based replenishment models bypassing traditional wholesale markups. Target dermatological study portfolios for dermal elasticity claims where EFSA's evolving NHCR Article 13.5 interpretation has opened positioning space. For Investors and Strategic Acquirers: Marine extraction specialists with North Sea coastal operations and verified circular economy credentials represent the most defensible acquisition archetype as CSRD sustainability reporting mandates reshape procurement preferences. Long-term viability frames around precision fermentation transition timelines and tannery-waste valorization chain consolidation. Watch EMA novel food assessment acceleration for genetically modified yeast fermentation as the signal indicating alternative supply source inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | EMA novel food pathways for yeast-derived collagen diversify supply beyond animal inputs. |
| Pharmacy Channel Expansion | Germany's Apotheke network validates therapeutic positioning through professional recommendation systems. |
| Backward Integration into Hide Processing | French and Belgian tannery-waste valorization secures raw material flows against supply concentration risks. |
| Dermatological Study Portfolio Investment | EFSA's NHCR Article 13.5 evolution favors structural skin claims over joint mobility marketing. |
| Subscription-Based Replenishment Launch | UK and Netherlands direct-to-consumer platforms capture recurring revenue from metropolitan professionals. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with collagen manufacturers, pharmacy procurement managers, sports nutrition formulators, and EFSA regulatory consultants; and secondary validation through REACH registration databases, EMA novel food submission records, and customs trade flows for hydrolyzed collagen peptides. Bottom-up volume modeling triangulated against top-down value projections derived from channel margin structures across Germany, France, and the UK.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product form, distribution channel, end-user archetype, and certification grade tier. CAGRs emerged from growth driver elasticity analysis applied to base year consumption clusters. Industry-specific inputs incorporated EFSA health claim evaluation timelines, North Sea fishery quota trajectories, and pharmacy channel penetration rates by member state.
The analysis sits within stated boundaries; outcomes outside EMA regulatory acceleration or CSRD disclosure mandate timelines would require recalibration. Forecasts reflect assumptions about precision fermentation commercialization pathways and tannery-waste valorization chain stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Global Nutraceuticals Product Market