
 Calcium Supplements Market | 2026-2036
Calcium Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Supplements Market Outlook
The EU Green Deal is restructuring calcium supplement procurement across European pharmacy chains, forcing manufacturers to demonstrate carbon-transparent sourcing and recyclable packaging. Pfizer leverages its pharmaceutical distribution network to sustain shelf presence in regulated channels. Blackmores anchors its position through vertically integrated botanical and mineral supply chains in Australia. Novartis competes via prescription-adjacent positioning that blurs the line between OTC supplements and medical nutrition.
Calcium supplements are mineral-based dietary additives formulated as salts—carbonate, citrate, lactate, or gluconate—typically standardized to elemental calcium content of 200–600 mg per unit, manufactured through precipitation, crystallization, or direct compression into oral dosage forms intended to correct dietary deficiencies and support skeletal homeostasis. Calcium carbonate dominates mass-market volume due to its high elemental calcium density and low production cost, though calcium citrate commands premium positioning among consumers with achlorhydria or proton pump inhibitor dependencies. The gummies form category captures disproportionate growth in pediatric and senior compliance segments where swallowing barriers limit tablet uptake.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity, purity, and composition standards that filter out non-compliant importers, while the EMA's borderline classification debates between foods and medicines create jurisdictional uncertainty for novel delivery formats. India's FSSAI mandates calcium fortification thresholds in packaged foods that indirectly compete with standalone supplement demand. Stakeholders must monitor evolving pharmacovigilance obligations as regulators scrutinize cardiovascular safety signals associated with high-dose calcium regimens.
Market Dynamics
The FDA's Current Good Manufacturing Practice enforcement is compressing the supplier base by disqualifying non-compliant importers, while geriatric population concentration in Japan and Germany pulls demand toward high-absorption formulations. Carbon-transparent sourcing mandates under the EU Green Deal are restructuring procurement investments across European pharmacy chains.
Growth Catalysts
- Aging demographics:Japan's super-aged society and Germany's expanding 65-plus population drive prescription-adjacent calcium positioning in regulated pharmacy channels.
- Regulatory clarity:India's FSSAI fortification mandates in packaged foods create adjacent demand pull for standalone supplement formats.
- Delivery innovation:Gummy formulations capture pediatric and senior segments where tablet swallowing barriers limit compliance.
Market Restraints
- Input cost volatility:Limestone-derived calcium carbonate feedstock faces energy-intensive processing cost swings tied to natural gas pricing.
- Supply concentration risk:Precipitated calcium carbonate production clusters in China's industrial belts, exposing buyers to logistics disruption.
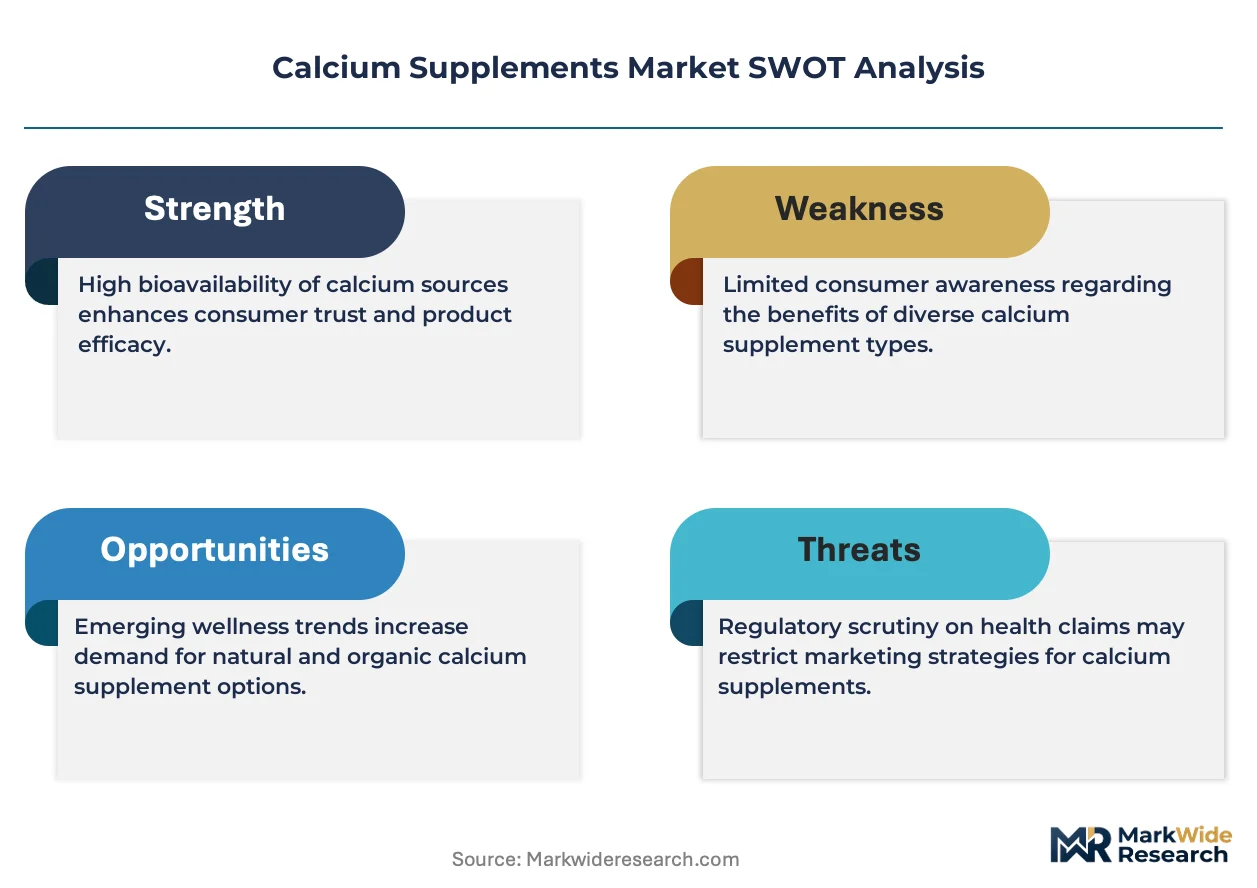
- Cardiovascular safety scrutiny:Pharmacovigilance obligations from the FDA and EMA impose labeling burdens on high-dose regimen marketers.
Strategic Opportunities
- Direct-to-consumer channels:Online retail platforms bypass pharmacy gatekeepers, enabling subscription-based replenishment models.
- Achlorhydria-targeted formulations:Proton pump inhibitor dependencies create premium positioning space for calcium citrate salts.
- Carbon footprint certification:EU Green Deal procurement rules reward manufacturers with verified Scope 3 emissions reductions.
Industry Challenges
- Formulation talent scarcity:Bioavailability optimization requires cross-trained pharmaceutical scientists conversant in both mineral chemistry and gastrointestinal physiology.
- EMA borderline classification:Novel delivery formats face jurisdictional uncertainty between food and medicine frameworks, extending time-to-market.
- Legacy system integration:Track-and-trace compliance for FDA lot-level requirements strains small-batch manufacturers with paper-based quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Supplements Market |
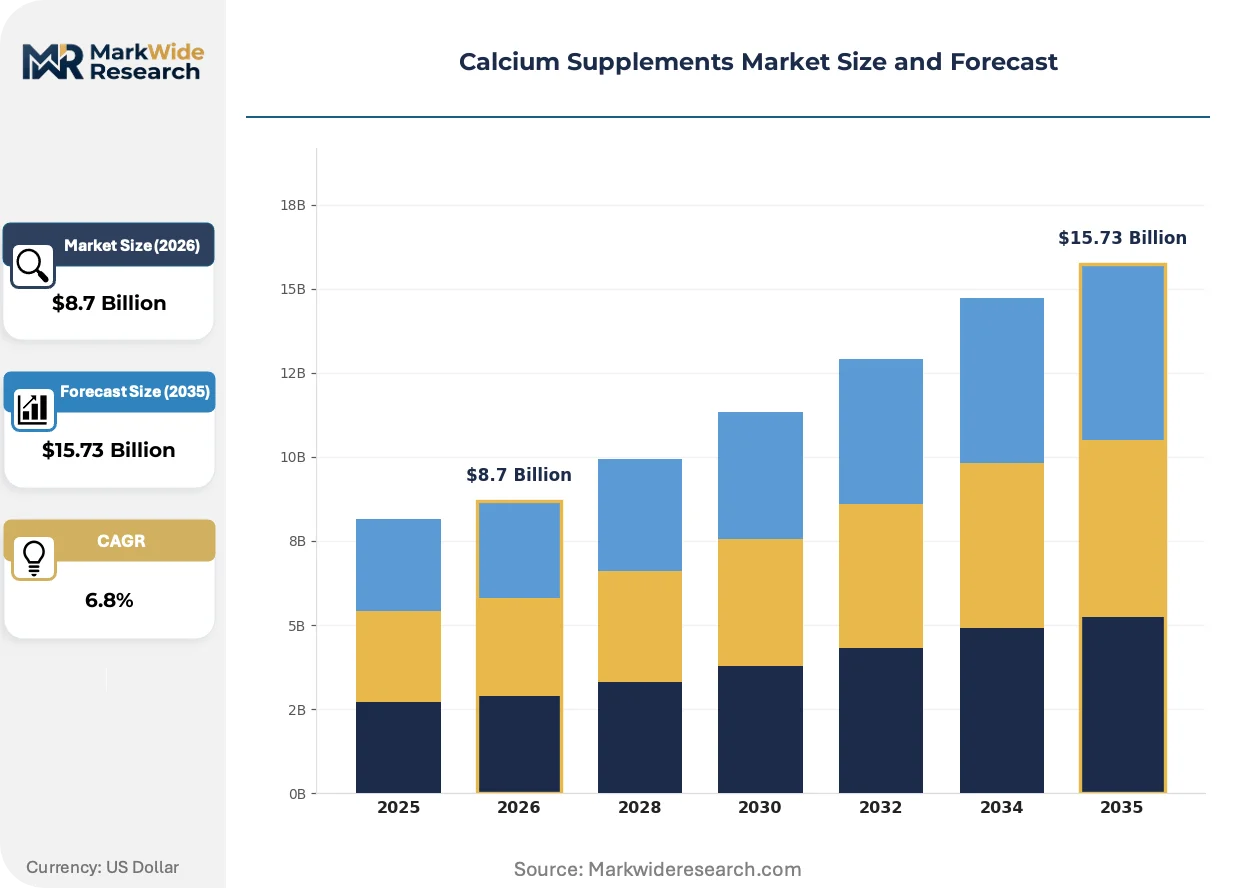
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Citrate, Calcium Carbonate, Calcium Lactate, Calcium Gluconate Distribution Channel: Online Retail, Supermarkets, Health Shops, Pharmacies Form: Tablets, Softgels, Powders, Gummies End User: Adults, Pregnant Women, Children, Seniors |
| Companies Covered | Baxter International, Merck, Pfizer, Swisse, Blackmores, Novartis, Amphastar, Caltrate, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Supplements Market Strategic Shifts
Calcium supplement innovation clusters around absorption efficiency, regulatory compliance automation, and format accessibility. These vectors are compressing traditional tablet dominance while elevating formulation science as a competitive differentiator.
Nano-precipitation calcium carbonate is consolidating quality control by enabling tighter particle-size distribution and dissolution-rate standardization. Contract manufacturers serving European pharmacy chains are adopting these systems to meet EMA stability requirements. The technology is consolidating mid-tier producers into specialized toll-manufacturing relationships with brand holders.
The EU Green Deal's carbon border adjustment mechanism is forcing raw material provenance documentation across European supply chains. German and French pharmacy procurement now requires lifecycle emissions disclosures from limestone suppliers. Calcium citrate producers with certified low-carbon fermentation processes capture shelf-space preference in these markets.
Subscription-based replenishment models are displacing intermittent pharmacy purchasing among chronic-condition consumers. Direct-to-consumer platforms use adherence data to personalize dosage timing and co-nutrient bundling. Japan's METI-approved functional food claims enable cross-selling between supplements and fortified beverages through these digital channels.
Calcium Supplements Market Segmentation
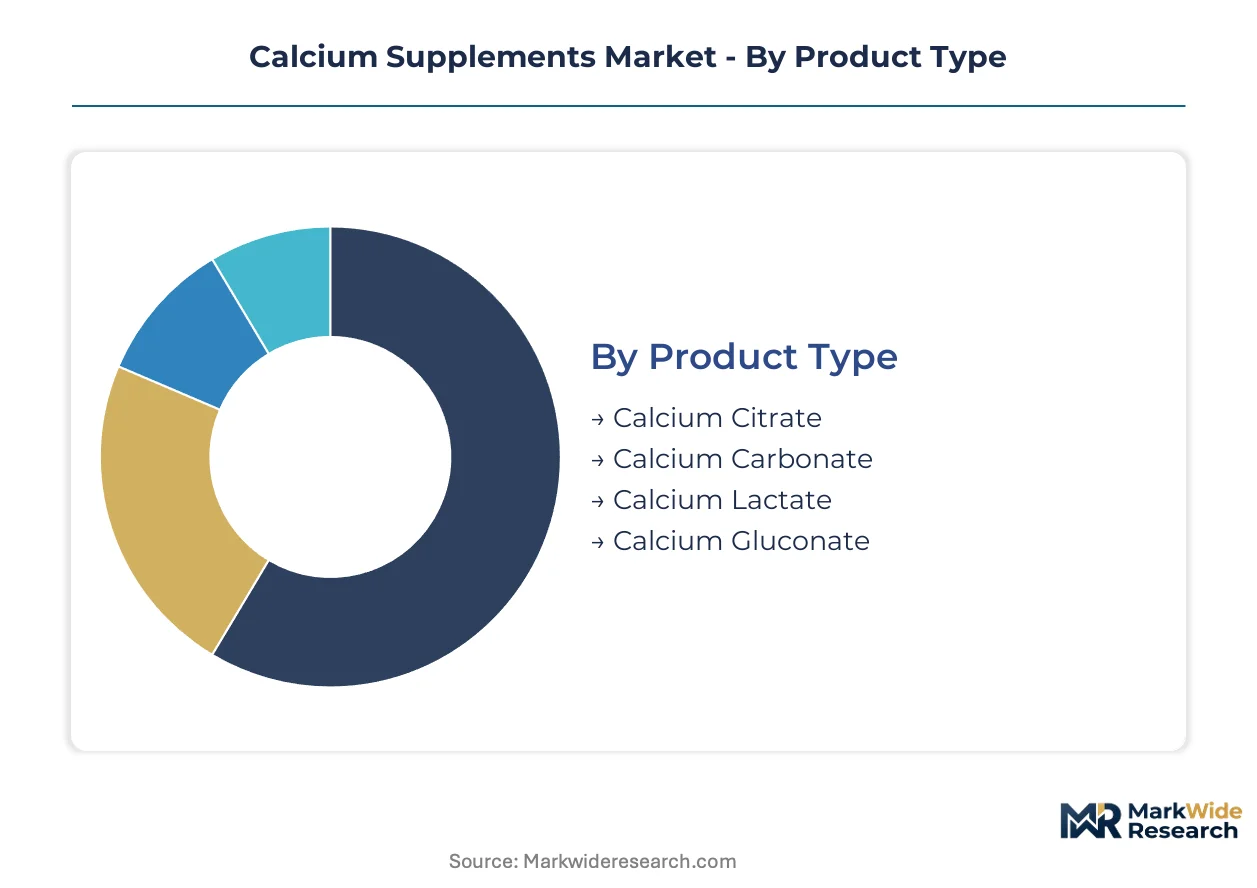
Calcium supplement segmentation reveals distinct capital requirements across mineral chemistry, absorption kinetics, and compliance infrastructure. Manufacturers must align production investments with the specific formulation and channel demands of each segment.
Product Type:
Capital intensity varies sharply across salt chemistries, with precipitation infrastructure and purity certification driving fixed-cost differentiation.
- Calcium Carbonate:High elemental calcium density at 40% by weight enables compact tablet formulations. Limestone-derived feedstock demands energy-intensive calcination; demand concentrates in Germany's pharmacy chains where cost-conscious seniors prioritize value positioning.
- Calcium Citrate:Produced via fermentation of citric acid with calcium hydroxide, yielding superior bioavailability in low-acid gastric environments. Japan's proton pump inhibitor-dependent geriatric population absorbs this segment fastest.
- Calcium Lactate:Dairy-industry byproduct sourcing requires lactose-handling compliance infrastructure.
- Calcium Gluconate:Pharmaceutical-grade crystallization commands cleanroom investment thresholds.
Calcium carbonate absorbs the bulk of installed capacity; calcium citrate is expanding most quickly.
Distribution Channel:
Channel selection determines regulatory compliance burden and working capital intensity, with direct-to-consumer platforms requiring digital infrastructure over physical shelf-space investment.
- Online Retail:Subscription models demand CRM and adherence-tracking software investment. India's FSSAI-labeled products gain traction here through direct-to-consumer platforms bypassing traditional pharmacy gatekeepers.
- Pharmacies:EU Green Deal carbon documentation requirements favor established suppliers with verified Scope 3 data.
- Supermarkets:Mass-market placement requires trade spend and promotional slotting fees.
- Health Shops:Specialist positioning tolerates higher per-unit pricing with educated staff consultation.
Online retail captures the steepest expansion trajectory; pharmacies retain the highest margin stability.
Form:
Manufacturing equipment specialization creates segment-specific capital barriers, with gummy production requiring confectionery-extrusion lines distinct from tablet compression.
- Tablets:Direct compression and wet granulation dominate high-volume output. Germany's regulated pharmacy channels standardize on this format for geriatric compliance programs.
- Gummies:Gelatin or pectin matrices require temperature-controlled molding and coating infrastructure. Pediatric demand in Japan's functional food segment accelerates format adoption.
- Softgels:Rotary die encapsulation limits supplier base to specialized contract manufacturers.
- Powders:Bulk blending equipment serves sports nutrition and institutional channels.
Tablets command the majority of production line investment; gummies are climbing the fastest.
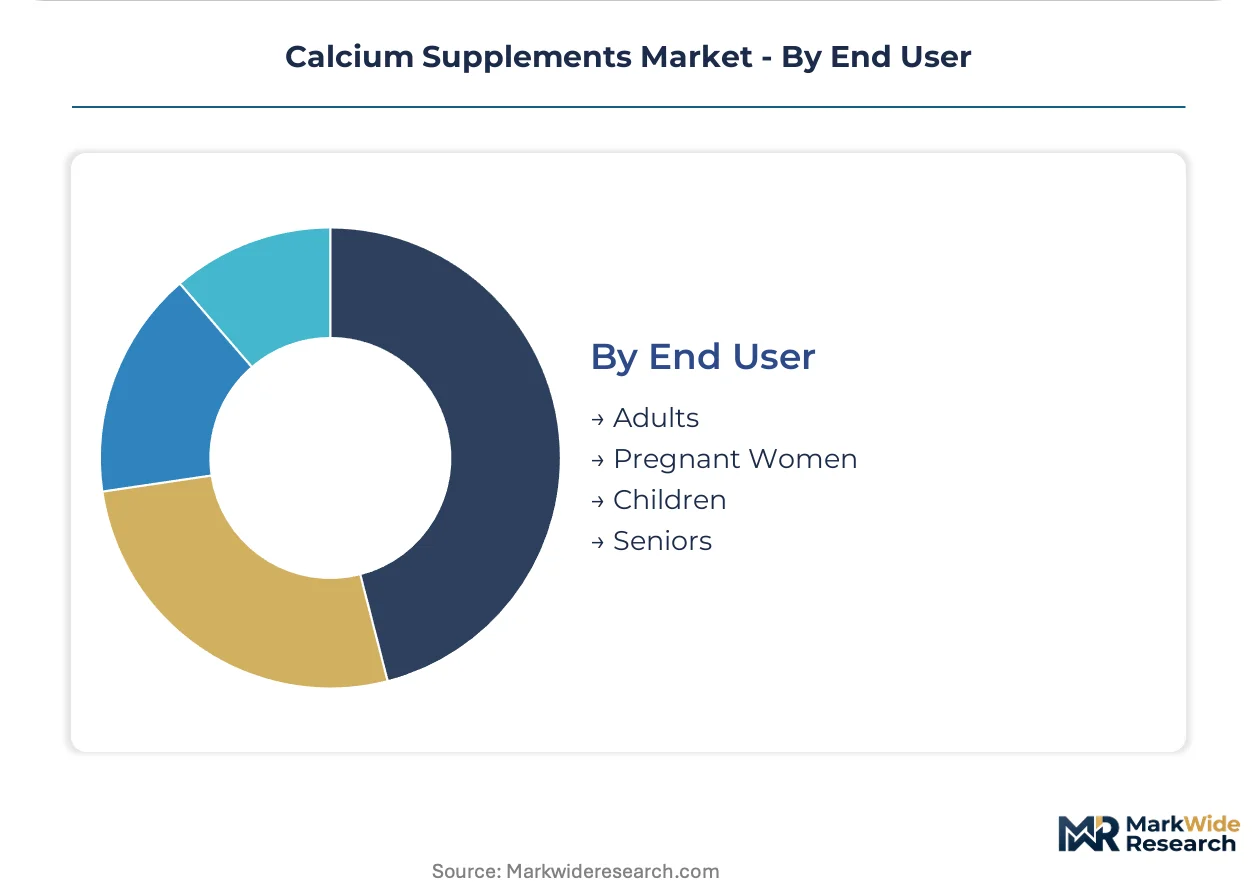
End User:
Formulation R&D intensity concentrates in segments with physiological specificity or compliance barriers, driving divergent clinical substantiation requirements.
- Seniors:High-absorption citrate salts and reduced tablet burden define product development. Japan's super-aged society generates prescription-adjacent positioning in regulated channels.
- Pregnant Women:Prenatal co-formulation with vitamin D and folate requires teratogenicity testing investment.
- Adults:Maintenance dosing drives carbonate volume through cost efficiency.
- Children:Palatability engineering and choking-hazard mitigation shape gummy and liquid development.
Seniors represent the deepest R&D investment concentration; pregnant women show the strongest premium pricing tolerance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's pharmaceutical manufacturing corridor concentrates calcium carbonate precipitation capacity serving Asia-Pacific distribution networks. German limestone processing clusters in the Rhineland feed European pharmacy chains with carbon-certified feedstock. Japanese functional food innovators in Kansai pioneer gummy format development for aging populations.
United States
FDA Current Good Manufacturing Practice enforcement compresses the supplier base by disqualifying non-compliant importers. The agency's dietary supplement identity and purity standards filter out substandard carbonate sources. New Jersey's contract manufacturing corridor consolidates toll-production relationships with brand holders seeking compliance automation.
Germany
Supermarket pharmacy chains demand carbon-transparent sourcing documentation under EU Green Deal procurement rules. The country's national pharmaceutical regulator enforces borderline classification clarity between foods and medicines. Rhineland industrial belts host precipitated calcium carbonate production serving regulated pharmacy channels with verified Scope 3 emissions data.
Japan
Proton pump inhibitor dependencies among the super-aged geriatric population accelerate calcium citrate absorption. METI-approved functional food claims enable cross-selling between supplements and fortified beverages. Kansai region manufacturers pioneer gummy format innovation for senior compliance segments where tablet swallowing barriers limit uptake.
India
FSSAI fortification mandates in packaged foods create adjacent demand pull for standalone supplement formats. The country's national food regulator mandates calcium thresholds in edible oils and milk products. Maharashtra's direct-to-consumer platforms bypass traditional pharmacy gatekeepers with subscription-based replenishment models.
China
Dual carbon goals under MEE supervision reshape limestone-derived feedstock processing economics. The national medical products administration enforces quality consistency standards for mineral salt imports. Shandong Peninsula industrial clusters concentrate precipitation infrastructure exposing buyers to logistics disruption risks from energy-intensive calcination.
Calcium Supplements Market Competitive Environment
The competitive structure tilts toward pharmaceutical-origin players with regulated channel access. Consolidation pressure favors entities possessing vertical control over mineral supply chains and carbon certification infrastructure. Three archetypes dominate: prescription-adjacent pharmaceutical divisions, vertically integrated botanical-mineral specialists, and toll-manufacturing contract operators. Capacity expansion and regulatory compliance automation constitute the dominant competitive moves.
Among pharmaceutical-origin players, Pfizer and Novartis occupy positions bridging OTC supplements and medical nutrition categories. Blackmores anchors the vertically integrated specialist tier with captive supply chain control over botanical and mineral sourcing. Baxter International sits within the hospital-channel vector where parenteral calcium formulations serve acute care settings.
| Leading Market Players |
|---|
| Baxter International |
| Merck |
| Pfizer |
| Swisse |
| Blackmores |
| Novartis |
| Amphastar |
| Caltrate |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Natural gas futures pricing cascades through calcium carbonate calcination economics, compressing margins for limestone-derived feedstock processors while elevating fermentation-based citrate salts toward premium positioning in EU pharmacy procurement.
Pricing Analysis
Elemental calcium density per unit dose anchors value-based pricing, with carbonate salts commanding economy positioning against citrate's premium absorption claims. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and bioavailability testing investment. Cost compression in carbonate segments intensifies as energy-intensive calcination exposes producers to input volatility. Germany's pharmacy chains exhibit highest price sensitivity; Japan's proton pump inhibitor-dependent geriatric population shows lowest sensitivity to citrate premiums.
Supply Chain Analysis
EMA stability certification and FDA Current Good Manufacturing Practice qualification filter supplier eligibility, consolidating toll-manufacturing relationships around compliant contract operators. Precipitated calcium carbonate production clusters in China's Shandong Peninsula, Germany's Rhineland, and India's Maharashtra industrial belts. Limestone feedstock, citric acid fermentation stocks, and pharmaceutical-grade excipients constitute critical input dependencies. Single-source vulnerability concentrates in Chinese precipitation capacity exposed to energy policy disruption. Distribution runs through direct-to-consumer platforms and regulated pharmacy channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into limestone mining and fermentation feedstock production to secure cost transparency and carbon certification documentation.
For Market Incumbents: To counter contract manufacturing commoditization, Pfizer and Novartis should deepen captive supply of pharmaceutical-grade carbonate precipitation capacity in FDA-compliant jurisdictions. Blackmores must secure certified low-carbon fermentation partnerships ahead of EU Green Deal procurement deadlines. Certification investment in Scope 3 emissions tracking is the critical defensive lever. For New Entrants and Emerging Players: Launch via subscription-based direct-to-consumer platforms targeting India's FSSAI-labeled segment, where pharmacy gatekeeper bypass enables rapid scale. White-space concentration sits in pediatric gummy formats for Japan's functional food crossover and achlorhydria-targeted citrate positioning among proton pump inhibitor users. Co-nutrient bundling with vitamin D drives initial adherence capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier carbonate producers with stranded calcination assets in Germany and China facing dual carbon compliance costs. Five-to-ten-year viability hinges on carbon border adjustment mechanism adaptation and fermentation process conversion capability. The signal to watch is EU pharmacy chain delisting of uncertified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Program | EU Green Deal procurement rules now mandate verified Scope 3 emissions disclosures from limestone suppliers. |
| Direct-to-Consumer Launch | Subscription platforms bypass pharmacy gatekeepers in India and capture adherence data for personalization. |
| Backward Integration into Feedstock | Captive limestone mining and citric acid fermentation secure cost transparency and carbon documentation. |
| Gummy Format Capacity Expansion | Confectionery-extrusion infrastructure addresses pediatric and senior compliance barriers in Japan's functional food segment. |
| Regulatory Compliance Automation | FDA lot-level track-and-trace systems filter non-compliant importers and consolidate toll-manufacturing relationships. |
Study Parameters
Independent corroboration across regulatory filings, trade customs data, and pharmaceutical procurement databases underwrites the qualitative findings. Primary interviews with formulation scientists at carbonate precipitation facilities, pharmacy procurement managers in Germany and Japan, FSSAI compliance officers, and direct-to-consumer platform operators combined with secondary validation from FDA warning letters, EMA borderline classification decisions, and EU Green Deal implementation guidance. Bottom-up capacity modeling and top-down consumption estimates triangulate volume figures.
Rate-of-change decomposition across mineral chemistry, distribution channel, dosage form, and end-user physiology dimensions structures the analytical framework. CAGRs derive from segment-level absorption kinetics modeling and regulatory adoption curve analysis. Inputs include geriatric population projections, proton pump inhibitor prescription rates, and carbon certification penetration thresholds across European pharmacy chains.
Limestone feedstock cost volatility, EMA borderline reclassification events, and FDA cardiovascular safety signal enforcement are the dominant revision risks. Forecasts reflect documented assumptions on regulatory stability and energy transition pacing. A model refresh is warranted upon material change in EU carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Milk Thistle Market