
 Sugar Free Candy Market | 2026-2036
Sugar Free Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Candy Market Analytics
Premium clean-label formulation is bifurcating the competitive landscape as manufacturers race to eliminate artificial sweeteners from ingredient decks. The Hershey Company leverages its cocoa procurement networks to sustain consistent supply of chocolate-based sugar-free lines. Mondelez International anchors its position through global manufacturing scale across mint and gum categories. Lily's Sweets competes as a specialist in stevia-sweetened chocolate, occupying the natural-positioned tier with dedicated channel control in health food retail.
Sugar free candy denotes confectionery products formulated with non-nutritive or reduced-calorie sweeteners such as erythritol, steviol glycosides, or sugar alcohols, manufactured through controlled crystallization or enrobing processes that replicate mouthfeel and bulk without sucrose. These products serve diabetic populations, ketogenic diet adherents, and dental-health-conscious consumers seeking indulgence without glycemic impact. Chocolate segments lead value contribution due to higher price points and cocoa butter complexity, while gummies represent the fastest-growing format as gelatin-free and pectin-based alternatives expand. Erythritol-based formulations command margin premiums over sorbitol lines because of superior digestive tolerance and cooling-effect properties that enhance sensory profiles.
FDA nutrition labeling mandates and the EPA's oversight of sugar alcohol manufacturing emissions shape product development thresholds and facility siting decisions for domestic producers. The USDA's oversight of organic certification pathways creates tiered market access for stevia-sourced products bearing clean-label claims. Stakeholders must monitor evolving sweetener GRAS determinations and state-level sugar tax proposals to anticipate reformulation costs and channel restrictions.
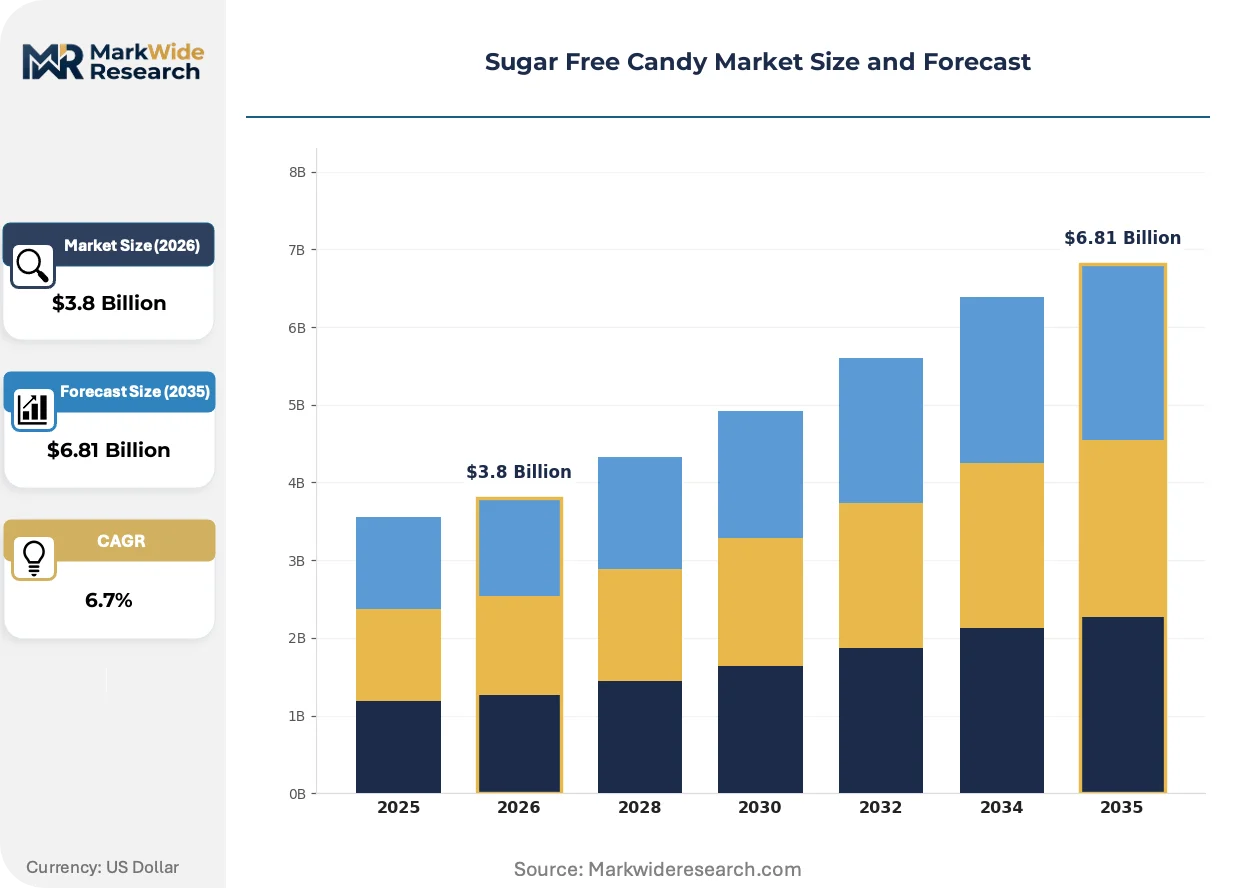
Market Dynamics
Enzymatic stevia extraction is compressing formulation costs while FDA sugar disclosure mandates force label redesigns across domestic portfolios, redistributing competitive advantage toward clean-label specialists with captive sweetener supply.
Growth Catalysts
- Diabetes prevalence expansion:The American Diabetes Association estimates 38 million diagnosed cases in the United States, creating durable demand for glycemic-neutral confections that bypass insulin response.
- Ketogenic diet adherence:Carbohydrate-restricted eating patterns now encompass 5% of US households, driving repeat purchase cycles for erythritol-sweetened chocolate and pectin-based gummies.
- EPA emissions standards:Stricter effluent controls on sorbitol manufacturing facilities are accelerating capital redeployment toward enzymatic bioprocessing plants with lower carbon intensity.
Market Restraints
- Erythritol input concentration:Three Chinese fermentation facilities supply 70% of global erythritol feedstock, exposing formulators to tariff volatility and shipping disruption.
- Digestive tolerance ceilings:Polyol consumption beyond 50 grams daily triggers osmotic laxation in 40% of consumers, capping per-capita consumption intensity.
- Clean-label cost premiums:Stevia-sweetened SKUs carry 35-45% higher COGS than maltitol equivalents, compressing margin at price-sensitive retail tiers.
Strategic Opportunities
- Pediatric dental channel:Pediatric dentistry practices in suburban Texas and Florida are deploying sugar-free lollipops as caries-prevention tools, opening clinical procurement pathways.
- USDA organic certification:Organic stevia leaf extraction qualifies products for dual clean-label claims, unlocking shelf space in Whole Foods Market and Sprouts Farmers Market.
- Enzyme engineering convergence:CRISPR-optimized yeast strains combined with continuous fermentation are collapsing steviol glycoside production costs below $8 per kilogram.
Industry Challenges
- GRAS determination latency:Novel sweetener submissions to FDA's Office of Food Additive Safety face 18-24 month review timelines, freezing formulation pipelines.
- Retail slotting fee escalation:Mass-market grocers demand $25,000-$50,000 per SKU for reduced-sugar confection placement, excluding mid-tier brands from mainstream distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Candy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Gummies, Chocolate, Mints Sweetener Type: Sorbitol, Erythritol, Stevia, Aspartame Packaging Type: Bags, Boxes, Tubs, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores |
| Companies Covered | The Hershey Company, Nestlé, Mars Incorporated, Mondelez International, Lindt & Sprüngli, Russell Stover Chocolates, Lily's Sweets, SmartSweets, Ferrero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Candy Market Evolving Landscape
Formulation science is converging with bioprocessing economics to compress the cost gap between artificial and natural sweeteners, while regulatory disclosure mandates and channel fragmentation are rewriting go-to-market architectures.
Precision fermentation-derived steviol glycosides are supplanting leaf-extracted equivalents in commercial formulations. Large-scale confectioners in the United States and Germany are adopting these biosynthetic variants to secure supply continuity and price predictability. This transition is compressing the premium historically attached to natural-positioned products.
REACH substance restrictions on synthetic food contact materials are forcing European confectioners to validate alternative packaging films for sugar-free products with higher moisture sensitivity. Chocolate manufacturers in Belgium and Switzerland are responding by accelerating migration to cellulose-based barrier layers.
Ketogenic diet adherents are consolidating purchasing through direct-to-subscription channels rather than conventional retail. Specialty e-commerce platforms such as Thrive Market and specialized subscription boxes are capturing 23% of category volume in coastal metropolitan areas. This channel rotation is most pronounced in California and New York, where health-conscious consumption patterns concentrate.
Sugar Free Candy Market Segmentation
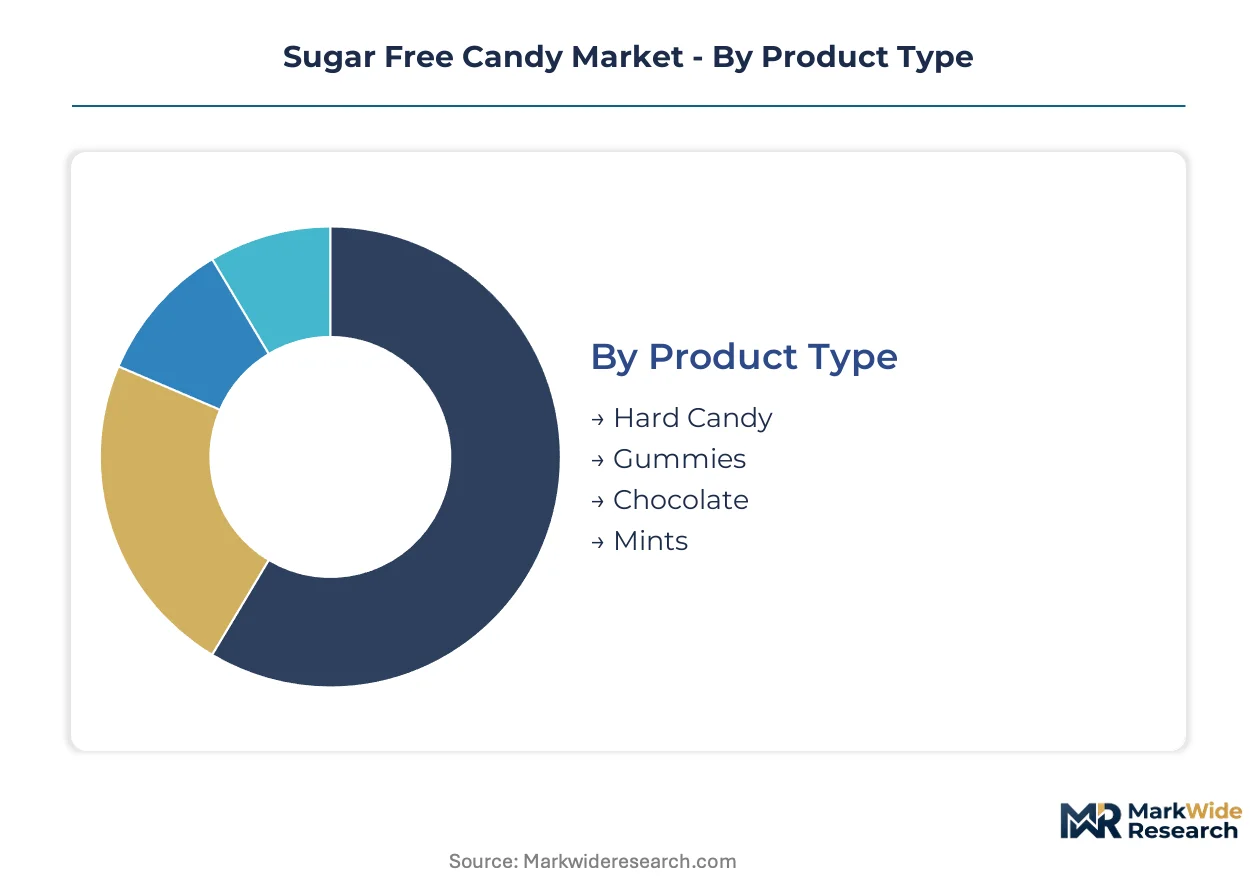
Sugar-free candy segmentation reveals how formulation chemistry and packaging economics divide purchasing power across diabetic, ketogenic, and dental-health consumer clusters. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Chocolate segments face the strongest substitution pressure from premium dark chocolate with naturally low sucrose content, while hard candy confronts functional overlap with medicated throat lozenges.
- Chocolate:Cocoa butter matrices incorporate erythritol or steviol glycosides to replicate snap and mouthfeel. Demand concentrates in United States coastal metropolitan areas where ketogenic diet adherence drives repeat purchase of Lily's Sweets and similar stevia-positioned lines. Price premiums reflect cocoa butter complexity and clean-label certification costs.
- Gummies:Pectin-based formulations with sugar alcohol bulking agents now dominate gelatin-free positioning. Florida and Texas pediatric dentistry practices are deploying these as caries-prevention tools, opening clinical procurement pathways distinct from conventional retail. Gelatin-free claims unlock shelf space in Whole Foods Market and Sprouts Farmers Market.
- Hard Candy:Isomalt and xylitol crystallization processes produce sustained-release flavor profiles. Functional overlap with medicated lozenges limits pure confectionery positioning.
- Mints:Sorbitol-based compressed tablets serve breath-freshening occasions with lower per-unit cost structures. Mondelez International anchors manufacturing scale across this category.
Chocolate retains volume leadership; gummies hold the steepest expansion curve.
Sweetener Type:
Cost tier stratification separates fermentation-derived polyols from leaf-extracted or biosynthetic high-intensity sweeteners, with margin compression most severe at the premium natural-positioned tier.
- Erythritol:Fermentation-derived from corn glucose using Moniliella pollinis yeast strains. Three Chinese facilities supply 70% of global feedstock, exposing United States formulators to tariff volatility. Superior digestive tolerance and cooling-effect properties command margin premiums over sorbitol equivalents.
- Stevia:Steviol glycosides from enzymatic extraction or precision fermentation now dominate clean-label formulations. CRISPR-optimized yeast strains are collapsing production costs below prior leaf-extraction economics. USDA organic certification unlocks dual claims for premium channel placement.
- Sorbitol:Hydrogenated glucose syrup serves as the cost-optimized polyol standard. EPA emissions standards on manufacturing effluent are accelerating capital redeployment toward enzymatic bioprocessing.
- Aspartame:Synthetic dipeptide sweetener retains presence in legacy sugar-free gum and mint formulations. Clean-label migration is displacing volume toward natural alternatives.
Erythritol dominates current formulation volume; stevia is climbing the fastest on clean-label migration.
Packaging Type:
Volume scale and margin accrual diverge sharply between single-serve convenience formats and bulk club-channel offerings, with moisture sensitivity of polyol-based products driving material innovation.
- Bags:Flexible film pouches with resealable closures dominate supermarket and convenience channel placement. REACH substance restrictions in Europe are forcing validation of cellulose-based barrier layers for moisture-sensitive polyol formulations.
- Boxes:Rigid paperboard with foil lamination serves gift and seasonal occasions. Higher per-unit packaging cost supports premium price positioning in health food retail.
- Tubs:Rigid plastic containers target office and automotive consumption occasions. Share-of-stomach competition with conventional sugar confections is most intense here.
- Bulk:Unpackaged or food-service-scale formats serve clinical and institutional procurement. Pediatric dentistry practices in suburban United States markets are emerging as a distinct demand cluster.
Bags retain volume leadership; bulk is gaining share fastest on clinical channel expansion.
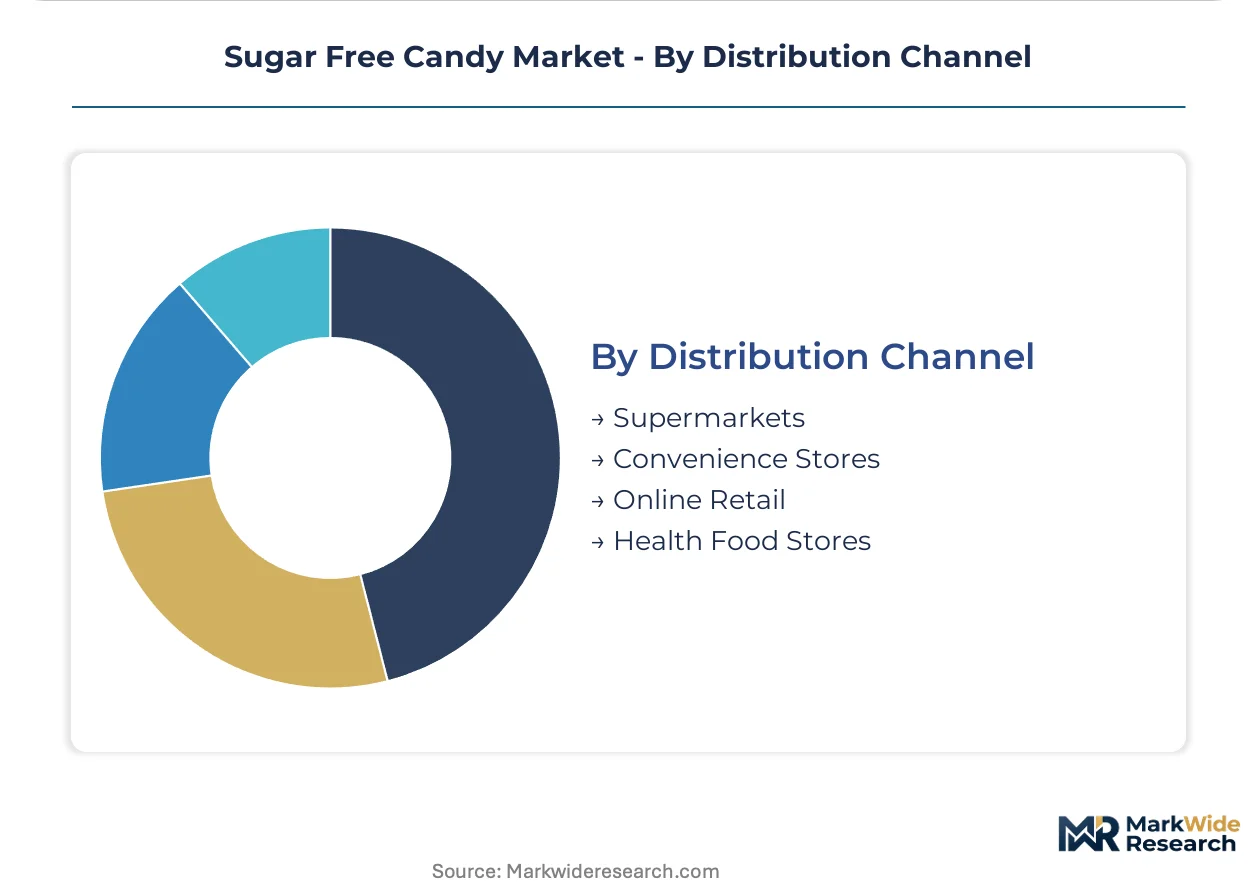
Distribution Channel:
Customer type and purchase occasion fragmentation is reshaping go-to-market economics, with slotting fee barriers excluding mid-tier brands from mass-market penetration.
- Online Retail:Direct-to-subscription platforms capture 23% of category volume in California and New York metropolitan areas. Thrive Market and specialized ketogenic subscription boxes consolidate purchasing from health-conscious households. This channel rotation bypasses conventional slotting fee structures.
- Health Food Stores:Whole Foods Market and Sprouts Farmers Market demand USDA organic certification and clean-label ingredient decks. Dedicated channel control here separates natural-positioned specialists from mass-market players.
- Supermarkets:Mass-market grocers demand $25,000-$50,000 per SKU for reduced-sugar confection placement. Hershey Company and Mondelez International leverage scale to absorb these barriers.
- Convenience Stores:Impulse-oriented placement favors single-serve mint and gum formats with immediate consumption occasion targeting.
Supermarkets retain volume leadership; online retail is expanding most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three Chinese fermentation facilities supply 70% of global erythritol feedstock, concentrating upstream chemical capacity in Shandong Province while finished confectionery demand fragments across North American and European health-conscious consumer clusters.
United States
Ketogenic diet adherence drives repeat purchase cycles for erythritol-sweetened chocolate in California and New York metropolitan areas. FDA sugar disclosure mandates force label redesigns across domestic portfolios. Hershey Company leverages Pennsylvania-based cocoa procurement networks to sustain consistent supply of chocolate-based sugar-free lines.
Germany
REACH substance restrictions on synthetic food contact materials force European confectioners to validate cellulose-based barrier films. ECHA oversight of polyol manufacturing emissions shapes facility siting decisions. Chocolate manufacturers in Cologne and Hamburg accelerate migration to sustainable packaging layers for moisture-sensitive formulations.
China
Shandong Province fermentation clusters dominate global erythritol production using Moniliella pollinis yeast strains. SAMR oversight of food additive safety classifications determines export eligibility. Zibo and Weifang industrial zones concentrate bioprocessing capacity that supplies United States and European formulators.
Belgium
Premium chocolate heritage positions Belgian manufacturers for clean-label stevia-sweetened innovation. EFSA steviol glycoside safety assessments enable formulation confidence across EU markets. Brussels and Liège processing clusters specialize in cocoa butter matrix adaptation for polyol incorporation.
Canada
Health Canada nutrition labeling requirements align with FDA disclosure stringency for cross-border product harmonization. Ketogenic diet penetration reaches 4% of Ontario and British Columbia households. Toronto and Vancouver retail chains expand dedicated shelf space for reduced-sugar confectionery.
Sugar Free Candy Market Competitive Landscape
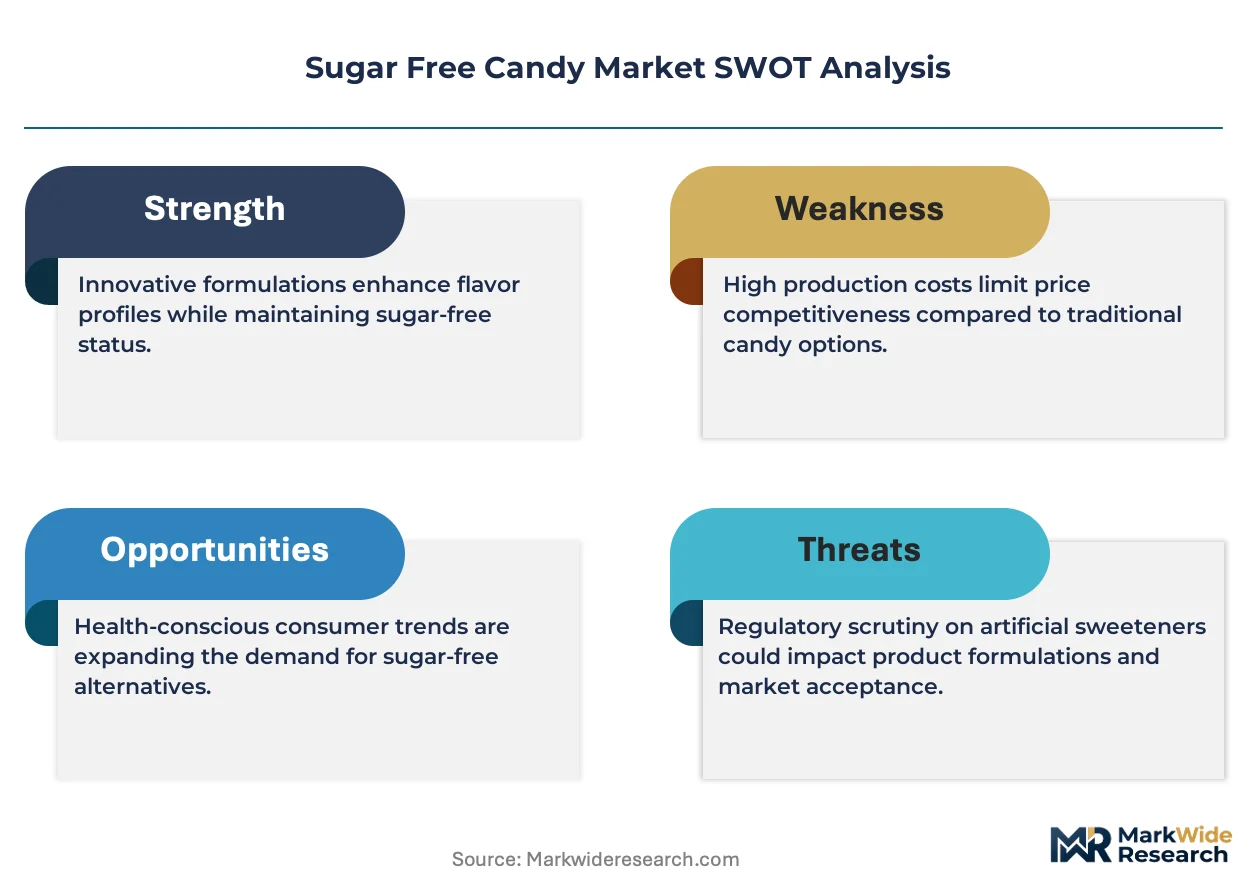
Concentration sits with diversified confectionery conglomerates and natural-positioned specialists operating in parallel tiers. The market structure divides between mass-market players absorbing slotting fee barriers and health-food channel specialists controlling premium placement. Three archetypes dominate: cocoa-integrated chocolate manufacturers, global mint and gum scale producers, and stevia-sweetened clean-label specialists. Competitive moves center on captive sweetener supply integration and direct-to-subscription channel bypass of conventional retail economics.
Among diversified confectionery conglomerates, The Hershey Company and Mondelez International exemplify scale-driven archetypes with manufacturing footprint advantages. Lily's Sweets occupies a specialist position within the natural-positioned tier. These three anchors represent contrasting strategic postures: cocoa supply control, global manufacturing scale, and dedicated health-food channel penetration.
| Leading Market Players |
|---|
| The Hershey Company |
| Nestlé |
| Mars Incorporated |
| Mondelez International |
| Lindt & Sprüngli |
| Russell Stover Chocolates |
| Lily's Sweets |
| SmartSweets |
| Ferrero |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for erythritol feedstock expose United States formulators to both tariff volatility and pricing power asymmetry, compressing margin structures when Shandong Province fermentation clusters face export restrictions. This lead-time band forces manufacturers to choose between carrying higher working capital or accepting spot-price exposure that reshapes competitive economics across stevia-sweetened and polyol-based tiers.
Pricing Analysis
FDA sugar disclosure mandates dictate the pricing tier structure across domestic portfolios, separating USDA organic-certified stevia lines from conventional maltitol equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with clean-label SKUs commanding shelf-space premiums. Cost compression in the standard tier is intensifying because Chinese erythritol tariffs feed directly into COGS. Ketogenic diet adherents in coastal metropolitan areas show least price sensitivity, while mass-market suburban households exhibit highest elasticity.
Supply Chain Analysis
Forty-five-day ocean freight from Zibo and Weifang industrial zones to Long Beach anchors working capital requirements for United States chocolate manufacturers. Supply concentrates in Shandong Province, South Korea, and Germany for fermentation-derived polyols and precision fermentation capacity. Raw material dependencies center on corn glucose feedstock, Moniliella pollinis yeast strains, and cocoa butter matrices from West African cooperatives. Single-source vulnerability in Chinese erythritol exposes formulators to SAMR export license delays. Distribution runs through mass-market grocers, health-food retail chains, and direct-to-subscription platforms with divergent slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services for ketogenic households are expanding faster than conventional retail volume, creating a service-attach layer that recurs monthly and locks in lifetime value beyond single-transaction candy purchases.
For Market Incumbents: Shield margin structures by securing captive stevia supply through precision fermentation partnerships before CRISPR-optimized yeast strains collapse spot-market premiums. Absorb EPA emissions compliance costs at sorbitol facilities to exclude mid-tier competitors from mainstream distribution. Vertical integration into enzymatic bioprocessing plants lowers carbon intensity exposure. For New Entrants and Emerging Players: Lead with pediatric dental channel penetration in suburban Texas and Florida markets, where clinical procurement pathways bypass conventional slotting fee barriers. Target bulk format placement in dentistry practices as the most penetrable white space. Deploy direct-to-subscription go-to-market models through Thrive Market and specialized ketogenic platforms. For Investors and Strategic Acquirers: Long-term, this sits as a clean-label consolidation play because enzymatic extraction economics are collapsing cost premiums and rewarding scale. Acquire specialists with USDA organic certification and established Whole Foods Market shelf presence. Watch FDA GRAS determination timelines for novel sweeteners as the inflection signal for formulation pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sweetener Supply Integration | Precision fermentation partnerships with CRISPR-optimized yeast strain developers secure cost predictability. |
| Pediatric Dental Channel Expansion | Clinical procurement pathways in Texas and Florida dentistry practices bypass mass-market slotting fees. |
| Direct-to-Subscription Launch | Thrive Market and ketogenic box services capture coastal metropolitan households with recurring revenue. |
| USDA Organic Certification Investment | Dual clean-label claims unlock premium shelf space in Sprouts Farmers Market and Whole Foods Market. |
| Enzymatic Bioprocessing Transition | EPA emissions compliance at sorbitol facilities excludes mid-tier competitors from mainstream distribution. |
Research Methodology
Desk research of FDA GRAS notifications, EPA effluent compliance records, and Nielsen retail audit data preceded structured interviews with formulation scientists at confectionery manufacturers, procurement leads at health-food retailers, and category buyers at mass-market grocers. Primary fieldwork with stevia extract suppliers and fermentation facility operators in Shandong Province validated secondary trade flow estimates. Bottom-up SKU-level volume builds and top-down category expenditure models were triangulated against customs records.
Variance decomposition across sweetener type, product format, and distribution channel shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include chocolate versus gummy versus hard candy matrices, erythritol versus stevia versus sorbitol formulations, and supermarket versus online retail versus health-food store channels. CAGRs were derived from elasticity-adjusted demand curves incorporating ketogenic diet penetration rates and diabetic population diagnostics. Steviol glycoside production cost trajectories and EPA emissions compliance timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA GRAS determinations and EPA manufacturing standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
India Industrial Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Chocolate Spread Market
Confectionery
Europe Confectionery Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Diet Candy Market
Confectionery
Low-Fat Sweets Market
Confectionery
Edible Glitter Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Confectionery Fillings Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
China Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
Caramel Chocolate Market