
 South America Olive Market | 2026-2036
South America Olive Market Size, Share, and Industry Trends Forecast 2026-2036
South America Olive Market Analytics
Subscription-based olive oil club services is consolidating purchasing patterns among premium consumers in Buenos Aires and São Paulo. Olivícola Laur leverages direct-to-consumer channels to sustain recurring revenue from specialty buyers. Solfrut anchors its position through controlled distribution in Argentine domestic retail. Olisur S.A. competes on extra-virgin certification depth across Chilean export markets.
Olive cultivation in South America encompasses fruit-bearing Olea europaea orchards producing oil, table fruit, and processed derivatives with free acidity thresholds below 0.8% for extra-virgin grades. The crop serves commercial oil extraction, packaged retail, and food manufacturing supply chains. Olive oil commands the dominant value share as health-positioned SKUs displace conventional cooking fats in Brazilian supermarkets. Table olives accelerate through food service penetration in Colombian and Peruvian restaurant channels. Bulk containers concentrate margin capture among exporters supplying North American and European buyers under traceability protocols.
Argentina's INTA sets varietal registration and phytosanitary standards governing orchard establishment and fruit quality benchmarks. Chile's Ministry of Agriculture enforces export certification aligned with USDA organic equivalence and EU PDO recognition requirements. Brazil's MAPA inspects import flows for compliance with Mercosur sanitary regulations. Stakeholders must monitor irrigation water access rulings and biocide reauthorization cycles that determine long-term orchard viability across the Andean production belt.
Market Dynamics
High-density super-intensive planting systems are compressing orchard establishment timelines across Argentina's Mendoza corridor and Chile's Central Valley, forcing capital reallocation toward mechanized harvesting infrastructure.
Growth Catalysts
- EU Organic Equivalence Recognition:Chile's Ministry of Agriculture secured mutual recognition agreements enabling seamless entry of certified organic olive oil into European retail channels.
- Drip Irrigation Expansion:Chilean producers are retrofitting traditional flood-irrigated blocks with precision moisture sensors and automated valve networks.
- Health-Positioned SKUs:Brazilian supermarkets are displacing conventional cooking fats with extra-virgin olive oil in dedicated premium aisle sections.
Market Restraints
- Input Cost Volatility:Argentine orchard operators face fertilizer price swings tied to peso devaluation and import licensing delays.
- Supply Concentration Risk:Mendoza's high-density corridors account for disproportionate export-grade volume, exposing buyers to regional frost events.
- Substitution Threat:Avocado oil and high-oleic sunflower oil compete for shelf space in Brazilian and Colombian retail.
Strategic Opportunities
- Underpenetrated Geography:Colombian Andean foothills offer untapped hectarage for super-intensive establishment with favorable diurnal temperature variation.
- Regulatory Tailwind:Brazil's MAPA is streamlining Mercosur sanitary protocols for intra-bloc olive oil trade.
- Channel Innovation:Subscription-based olive oil clubs are consolidating purchasing patterns among premium consumers in Buenos Aires and São Paulo.
Industry Challenges
- Skill Gap in Mechanized Harvesting:Argentine and Chilean operators lack trained technicians for over-the-row harvester maintenance.
- Certification Timeline Compression:INTA varietal registration and EU organic equivalence audits create multi-year delays for new orchard entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Olive Market |
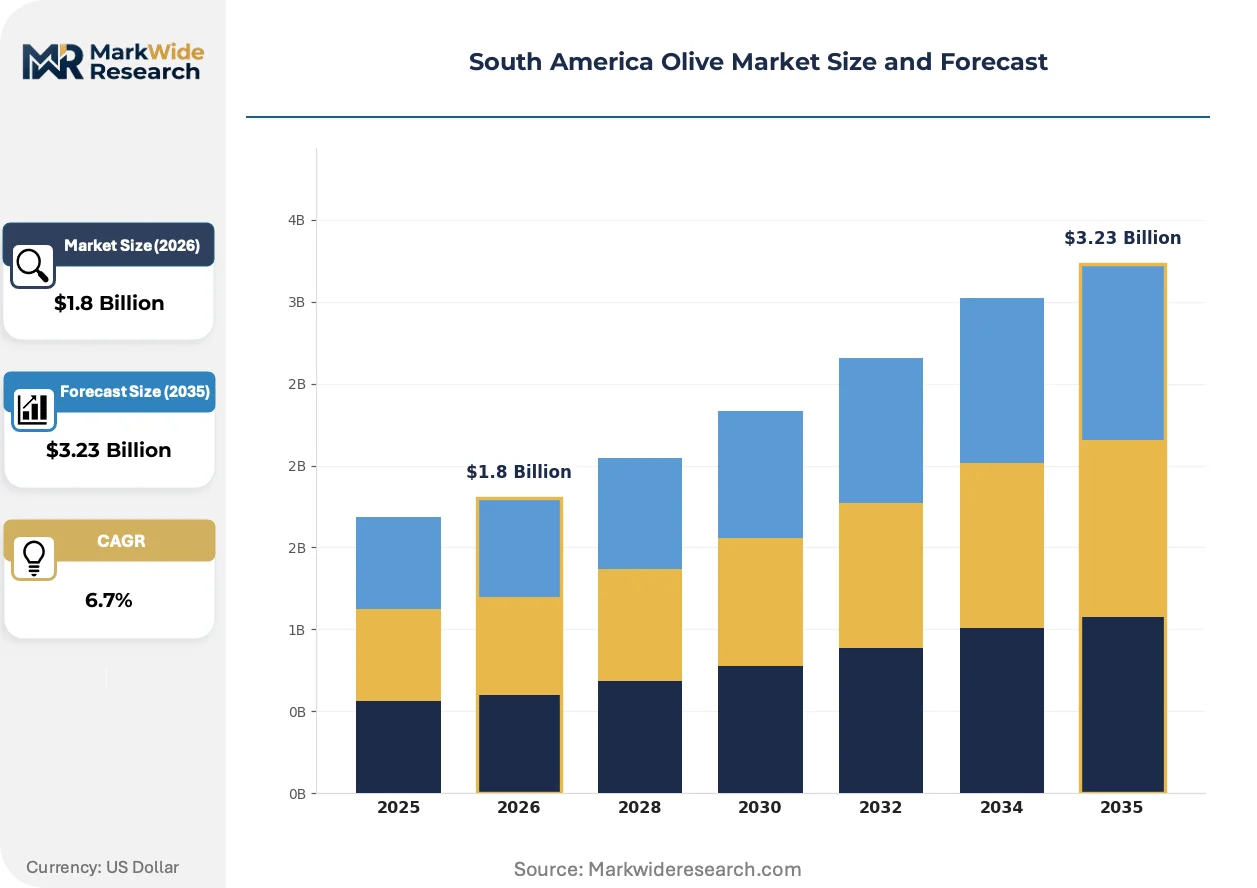
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Table Olives, Olive Paste, Olive Extract Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Food Service End User: Households, Restaurants, Food Manufacturers, Exporters Package Type: Bottles, Tins, Jars, Bulk Containers |
| Companies Covered | Olivícola Laur, Solfrut, Familia Zuccardi, Olisur S.A., Valle Grande S.A., Las Piedras, Prosperato, Deoleo S.A., Dcoop S.C.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Olive Market Evolving Landscape
Mechanization, traceability mandates, and direct-to-consumer channel experimentation are restructuring how South American olive oil reaches end buyers.
Robotic over-the-row harvesters are automating fruit collection in Chile's Central Valley super-intensive blocks. Large-scale producers in the Colchagua and Curicó provinces adopted these machines during the past three harvest cycles. The technology is automating labor cost structures and compressing harvest windows from weeks to days.
Argentina's INTA tightened phytosanitary documentation requirements for nursery stock movement between provinces. The regulation forces orchard developers to source certified plants through registered propagation facilities. Mendoza-based establishment projects are absorbing compliance costs and extending pre-planting procurement cycles.
Specialty buyers in São Paulo and Buenos Aires are migrating from supermarket aisles to producer-direct subscription channels. This pattern fragments traditional wholesale offtake and rewards brands with traceability storytelling. Olivícola Laur and similar operators capture recurring revenue through controlled digital storefronts rather than retail slotting fees.
South America Olive Market Segmentation
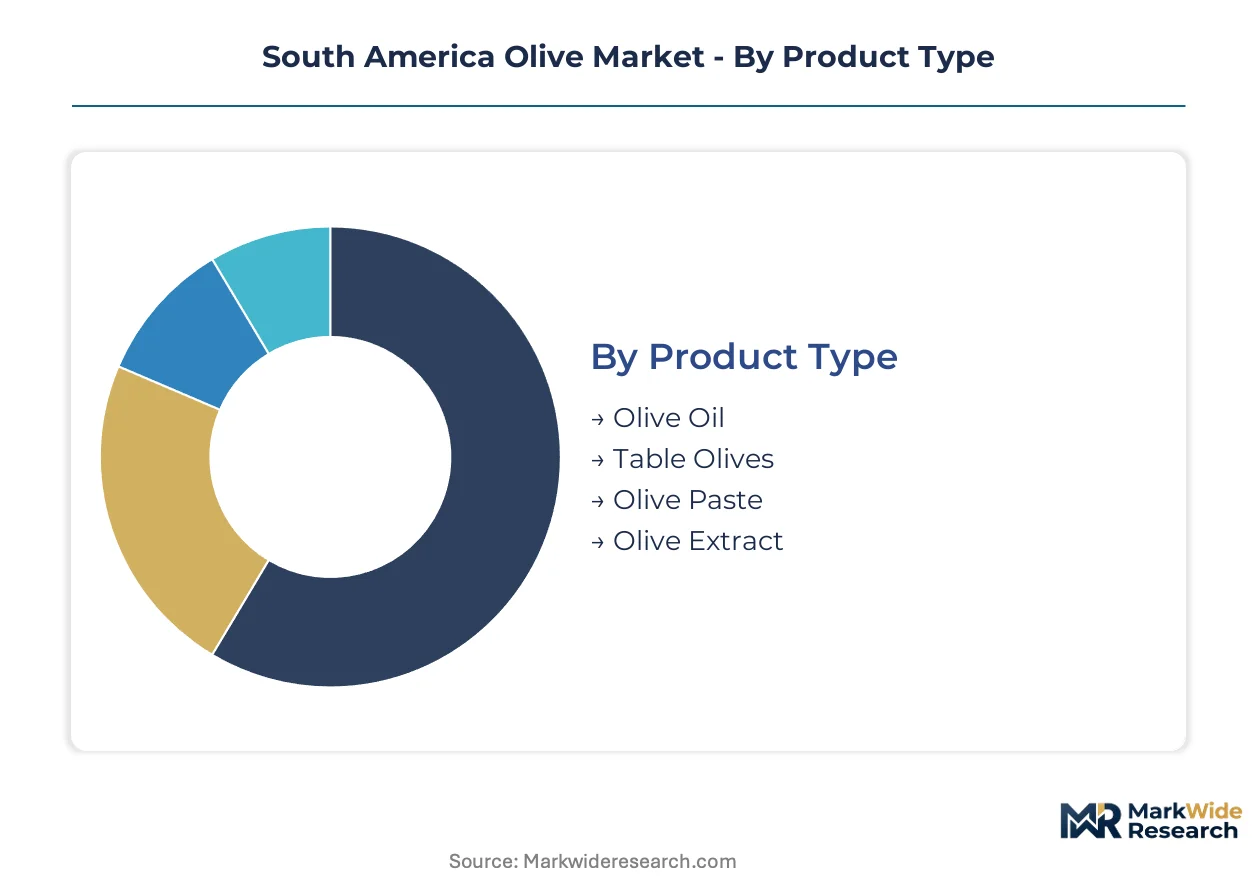
South American olive markets fragment across four distinct axes that determine margin capture and channel strategy. Product form dictates certification requirements and price realization. Distribution and packaging configurations shape working capital intensity and buyer relationships.
Product Type:
Buyers in this category separate by end-use application and quality threshold requirements.
- Olive Oil:Extra-virgin grades with free acidity below 0.8% command premium positioning in Brazilian supermarkets and Argentine export channels. Mendoza's high-density corridors and Chile's Central Valley concentrate supply for North American and European buyers under traceability protocols.
- Table Olives:Cured and brined fruit serves food service penetration in Colombian and Peruvian restaurant channels. Demand concentrates in urban consumption centers where appetizer and pizza applications drive volume.
- Olive Paste:Concentrated pulp derivatives supply food manufacturing formulations for spreads and sauces.
- Olive Extract:Functional ingredient streams target cosmetic and nutraceutical processors seeking polyphenol content.
Volume sits with Olive Oil; growth tilts toward Table Olives.
Distribution Channel:
Channel selection in this market tracks buyer sophistication and purchase frequency patterns.
- Supermarkets:Brazilian retail chains displace conventional cooking fats with dedicated premium aisle sections for extra-virgin SKUs. Slotting fees and promotional calendars determine brand visibility.
- Specialty Stores:Curated assortments in Buenos Aires and São Paulo serve connoisseur segments seeking traceability storytelling and limited editions.
- Online Retail:Subscription-based olive oil clubs consolidate recurring revenue from premium consumers through controlled digital storefronts.
- Food Service:Bulk procurement by Colombian and Peruvian restaurants accelerates table olive throughput.
Supermarkets anchor current volume; Online Retail climbs the fastest.
End User:
End-user categories diverge by volume scale and specification stringency.
- Households:Health-conscious consumers across Brazil and Argentina drive premium olive oil adoption through retail channels.
- Restaurants:Food service operators in Colombia and Peru source table olives for appetizer and pizza applications.
- Food Manufacturers:Processors incorporate olive oil and paste into packaged sauces, spreads, and prepared foods.
- Exporters:Chilean and Argentine operators supply North American and European buyers under USDA organic equivalence and EU PDO recognition requirements.
Households dominate consumption volume; Exporters gain share fastest.
Package Type:
Packaging economics separate by shelf-life requirements and logistics cost structures.
- Bottles:Glass and PET formats dominate retail olive oil presentation with UV protection and pour control features.
- Tins:Metal containers preserve oil quality for export-grade shipments to European and North American markets.
- Jars:Brined table olive presentation for retail and food service channels.
- Bulk Containers:Tote and drum formats concentrate margin capture among exporters supplying industrial buyers and food manufacturers.
Bottles lead household volume; Bulk Containers expand most quickly for export-grade supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina and Chile dominate production while Brazil absorbs the majority of consumption. This asymmetry shapes cross-border trade flows and investment patterns across the continent.
Argentina
Mendoza's high-density olive corridors generate the bulk of export-grade extra-virgin supply for North American buyers. INTA breeding programs and varietal registration standards govern orchard establishment timelines and phytosanitary compliance. San Juan province is expanding super-intensive blocks with mechanized harvesting infrastructure.
Chile
The Central Valley concentrates drip-irrigated super-intensive orchards serving EU organic equivalence protocols. The Ministry of Agriculture enforces export certification aligned with USDA and PDO recognition requirements. Colchagua and Curicó provinces deploy robotic over-the-row harvesters to compress seasonal labor windows.
Brazil
São Paulo and Rio de Janeiro metro areas drive premium olive oil adoption through subscription clubs and specialty retail channels. MAPA inspects import flows for Mercosur sanitary compliance and streamlines intra-bloc trade protocols. Supermarket chains displace conventional cooking fats with dedicated extra-virgin aisle sections.
Colombia
Andean foothills offer untapped hectarage for super-intensive establishment with favorable diurnal temperature variation. Bogotá and Medellín restaurant channels accelerate table olive demand for appetizer and pizza applications. Food service procurement concentrates in urban consumption centers.
Peru
Lima's food service operators source imported table olives and olive oil through coastal distribution hubs. Coastal valleys are evaluating irrigation infrastructure for potential orchard development. Regulatory alignment with Mercosur sanitary standards facilitates regional trade integration.
South America Olive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South America olive market. Orchard operators with owned cultivation and milling assets face specialized trading houses that source through contract farming networks. The structure fragments across three archetypes: vertically integrated estate producers, cooperative aggregators, and brand-focused packagers. Dominant competitive moves include backward integration into controlled hectarage and direct-to-consumer channel bypass of traditional wholesale.
Within the estate-producer tier, Olivícola Laur exemplifies the direct-to-consumer archetype through subscription-based revenue models. Solfrut anchors a position in Argentine domestic retail through controlled distribution relationships. Olisur S.A. occupies the export-certified segment with emphasis on extra-virgin grade depth for international buyers. These three S.A.-structured entities represent contrasting strategic postures within the same regulatory environment.
| Leading Market Players |
|---|
| Olivícola Laur |
| Solfrut |
| Familia Zuccardi |
| Olisur S.A. |
| Valle Grande S.A. |
| Las Piedras |
| Prosperato |
| Deoleo S.A. |
| Dcoop S.C.A. |
| Others |
Value Network & Pricing Analysis
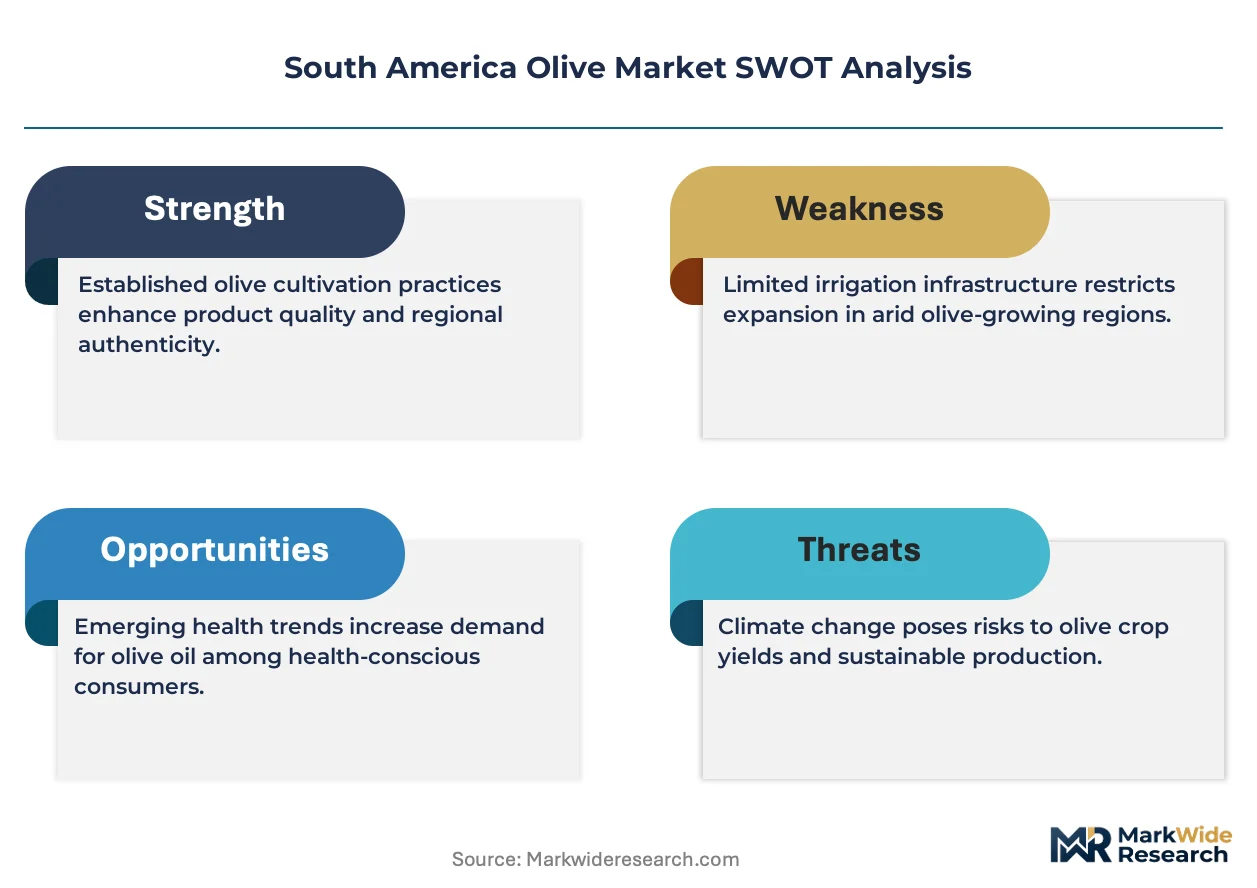
Fertilizer input costs originating from Argentine peso devaluation and import licensing delays cascade through Mendoza's high-density corridors into premium extra-virgin pricing tiers, while Chilean drip-irrigation retrofits compress operational expenditure structures for Central Valley exporters serving EU organic equivalence protocols.
Pricing Analysis
Cost-down pressure on standard-grade olive oil accelerates as high-oleic sunflower oil and avocado oil compete for Brazilian supermarket shelf space. Three-tier pricing structure across premium extra-virgin, standard virgin, and economy refined grades separates Mendoza estate producers from Chilean export-certified operators and Argentine domestic packagers. INTA varietal registration timelines and EU organic equivalence audit cycles extend payback periods for new orchard entrants, compressing returns. Brazilian households exhibit highest price sensitivity among end-users, while North American and European export buyers prioritize certification depth over unit cost.
Supply Chain Analysis
Seasonal labor availability constraints in Mendoza and Chile's Central Valley super-intensive blocks force capital reallocation toward robotic over-the-row harvester deployment. Supply concentrates in Argentina and Chile for export-grade extra-virgin production, with Brazil as dominant consumption market. Phytosanitary nursery stock dependencies and drip irrigation equipment sourcing from international vendors create single-source vulnerability during peso volatility episodes. Distribution runs through Buenos Aires and São Paulo specialty retail channels, subscription-based direct-to-consumer platforms, and bulk container shipments to North American and European industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's INTA varietal registration standards and Chile's EU organic equivalence protocols erect multi-year compliance barriers that protect incumbent orchard operators from rapid competitive entry.
For Market Incumbents: Lock in Mendoza and Central Valley hectarage through long-term lease structures or acquisition of established super-intensive blocks before Colombian Andean foothill development accelerates. Invest in mechanized harvesting technician training programs to close skill gaps that constrain harvest window compression. Defend against avocado oil substitution in Brazilian retail by deepening extra-virgin certification storytelling and traceability documentation. For New Entrants and Emerging Players: Capture Colombian Andean foothill greenfield opportunities where favorable diurnal temperature variation supports super-intensive establishment without incumbent supply concentration exposure. Target Bogotá and Medellín food service channels for table olive penetration where appetizer and pizza applications drive unmet demand. Pursue direct-to-consumer subscription club models in São Paulo and Buenos Aires to bypass supermarket slotting fee structures. For Investors and Strategic Acquirers: INTA registration completion for new varietal introductions is the leading indicator that Argentine orchard development timelines are compressing toward investable horizons. Prioritize estate producers with captive Mendoza or Central Valley hectarage, in-house milling assets, and established EU organic equivalence certification. Watch for MAPA streamlining of Mercosur sanitary protocols as signal that Brazilian import channel efficiency is improving.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Hectarage | Captures margin from orchard to bottle across Mendoza and Central Valley corridors. |
| Mechanized Harvesting Infrastructure Deployment | Compresses labor-dependent harvest windows from weeks to days in super-intensive blocks. |
| Direct-to-Consumer Subscription Channel Launch | Bypasses São Paulo and Buenos Aires supermarket slotting fees for recurring revenue capture. |
| EU Organic Equivalence Certification Investment | Unlocks seamless European retail channel access for Chilean Central Valley exporters. |
| Colombian Andean Foothill Orchard Development | Establishes production footprint in underpenetrated geography with favorable temperature variation. |
Research Methodology
Document review covered INTA varietal registration databases, Chile Ministry of Agriculture export certification records, and MAPA Mercosur sanitary protocol filings, complemented by interviews with Mendoza orchard operations managers, Chilean Central Valley irrigation specialists, São Paulo specialty retail buyers, and Buenos Aires subscription club operators. Secondary validation drew from customs trade flow data, agricultural ministry harvest reports, and equipment manufacturer shipment disclosures. Bottom-up hectarage and yield estimates triangulated against top-down consumption surveys across Brazilian, Argentine, Colombian, and Peruvian household panels.
Segment-level value outputs trace to modeled projections across product type, distribution channel, end user, and package type dimensions, with additional granularity on irrigation system configuration and certification tier. CAGRs derive from historical harvest volume trajectories, import penetration trends, and premium SKU displacement patterns in Brazilian retail. Forecast inputs incorporate INTA breeding program pipeline timelines, drip irrigation retrofit adoption curves, and robotic harvester deployment schedules across Colchagua and Curicó provinces.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to peso devaluation cycles, biocide reauthorization rulings, and frost event frequency in Mendoza's high-density corridors. Material deviation in EU organic equivalence mutual recognition status or MAPA protocol streamlining progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Starchy Roots Market