
 North America Olive Market | 2026-2036
North America Olive Market Size, Share, and Industry Trends Forecast 2026-2036
North America Olive Market Analytics
California's Sustainable Groundwater Management Act is broadening compliance requirements for olive growers throughout the Central Valley. California Olive Ranch leverages extensive orchard holdings to sustain volume leadership in domestic extra virgin production. Deoleo anchors European supply relationships that compete with regional processors on price. Pompeian, Inc. differentiates through established retail shelf presence across mass-market channels.
North American olives comprise the fruit of Olea europaea, typically harvested at maturation indices of 3.0 to 5.0 for oil extraction or brine-cured at lower indices for table consumption, with oil yields ranging from 15% to 25% by weight depending on cultivar and pressing method. Olive oil dominates value capture due to premium pricing for extra virgin grades, while table olives occupy stable volume positions in retail and food service. Specialty stores and online retailers represent the fastest-growing distribution channels as consumer purchasing shifts toward direct-to-home formats and curated assortments.
The U.S. FDA enforces standards of identity for olive oil grades under the Federal Food, Drug, and Cosmetic Act, while USDA organic certification shapes premium positioning for California and imported products. Canada's CFIA administers parallel olive oil purity standards under the Safe Food for Canadians Regulations, creating dual compliance pathways for cross-border suppliers. Stakeholders must monitor evolving authenticity testing protocols and water allocation rulings that will determine orchard expansion feasibility.
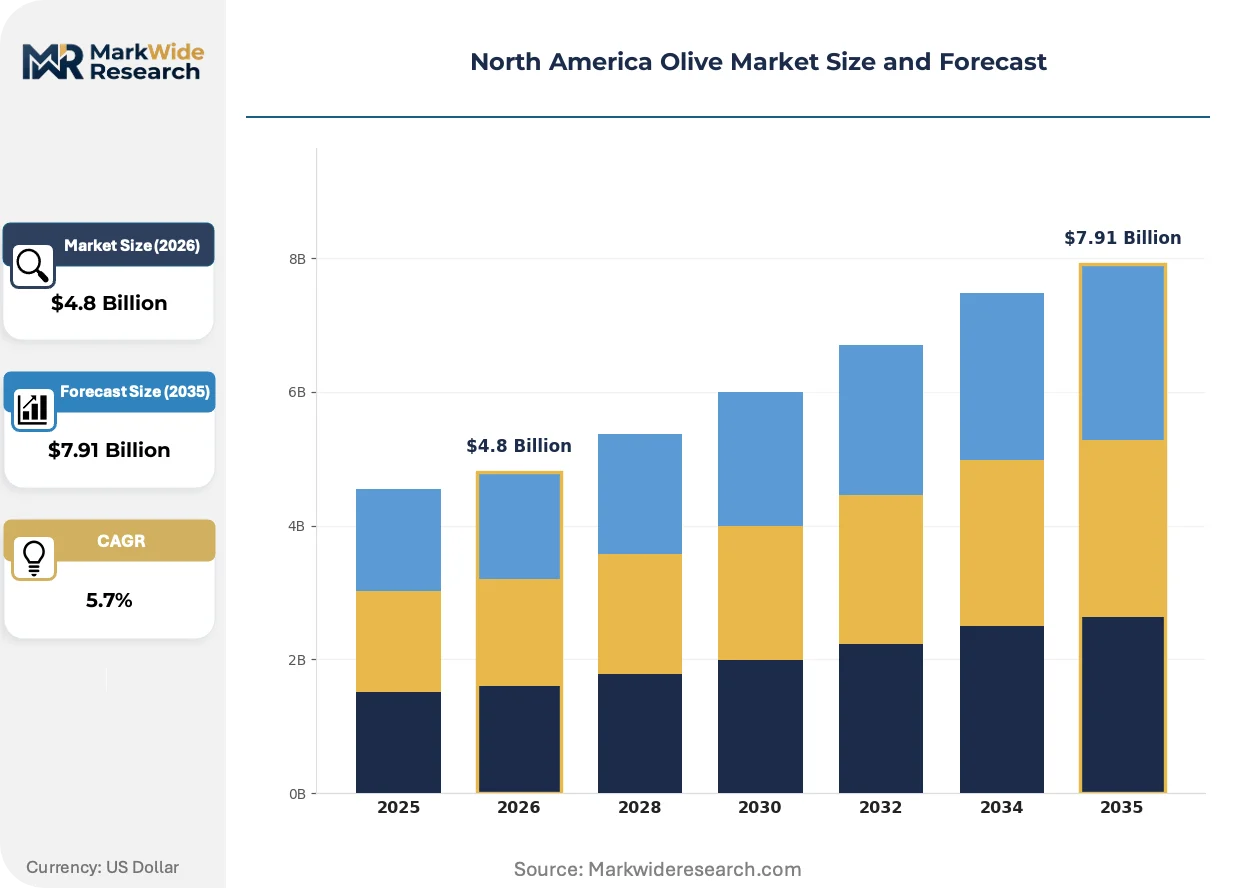
Market Dynamics
California's Sustainable Groundwater Management Act is compressing orchard expansion timelines while Mediterranean restaurant chains and specialty retailers pull volume through direct procurement contracts.
Growth Catalysts
- Water regulation compliance:California's SGMA implementation is accelerating orchard consolidation among capitalized growers who can fund groundwater sustainability plans.
- Specialty retail expansion:Curated food retailers across the United States and Canada are building direct relationships with Central Valley processors, bypassing traditional distribution tiers.
- Extra virgin grade premiums:Cold-press extraction technology adoption is enabling smaller producers to capture price premiums previously reserved for established brands.
Market Restraints
- Input cost volatility:Agricultural water allocation uncertainty in California's Central Valley is creating unhedgeable cost exposure for irrigated orchards.
- Supply concentration risk:European bulk oil imports, particularly from Spanish cooperatives, dominate price-setting for standard grades in North American food service.
- Substitution threat:Avocado oil and high-oleic sunflower oil are displacing olive oil in cost-sensitive commercial frying applications.
Strategic Opportunities
- Underpenetrated channel:Direct-to-consumer subscription models represent white space for California producers to build recurring revenue outside retail slotting constraints.
- Regulatory tailwind:USDA organic certification requirements are creating tiered pricing separation that rewards domestic producers with controlled supply chains.
- Emerging application:Functional food and cosmetic formulations using olive-derived polyphenols are opening industrial offtake contracts beyond edible oils.
Industry Challenges
- Skill gap in phenolic analysis:Laboratory capacity for authenticity testing and grade verification is concentrated among third-party providers, creating bottlenecks for compliance documentation.
- Capex intensity for mechanization:Super-high-density planting systems require substantial upfront investment in mechanical harvesters that depreciate across narrow seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Olive Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Olives, Olive Oil, Olive Paste, Olive Leaf Extract Grade: Extra Virgin, Virgin, Pure, Pomace Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Food Service End User: Household, Food Manufacturers, Restaurants, Cafes |
| Companies Covered | California Olive Ranch, Deoleo, Pompeian, Inc., Borges International Group, Colavita, Sovena Group, Gaea North America, The Olive Oil Source, Acesur North America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Olive Market Evolving Landscape
Mechanical harvesting systems, regulatory authenticity protocols, and channel restructuring are compressing cost structures while fragmenting buyer access across the North American olive supply chain.
Optical sorting technology paired with machine vision is automating defect detection in table olive processing lines. Mid-scale California packers are deploying these systems to reduce manual labor dependency during seasonal peaks. The technology is automating quality consistency that previously required experienced sorters, enabling round-the-clock operation without shift differentials.
The U.S. FDA's updated nutrition labeling requirements for edible oils are mandating fatty acid profile disclosure on retail packaging. California processors must reformulate label designs and validate laboratory testing protocols to maintain shelf placement. Extra virgin grades face the tightest compliance windows given their premium positioning and consumer scrutiny.
Food service distributors are unbundling bulk oil procurement from broadline contracts, enabling Mediterranean restaurant chains to source directly from importers or domestic mills. This disintermediation is compressing distributor margins while rewarding suppliers with traceability documentation and flexible lot sizing. The Northeast corridor exhibits the fastest channel restructuring as independent operators consolidate purchasing through group procurement organizations.
North America Olive Market Segmentation
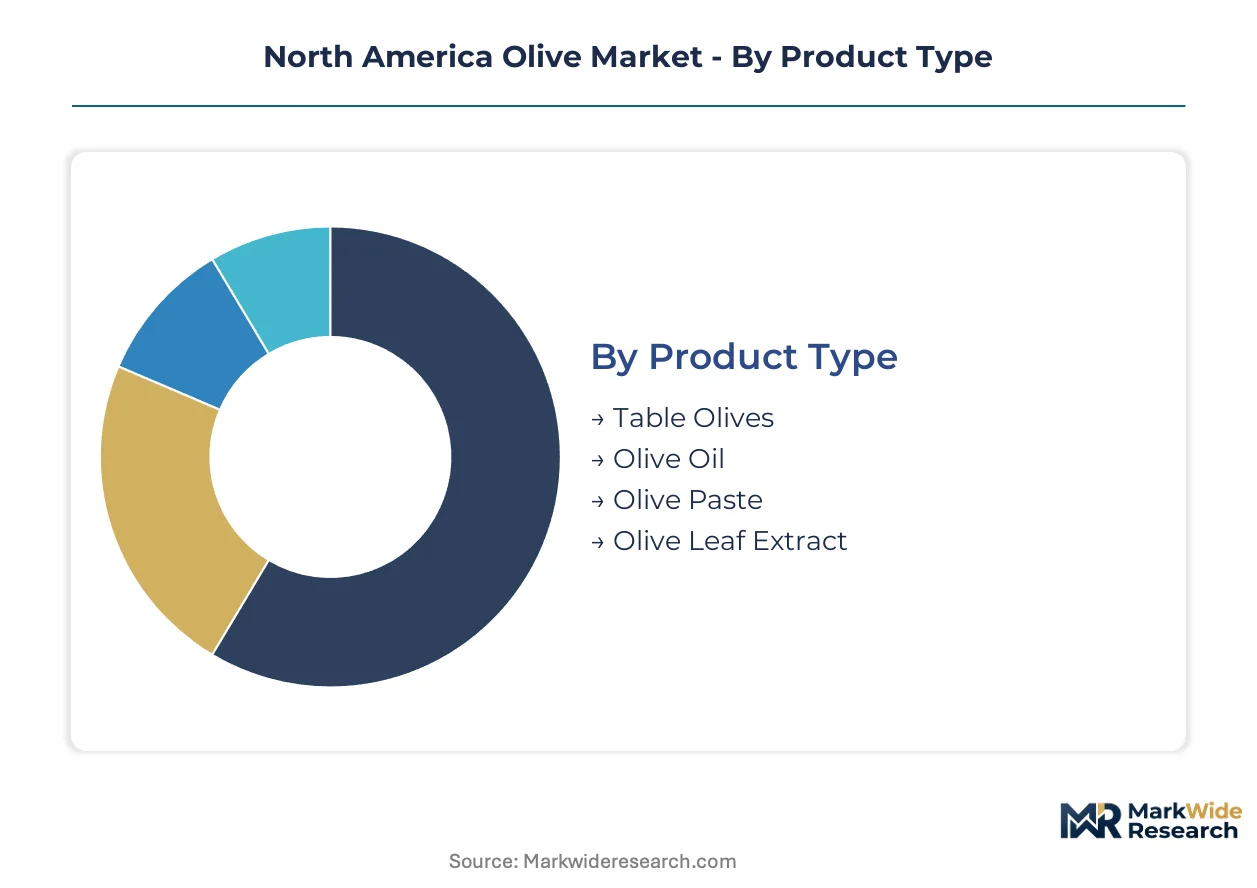
Segmentation in the North American olive market reveals how grade premiums, channel restructuring, and end-use specialization create divergent margin profiles across otherwise homogeneous fruit inputs. Understanding these fault lines exposes where capital deployment captures pricing power versus commodity exposure.
Product Type:
Upgrade cycles in extraction technology and consumer format preferences are redistributing value capture across processed olive outputs.
- Olive Oil:Cold-press extraction yields 15-25% by weight depending on cultivar and maturation index, with extra virgin grades commanding shelf price multiples over refined alternatives. California processors and Spanish importers compete for dominance in U.S. Northeast corridor retail placement.
- Table Olives:Brine-cured fruit harvested at maturation indices below 3.0 delivers stable volume through mass-market retail and Mediterranean restaurant chain procurement. California's Central Valley packers face labor cost pressure during seasonal sorting peaks.
- Olive Paste:Tapenade and spread formats concentrate in specialty retail and direct-to-consumer channels with shorter production runs.
- Olive Leaf Extract:Functional ingredient applications in supplements and cosmetics are gaining industrial offtake contracts beyond edible uses.
Volume placements concentrate in olive oil; the faster expansion belongs to olive leaf extract.
Grade:
Cost tier stratification separates capital-intensive quality verification from bulk commodity positioning.
- Extra Virgin:Free acidity below 0.8% and zero sensory defects under IOC standards require rapid processing post-harvest. California producers with controlled supply chains capture USDA organic certification premiums.
- Virgin:Slightly elevated acidity thresholds permit broader sourcing flexibility while maintaining cold-press labeling claims.
- Pure:Refined-virgin blends serve price-sensitive food service accounts with neutral flavor profiles.
- Pomace:Solvent-extracted residual oil occupies industrial frying and soap manufacturing applications with minimal brand attachment.
Revenue concentrates in extra virgin; pomace delivers volume floor protection.
Distribution Channel:
Customer type fragmentation is forcing suppliers to maintain parallel competency in mass-market slotting negotiations and direct relationship management.
- Supermarkets:Mass-market shelf placement demands broadline distributor relationships and promotional fund participation.
- Specialty Stores:Curated assortments and trained staff enable premium positioning for estate-bottled and single-varietal offerings.
- Online Retailers:Subscription models and direct-to-home formats are climbing fastest as purchasing shifts away from physical inspection.
- Food Service:Mediterranean restaurant chains and institutional buyers are unbundling procurement from broadline contracts to source directly.
Supermarkets anchor volume throughput; online retailers are expanding most quickly.
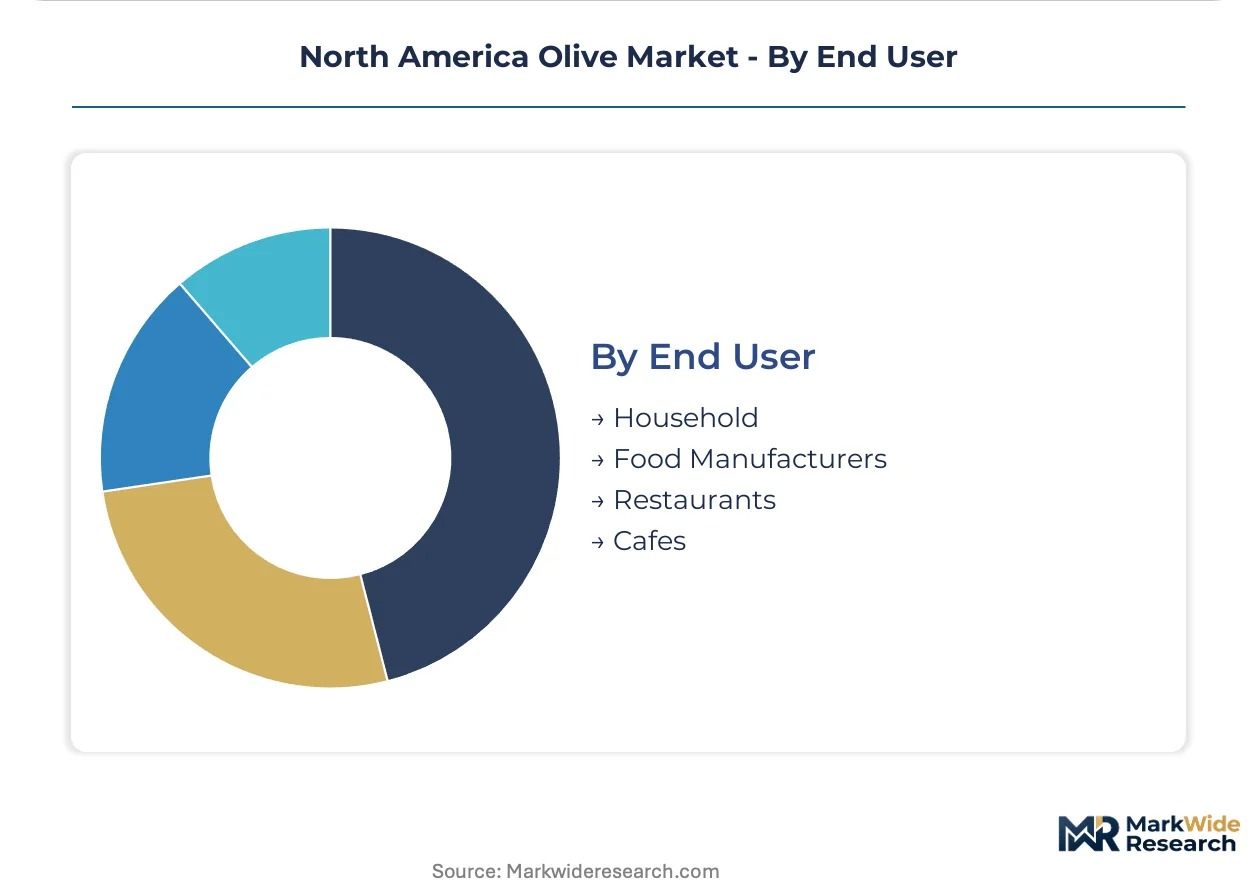
End User:
Application maturity determines whether procurement emphasizes traceability documentation or cost minimization.
- Household:Retail purchasers respond to grade labeling and origin claims with high substitution elasticity between domestic and imported alternatives.
- Food Manufacturers:Bulk oil buyers in baking and prepared foods prioritize fatty acid stability and consistent supply over varietal distinction.
- Restaurants:Mediterranean restaurant chains in the U.S. Northeast corridor are consolidating purchasing through group procurement organizations.
- Cafes:Small-format food service accounts represent fragmented demand with limited individual contract value.
Food manufacturers drive bulk volume; restaurants are restructuring procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley dominates North American olive production, with Fresno and Tulare counties hosting the continent's densest concentration of super-high-density orchards and cold-press processing facilities.
United States
California's Central Valley growers face tightening groundwater allocations under the Sustainable Groundwater Management Act. The U.S. FDA enforces fatty acid profile disclosure requirements for retail olive oil packaging. Fresno County processors are consolidating orchard holdings to fund compliance infrastructure for groundwater sustainability plans.
Canada
Mediterranean restaurant chains in Toronto and Vancouver are unbundling bulk oil procurement from broadline distributor contracts. Health Canada administers olive oil purity standards under the Safe Food for Canadians Regulations. Montreal's specialty retail corridor is expanding direct-import relationships with Spanish cooperatives.
Mexico
Emerging table olive consumption in Mexico City and Guadalajara is pulling trial volumes through U.S. border processors. Mexico's Federal Commission for the Protection against Sanitary Risk enforces imported food oil labeling requirements. Baja California test orchards are evaluating Mediterranean cultivar adaptation for potential domestic oil production.
North America Olive Market Competitive Landscape
Premium-margin players sit above commodity-margin players across grade certification and channel access. The North American olive market structures around three tiers: domestic estate bottlers with controlled supply chains, European importers with cooperative sourcing scale, and private-label packers serving mass retail. Three archetypes dominate competitive positioning: orchard-integrated processors, import-brand distributors, and specialty-channel curators. Capacity consolidation and direct-to-restaurant procurement bypassing distributors represent the dominant competitive moves reshaping margin capture.
Among orchard-integrated processors, California Olive Ranch exemplifies the domestic volume-leader archetype through extensive Central Valley holdings. Deoleo and Pompeian, Inc. occupy positions within the import-brand tier, with the former anchoring European supply relationships and the latter representing established mass-market shelf presence. These three entities collectively illustrate how competitive advantage separates across supply chain control depth versus retail distribution breadth.
| Leading Market Players |
|---|
| California Olive Ranch |
| Deoleo |
| Pompeian, Inc. |
| Borges International Group |
| Colavita |
| Sovena Group |
| Gaea North America |
| The Olive Oil Source |
| Acesur North America |
| Others |
Value Network & Pricing Analysis
Family-owned orchard holdings across California's Central Valley anchor supply discipline through patient capital allocation, enabling groundwater sustainability investments that commodity traders cannot replicate while enforcing grade-based pricing premiums through controlled harvest-to-bottle traceability.
Pricing Analysis
Cold-press yield performance anchors value-based pricing for extra virgin grades, with free acidity thresholds below 0.8% commanding shelf multiples over refined alternatives. USDA organic certification and IOC sensory standards create two-tier separation between estate-bottled premiums and mass-market positioning. Price erosion runs through standard grades as Spanish cooperative imports flood food service channels. Food manufacturers exhibit highest price sensitivity due to bulk procurement volumes, while specialty retailers absorb premiums for traceability documentation.
Supply Chain Analysis
Container freight rates from Spanish ports to U.S. East Coast distribution centers directly compress importer margins during peak Mediterranean harvest windows. Supply concentrates in Spain, Italy, and California for oil extraction, with Morocco and Turkey supplying brine-cured table varieties. Mechanical harvester fleets, groundwater pumping infrastructure, and cold-press processing equipment constitute capital-intensive input dependencies. Single-source vulnerability concentrates in Spanish cooperative bulk oil contracts that set regional price floors. Distribution runs through unbundled direct procurement by Mediterranean restaurant chains bypassing broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
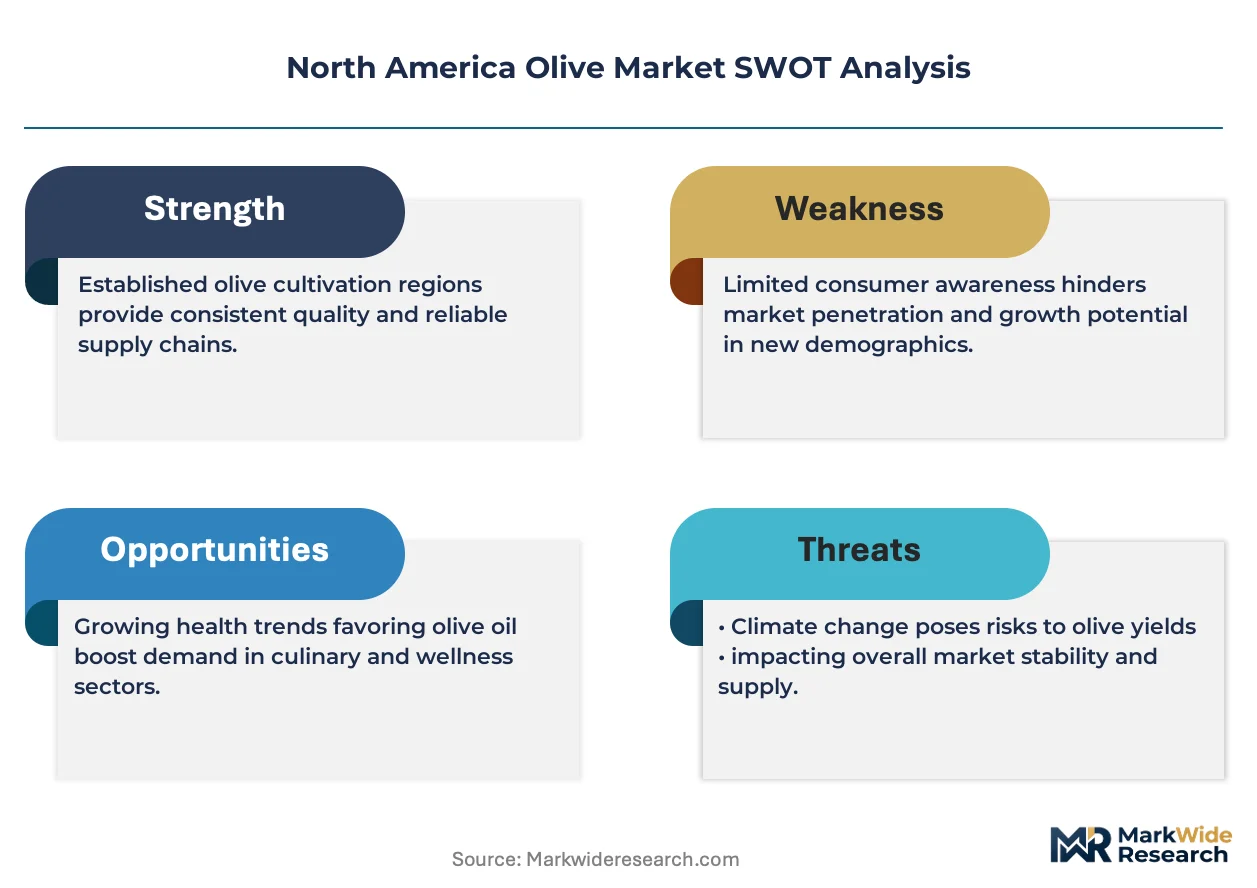
This market functions as a consolidation play where California's Sustainable Groundwater Management Act compliance costs force sub-scale orchard operators toward exit or acquisition by capitalized processors.
For Market Incumbents: Anticipate water allocation rulings by consolidating contiguous orchard holdings to spread fixed compliance infrastructure across larger productive acreage. Deepen backward integration into mechanical harvesting fleets to depreciate capital across extended seasonal windows and reduce labor cost exposure during peak sorting periods.
For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting the U.S. Northeast corridor, where purchasing shifts away from physical inspection fastest. Exploit white space in olive leaf extract functional ingredients for supplement and cosmetic formulations beyond edible oil applications.
For Investors and Strategic Acquirers: FDA enforcement actions against adulterated imports are the leading indicator that domestic estate bottlers with controlled supply chains will capture sustained pricing power. Target orchard-integrated processors with groundwater sustainability plan approvals already filed. Monitor laboratory capacity expansion for phenolic analysis as inflection signal for compliance infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Consolidation | California Olive Ranch leverages contiguous holdings to fund SGMA compliance infrastructure across Fresno County. |
| Direct-to-Restaurant Procurement | Mediterranean chains in the Northeast corridor unbundle from broadline distributors to source traceable lots. |
| Mechanical Harvester Deployment | Super-high-density plantings reduce manual labor dependency during narrow seasonal processing windows. |
| Organic Certification Investment | USDA tiered requirements create pricing separation rewarding controlled domestic supply chains. |
| Functional Ingredient Expansion | Olive-derived polyphenols open industrial offtake contracts beyond traditional edible oil applications. |
Research Methodology
Document review covered FDA enforcement records, USDA organic certification databases, California Department of Water Resources groundwater sustainability filings, and trade flow customs data, complemented by interviews with Central Valley orchard operators, Mediterranean restaurant chain procurement directors, specialty retail category buyers, cold-press processing facility managers, and third-party laboratory authentication providers. Secondary validation drew from IOC trade statistics, CFIA regulatory guidance, and academic phenolic analysis research. Bottom-up orchard yield modeling and top-down retail channel revenue estimates were cross-triangulated.
Historical volume trajectories were cross-referenced against panel input from supply chain participants to anchor projection assumptions across the analysis window. Segmentation modeling captured product type, grade tier, distribution channel, and end-use application dimensions. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost absorption rates and water allocation constraint scenarios specific to California's Central Valley growing region.
Revisions become necessary when groundwater sustainability plan rulings, FDA authenticity testing protocol updates, or Spanish cooperative export pricing shifts materialize outside modeled parameters. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market