
 Cambodia Fruits and Vegetables Market | 2026-2036
Cambodia Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Fruits and Vegetables Market Outlook
ASEAN Sanitary and Phytosanitary harmonization is expanding compliance requirements for Cambodian exporters entering regional value chains. THACO AGRI leverages integrated farm-to-port logistics to sustain cold-chain integrity for premium fruit shipments. Fresh Del Monte Produce anchors international quality benchmarks through its controlled ripening protocols and varietal selection programs.
Cambodia fruits and vegetables encompass fresh and minimally processed horticultural outputs cultivated across tropical lowlands and Mekong floodplains, with harvest cycles governed by monsoon patterns and supplemental irrigation. The category serves domestic food security, regional export markets, and processing feedstock for juice concentrates and dried products. Citrus and stone fruits command structural priority in export revenue pools due to Chinese and Vietnamese procurement contracts. Root vegetables dominate volume throughput through wholesale channels serving institutional buyers and wet-market vendors. Organic sales represent the fastest-expanding end-use segment as EU and Japanese importers tighten residue-limit protocols.
Cambodia's Ministry of Agriculture, Forestry and Fisheries administers planting permits and export phytosanitary certification under ASEAN framework obligations. The country's national food safety regulator enforces Codex-aligned maximum residue limits for produce entering formal retail and cross-border channels. Stakeholders must monitor evolving EU deforestation regulation traceability requirements and their potential extension to fruit supply chains originating from converted forest landscapes.
Market Dynamics
ASEAN Sanitary and Phytosanitary harmonization is compressing compliance timelines for Cambodian exporters, forcing rapid upgrades in traceability systems and cold-chain infrastructure to maintain regional market access.
Growth Catalysts
- ASEAN SPS Framework Alignment:Cambodia's Ministry of Agriculture, Forestry and Fisheries is streamlining phytosanitary certification to unlock Vietnamese and Thai procurement contracts for citrus exporters.
- Chinese Import Demand:Fresh longan and mango shipments through Bavet border crossings are scaling as Chinese buyers tighten specifications on sugar content and shelf-life metrics.
- Drip Irrigation Diffusion:Mekong floodplain cultivators are adopting pressure-compensating drip systems to extend dry-season production windows and improve yield consistency.
Market Restraints
- Fuel Price Volatility:Diesel costs for refrigerated trucking between Phnom Penh and Sihanoukville port are eroding margins for smallholder cooperatives lacking fleet scale.
- Input Concentration Risk:Fertilizer and agrochemical supply chains remain dependent on Vietnamese distributors, exposing Cambodian growers to cross-border tariff fluctuations.
- Post-Harvest Loss Rates:Absence of consolidated packing houses in Battambang and Pursat provinces forces reliance on informal roadside handling, degrading export-grade fruit quality.
Strategic Opportunities
- EU Deforestation Regulation Traceability:Early compliance investments in geospatial farm-mapping will position Cambodian banana and mango exporters ahead of competitors facing 2025 due diligence deadlines.
- Organic Certification Pipeline:Japanese JAS and EU organic standards represent underserved premium channels where residue-free Cambodian produce commands price multiples over conventional grades.
- E-Commerce Direct Sales:Fresh produce aggregation platforms linking Battambang orchards to Phnom Penh households are bypassing traditional wet-market intermediaries and capturing margin recovery.
Industry Challenges
- Cold-Chain Technician Scarcity:Refrigeration mechanics and temperature-controlled logistics managers remain concentrated in Phnom Penh, constraining quality assurance in peripheral growing provinces.
- Phytosanitary Audit Backlogs:Limited inspector capacity at Cambodia's national plant protection office is delaying export clearance timelines during peak harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Fruits and Vegetables Market |
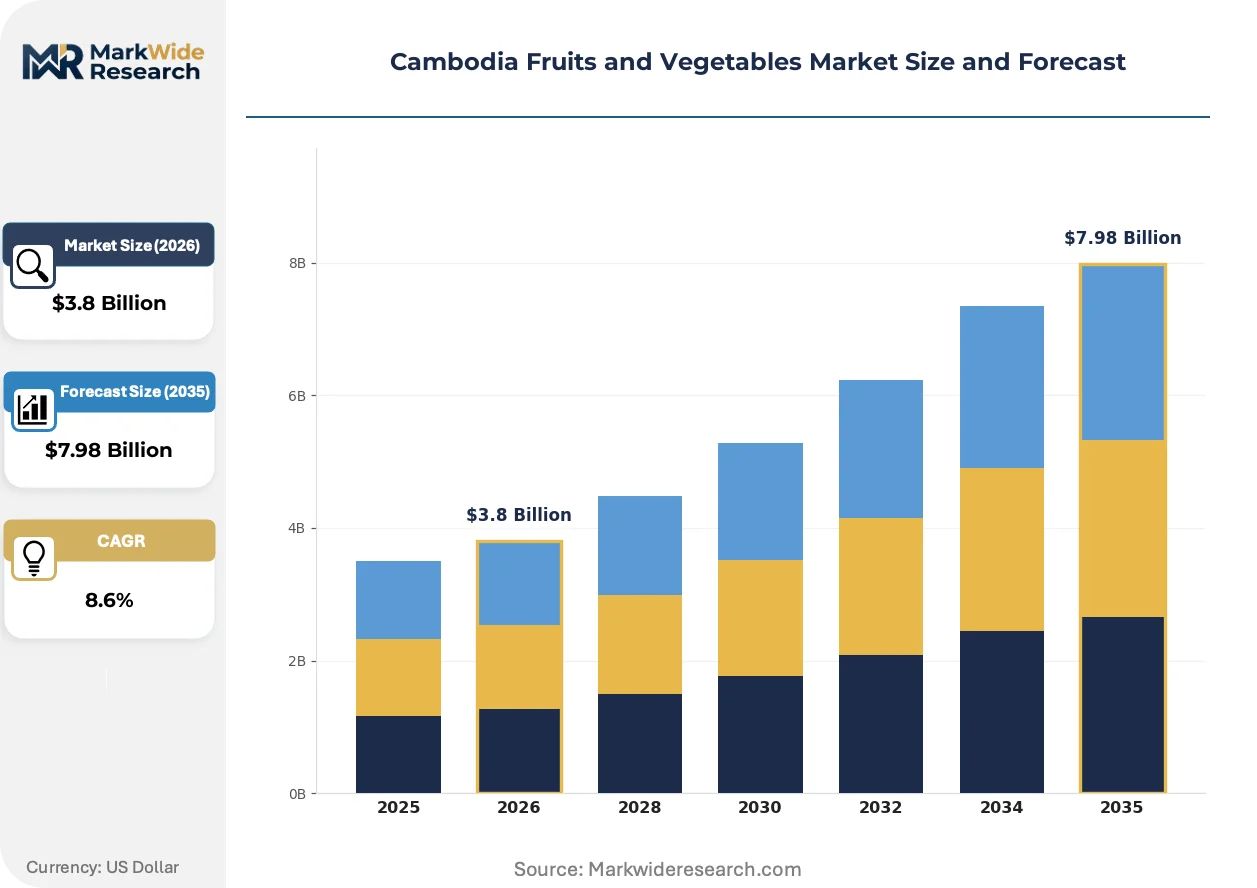
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Leafy Greens, Root Vegetables, Stone Fruits End Use: Fresh Produce, Processed Products, Organic Sales, Export Distribution Channel: Supermarkets, Farmer's Markets, Wholesalers, Online Retail Packaging Type: Bags, Boxes, Crates, Bulk Packaging |
| Companies Covered | Heifer International, Cambodia Agricultural Cooperatives Network, THACO AGRI, Private Fleet Operators Association, Chinese-Funded Processing Plants Consortium, Fresh Del Monte Produce, Techo International Airport, Cambodian Export Consolidation Centers, Coconut Palm Group Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Fruits and Vegetables Market Strategic Shifts
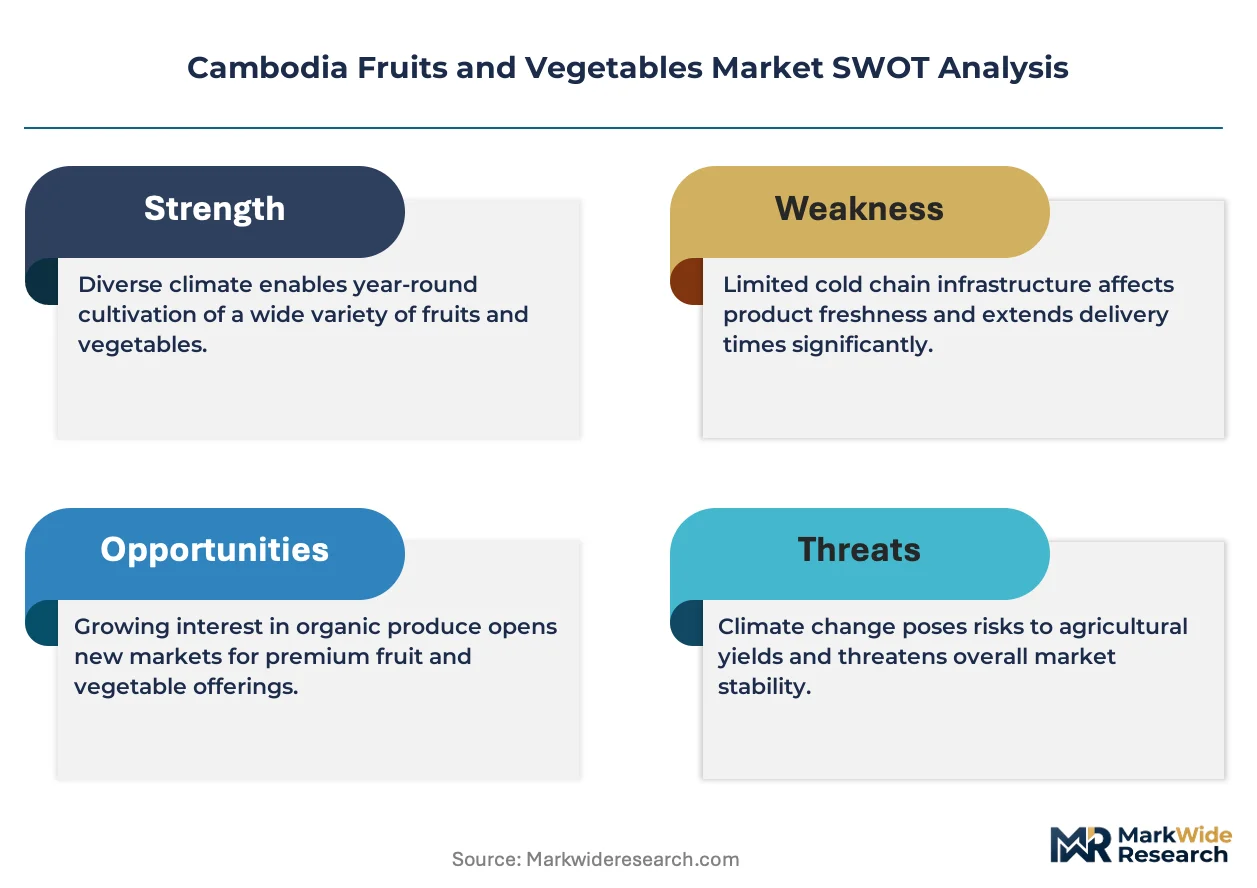
Digital traceability platforms and controlled-atmosphere storage technologies are restructuring how Cambodian produce moves from farm to export terminal, compressing quality variance and enabling premium market access.
Modified atmosphere packaging integrated with ethylene-absorbing sachets is overtaking conventional waxed-carton methods for longan and mango shipments to China. Exporters serving Shanghai and Guangzhou wholesale markets are adopting these systems within eighteen-month replacement cycles. The technology is enabling Cambodian suppliers to compete with Thai and Vietnamese peers on shelf-life guarantees without air-freight cost premiums.
Cambodia's national food safety regulator is enforcing Codex-aligned maximum residue limits ahead of full ASEAN harmonization deadlines. Domestic wholesale markets in Phnom Penh are now subject to random pesticide screening, diverting non-compliant produce to informal channels. Wet-market vendors and institutional buyers are responding by demanding supplier certificates of analysis, accelerating laboratory testing infrastructure investments.
Cross-border procurement patterns are rotating toward consolidated buying desks operated by Vietnamese and Chinese trading houses. Smallholder farmers in Kampong Speu and Kandal provinces are losing direct market access as these intermediaries impose volume minimums and exclusive supply contracts. The concentration is most visible in durian and jackfruit segments where Chinese demand has compressed traditional Thai supply dominance.
Cambodia Fruits and Vegetables Market Segmentation
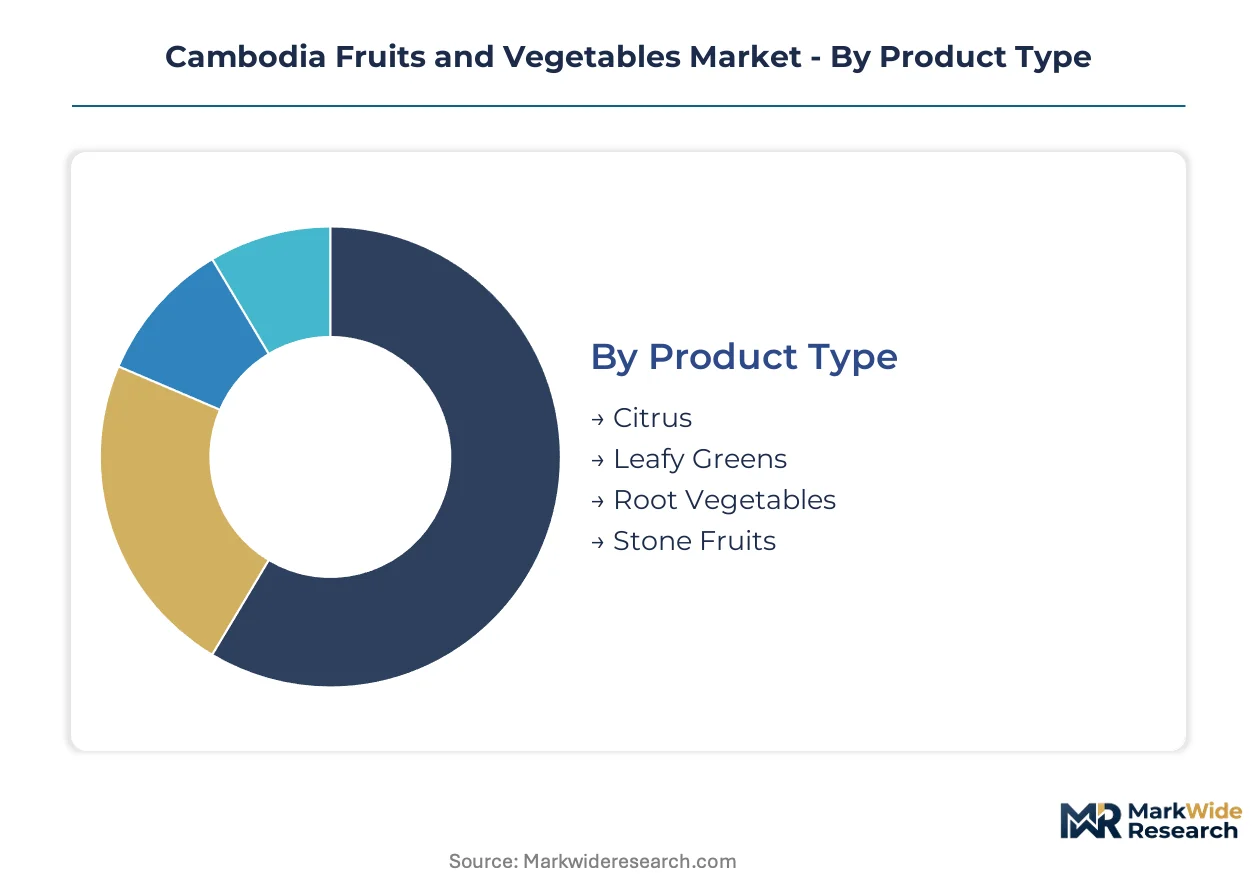
Cambodia's fruits and vegetables market fragments across cultivation characteristics, end-use specifications, and logistics requirements. Each segment demands distinct cold-chain protocols, certification standards, and buyer relationship structures.
Product Type:
Upgrade cycles in planting stock and post-harvest handling differentiate performance across varietal categories.
- Citrus:Pomelo and mandarin cultivars dominate export revenue pools through Vietnamese and Chinese procurement contracts. Battambang province growers are replanting with disease-resistant rootstock to extend productive orchard life beyond fifteen-year cycles.
- Stone Fruits:Mango and longan shipments through Bavet border crossings require controlled ripening protocols to meet Chinese sugar-content specifications. Kampong Speu orchards are installing ethylene-absorbing storage to reduce rejection rates at wholesale markets.
- Leafy Greens:Morning glory and water spinach serve domestic wet-market demand through Phnom Penh distribution clusters.
- Root Vegetables:Cassava and sweet potato volumes flow through Pursat and Battambang wholesale channels to institutional buyers.
Root vegetables sit at the top of the volume ranking, with stone fruits climbing the fastest.
End Use:
Application-specific quality tiers drive divergence in farm-gate pricing and certification investments.
- Fresh Produce:Unprocessed horticultural outputs move through Phnom Penh wet markets and modern retail channels with shelf-life windows of three to seven days. Kampong Cham smallholders are losing margin to consolidated buying desks that impose volume minimums.
- Organic Sales:JAS-certified and EU-standard residue-free produce commands price multiples through Japanese and European import channels. Kandal province cooperatives are converting orchard blocks to capture premium procurement contracts.
- Export:Cross-border shipments to Vietnam and Thailand require ASEAN SPS-compliant phytosanitary documentation from Cambodia's Ministry of Agriculture, Forestry and Fisheries.
- Processed Products:Juice concentrates and dried fruit feedstock absorb grade-B harvests rejected from fresh export channels.
Fresh produce dominates current revenue, while organic sales are gaining share fastest.
Distribution Channel:
Channel selection determines cold-chain infrastructure requirements and margin capture potential for Cambodian growers.
- Wholesalers:Traditional aggregators in Phnom Penh's Dangkao and Meanchey districts control volume throughput to wet-market vendors and institutional kitchens. Smallholder farmers in peripheral provinces remain dependent on these intermediaries for market access.
- Online Retail:Fresh produce aggregation platforms are linking Battambang orchards directly to Phnom Penh households, bypassing traditional intermediaries. Delivery networks are expanding same-day service coverage to capture margin recovery.
- Supermarkets:Modern retail chains require Codex-aligned residue documentation and temperature-controlled receiving protocols.
- Farmer's Markets:Direct producer-to-consumer sales concentrate in peri-urban Phnom Penh zones with minimal certification requirements.
Wholesalers retain the highest volume share, with online retail expanding most quickly.
Packaging Type:
Packaging technology selection governs shelf-life extension and export-grade quality maintenance.
- Modified Atmosphere Boxes:Waxed cartons integrated with ethylene-absorbing sachets are replacing conventional methods for longan and mango shipments to China. Exporters serving Shanghai wholesale markets are adopting these systems within compressed replacement cycles.
- Crates:Reusable plastic containers enable farm-to-retail handling without quality degradation for domestic supermarket channels.
- Bags:Perforated polyethylene serves leafy greens and small-volume retail portions through wet-market vendors.
- Bulk Packaging:Open-top containers move root vegetables and processing-grade harvests through low-cost logistics chains.
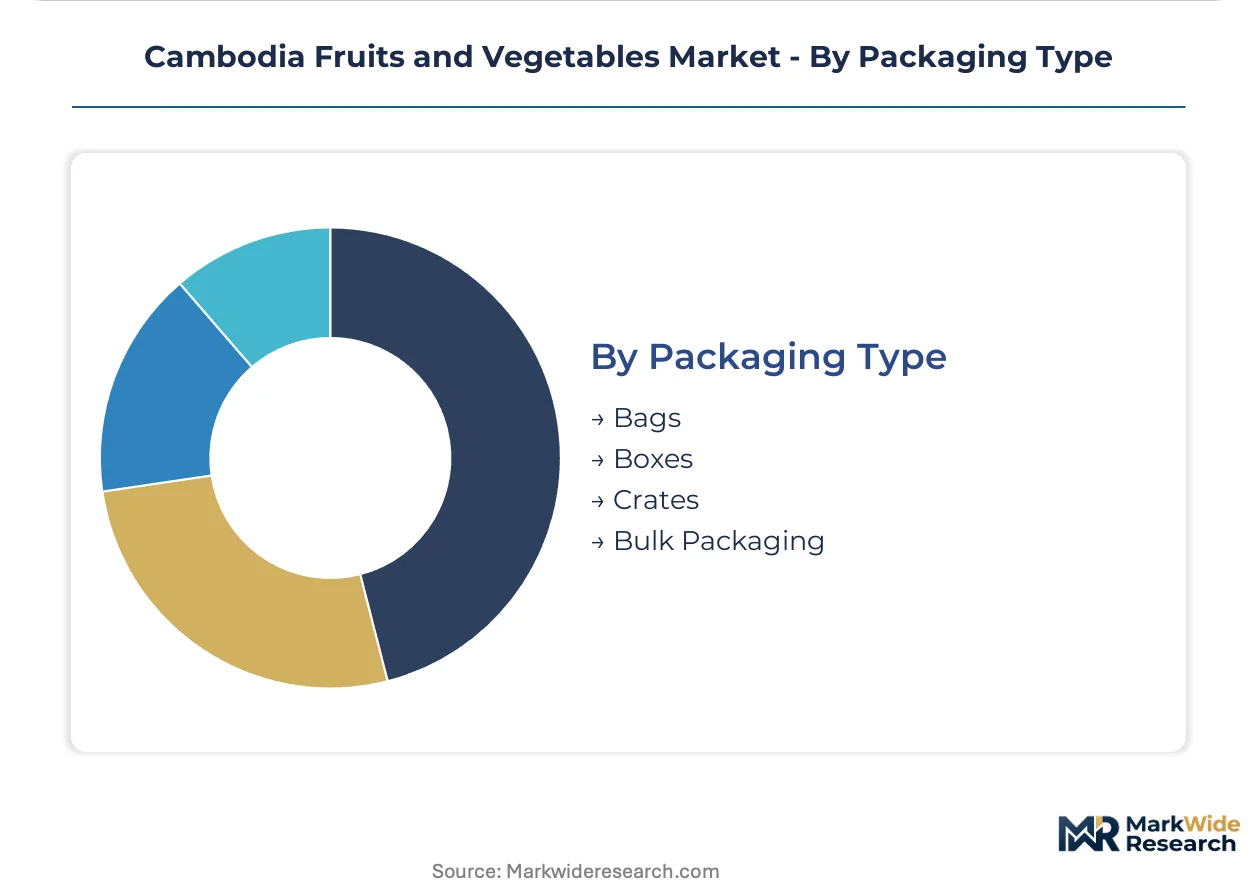
Bulk packaging handles the greatest tonnage, with modified atmosphere boxes showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder farmer cooperatives and peri-urban cultivation clusters anchor Cambodia's horticultural workforce across distinct agro-ecological zones. The country's Ministry of Agriculture, Forestry and Fisheries administers planting permits and export phytosanitary certification under ASEAN framework obligations. Each province presents differentiated infrastructure maturity and market access pathways.
Battambang Province
Citrus and pomelo orchards drive Battambang's export revenue through Vietnamese procurement contracts. The province's national plant protection office maintains phytosanitary certification capacity for cross-border shipments. Disease-resistant rootstock replanting programs are extending productive orchard cycles beyond fifteen years in Battambang's northwestern cultivation belts.
Kampong Speu Province
Stone fruit cultivation concentrates in Kampong Speu's Mekong floodplain zones serving Chinese buyers through Bavet border crossings. Ethylene-absorbing storage installations are reducing rejection rates at wholesale markets. Kampong Speu smallholders are losing direct market access to consolidated Vietnamese and Chinese buying desks imposing volume minimums.
Kandal Province
Peri-urban vegetable production supplies Phnom Penh's wet markets and modern retail channels with three-to-seven-day shelf-life windows. The national food safety regulator enforces Codex-aligned maximum residue limits in Kandal's wholesale markets. Organic certification conversion programs are capturing Japanese JAS and EU premium procurement contracts.
Pursat Province
Root vegetable volumes flow through Pursat's wholesale channels to institutional buyers and processing facilities. Absence of consolidated packing houses forces reliance on informal roadside handling degrading export-grade quality. Drip irrigation diffusion is extending dry-season production windows in Pursat's cassava and sweet potato cultivation zones.
Phnom Penh Peri-Urban Zone
Fresh produce aggregation platforms are linking peripheral orchards directly to Phnom Penh households bypassing traditional intermediaries. Same-day delivery networks are expanding coverage to capture margin recovery from wet-market displacement. Cold-chain technician scarcity remains concentrated in Phnom Penh constraining quality assurance in peripheral growing provinces.
Cambodia Fruits and Vegetables Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Cambodia's fruits and vegetables supply chain. The vendor base fragments across agricultural cooperatives, integrated logistics operators, and international trading houses with divergent scale advantages. Three archetypes dominate: integrated farm-to-port operators controlling cold-chain integrity, cooperative networks aggregating smallholder output, and international processors anchoring quality benchmarks. Capacity expansion in controlled-atmosphere storage and strategic partnerships with Chinese-funded processing infrastructure represent the dominant competitive moves.
Within the integrated logistics tier, THACO AGRI and Fresh Del Monte Produce exemplify divergent approaches to quality assurance and market access. THACO AGRI anchors farm-to-port cold-chain integrity for premium fruit shipments through controlled logistics networks. Fresh Del Monte Produce occupies a position anchoring international quality benchmarks through varietal selection and ripening protocol investments. Among cooperative and development-focused operators, Heifer International and Cambodia Agricultural Cooperatives Network represent smallholder aggregation archetypes with contrasting commercialization depth.
| Leading Market Players |
|---|
| Heifer International |
| Cambodia Agricultural Cooperatives Network |
| THACO AGRI |
| Private Fleet Operators Association |
| Chinese-Funded Processing Plants Consortium |
| Fresh Del Monte Produce |
| Techo International Airport |
| Cambodian Export Consolidation Centers |
| Coconut Palm Group Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Diesel costs for refrigerated trucking between Phnom Penh and Sihanoukville port cascade through three distinct pricing tiers downstream. Smallholder cooperatives lacking fleet scale absorb margin compression in the economy segment, while integrated operators with captive cold-chain assets defend premium positioning through quality guarantees.
Pricing Analysis
Certification-bundled versus unbundled service splits separate premium JAS-certified organic channels from conventional wet-market supply. Three-tier pricing structure across premium, standard, and economy levels tracks residue compliance, cold-chain integrity, and volume scale. Cost compression in the standard tier is intensifying because Vietnamese buying desks impose volume minimums that exclude fragmented smallholders. Wet-market vendors and institutional buyers exhibit highest price sensitivity, while Japanese and EU importers accepting residue-free premiums show lowest.
Supply Chain Analysis
Freight cost volatility for cross-border refrigerated trucking erodes exporter margins disproportionately in peripheral growing provinces. Supply concentrates in Battambang citrus belts, Kampong Speu stone fruit zones, and Kandal peri-urban vegetable clusters. Input dependencies rest on Vietnamese fertilizer distributors, Chinese ethylene-absorbing packaging suppliers, and Thai cold-chain equipment providers. Single-source vulnerability in phytosanitary certification capacity at Cambodia's national plant protection office threatens peak-season export clearance. Distribution runs through Phnom Penh wholesale aggregators, direct-to-household e-commerce platforms, and Bavet border crossing procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's fruits and vegetables market functions as a stable compounder anchored by ASEAN sanitary and phytosanitary harmonization that permanently expands regional market access for compliant exporters.
For Market Incumbents: Anticipate margin compression from consolidated Vietnamese and Chinese buying desks by securing backward integration into controlled-atmosphere storage and captive cold-chain fleets. Defend position through early EU deforestation regulation geospatial farm-mapping investments that lock in premium channel access ahead of competitor compliance timelines. Certification capacity expansion at Cambodia's national plant protection office represents the priority infrastructure lever. For New Entrants and Emerging Players: The price-point gap between JAS-certified organic premiums and conventional wet-market supply creates white-space opportunity in residue-free mid-tier positioning for domestic supermarket channels. Target Battambang and Pursat province smallholder aggregation where informal roadside handling degrades quality and consolidators capture arbitrage. Pursue e-commerce direct-sales platforms linking peripheral orchards to Phnom Penh households as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for cold-chain logistics operators because fragmented smallholder supply chains lack temperature-controlled infrastructure and yield consistent margin capture for integrated platforms. The five-to-ten year viability window favors acquisition of cooperative networks with existing phytosanitary certification relationships and established buyer linkages. Monitor Chinese-funded processing infrastructure announcements as the signal to watch for demand inflection and contract security.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Controlled-atmosphere storage installations in Battambang and Kampong Speu reduce post-harvest loss rates for export-grade fruit. |
| Organic Certification Pipeline | JAS and EU organic standard compliance unlocks Japanese and European premium procurement contracts for residue-free produce. |
| Geospatial Farm-Mapping | Early EU deforestation regulation traceability investments position Cambodian exporters ahead of competitor compliance deadlines. |
| E-Commerce Platform Development | Direct orchard-to-household aggregation bypasses traditional Phnom Penh wet-market intermediaries and captures margin recovery. |
| Drip Irrigation Diffusion | Pressure-compensating systems in Pursat and Battambang extend dry-season production windows and improve yield consistency. |
Study Parameters
Multiple input streams — primary interviews with agricultural cooperative managers, cold-chain logistics operators, and Ministry of Agriculture certification officers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged phytosanitary inspectors at Cambodia's national plant protection office, procurement managers at Vietnamese and Chinese trading houses, and supermarket category buyers in Phnom Penh. Secondary sources included ASEAN trade statistics, Cambodia's Ministry of Agriculture planting permit records, and EU deforestation regulation compliance guidance documents.
Historical volume trajectories were cross-referenced against expert panel assessments to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled encompassed product type, end-use specification, distribution channel, and packaging technology tier. CAGRs were derived through regression analysis of planted area expansion, yield improvement curves, and export contract growth patterns. Industry-specific forecast inputs incorporated monsoon variability indices and cross-border infrastructure development timelines.
Caveats apply where fuel price volatility, phytosanitary audit backlogs, or EU regulatory enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about ASEAN integration pace and Chinese import demand stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market