
 Telematics Control Unit Market | 2026-2036
Telematics Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics Control Unit Market Outlook
Fleet management is recalibrating the end-use mix for telematics control units as logistics operators prioritize real-time visibility and predictive maintenance. Continental AG leverages its embedded systems expertise across European OEM programs. Robert Bosch GmbH sustains manufacturing scale through its Stuttgart-based electronics operations. Denso Corporation anchors Asian supply relationships with tier-one automotive manufacturers.
A telematics control unit is an embedded automotive electronic module integrating GPS receivers, cellular modems, microcontrollers, and CAN bus interfaces to enable vehicle-to-infrastructure communication, remote diagnostics, and emergency response automation. The device processes location data, engine parameters, and driver behavior metrics through firmware executing on ARM-based processors with automotive-grade temperature tolerances. Embedded Units dominate unit shipments as OEMs factory-install hardware to comply with regulatory mandates, while Fleet Management Solutions capture expanding software and service margin pools. Cellular Connectivity leads technology adoption as 4G LTE and 5G modules displace earlier 2G implementations. OEMs represent the most concentrated buyer segment, though Insurance Companies are emerging as a distinct demand channel through usage-based policy programs.
The European Union's ECall regulation, the United States NHTSA safety frameworks, and China's MIIT connected vehicle standards collectively mandate automatic crash notification and remote diagnostic capabilities that require certified telematics hardware. EMA and EU AI Act provisions are beginning to shape data governance requirements for biometric driver monitoring applications. Stakeholders must monitor spectrum allocation decisions for C-V2X communication and evaluate regional certification divergence before committing to platform architectures.
Market Dynamics
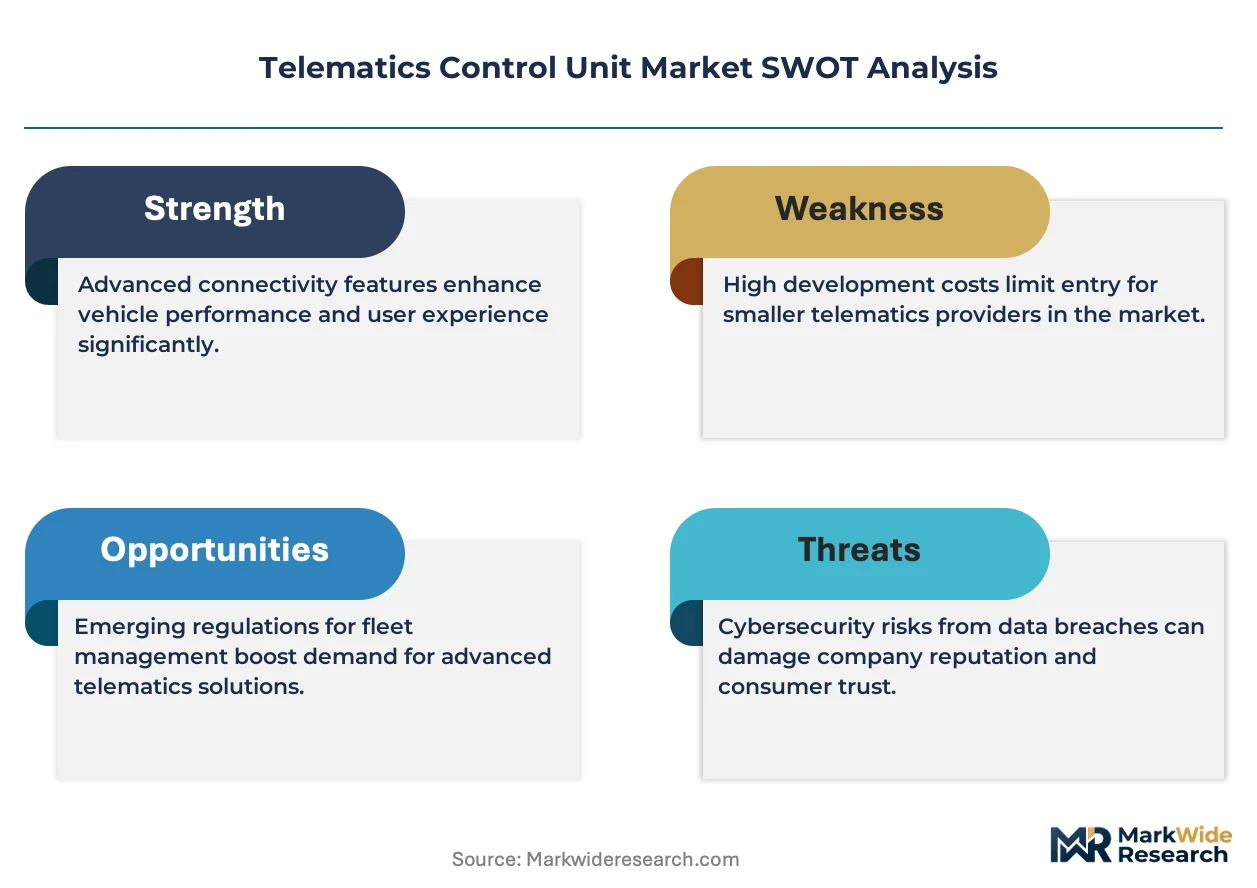
Fleet operators are forcing a demand recalibration as embedded connectivity shifts from optional feature to compliance-mandated infrastructure. Cellular module integration now determines platform competitiveness.
Growth Catalysts
- ECall Mandates:The European Union's automatic crash notification regulation compels OEMs to factory-install certified telematics hardware across all new vehicle registrations.
- 5G Module Deployment:Automotive-grade cellular modems are displacing legacy 2G implementations as telecommunications operators sunset older network generations.
- Fleet Management Software:Logistics operators are bundling predictive maintenance algorithms with hardware procurement, expanding recurring revenue pools beyond unit sales.
Market Restraints
- Semiconductor Supply Concentration:ARM-based automotive microcontrollers face allocation constraints from concentrated foundry capacity in Taiwan and South Korea.
- Certification Timeline Friction:NHTSA safety validation protocols in the United States extend hardware approval cycles by 14-18 months versus European type-approval processes.
- Cellular Subscription Cost Structure:Recurring connectivity fees compress fleet operator margins in price-sensitive commercial vehicle segments.
Strategic Opportunities
- Usage-Based Insurance Channels:Insurance Companies are emerging as direct procurement stakeholders through driver behavior data monetization programs.
- Biometric Monitoring Convergence:Driver fatigue detection systems combining CAN bus data with cabin cameras create new hardware attachment points.
- India Automotive Production:Domestic OEM expansion under PLI scheme incentives is generating demand for localized telematics module sourcing.
Industry Challenges
- Firmware Integration Complexity:Multi-protocol stacks combining C-V2X, GPS, and cellular modems require scarce embedded systems engineering talent.
- Cross-Border Data Governance:GDPR in Europe, China's data localization rules, and state-level privacy statutes in the United States create fragmented compliance architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics Control Unit Market |
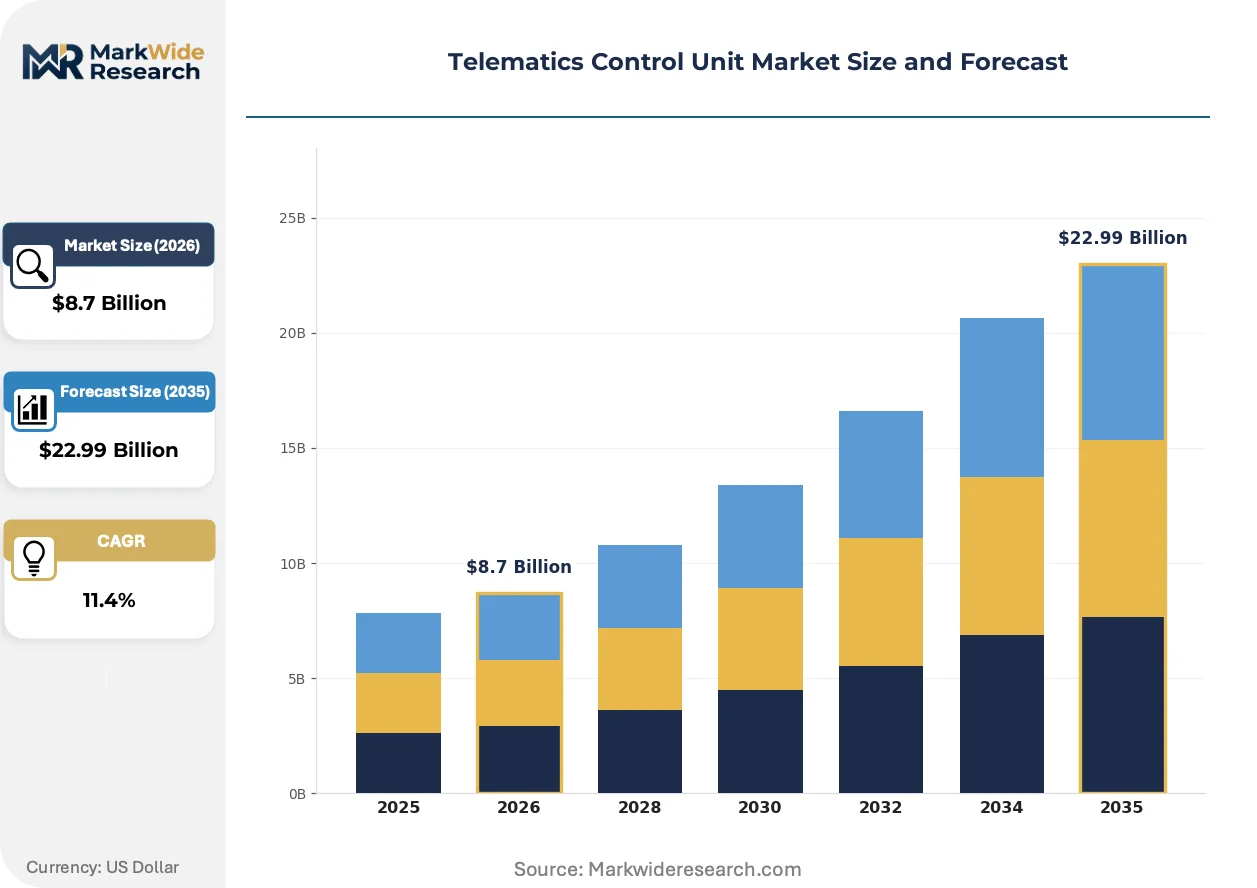
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Units, Aftermarket Devices, Fleet Management Solutions, Mobile Telematics Technology: GPS Tracking, Cellular Connectivity, Satellite Communication, Short-Range Communication End User: OEMs, Fleet Operators, Insurance Companies, Individual Consumers Application: Vehicle Tracking, Driver Behavior Monitoring, Remote Diagnostics, Emergency Services |
| Companies Covered | Continental AG, Marelli Holdings, LG Electronics, Visteon Corporation, Valeo, Harman International, Denso Corporation, Ficosa International, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics Control Unit Market Strategic Shifts
Edge computing architectures are redistributing processing loads away from centralized cloud infrastructure. This shift is compressing latency requirements and rewriting supplier value capture models.
Software-defined radio modules are decentralizing cellular connectivity hardware from discrete modem components into reprogrammable baseband processors. Tier-one suppliers are consolidating multiple regional SKUs into single programmable units. This consolidation is compressing inventory carrying costs while extending platform lifecycle coverage across 4G and 5G spectrum allocations.
China's MIIT connected vehicle standards are mandating V2X communication capabilities as a prerequisite for new energy vehicle subsidies. Domestic OEMs are accelerating C-V2X chipset qualification to maintain incentive eligibility. The regulation is forcing module suppliers to prioritize Chinese certification timelines over European or North American approval sequences.
Fleet procurement departments are unbundling hardware acquisition from connectivity service contracts. Large logistics operators are negotiating direct relationships with telecommunications carriers rather than accepting OEM-bundled subscriptions. This disintermediation is most visible in German and United States commercial vehicle markets where fleet scale exceeds ten thousand units.
Telematics Control Unit Market Segmentation
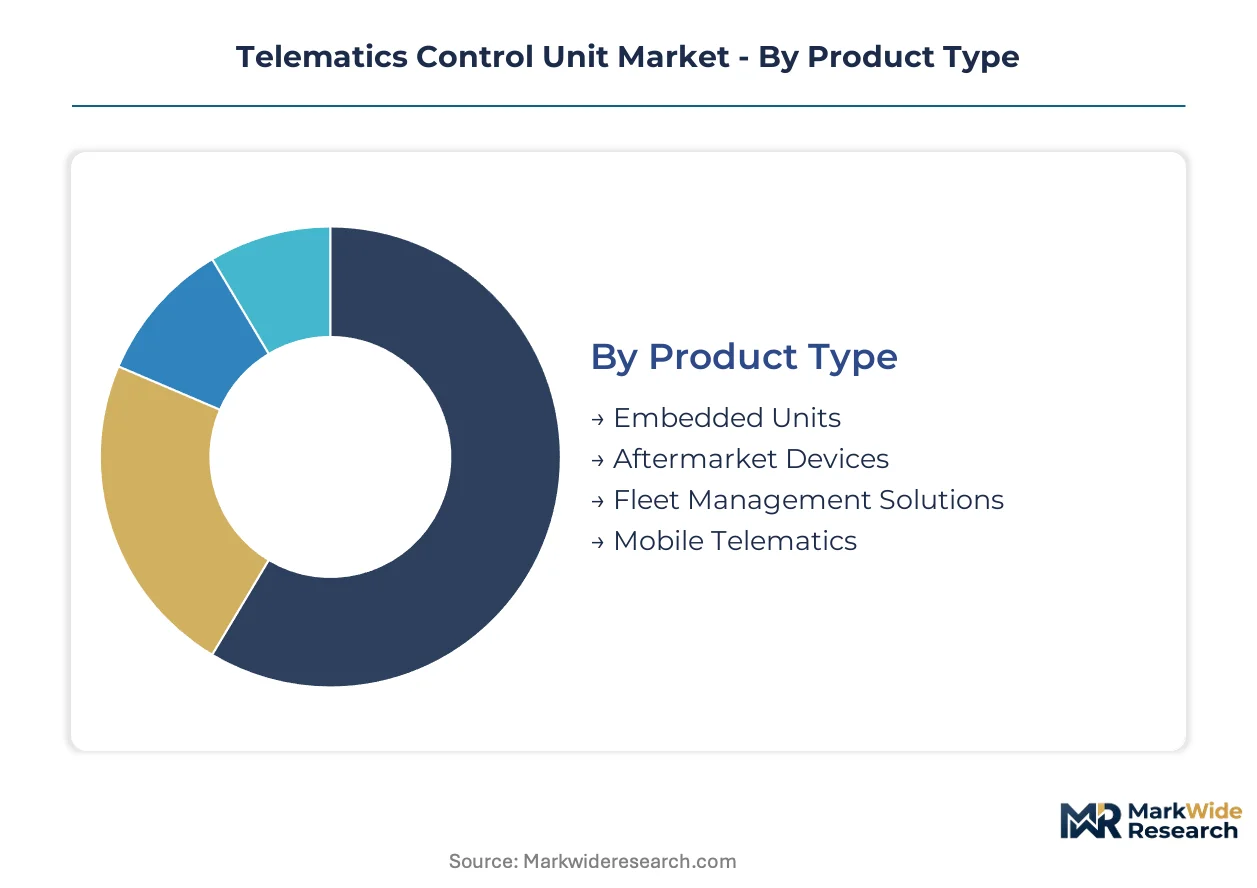
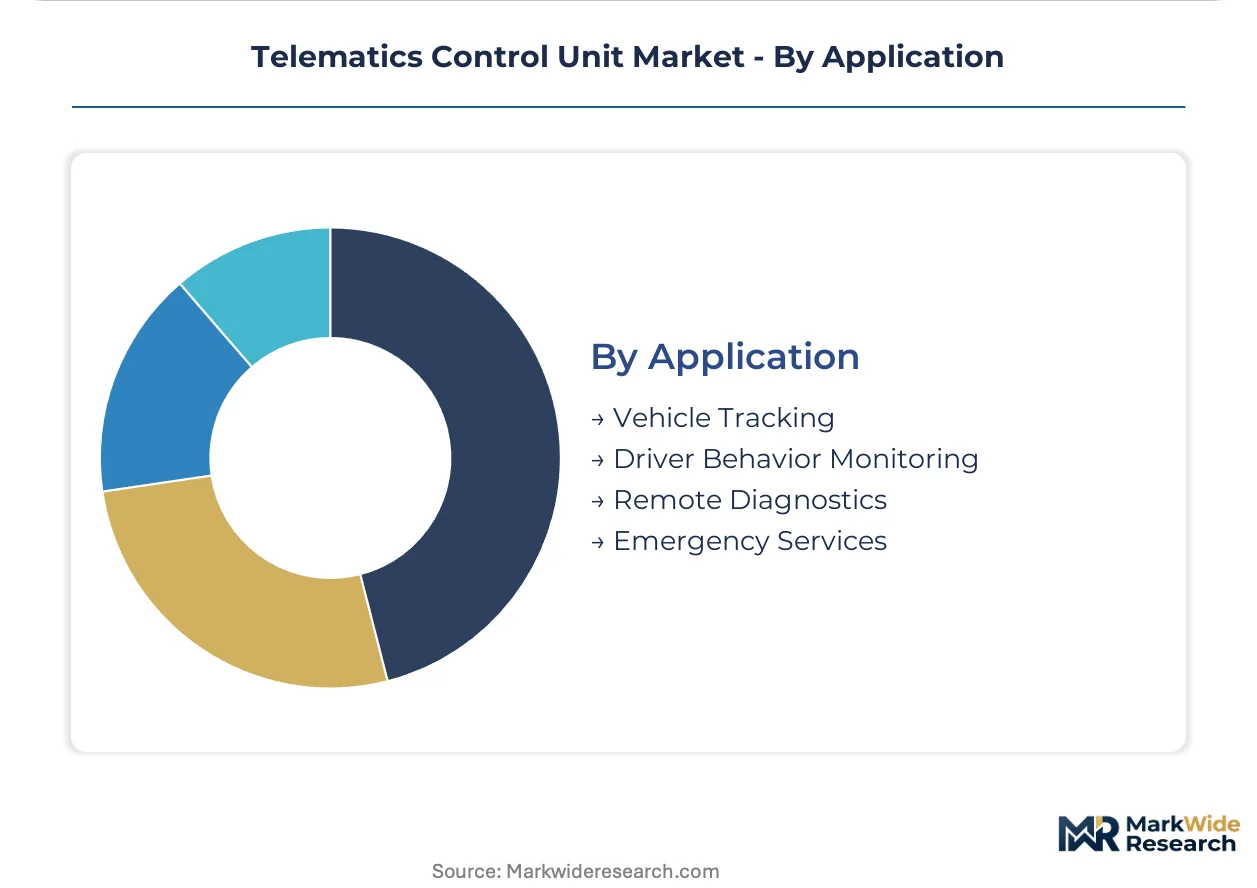
Telematics control unit segmentation reveals how hardware procurement patterns diverge between regulatory compliance and commercial optimization. Fleet operators and OEMs deploy fundamentally different sourcing strategies across product architectures, connectivity technologies, and end-use applications.
Product Type:
Replacement cycles vary sharply across installation methods, with factory-embedded systems tied to vehicle platform lifecycles and aftermarket devices tracking independent refresh schedules.
- Embedded Units:Factory-integrated modules with automotive-grade temperature tolerances and CAN bus interfaces. OEMs in Germany and the United States install these to satisfy ECall mandates and NHTSA safety frameworks, locking in seven-to-ten-year hardware lifecycles.
- Fleet Management Solutions:Bundled hardware-software platforms combining predictive maintenance algorithms with real-time visibility dashboards. Logistics operators with ten-thousand-plus unit fleets in the United States negotiate direct carrier relationships, bypassing OEM subscription markups.
- Aftermarket Devices:Retrofit modules for legacy vehicle compatibility.
- Mobile Telematics:Smartphone-dependent solutions for cost-sensitive individual consumers.
Embedded Units sits at the top of the volume ranking, with Fleet Management Solutions climbing the fastest.
Technology:
Cost tiers stratify sharply by connectivity infrastructure, with cellular modules commanding premium positioning against satellite alternatives.
- Cellular Connectivity:4G LTE and 5G automotive-grade modems displacing legacy 2G implementations. Telecommunications operators in Germany and China are sunsetting older network generations, forcing module refresh cycles.
- GPS Tracking:Multi-constellation receivers processing location data through ARM-based processors. Fleet operators across commercial vehicle segments demand sub-meter accuracy for geofencing compliance.
- Satellite Communication:Backup connectivity for remote territory coverage.
- Short-Range Communication:C-V2X and DSRC protocols for vehicle-to-infrastructure messaging.
Cellular Connectivity captures the dominant revenue share, while C-V2X-enabled Short-Range Communication is expanding most quickly.
End User:
Customer type determines margin structure, with concentrated OEM procurement contrasting against fragmented insurance channel development.
- OEMs:Vehicle manufacturers integrating telematics hardware during assembly. German and Chinese OEMs face MIIT connected vehicle standards and EU AI Act data governance requirements.
- Fleet Operators:Logistics companies unbundling hardware from connectivity contracts. Large United States operators negotiate volume-based cellular subscriptions directly.
- Insurance Companies:Usage-based policy programs monetizing driver behavior data.
- Individual Consumers:Retail purchasers of aftermarket safety and tracking solutions.
OEMs dominate absolute unit procurement, with Insurance Companies representing the steepest expansion trajectory.
Application:
Maturity levels diverge by functional complexity, with basic vehicle tracking commoditizing while biometric monitoring commands technical premiums.
- Vehicle Tracking:Core location monitoring for fleet visibility and theft recovery. German commercial operators deploy this as baseline compliance infrastructure.
- Driver Behavior Monitoring:CAN bus data combined with cabin cameras for fatigue detection. United States insurance programs use this for risk-adjusted premium calculation.
- Remote Diagnostics:Engine parameter monitoring for predictive maintenance scheduling.
- Emergency Services:Automatic crash notification systems mandated by ECall regulations.
Vehicle Tracking holds the largest installed base, with Driver Behavior Monitoring gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where telematics hardware production concentrates, with OEMs migrating module sourcing toward jurisdictions offering faster certification timelines and localized incentive structures. The cost-of-compliance gap between European type-approval and United States NHTSA validation cycles creates procurement advantages for suppliers operating across multiple regulatory domains.
United States
NHTSA safety validation protocols extend hardware approval cycles by fourteen to eighteen months, compelling OEMs to front-load certification investments. Fleet operators with ten-thousand-plus unit scales negotiate direct cellular carrier relationships, bypassing manufacturer subscription markups. Michigan and Ohio anchor automotive electronics manufacturing clusters where tier-one suppliers co-locate with OEM assembly plants.
Germany
ECall mandates and EU AI Act data governance requirements drive factory-installed embedded unit procurement. Stuttgart-based electronics operations sustain manufacturing scale through integrated supply relationships with domestic OEMs. Bavaria concentrates firmware engineering talent for multi-protocol stack development combining C-V2X, GPS, and cellular modem integration.
China
MIIT connected vehicle standards mandate V2X capabilities as prerequisites for new energy vehicle subsidies, accelerating C-V2X chipset qualification timelines. Domestic OEMs prioritize Chinese certification sequences over European or North American approval pathways. Yangtze River Delta electronics clusters dominate automotive-grade cellular module production for both domestic consumption and export markets.
India
PLI scheme incentives for domestic OEM expansion generate demand for localized telematics module sourcing. Maharashtra and Gujarat host emerging electronics manufacturing services clusters targeting automotive tier-one procurement. BIS certification requirements for automotive electronics create compliance barriers that favor established suppliers with existing testing infrastructure.
Japan
METI industrial policy supports connected vehicle deployment through standardized V2X communication frameworks. Tier-one suppliers leverage domestic semiconductor packaging capabilities for automotive-grade microcontroller integration. Kanto region electronics clusters maintain precision manufacturing competencies for GPS receiver and cellular modem assembly.
Telematics Control Unit Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with embedded unit procurement favoring vertically integrated tier-one suppliers while fleet management solutions attract software-centric challengers. Market structure concentrates around automotive electronics conglomerates with existing OEM supply relationships, though cellular modem specialists capture margin pools in connectivity hardware. Three archetypes dominate: integrated automotive electronics conglomerates, cellular communications module specialists, and fleet software platform operators. Competitive moves center on software-defined radio consolidation reducing regional SKU complexity and direct telecommunications carrier partnerships disintermediating OEM subscription bundles.
Among German automotive electronics conglomerates, Continental AG and Robert Bosch GmbH occupy positions exemplifying integrated tier-one supply architectures, while Denso Corporation anchors Asian supply relationships through its Japanese manufacturing base. These three entities represent the scale-driven end of hardware procurement, with their geographic distribution across Stuttgart, Munich, and Aichi Prefecture reflecting regional production gravity in automotive electronics.
| Leading Market Players |
|---|
| Continental AG |
| Marelli Holdings |
| LG Electronics |
| Visteon Corporation |
| Valeo |
| Harman International |
| Denso Corporation |
| Ficosa International |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
OEM procurement concentration in Germany and the United States anchors contract-based long-term offtake structures, with volume scale determining tier placement and cellular subscription bundling shaping total cost of ownership calculations.
Pricing Analysis
Distributor margins on aftermarket devices compress as fleet operators negotiate direct carrier relationships, bypassing traditional markup layers. Pricing stratifies across automotive-grade certification tiers, with ECall-mandated embedded units commanding premiums over retrofit alternatives. Cost compression in commercial vehicle segments intensifies as logistics operators unbundle hardware from connectivity contracts. Insurance companies demonstrate lowest price sensitivity, absorbing biometric monitoring premiums for usage-based policy differentiation.
Supply Chain Analysis
Freight costs from Taiwan and South Korea to German and United States assembly plants escalate as semiconductor foundry concentration strains just-in-time delivery windows. ARM-based automotive microcontrollers draw from concentrated wafer capacity, while cellular modems and GPS receivers rest on Asian electronics manufacturing clusters. Single-source vulnerability in Taiwan semiconductor packaging creates exposure to regional disruption. Distribution runs through tier-one supplier networks co-located with OEM assembly plants in Stuttgart, Michigan, and Aichi Prefecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telematics control unit market compounds as a regulatory mandate market, with ECall and comparable automatic crash notification frameworks across the European Union, United States, and China institutionalizing embedded hardware demand.
For Market Incumbents: Deploy software-defined radio consolidation to compress regional SKU complexity and extend platform lifecycle coverage. Deepen backward integration into automotive-grade cellular modem sourcing to defend against allocation constraints from Taiwan and South Korea foundries. Prioritize firmware engineering talent acquisition for multi-protocol stack development combining C-V2X, GPS, and 5G integration. For New Entrants and Emerging Players: Enter via usage-based insurance channels, where driver behavior data monetization programs create procurement entry points outside OEM supply relationships. Target Indian domestic OEM expansion under PLI scheme incentives, where localized module sourcing requirements favor new supplier qualification. Position biometric monitoring convergence offerings as hardware attachment points for fatigue detection systems. For Investors and Strategic Acquirers: Automotive electronics conglomerates with existing OEM supply relationships are the most active acquirers in this space, consolidating cellular modem specialists and fleet software platform operators. Long-term viability hinges on software-defined vehicle architecture alignment and direct telecommunications carrier partnership models. Monitor fleet procurement department unbundling trends as inflection indicators for margin pool redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Consolidation | Reduces inventory carrying costs while extending platform coverage across 4G and 5G spectrum allocations. |
| Direct Carrier Partnership Formation | Disintermediates OEM subscription markups for fleet operators exceeding ten thousand units. |
| C-V2X Chipset Qualification Acceleration | Maintains MIIT subsidy eligibility for Chinese new energy vehicle programs. |
| Firmware Engineering Talent Acquisition | Addresses scarcity in embedded systems capability for multi-protocol integration. |
| Localized Module Sourcing Expansion | Captures PLI scheme incentives in Indian automotive electronics manufacturing clusters. |
Study Parameters
Multiple input streams — OEM platform engineering interviews, tier-one supplier procurement discussions, fleet operator technology assessments, and cellular carrier partnership evaluations — were reconciled against vehicle production databases, regulatory filing records, and telecommunications infrastructure deployment reports. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions across embedded, aftermarket, and fleet management solution categories.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including installation method, connectivity technology, end-user archetype, and application function. CAGRs derived from fitted growth curves incorporating ECall mandate phase-in schedules, 5G network sunset timelines, and fleet management software adoption curves. Industry-specific inputs encompassed NHTSA validation protocol durations, MIIT connected vehicle standard compliance windows, and EU AI Act data governance implementation trajectories.
Inputs from OEM production planning systems and telecommunications carrier subscription databases were available through the study window; gaps in aftermarket device channel flow data introduce uncertainty bands around retrofit segment estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and semiconductor foundry capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market