
 Cellulose Powder Market | 2026-2036
Cellulose Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Powder Market Intelligence
Aftermarket excipient customization revenue is rewriting profit distribution across the cellulose powder value chain. J. Rettenmaier & Söhne GmbH + Co KG leverages its wood-pulp backward integration to control raw material quality from forestry through pharmaceutical-grade refinement. Roquette Frères anchors its position through plant-based cellulose sourcing that appeals to clean-label pharmaceutical and food clients. Sigachi Industries Limited competes on microcrystalline cellulose specialization for high-volume tablet manufacturing in Asian markets.
Cellulose powder consists of mechanically or chemically processed plant-derived cellulose fibers, typically 20-200 microns in particle size, functioning as binders, disintegrants, and flow agents in solid dosage forms and processed foods. Microcrystalline cellulose dominates pharmaceutical applications due to its compressibility and inertness, while nanocellulose represents the fastest-expanding product type as barrier films and rheology modifiers gain traction in cosmetics and coatings. Pharmaceutical-grade material commands premium positioning over industrial-grade supply, reflecting the cost of compliance with pharmacopeial monographs and sterility assurance.
EMA's excipient risk assessment guidelines and FDA's IPEC-PQG GMP standards shape supplier qualification burdens, pushing smaller cellulose processors toward third-party certification or exit. REACH registration requirements for novel nanocellulose variants add toxicology testing costs that favor established European and North American producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs, as divergence in particle size and moisture specifications threatens to fragment supply strategies across export markets.
Market Dynamics
Pharmaceutical-grade cellulose powder supply chains are consolidating around backward-integrated wood-pulp processors capable of meeting tightening pharmacopeial purity standards across multiple jurisdictions simultaneously.
Growth Catalysts
- Oral solid dosage expansion:Generic drug manufacturers in India and Germany are scaling tablet production, driving excipient volume requirements for binders and disintegrants.
- EMA excipient risk assessment guidelines:Regulatory clarity on supplier qualification is accelerating formal procurement relationships with certified cellulose processors.
- Nanocellulose barrier films:Cosmetics formulators are adopting cellulose-derived rheology modifiers for sustainable packaging solutions.
Market Restraints
- Softwood pulp price volatility:Input costs for pharmaceutical-grade cellulose fluctuate with Nordic forestry harvest cycles and energy-intensive chemical processing.
- REACH registration burdens:Novel nanocellulose variants require extensive toxicology dossiers that smaller European processors cannot fund.
- Starch-based substitutes:Modified starches compete in food applications where compressibility requirements are less stringent.
Strategic Opportunities
- Clean-label food penetration:Plant-derived cellulose appeals to European consumers rejecting synthetic additives in processed foods.
- Indian contract manufacturing:CDMO expansion in Hyderabad and Ahmedabad creates localized excipient demand requiring GMP-certified supply.
- Pharmacopeial harmonization:Convergence between USP, EP, and JP monographs would enable single-specification exports across major markets.
Industry Challenges
- Analytical chemistry talent scarcity:Particle size distribution and moisture content testing require specialized technicians that cellulose processors struggle to recruit.
- Sterility assurance capex:Pharmaceutical-grade production demands dedicated cleanroom facilities and isolator technology.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and CDSCO approvals create extended product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Powder Market |
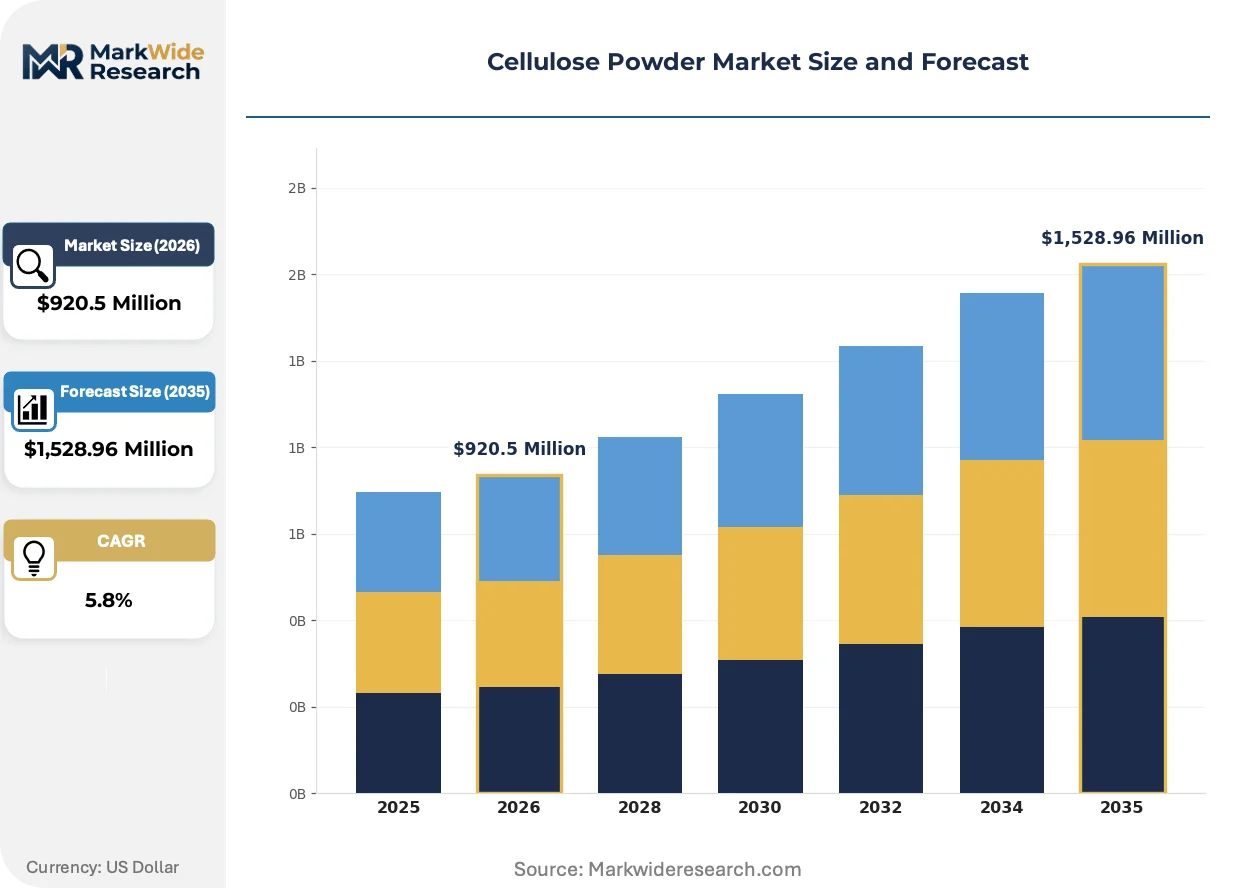
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,528.96 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline, Nanocellulose, Cellulose Acetate, Filter Paper Application: Food Additives, Pharmaceuticals, Cosmetics, Paints Grade: High Purity, Industrial Grade, Food Grade, Pharmaceutical Grade End User: Food Industry, Healthcare Sector, Personal Care, Construction |
| Companies Covered | J. Rettenmaier & Söhne GmbH + Co KG, Asahi Kasei Corporation, Roquette Frères, Merck Group, Sigachi Industries Limited, Ingredion Incorporated, Ankit Pulps and Boards Pvt. Ltd., DFE Pharma, Accent Microcell Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Powder Market Strategic Shifts & Innovations
Process analytical technology and real-time release testing are compressing quality verification cycles, while sustainability mandates reshape raw material sourcing priorities across the cellulose value chain.
Continuous manufacturing platforms are digitizing quality control in cellulose powder production. Pharmaceutical tablet manufacturers are adopting PAT-enabled direct compression lines that demand excipients with tighter particle size distributions. This technology is digitizing batch record-keeping and enabling real-time release decisions that shorten production cycles.
REACH authorization requirements for novel nanomaterials are tightening toxicology data obligations across European cellulose processors. The regulation forces investment in dedicated regulatory affairs capacity or third-party testing partnerships. Nanocellulose developers in Germany and Scandinavia are responding by pre-submitting registration dossiers before commercial scale-up.
Direct supplier relationships are displacing traditional distributor intermediaries in pharmaceutical excipient procurement. Large generic manufacturers are negotiating long-term offtake agreements with cellulose processors for volume certainty. This pattern is most pronounced in India, where CDMOs seek captive supply arrangements to secure FDA-audited material streams.
Cellulose Powder Market Segmentation
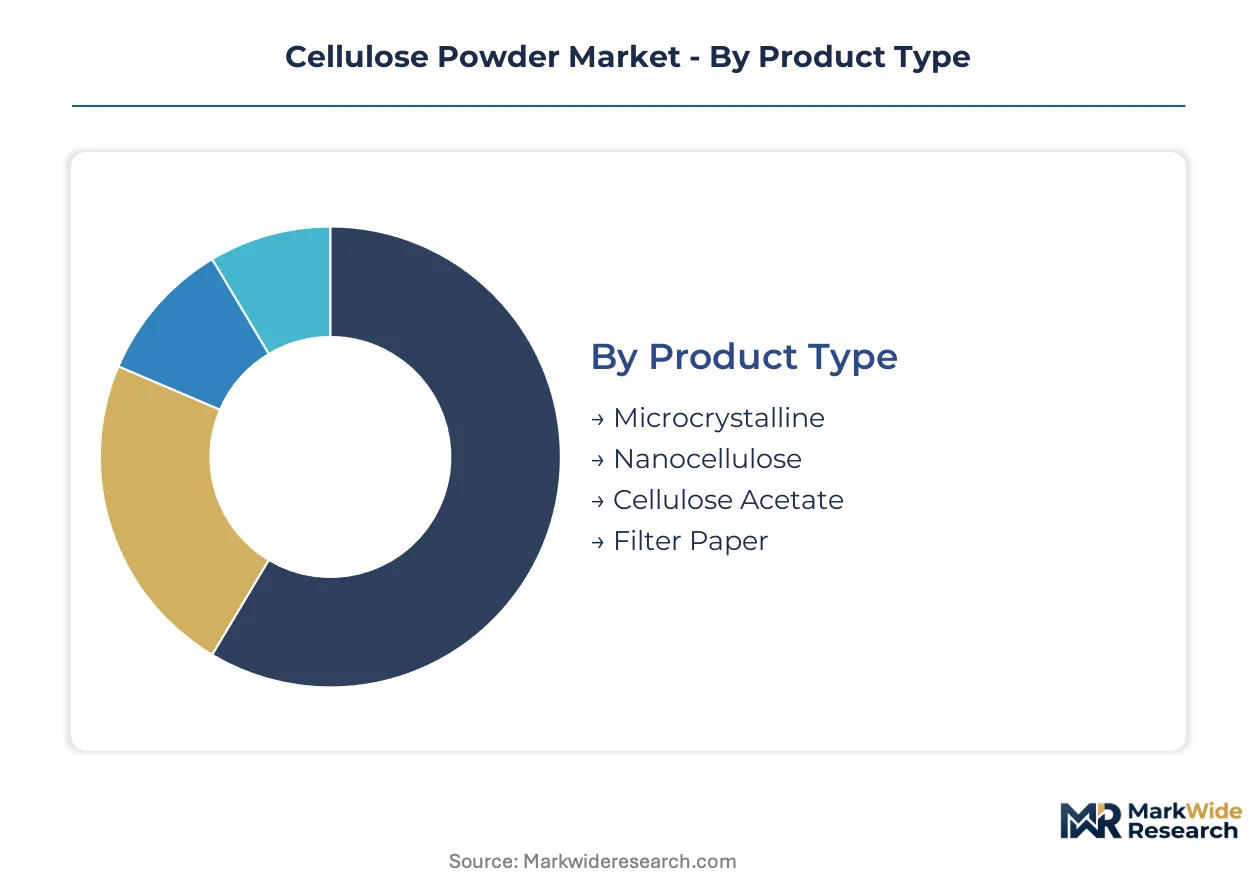
Cellulose powder segmentation reveals how functional specifications and compliance tiers fragment procurement strategies across pharmaceutical, food, and industrial channels. Product chemistry, purity grades, and end-use certification requirements create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
Mature mechanical processing technologies dominate commercial volumes, while emerging nanoscale refinement methods capture premium positioning in specialty applications.
- Microcrystalline:Depolymerized wood pulp refined through acid hydrolysis yields particles with controlled compressibility and flow properties. Tablet manufacturers in India and Germany specify this grade for high-speed direct compression lines, with FDA-audited supply chains commanding price premiums over industrial alternatives.
- Nanocellulose:Cellulose fibrils or crystals under 100 nanometers deliver exceptional barrier properties and rheology modification. Cosmetics formulators in Scandinavia and Germany adopt nanocellulose for sustainable packaging films, though REACH registration costs constrain smaller European processors from commercial scale-up.
- Cellulose Acetate:Esterified cellulose derivative serving filtration and specialty coating applications where thermal stability matters.
- Filter Paper:Unrefined or lightly processed cellulose matrices for laboratory and industrial separation processes.
Microcrystalline cellulose retains volume leadership; nanocellulose holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity food additives from pharmaceutical excipients where compliance documentation drives procurement decisions.
- Food Additives:Anti-caking agents, thickeners, and stabilizers derived from plant fiber. European clean-label regulations accelerate substitution of synthetic additives with cellulose-based alternatives in processed meat and bakery applications.
- Pharmaceuticals:Binders, disintegrants, and diluents for oral solid dosage forms. Generic drug manufacturers in Hyderabad and Ahmedabad negotiate long-term offtake agreements with GMP-certified processors to secure FDA-audited material streams.
- Cosmetics:Rheology modifiers and microbead replacements in skincare formulations.
- Paints:Thickeners and stabilizers for water-based coating systems.
Pharmaceutical applications command the highest compliance premiums; food additive volumes expand most quickly through clean-label substitution.
Grade:
Customer type stratification creates four distinct certification ladders with escalating analytical and documentation requirements.
- Pharmaceutical Grade:Material meeting USP, EP, and JP monographs with validated sterility assurance and particle size distribution controls. CDSCO-registered Indian facilities and FDA-inspected European plants dominate supply, with dedicated cleanroom infrastructure creating capital barriers to entry.
- High Purity:Refined cellulose for electronics and specialty chemical applications requiring low metal content and controlled moisture specifications.
- Food Grade:FSSAI and EFSA-compliant material for direct food contact, with allergen and GMO documentation increasingly required by European retailers.
- Industrial Grade:Unrefined or standard-processed cellulose for construction, papermaking, and non-critical applications.
Pharmaceutical grade captures the steepest margin expansion; industrial grade retains baseline volume throughput.
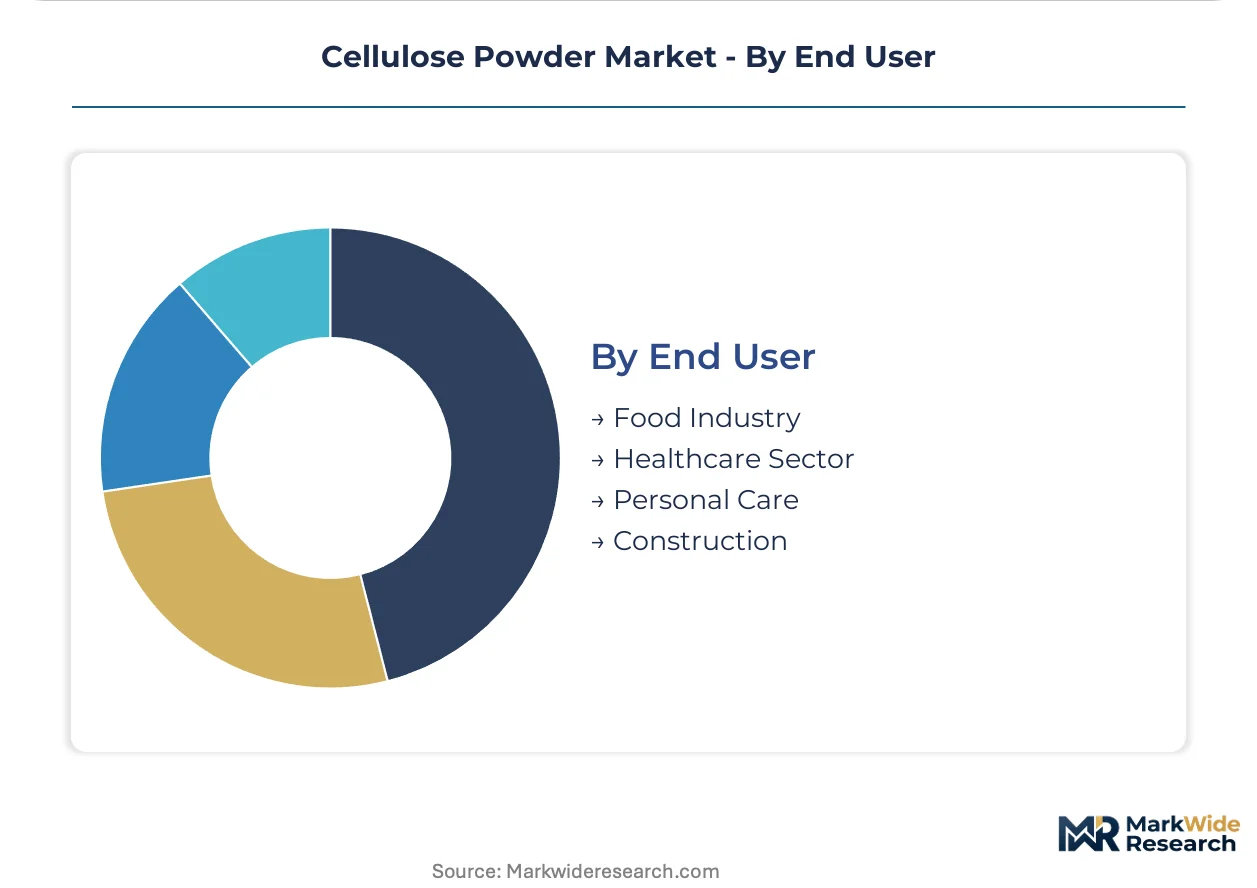
End User:
Supply concentration patterns differ sharply between regulated healthcare channels and fragmented construction applications.
- Healthcare Sector:Hospitals, clinics, and pharmaceutical manufacturers consuming excipients and medical-grade cellulose derivatives. EMA excipient risk assessment guidelines accelerate formal procurement relationships with certified processors capable of multi-jurisdiction pharmacopeial compliance.
- Food Industry:Processed food manufacturers and ingredient blenders. German and Indian contract manufacturers drive localized demand for GMP-certified cellulose as CDMO expansion concentrates in both markets.
- Personal Care:Cosmetics and hygiene product formulators seeking plant-derived alternatives to synthetic polymers.
- Construction:Cement and mortar additive applications where cellulose ethers modify water retention and workability.
Healthcare sector procurement concentrates around audited suppliers; food industry volumes expand most quickly through clean-label penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in India and Germany absorb price premiums for GMP-certified cellulose without volume elasticity, while food-grade purchasers in Brazil and Mexico exhibit sharp substitution toward starch alternatives when pulp input costs spike.
Germany
EMA excipient risk assessment guidelines drive formal procurement relationships with certified cellulose processors. REACH authorization requirements for nanocellulose variants force toxicology pre-submissions before commercial scale-up. J. Rettenmaier & Söhne leverages wood-pulp backward integration from forestry through pharmaceutical-grade refinement in Rosenberg.
India
CDSCO-registered facilities in Hyderabad and Ahmedabad negotiate long-term offtake agreements with generic drug manufacturers scaling tablet production. FSSAI compliance documentation for food-grade cellulose tightens as clean-label processed food penetration accelerates. Sigachi Industries anchors microcrystalline cellulose specialization for high-volume pharmaceutical manufacturing in Telangana.
United States
FDA IPEC-PQG GMP standards shape supplier qualification burdens that push smaller processors toward third-party certification or market exit. EPA oversight of wood-pulp processing emissions elevates capital requirements for chemical refinement stages. Roquette Frères positions plant-based cellulose sourcing to appeal clean-label pharmaceutical and food clients.
China
NMPA pharmacopeial harmonization pressures create extended product launch timelines for multi-jurisdiction cellulose exporters. MIIT industrial standards for nanocellulose production quality reshape domestic competitive positioning. Asahi Kasei Corporation maintains regional supply relationships for specialty cellulose derivatives serving electronics and filtration applications.
Brazil
ANVISA pharmaceutical excipient registration requirements concentrate import demand around pre-qualified European and North American suppliers. Modified starches from domestic cassava processing compete aggressively in food applications where compressibility standards remain permissive. Ingredion Incorporated leverages regional starch expertise to defend position against cellulose penetration in processed meat and bakery segments.
Cellulose Powder Market Key Industry Players
Backward-integrated wood-pulp processors and plant-based specialty suppliers split the market into distinct certification tiers. The vendor base concentrates around European and Asian facilities capable of simultaneous USP, EP, and JP pharmacopeial compliance. Three archetypes dominate: forestry-integrated refiners with captive pulp supply, pharmaceutical-grade specialists with dedicated cleanroom infrastructure, and diversified ingredient houses with cross-sector cellulose portfolios. Capacity expansion and strategic partnerships constitute the primary competitive vectors as CDMOs seek captive supply arrangements.
Among European forestry-integrated processors, J. Rettenmaier & Söhne GmbH + Co KG exemplifies the backward-integrated archetype with controlled raw material quality from forestry through refinement. Roquette Frères occupies a position within the plant-based specialty tier, appealing to clean-label pharmaceutical and food clients through non-wood sourcing. Sigachi Industries Limited represents the pharmaceutical-grade specialist archetype in Asian markets, with microcrystalline cellulose positioning for high-volume tablet manufacturing.
| Leading Market Players |
|---|
| J. Rettenmaier & Söhne GmbH + Co KG |
| Asahi Kasei Corporation |
| Roquette Frères |
| Merck Group |
| Sigachi Industries Limited |
| Ingredion Incorporated |
| Ankit Pulps and Boards Pvt. Ltd. |
| DFE Pharma |
| Accent Microcell Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
REACH registration burdens for novel nanocellulose variants determine both the three-tier pricing structure across pharmaceutical, food, and industrial grades and the geographic consolidation of qualified suppliers. Nordic softwood pulp volatility feeds directly into margin compression for processors lacking backward integration into forestry assets.
Pricing Analysis
Aftermarket excipient customization revenue drives lifetime value through multi-year technical service agreements. Pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade tiers with USP/EP/JP certification commanding substantial premiums over FSSAI-compliant material. Cost compression in industrial-grade supply is intensifying because modified starches from domestic cassava processing compete aggressively in food applications. Generic drug manufacturers in India exhibit the sharpest price sensitivity, while European pharmaceutical buyers absorb premiums without volume elasticity.
Supply Chain Analysis
Tariff exposure between European Union and United Kingdom markets dominates supply chain risk for cellulose processors serving dual jurisdictions post-Brexit. Manufacturing concentrates in Germany, India, and the United States with qualified cleanroom infrastructure. Production draws from Nordic softwood pulp, South American eucalyptus fiber, and Asian cotton linters as primary cellulose feedstocks. Single-source vulnerability persists for pharmaceutical-grade material where FDA-audited facilities number fewer than twenty globally. Distribution runs through direct supplier relationships displacing traditional distributor intermediaries, particularly for CDMO offtake agreements in Hyderabad and Ahmedabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry talent scarcity constrains quality verification capacity across the cellulose powder value chain. Particle size distribution and moisture content testing require specialized technicians that processors struggle to recruit, creating bottlenecks for multi-jurisdiction certification timelines.
For Market Incumbents: Entrench market position through captive forestry assets that buffer Nordic softwood pulp price volatility and accelerate pharmacopeial harmonization investments to reduce multi-jurisdiction approval delays. Backward integration into wood-pulp processing remains the critical defensive lever against margin erosion from starch-based substitutes in food applications. For New Entrants and Emerging Players: Nanocellulose barrier film applications in Scandinavian cosmetics markets represent the most penetrable entry point given REACH pre-submission requirements that favor dedicated regulatory affairs capacity. Indian contract manufacturing clusters in Telangana and Gujarat offer localized excipient demand requiring GMP-certified supply. A go-to-market angle emphasizing plant-derived sourcing appeals to clean-label pharmaceutical and food clients. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated processors with captive pulp supply and established multi-jurisdiction pharmacopeial compliance. Long-term viability hinges on sterility assurance capex discipline and regulatory affairs capacity depth. CDSCO registration timelines for Indian facilities serve as the critical inflection indicator for geographic supply shift momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | J. Rettenmaier & Söhne's Rosenberg facility demonstrates quality control from wood-pulp through pharmaceutical-grade refinement. |
| Pharmacopeial Harmonization Investment | Convergence between USP, EP, and JP monographs would enable single-specification exports across major regulated markets. |
| Long-term Supply Agreement | Generic manufacturers in Hyderabad negotiate multi-year offtake contracts to secure FDA-audited material streams. |
| Regulatory Affairs Capacity Buildout | REACH toxicology dossiers for nanocellulose variants favor established European producers with dedicated compliance teams. |
| Clean-Label Positioning | Roquette Frères leverages plant-based cellulose sourcing to differentiate from wood-pulp competitors in pharmaceutical and food channels. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EMA excipient risk assessment guidelines, USP monograph databases, and Nordic forestry harvest cycle reports. Interviews with pharmaceutical procurement managers at Indian CDMOs, quality assurance directors at European cellulose processors, regulatory affairs leads specializing in REACH registration, and formulation scientists at generic drug manufacturers inform supply chain and pricing dynamics. Bottom-up volume modeling from tablet production statistics and top-down value reconciliation against customs trade data ensure cross-validated outputs.
Forecast inputs include oral solid dosage expansion trajectories, softwood pulp futures pricing, and CDSCO facility registration timelines across the projection horizon. Segmentation dimensions encompass product chemistry, purity grade tier, end-use certification requirements, and regional regulatory cluster. CAGRs derive from regression analysis against historical excipient consumption patterns and pharmaceutical manufacturing capacity announcements. Nanocellulose commercialization timelines and pharmacopeial harmonization progress constitute industry-specific forecast variables.
Practitioners should monitor REACH authorization rulings for novel nanomaterials and CDSCO inspection backlog clearance rates for early signals of supply constraint or regulatory acceleration. Forecasts reflect documented assumptions regarding generic drug manufacturing migration patterns and forestry harvest cycle normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Global Basic Chemicals Market