
 Sports Flooring Market | 2026-2036
Sports Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Flooring Market Analysis
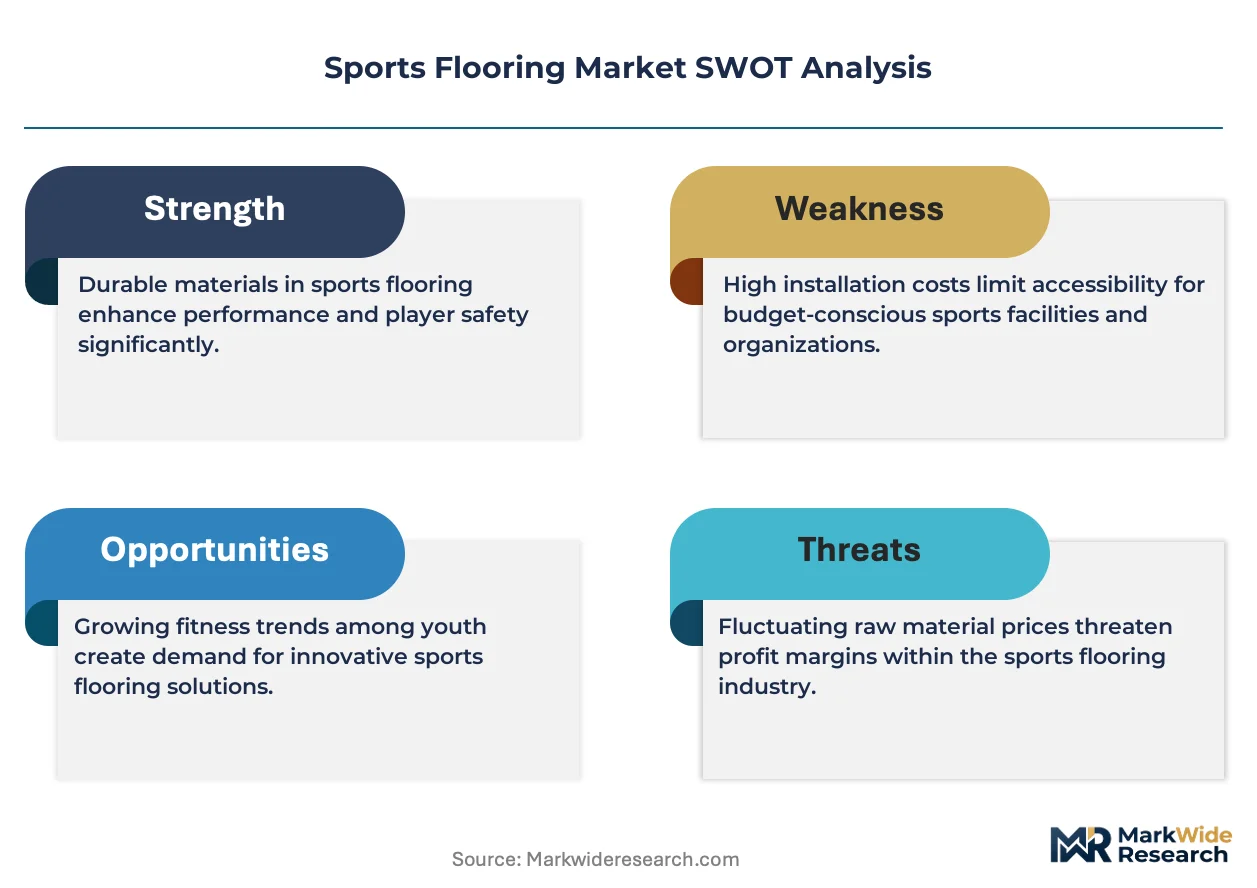
Certified flooring installer shortages across Western Europe is reorganizing project timelines and pushing facility owners toward modular systems. Tarkett SA leverages its integrated polymer compounding network to control raw material quality from resin to finished surface. Gerflor SAS anchors its position through deep specialization in resilient vinyl systems for handball and basketball courts. MONDO S.p.A. dominates the elite track and field segment with prefabricated rubber surfaces engineered to World Athletics specifications.
Sports flooring comprises engineered surface systems designed to deliver calibrated shock absorption, vertical deformation, and ball rebound characteristics measured under EN 14904 and DIN 18032-2 protocols. These surfaces protect athlete joints while ensuring consistent playability across hardwood, synthetic, and rubber compositions manufactured through calendering, extrusion, or in-situ casting processes. Artificial turf commands substantial volume in outdoor applications yet faces margin compression from recycled infill regulations, while rubber flooring captures premium pricing in weight room and high-impact zones where density and slip resistance determine specification. Vinyl flooring sustains share in multi-purpose gymnasiums where cost-per-square-meter and acoustic performance drive municipal procurement decisions.
EMA's scrutiny of isocyanate exposure in polyurethane manufacturing is elevating compliance costs for European producers while creating specification advantages for water-based adhesive systems. The EU Green Deal's embodied carbon tracking requirements are pressuring suppliers to document recycled content percentages across rubber and vinyl product lines. Facility operators and specifiers must monitor evolving biomechanical research on surface-athlete injury correlations as insurers begin incorporating flooring compliance into liability underwriting criteria.
Market Dynamics
Polyurethane binder chemistry is forcing a wholesale reformulation of European manufacturing lines as REACH and EMA restrictions on isocyanate exposure tighten occupational exposure limits. Facility operators now face specification trade-offs between shock absorption performance and VOC compliance timelines.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Suppliers documenting recycled rubber content percentages gain specification preference in German municipal procurement cycles. DIN 18032-2 compliance now intersects with carbon disclosure requirements.
- Indoor athletic participation:Multi-sport facility operators across France and the Netherlands are accelerating renovation schedules to capture rising membership demand. Basketball and handball court installations drive specification volume.
- Prefabricated rubber surfaces:World Athletics certification requirements for elite track and field facilities are consolidating demand toward factory-controlled production quality. MONDO S.p.A.'s technical specifications set de facto industry benchmarks.
Market Restraints
- Petrochemical input volatility:Polyurethane resin and synthetic rubber prices fluctuate with crude oil derivatives, compressing margins on fixed-price municipal contracts. Tarkett SA's integrated compounding network provides partial insulation.
- Installer certification scarcity:Western Europe faces acute shortages of EN 14904-certified flooring technicians, extending project timelines by 30-60 days. Modular system adoption accelerates as a workaround.
- Recycled infill regulatory friction:Emerging restrictions on crumb rubber infill for artificial turf in France and Belgium threaten outdoor segment economics. Alternative organic infills carry performance and cost penalties.
Strategic Opportunities
- Eastern European municipal underpenetration:Poland and Czech Republic sports hall infrastructure lags Western standards, creating specification upgrade potential as EU cohesion funds flow toward facility modernization.
- Water-based adhesive convergence:Combination of low-VOC polyurethane binders with pressure-sensitive adhesive backing enables faster installation and reduced curing downtime. Gerflor SAS is repositioning vinyl product lines toward this chemistry.
- Insurer liability integration:Biomechanical research on surface-athlete injury correlations is entering underwriting criteria. Flooring compliance documentation becomes a risk management service opportunity.
Industry Challenges
- Biomechanical certification complexity:Facility operators must interpret conflicting vertical deformation and shock absorption data across EN 14904, DIN 18032-2, and sport federation specifications. Procurement decisions require specialized technical staffing.
- Legacy surface remediation:Asbestos-containing tiles in 1970s-1980s installations trigger hazardous material protocols during renovation. Removal costs often exceed new flooring material expenses.
- Cross-border specification harmonization:German DIN standards, French NF norms, and emerging Eastern European requirements create product portfolio fragmentation. Manufacturers maintain parallel SKUs for adjacent markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Flooring Market |
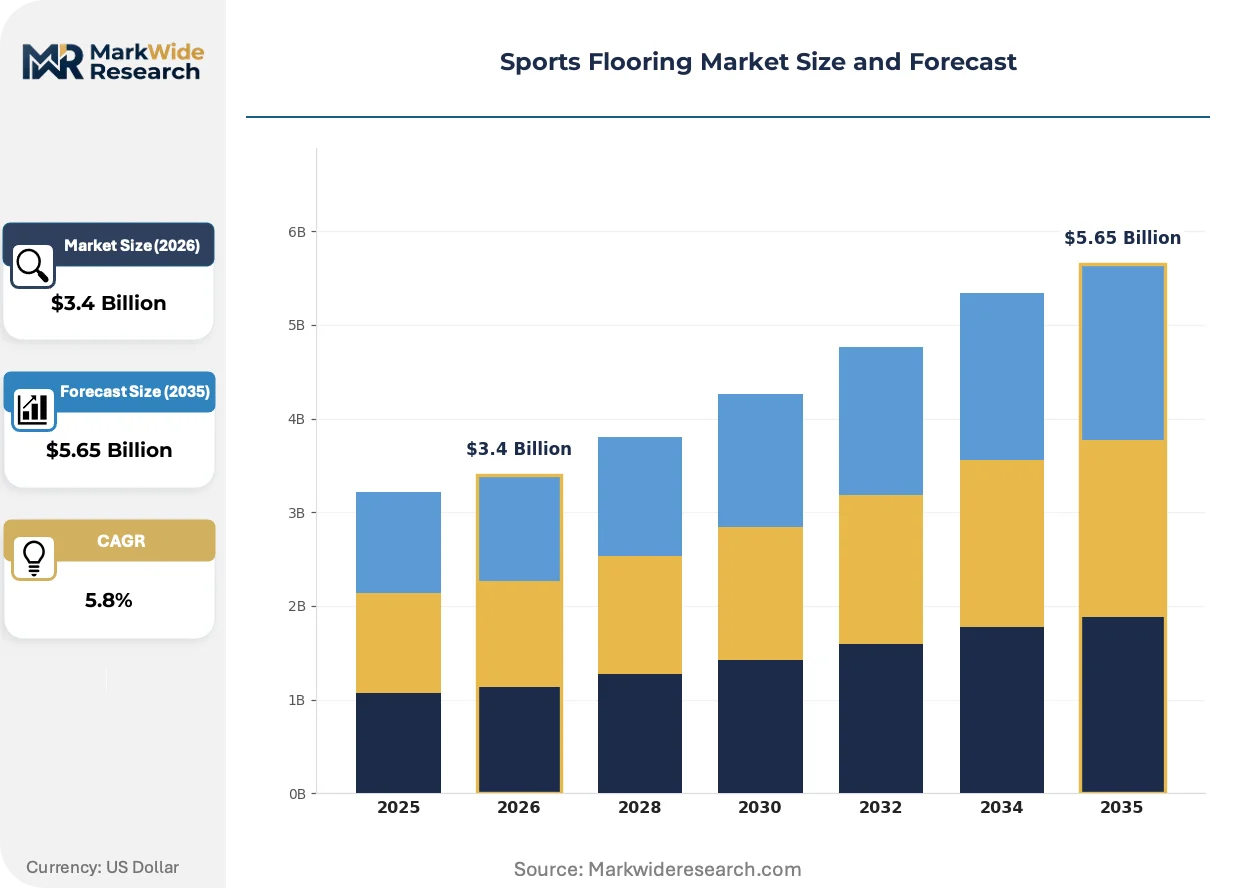
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
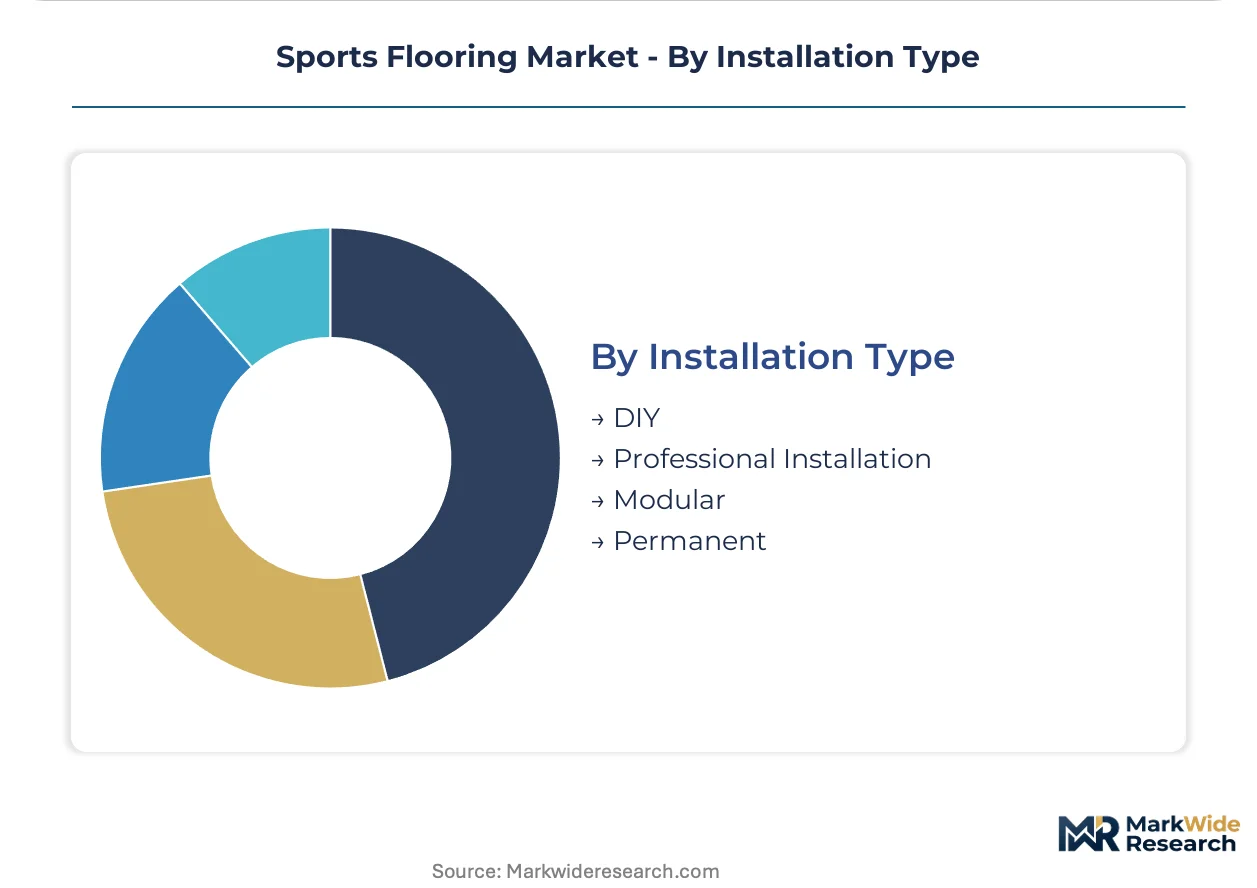
| Segmentation | Product Type: Artificial Turf, Vinyl Flooring, Rubber Flooring, Hardwood Flooring Application: Indoor Sports, Outdoor Sports, Multi-Sport Facilities, Gymnasiums End User: Schools, Fitness Centers, Sports Complexes, Professional Teams Installation Type: DIY, Professional Installation, Modular, Permanent |
| Companies Covered | Bauwerk Boen Group, Forbo, Tarkett SA, Polyflor, Junckers Industrier A/S, Gerflor SAS, EPI Group, MONDO S.p.A., Conica AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Flooring Market Emerging Trajectories
Surface chemistry and installation methodology are diverging sharply as regulatory pressure and labor scarcity force simultaneous adaptation. Three distinct vectors are reshaping competitive positioning.
Water-based polyurethane binders are fragmenting the solvent-borne installation market as EMA occupational exposure limits tighten across Belgium, France, and Germany. Municipal facility managers in Hamburg and Munich now specify low-VOC systems to accelerate occupancy timelines. The technology is fragmenting traditional contractor relationships as specialized applicators gain specification influence over generalist flooring installers.
REACH Annex XVII restrictions on isocyanate content are elevating compliance documentation burdens for in-situ casting operations. Manufacturers must now maintain batch-level exposure testing records extending back five years. Rubber flooring for weight rooms and high-impact zones faces the steepest cost adjustments as density specifications intersect with reformulation requirements.
Facility managers are unbundling installation from material supply, demanding fixed-price performance contracts that transfer subsurface preparation risk to contractors. German municipal procurement offices in Bavaria and North Rhine-Westphalia pioneered this model, which is spreading to Dutch and Austrian facility operators. The shift compresses margins for installers while rewarding manufacturers with integrated project management capabilities.
Sports Flooring Market Segmentation
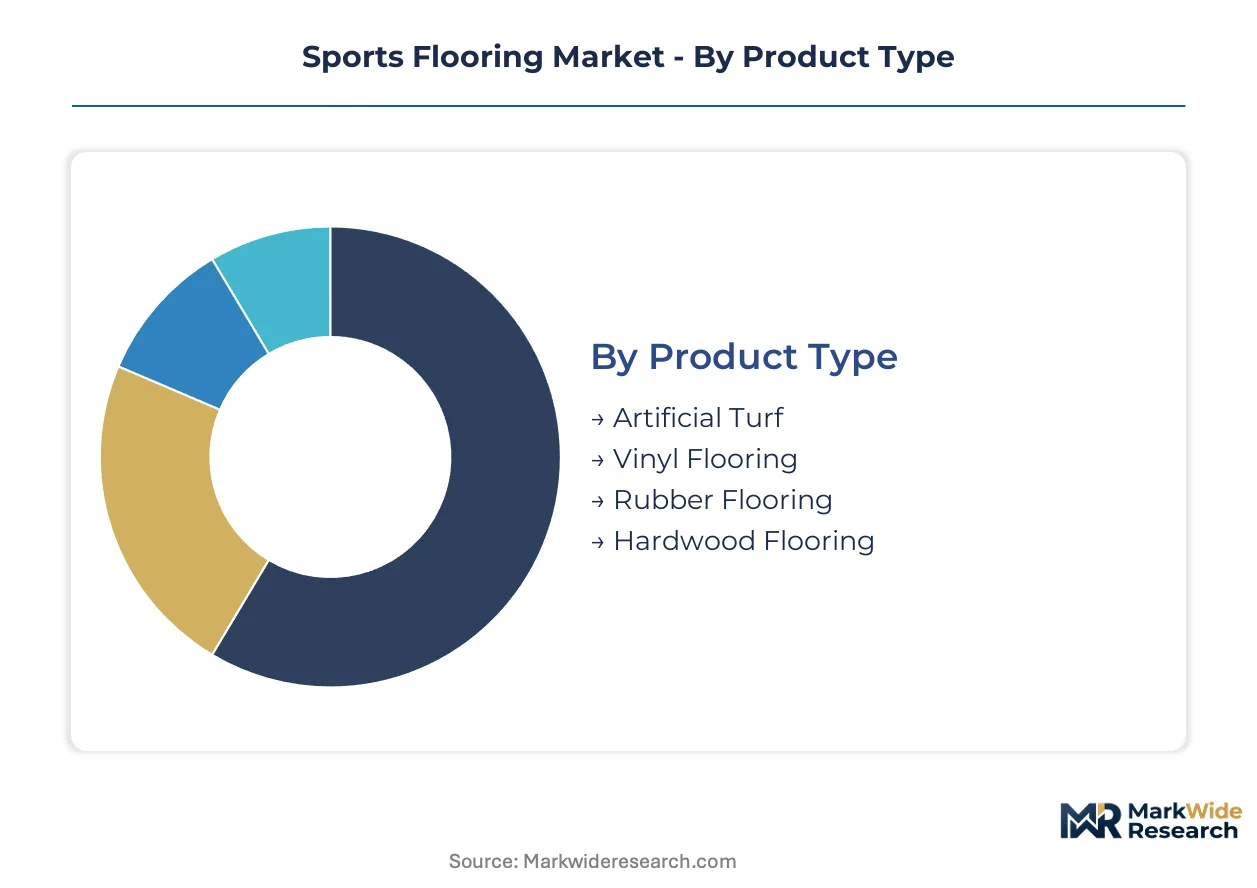
Sports flooring procurement decisions fragment across performance specifications, compliance requirements, and lifecycle cost calculations. Facility operators must reconcile athlete safety protocols with municipal budget constraints and installation timeline pressures.
Product Type:
REACH Annex XVII restrictions on isocyanate content and VOC emissions create divergent compliance burdens across material chemistries, reshaping specification preferences in German and French municipal tenders.
- Artificial Turf:Polyethylene and polypropylene fiber systems with polyurethane or latex backings dominate outdoor football and rugby pitches. French and Belgian regulators are scrutinizing crumb rubber infill composition, pressuring manufacturers toward organic alternatives that trade durability for compliance certainty.
- Vinyl Flooring:Multi-layer PVC systems with fiberglass reinforcement and polyurethane surface treatment deliver acoustic dampening and cost efficiency for multi-purpose gymnasiums. Hamburg municipal procurement offices specify low-VOC vinyl to accelerate post-installation occupancy timelines.
- Rubber Flooring:Prefabricated EPDM and SBR sheets for weight rooms and high-impact zones.
- Hardwood Flooring:Maple and beech systems for basketball courts requiring DIN 18032-2 shock absorption certification.
Established volume favors vinyl flooring; emerging adoption favors rubber flooring as biomechanical research elevates density specifications in elite training facilities.
Application:
Cost tier differentiation separates budget-constrained school renovations from premium professional installations, with specification complexity escalating alongside performance guarantees.
- Indoor Sports:Basketball, handball, and volleyball courts requiring calibrated ball rebound and vertical deformation under EN 14904 protocols. Dutch and Austrian facility operators are unbundling installation from material supply, transferring subsurface preparation risk to contractors through fixed-price performance contracts.
- Outdoor Sports:Football, rugby, and athletics tracks exposed to weathering and UV degradation. Recycled infill regulatory friction in France and Belgium threatens segment economics as alternative organic materials carry performance penalties.
- Multi-Sport Facilities:Convertible surfaces accommodating court markings for multiple disciplines.
- Gymnasiums:General-purpose recreational spaces prioritizing cost-per-square-meter and acoustic performance.
Procurement volume concentrates in indoor sports; specification complexity is climbing fastest in multi-sport facilities as operators demand convertible surface systems.
End User:
Customer type determines warranty expectations, maintenance protocols, and the balance between first-cost minimization and lifecycle durability.
- Schools:Municipal education facilities operating under constrained capital budgets with 15-20 year replacement cycles. Bavarian and North Rhine-Westphalia procurement offices pioneered fixed-price performance contracts that manufacturers with integrated project management capabilities now exploit.
- Fitness Centers:Commercial operators prioritizing rapid installation and minimal downtime. Modular rubber systems gain preference as certified installer shortages extend traditional project timelines.
- Sports Complexes:Multi-tenant facilities requiring federation-compliant surfaces.
- Professional Teams:Elite organizations demanding World Athletics or sport-specific certification with comprehensive biomechanical documentation.
Contract structure standardization favors schools; performance guarantee sophistication favors professional teams.
Installation Type:
Supply concentration in certified applicator networks is fragmenting traditional contractor relationships as specialized technicians gain specification influence.
- Professional Installation:Factory-trained crews executing in-situ casting or adhesive-bonded sheet systems with EN 14904 compliance certification. Western Europe faces acute technician shortages extending project timelines by 30-60 days.
- Modular:Prefabricated tile or plank systems with pressure-sensitive adhesive backing enabling faster deployment and reduced curing downtime. Gerflor SAS and Tarkett SA are repositioning product lines toward this chemistry to circumvent installer scarcity.
- DIY:Limited to small-scale residential or light commercial applications.
- Permanent:Traditional glued-down or poured systems with 20+ year service life expectations.
Project timeline pressure favors modular installation; durability guarantees favor permanent systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance requirements anchor European procurement specifications, with DIN 18032-2 and EN 14904 protocols serving as the de facto regulatory baseline for municipal facility tenders across the continent.
Germany
Municipal sports hall renovation cycles in Bavaria and North Rhine-Westphalia drive specification upgrades toward low-VOC polyurethane systems. The EU Green Deal's embodied carbon tracking intersects with DIN 18032-2 compliance, rewarding suppliers documenting recycled rubber content. Hamburg procurement offices now specify water-based adhesive systems to accelerate post-installation occupancy timelines.
France
Handball and basketball court installations concentrate demand in Île-de-France and Auvergne-Rhône-Alpes as multi-sport facility operators capture rising membership. ANSM scrutiny of isocyanate exposure elevates compliance costs for in-situ casting operations. Emerging restrictions on crumb rubber infill for artificial turf in northern municipalities threaten outdoor segment economics.
Netherlands
Fitness center operators in Amsterdam and Rotterdam prioritize modular rubber systems to circumvent certified installer shortages extending project timelines. Dutch facility managers pioneered unbundling installation from material supply, transferring subsurface preparation risk through fixed-price performance contracts now spreading to Austrian operators.
Belgium
EMA occupational exposure limits on isocyanate content are tightening fastest in Flanders, forcing wholesale reformulation of polyurethane binder chemistry. Brussels-area municipal tenders now require batch-level exposure testing records extending back five years. Alternative organic infills carry performance penalties as regulators scrutinize recycled rubber composition.
Poland
EU cohesion funds are flowing toward sports hall infrastructure modernization in Warsaw and Kraków, creating specification upgrade potential as Eastern European facilities lag Western standards. Polish municipal procurement offices are adopting EN 14904 protocols, opening opportunities for manufacturers with integrated project management capabilities.
Sports Flooring Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with European flooring manufacturers controlling polymer compounding networks to insulate against petrochemical input volatility. The market structure rewards backward integration into resin production and captive supply of synthetic rubber. Three archetypes dominate: integrated polymer compounders, resilient vinyl specialists, and prefabricated rubber surface engineers. Competitive moves concentrate on portfolio diversification toward water-based adhesive systems and geographic expansion into Eastern European municipal markets.
Within the integrated compounder tier, Tarkett SA and Gerflor SAS occupy positions anchored by in-house polymer networks spanning resin through finished surface production. MONDO S.p.A. exemplifies the prefabricated rubber specialist archetype, with its technical specifications setting de facto benchmarks for elite track and field certification. These three European entities represent the dominant competitive anchors as facility operators unbundle installation from material supply and procurement offices demand carbon disclosure documentation.
| Leading Market Players |
|---|
| Bauwerk Boen Group |
| Forbo |
| Tarkett SA |
| Polyflor |
| Junckers Industrier A/S |
| Gerflor SAS |
| EPI Group |
| MONDO S.p.A. |
| Conica AG |
| Others |
Supply Flow & Price Mechanics
Fixed-price performance contracts in German municipal procurement lock in supply access for manufacturers with integrated project management capabilities while compressing margins for installers absorbing subsurface preparation risk. Bavarian and North Rhine-Westphalia tenders now bundle DIN 18032-2 compliance documentation with embodied carbon disclosure requirements, creating price visibility for suppliers documenting recycled rubber content percentages.
Pricing Analysis
German specification premiums exceed Polish municipal benchmarks by substantial margins as DIN 18032-2 certification and EU Green Deal carbon tracking requirements concentrate procurement sophistication. Three-tier pricing structure across elite certification, standard municipal, and economy school renovation levels separates World Athletics-approved surfaces from EN 14904-compliant systems and basic vinyl installations. Cost compression in economy tiers intensifies because petrochemical input volatility squeezes fixed-price contracts, while professional teams exhibit least price sensitivity due to biomechanical liability exposure.
Supply Chain Analysis
Inventory buffers for polyurethane resin and synthetic rubber feedstock extend lead times by 30-60 days as Western European certified installer shortages disrupt project completion schedules. Manufacturing concentrates in Germany, France, and Italy where REACH Annex XVII compliance infrastructure anchors production quality standards. Raw material dependencies draw from crude oil derivatives, EPDM/SBR rubber compounds, and PVC resin, with commodity price volatility representing the dominant structural risk. Distribution runs through factory-trained applicator networks and specialized flooring contractors serving municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across DIN 18032-2, EN 14904, and sport federation protocols creates service-layer niches as facility operators struggle to interpret conflicting biomechanical data.
For Market Incumbents: Shield specification influence by embedding compliance documentation services into material supply contracts before insurers formalize flooring liability into underwriting criteria. Prioritize backward integration into water-based polyurethane binder production to capture margin from REACH-driven reformulation cycles. Expand captive applicator training capacity to offset certified technician scarcity extending project timelines. For New Entrants and Emerging Players: Installation risk unbundling from material supply represents the most penetrable service gap as Dutch and Austrian facility operators transfer subsurface preparation liability through fixed-price performance contracts. Target Polish municipal markets adopting EN 14904 protocols with integrated project management offerings that incumbent vinyl specialists lack. Penetrate through water-based adhesive system specialization serving Hamburg and Munich low-VOC procurement mandates. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors integrated polymer compounders with in-house resin production and carbon disclosure infrastructure. Long-term viability rests on manufacturers controlling raw material quality from compounding through finished surface certification. Acquisition focus should center on Eastern European facility modernization exposure and water-based chemistry repositioning capability. Watch for insurer liability integration into municipal procurement specifications as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Repositioning | Gerflor SAS and Tarkett SA accelerate low-VOC vinyl product line transitions to capture Hamburg and Munich municipal tenders. |
| Eastern European Expansion | EU cohesion fund flows into Warsaw and Kraków sports hall modernization create specification upgrade opportunities for integrated manufacturers. |
| Certified Installer Network Buildout | Factory-trained applicator capacity expansion addresses 30-60 day project timeline extensions plaguing Western European contractors. |
| Carbon Disclosure Documentation | Recycled rubber content tracking systems satisfy EU Green Deal procurement requirements intersecting with DIN 18032-2 compliance. |
| Insurer Partnership Development | Biomechanical injury correlation data services transform flooring compliance into risk management offerings for liability underwriting integration. |
Methodological Framework
The analysis maps polyurethane binder chemistry segments, vinyl flooring systems, rubber surfaces, and hardwood installations, each validated through municipal procurement officers, certified flooring installers, sports facility operators, and polymer compound technical directors. Primary interviews with EN 14904-certified applicators and German municipal tender specification writers combined with secondary validation from REACH Annex XVII documentation, DIN 18032-2 certification records, EMA occupational exposure filings, and customs trade data. Bottom-up project pipeline tracking across Bavaria, North Rhine-Westphalia, and Polish cohesion fund allocations triangulates against top-down petrochemical input cost modeling.
Consistency checks against EPDM and SBR rubber pricing indices, municipal construction expenditure databases, and World Athletics certification registries validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry type, installation methodology, application performance tier, and regional regulatory cluster. CAGRs derive from facility renovation cycle timing, indoor athletic participation trends, and compliance cost trajectory analysis with petrochemical volatility and installer availability as primary forecast sensitivity inputs.
Underlying assumptions cover REACH enforcement continuity, EU Green Deal procurement adoption rates, and insurer liability integration timing, with deviation risk concentrated in recycled infill regulatory bans and isocyanate exposure limit tightening. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Darts Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Sandbells Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
United States Running Gear Market