
 Global Mountain Bicycles Market | 2026-2036
Global Mountain Bicycles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mountain Bicycles Market Outlook
Carbon fiber is shifting from premium-only frames into mid-tier mountain bicycle offerings as resin-transfer molding costs decline. Trek Bicycle Corporation leverages its domestic composite manufacturing to control raw material flows. Giant Manufacturing Co. Ltd. anchors production scale across Asian assembly plants. Specialized Bicycle Components, Inc. differentiates through proprietary suspension kinematics and direct-to-consumer configuration tools.
Mountain bicycles are off-road cycling machines built with reinforced frames, knobby tires, and suspension systems absorbing terrain impacts across gradients exceeding fifteen degrees. Carbon fiber and aluminum dominate frame material selection, with titanium reserved for custom builders serving professional athletes. Full-suspension designs capture margin pools in advanced and professional rider categories where component integration commands premium pricing. Electric mountain bikes represent the fastest-expanding product type as pedal-assist regulations relax across European trail networks.
FDA oversight applies to wearable biometric sensors integrated into handlebar-mounted devices tracking rider physiology. REACH compliance in Europe restricts certain epoxy resins and surface coatings, compelling reformulation of frame finishing processes. ISO standards for bicycle safety testing govern structural integrity claims across export markets. Stakeholders must monitor how e-bike motor power classifications evolve in Germany, France, and Switzerland, as trail access permissions hinge on these thresholds and reshape addressable rider segments.
Market Dynamics
Carbon fiber resin-transfer molding cost compression is redrawing competitive boundaries between premium and mid-tier frame manufacturers, while Germany's trail-access regulations for electric mountain bikes are fragmenting rider segments by motor power classification.
Growth Catalysts
- E-MTB Regulatory Liberalization:France and Switzerland are relaxing pedal-assist power limits on alpine trail networks, expanding addressable rider populations in high-tourism mountain corridors.
- REACH-Driven Material Substitution:ECHA restrictions on legacy epoxy resins are accelerating bio-based resin adoption in frame finishing, creating first-mover advantages for compliant coating suppliers.
- Alpine Tourism Infrastructure:Austria and Italy are investing in lift-served bike parks, concentrating seasonal demand for enduro-rated full-suspension platforms.
Market Restraints
- Carbon Fiber Supply Concentration:Toray and Mitsubishi Chemical dominate aerospace-grade precursor supply, exposing frame builders to allocation risk during defense contract surges.
- F-Gas Compliance Burden:The EU F-Gas Regulation is forcing suspension manufacturers to retool damper fluid formulations, compressing R&D timelines for 2027 model year releases.
- Aluminum Price Volatility:LME aluminum contract swings above $2,600 per tonne are squeezing margin pools in entry-level hardtail categories where material cost dominates landed price.
Strategic Opportunities
- US Trail Network Expansion:Bureau of Land Management pilot programs in Utah and Colorado are opening previously restricted singletrack to Class 1 e-MTB access, creating untapped demand corridors.
- Biometric Sensor Integration:Wearable power meters and lactate threshold monitors are converging with handlebar-mounted displays, opening subscription revenue streams for training analytics platforms.
- Direct-to-Consumer Configuration Tools:Modular suspension kinematics and online frame geometry calculators are enabling build-to-order models that bypass traditional distributor markups.
Industry Challenges
- Composite Technician Scarcity:Resin-transfer molding and automated fiber placement require specialized labor pools concentrated in aerospace hubs, creating recruitment bottlenecks for frame manufacturers scaling mid-tier production.
- ISO 4210 Certification Timelines:Extended test protocols for full-suspension fatigue and impact resistance are delaying new model introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mountain Bicycles Market |
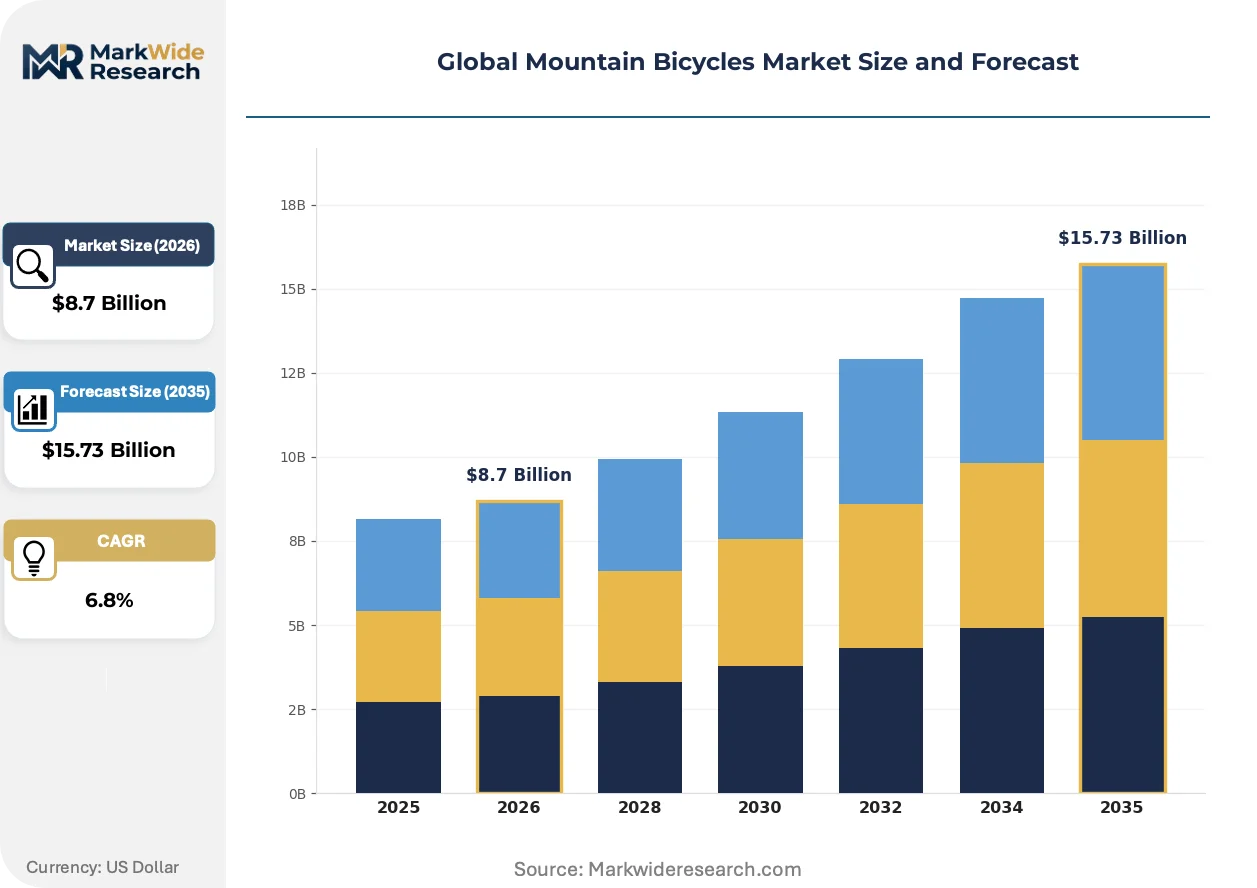
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardtail, Full-Suspension, Fat Bike, Electric Mountain Bike Frame Material: Aluminum, Carbon Fiber, Steel, Titanium Braking System: Disc Brakes, Rim Brakes, Hydraulic Brakes, Mechanical Brakes Target Audience: Beginner, Intermediate, Advanced, Professional |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co. Ltd., Specialized Bicycle Components, Inc., Cannondale Bicycle Corporation, Merida Industry Co. Ltd., Santa Cruz Bicycles, Scott Sports SA, Kona Bicycle Company, Rocky Mountain Bicycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mountain Bicycles Market Strategic Shifts
Suspension kinematics, powertrain electrification, and rider data capture are fusing into integrated platform architectures that redefine how manufacturers compete on performance customization rather than component spec sheets alone.
High-modulus carbon fiber is converging with thermoplastic resin systems in frame layup processes. Enduro racing teams in the Alps and Pacific Northwest are adopting these platforms for rapid crash replacement. This convergence is compressing repair cycle times from weeks to days, eroding the traditional advantage of aluminum durability claims in rental and fleet channels.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon-based damper fluids by 2030. Suspension manufacturers are reformulating with silicone and mineral oil alternatives, accelerating compatibility testing with legacy seal materials. German and Austrian OEMs face the steepest retooling curves given their concentration in high-performance gravity product lines.
Rider purchasing patterns are fragmenting across subscription-based component refresh programs and outright ownership models. Direct-to-consumer brands in North America and Northern Europe are unbundling after-sales service from initial purchase, partnering with independent bike shops for assembly and warranty fulfillment. This channel hybridization is most visible in Germany, where KBA e-bike motor registration requirements complicate pure digital sales fulfillment.
Global Mountain Bicycles Market Segmentation
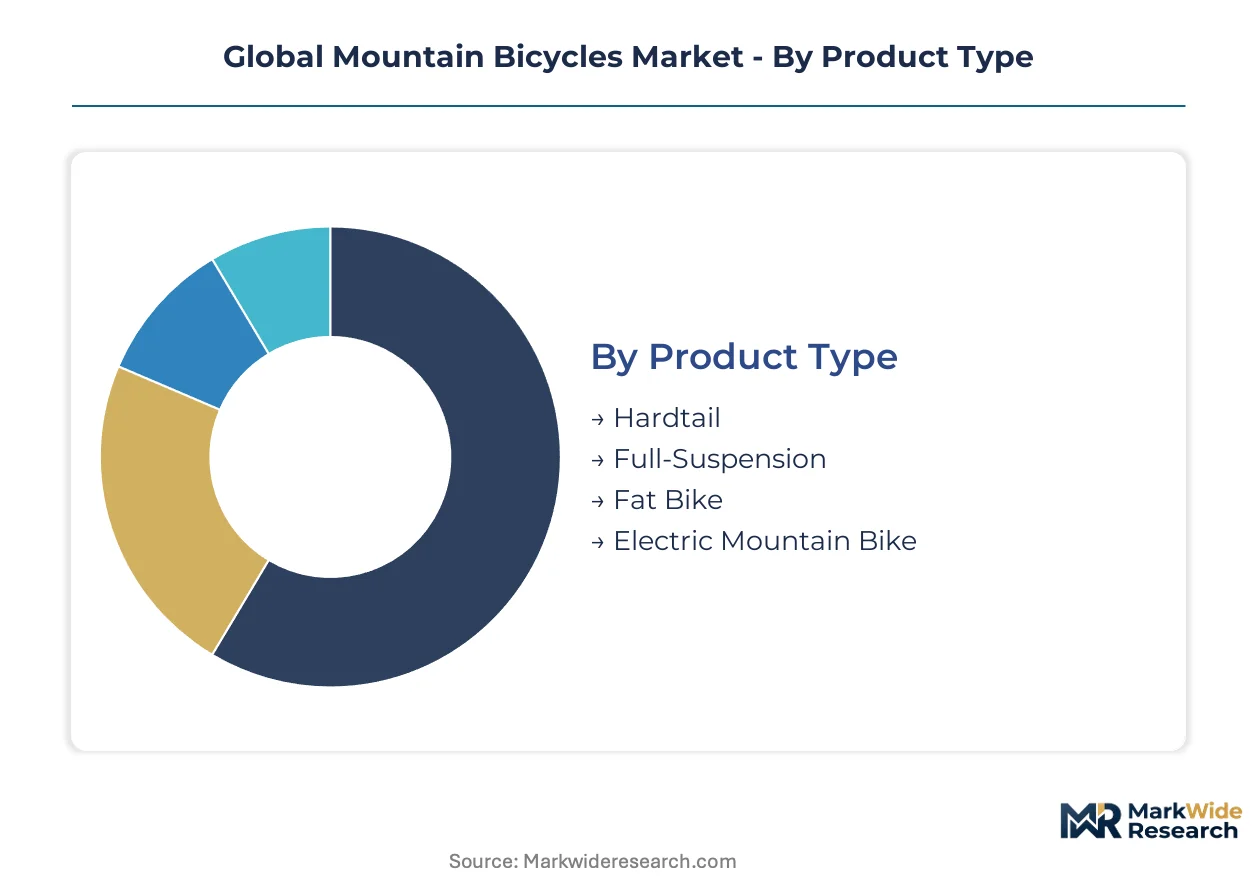
Mountain bicycle segmentation maps rider capability tiers to equipment specifications, with suspension architecture and powertrain electrification creating distinct margin pools across recreational and competitive use cases. Material selection and braking technology further stratify purchasing decisions by terrain severity and maintenance tolerance.
Product Type:
Integration depth varies sharply across this category, with electric powertrains embedding battery management and motor control systems while hardtail designs remain mechanically standalone.
- Hardtail:Front suspension only with rigid rear triangle delivers lower maintenance burden and reduced weight for cross-country racing and budget-conscious trail riders. Demand clusters in Germany's XC marathon circuits and US Midwest trail systems where climbing efficiency outweighs descending capability.
- Full-Suspension:Dual-suspension kinematics with linkage-driven rear shock absorption dominate enduro racing and alpine bike park rental fleets. Austrian and Italian lift-served destinations concentrate seasonal procurement of 150-170mm travel platforms.
- Fat Bike:Oversized tires (4.0-5.0 inch width) enable flotation across snow, sand, and wetland terrain where standard tires sink. Niche adoption persists in Scandinavian winter tourism and Canadian wilderness guiding operations.
- Electric Mountain Bike:Pedal-assist motor systems (250W-750W classifications) extend rider range and elevation gain capacity. Regulatory fragmentation across German trail access rules and Swiss alpine network permissions is reshaping motor power segmentation.
Volume placements concentrate in Hardtail; the faster expansion belongs to Electric Mountain Bike.
Frame Material:
Cost tier stratification drives material selection, with aerospace-grade carbon fiber commanding premium positioning against commodity aluminum in entry-level hardtails.
- Aluminum:6061-T6 and 7005 alloys dominate mass-market production through hydroformed tube shaping and TIG welding automation. LME price volatility above $2,600 per tonne is compressing margins in sub-$1,500 retail categories where material cost dominates landed pricing.
- Carbon Fiber:Toray T700 and T800 prepregs enable monocoque frame construction with tunable stiffness zones. Resin-transfer molding cost compression is displacing thermoset layup in mid-tier offerings previously aluminum-exclusive.
- Steel:Chromoly (4130) tubing persists in custom framebuilding and bikepacking segments prioritizing repairability and fatigue resistance over weight minimization.
- Titanium:Grade 9 (3Al-2.5V) and Grade 5 (6Al-4V) alloys serve professional athletes and bespoke builders where frame longevity justifies 3-4x cost premium over carbon.
Aluminum retains the highest unit placement; carbon fiber is climbing the fastest as RTM automation scales.
Braking System:
Application severity determines braking architecture, with gravity-rated hydraulic systems embedding heat management features absent from mechanical rim alternatives.
- Disc Brakes:Rotor-based friction systems (160-203mm diameter) deliver consistent performance in wet and muddy conditions across all mountain bike disciplines. Standard equipment on full-suspension and e-MTB platforms where rim braking surfaces are absent.
- Rim Brakes:Caliper-actuated pad contact with wheel rim persists in entry-level hardtails and vintage restoration markets. Rapid displacement by disc systems limits procurement to price-sensitive retail channels.
- Hydraulic Brakes:Sealed fluid lines with mineral oil or DOT fluid transmit force from lever to caliper, enabling single-finger modulation and heat dissipation. Mandatory specification for enduro racing and e-MTB categories where kinetic energy dissipation demands exceed mechanical system capacity.
- Mechanical Brakes:Cable-actuated disc or rim systems offer field serviceability without bleed equipment. Residual demand in remote touring and developing market contexts where specialized maintenance infrastructure is unavailable.
Disc configurations capture the majority of placements; hydraulic systems are gaining share fastest as e-MTB weight and speed classifications rise.
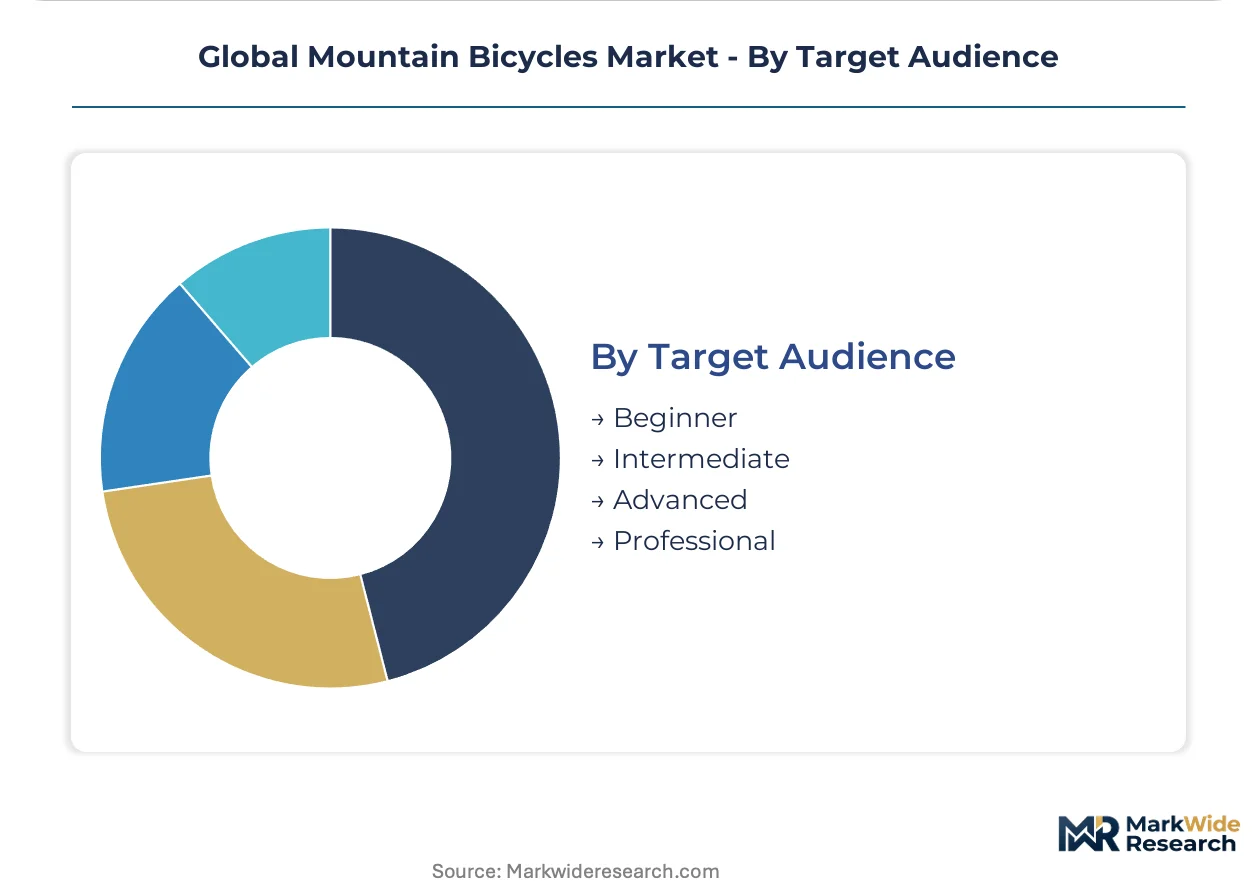
Target Audience:
Customer type segmentation aligns equipment specification to skill progression, with professional tiers demanding embedded telemetry and kinematic adjustability absent from beginner categories.
- Beginner:Riders with less than two years off-road experience prioritize durability and predictable handling over weight minimization. Hardtail aluminum frames with mechanical disc brakes dominate first-purchase decisions in German cycling club recruitment and US outdoor retailer channels.
- Intermediate:Skill development toward technical descending and jump lines drives full-suspension adoption with 120-140mm travel. Trail network expansion in Colorado and Utah is concentrating demand for versatile do-it-all platforms.
- Advanced:Competitive amateur racing and aggressive terrain riding require enduro-rated suspension (150-170mm) and carbon frame options. KBA motor registration requirements in Germany fragment e-MTB access permissions by rider certification level.
- Professional:Factory-sponsored athletes and elite competitors utilize custom geometry, telemetry-integrated suspension, and rapid prototype frames. Team partnerships with composite manufacturers in aerospace corridors accelerate repair cycle times from weeks to days.
Intermediate riders generate the highest absolute volume; the professional tier shows the steepest expansion trajectory as racing calendar professionalization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's export-processing zones and Germany's Mittelstand manufacturing corridors concentrate frame fabrication and component assembly for brands serving North American and European retail channels.
United States
Bureau of Land Management pilot programs in Utah and Colorado are opening restricted singletrack to Class 1 e-MTB access. FDA oversight applies to wearable biometric sensors integrated into handlebar-mounted training devices. The Pacific Northwest aerospace corridor supplies composite technicians for carbon fiber frame repair networks.
Germany
KBA motor registration requirements fragment e-MTB trail access permissions by power classification and rider certification level. The EU F-Gas Regulation forces suspension manufacturers to retool damper fluid formulations ahead of 2027 model releases. Bavaria's alpine tourism infrastructure concentrates seasonal demand for enduro-rated full-suspension platforms.
Switzerland
Pedal-assist power limits are relaxing across alpine trail networks, expanding addressable rider populations in high-tourism mountain corridors. Swissmedic compliance frameworks govern wearable physiological monitors sold through specialty retail. The Bernese Oberland cluster anchors lift-served bike park development.
China
MIIT standards for e-bike motor power and battery safety govern export-bound production from Yangtze River Delta assembly plants. GB standards for bicycle structural testing align with ISO 4210 fatigue protocols. Shenzhen and Dongguan hubs concentrate carbon fiber prepreg sourcing and frame finishing capacity.
France
Alpine departments are expanding pedal-assist access on GR footpaths previously restricted to non-motorized use. ANSM notification requirements apply to lactate threshold sensors marketed for athletic performance. Auvergne-Rhône-Alpes hosts the densest concentration of enduro racing teams and rapid-prototype frame builders.
Global Mountain Bicycles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated frame builders capturing margin in premium tiers while Asian assembly plants handle volume production for mid-market hardtails. The structure concentrates around three to five integrated groups with captive composite facilities and a fragmented long tail of regional assemblers. Dominant archetypes include heritage brands with direct-to-consumer configuration platforms, scale-driven OEMs with multi-site Asian production, and boutique fabricators serving professional racing teams. Competitive moves center on backward integration into carbon fiber precursor supply and strategic partnerships with independent bike shops for assembly fulfillment.
Among North American heritage brands, Trek Bicycle Corporation and Specialized Bicycle Components, Inc. occupy positions defined by proprietary suspension kinematics and domestic composite manufacturing control. Giant Manufacturing Co. Ltd. anchors the scale-driven tier with multi-facility Asian assembly capacity serving global brand portfolios.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. Ltd. |
| Specialized Bicycle Components, Inc. |
| Cannondale Bicycle Corporation |
| Merida Industry Co. Ltd. |
| Santa Cruz Bicycles |
| Scott Sports SA |
| Kona Bicycle Company |
| Rocky Mountain Bicycles |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap frame builders in Germany and Taiwan anchor pricing discipline through captive carbon fiber layup facilities, insulating premium tiers from raw material volatility while compressing mid-market margins through in-house production scale.
Pricing Analysis
Short lead-time premiums separate rush-order custom geometry from spot-inventory standard frames. Three-tier pricing structure across premium, standard, and economy levels stratifies by frame material grade and ISO 4210 certification tier. Pricing pressure stems from LME aluminum volatility above $2,600 per tonne squeezing entry-level hardtail margins. Beginners in German cycling clubs show highest price sensitivity; professional athletes purchasing titanium custom builds demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Toray and Mitsubishi Chemical dominating aerospace-grade carbon fiber precursor supply. Frame fabrication concentrates in Taiwan's export-processing zones, China's Yangtze River Delta, and Germany's Mittelstand manufacturing corridors. Raw material dependencies include Toray T700/T800 prepregs, 6061-T6 aluminum billets, and suspension damper fluids facing REACH reformulation. Tariff exposure on Chinese carbon fiber components threatens margin pools. Distribution runs through independent bike shops in Europe, direct-to-consumer platforms in North America, and specialty retailers in alpine tourism corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into carbon fiber precursor supply and captive suspension damper manufacturing defines the vertical-integration race, with first-movers securing allocation priority during aerospace contract surges.
For Market Incumbents: Acquire composite technician training pipelines in Pacific Northwest aerospace corridors to resolve recruitment bottlenecks. Lock long-term offtake agreements with Toray and Mitsubishi Chemical before defense allocation cycles tighten. E-MTB motor power classification fragmentation across German KBA rules threatens trail access permissions and demands proactive regulatory engagement. For New Entrants and Emerging Players: Direct-to-consumer configuration tools with modular suspension kinematics bypass distributor markups in North American markets. White-space targets include subscription-based component refresh programs for intermediate riders and biometric sensor-integrated handlebar displays. Penetrate US Bureau of Land Management pilot program corridors in Utah and Colorado where Class 1 e-MTB access is expanding. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier carbon fiber frame builders with resin-transfer molding automation in Taiwan and Germany. Five-to-ten year viability hinges on F-Gas Regulation compliance completion and REACH-aligned coating reformulation. Watch ECHA bio-based resin adoption curves as inflection indicator for first-mover coating suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor Supply | Toray allocation priority during aerospace surges secures frame builder production continuity. |
| Resin-Transfer Molding Automation Scale-Up | Mid-tier carbon fiber frame cost compression displaces aluminum in previously price-locked categories. |
| F-Gas Regulation Compliance Certification | Silicone and mineral oil damper fluid validation ahead of 2030 phasedown deadlines protects model year release timelines. |
| Direct-to-Consumer Configuration Platform Launch | Online frame geometry calculators with modular kinematics bypass traditional distributor margin extraction. |
| Biometric Sensor Integration Partnership | FDA-cleared wearable power meters and lactate threshold monitors open subscription analytics revenue streams. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with frame engineering directors, suspension R&D leads, independent bike shop owners, and alpine bike park procurement managers combined with secondary validation from ECHA substance restriction databases, KBA motor registration statistics, and ISO 4210 test protocol documentation. Bottom-up production volume estimates and top-down tourism expenditure triangulation converged on segment-level demand figures.
Granularity-level modeling captured product type, frame material, braking system, and target audience dimensions at country-level resolution across the projection horizon. CAGRs derived from trend-line extrapolation of resin-transfer molding cost curves, e-MTB regulatory liberalization pace, and alpine tourism infrastructure investment flows. Industry-specific inputs included F-Gas Regulation compliance timelines and REACH-driven material substitution elasticities.
The model holds under stable regulatory classification of e-MTB motor power thresholds; deviation in German KBA rulemaking or Swiss alpine network permissions would shift addressable rider segment boundaries. Forecasts reflect documented assumptions on carbon fiber precursor supply allocation and composite technician labor pool expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Knee Pads Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Quad Skate Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Europe Artificial Grass Market