
 Tennis Pole Market | 2026-2036
Tennis Pole Market Size, Share, and Industry Trends Forecast 2026-2036
Tennis Pole Market Analytics
Equipment leasing and municipal rental programs is narrowing the competitive field for capital-heavy permanent installations. Wilson Sporting Goods leverages its institutional sales network to dominate North American school district procurement. YONEX Co., Ltd. anchors its position through in-house aluminum extrusion capabilities that control raw material quality. Babolat VS SAS differentiates via specialized portable pole designs targeting tournament operators.
Tennis poles are vertical support structures, typically fabricated from aluminum, steel, or composite materials, engineered to withstand net tension loads of 150–200 kg while maintaining dimensional stability across temperature ranges. These components serve as the mechanical backbone for tennis court infrastructure in professional, educational, and recreational settings. Portable and retractable pole categories command expanding share as multi-use facility operators prioritize court reconfiguration flexibility. Steel and aluminum material segments retain volume leadership in permanent installations where durability expectations span decades. Composite formulations represent the fastest-growing material category as clubs seek reduced maintenance cycles and corrosion resistance.
FIFA-equivalent court standards from the International Tennis Federation, combined with national building codes enforced by Germany's KBA-adjacent sports facility regulators and the U.S. Consumer Product Safety Commission, govern structural load requirements and anchoring specifications. REACH compliance in Europe and OSHA workplace safety directives in the United States further constrain allowable material compositions and installation practices. Stakeholders must track evolving municipal sustainability procurement mandates that increasingly embed embodied carbon thresholds into public tender specifications.
Market Dynamics
Municipal sustainability procurement mandates are compressing supplier margins while forcing rapid material transitions toward low-carbon aluminum and recyclable composites across public tender processes.
Growth Catalysts
- EU F-Gas Regulation:Germany's KBA-adjacent sports facility regulators enforce embodied carbon thresholds that accelerate replacement cycles in club-level infrastructure renovation programs.
- Aluminum extrusion automation:In-house vertical control over raw material quality reduces defect rates and shortens lead times for institutional buyers.
- Multi-use facility operators:Portable and retractable pole categories expand as tournament operators prioritize rapid court reconfiguration flexibility.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting costs in European supply chains create input cost instability for permanent installation manufacturers.
- REACH compliance friction:ECHA substance restrictions constrain allowable coating chemistries and surface treatment processes.
- Steel substitution threat:Corrosion-resistant galvanized formulations retain cost advantage in budget-constrained municipal park departments.
Strategic Opportunities
- Equipment leasing channel:Rental programs for seasonal tournament operators create recurring revenue streams outside capital-heavy permanent sales.
- OSHA workplace safety directives:Installation certification requirements in the United States open service-attach revenue for qualified contractors.
- Composite recycling infrastructure:End-of-life pole recovery programs align with EU Green Deal circular economy targets.
Industry Challenges
- Welding technician scarcity:Specialized aluminum TIG certification requirements constrain installation capacity during peak construction seasons.
- ITF standardization delays:Net tension load testing protocol revisions create inventory stranding risk for pre-certified pole stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tennis Pole Market |
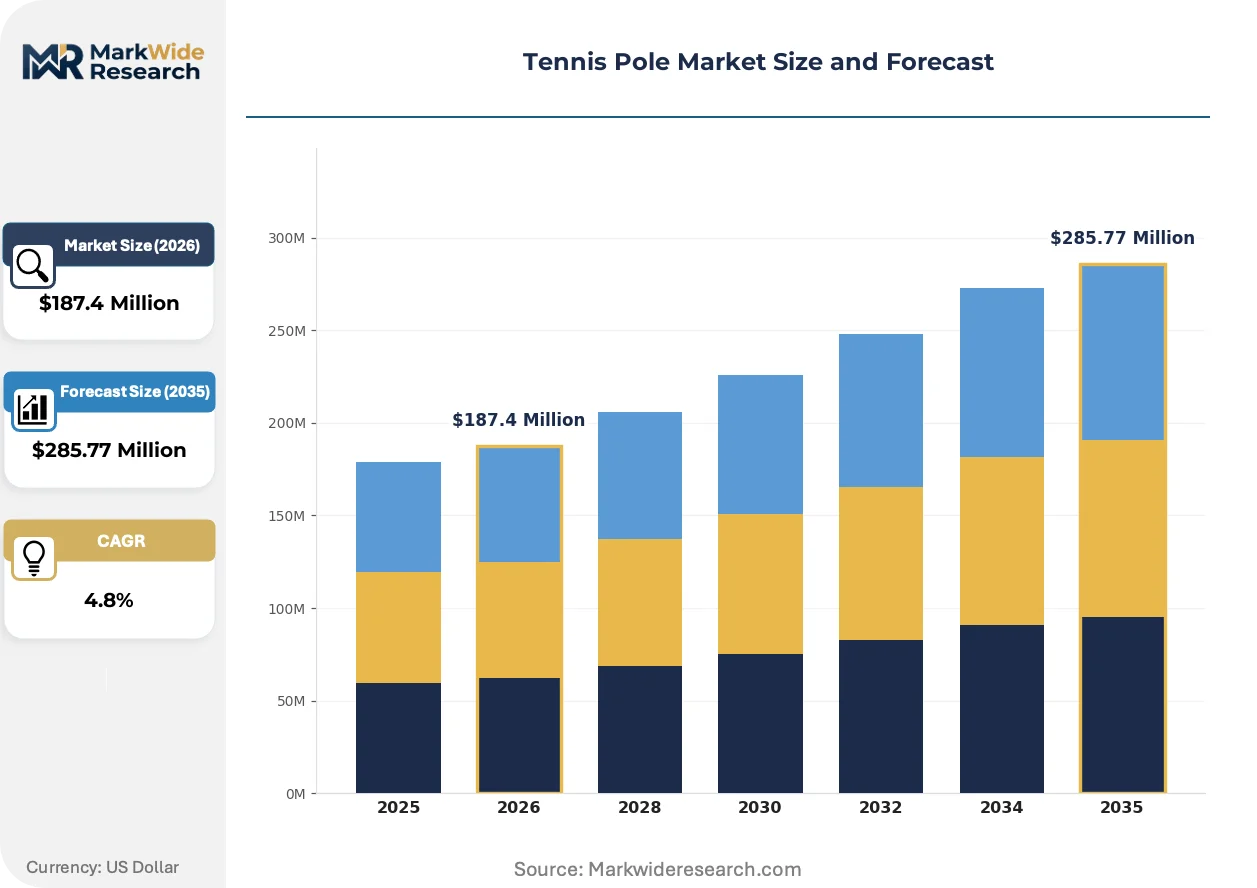
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
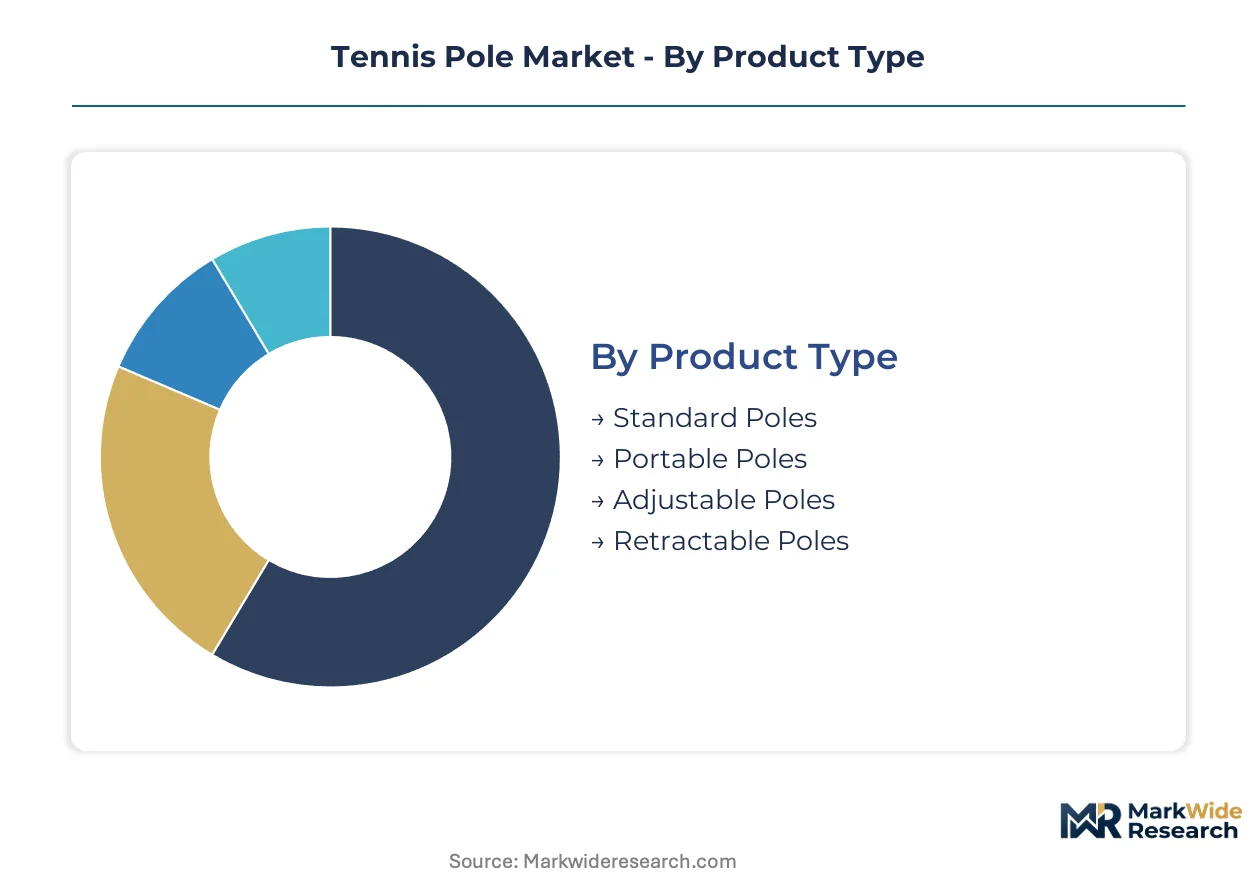
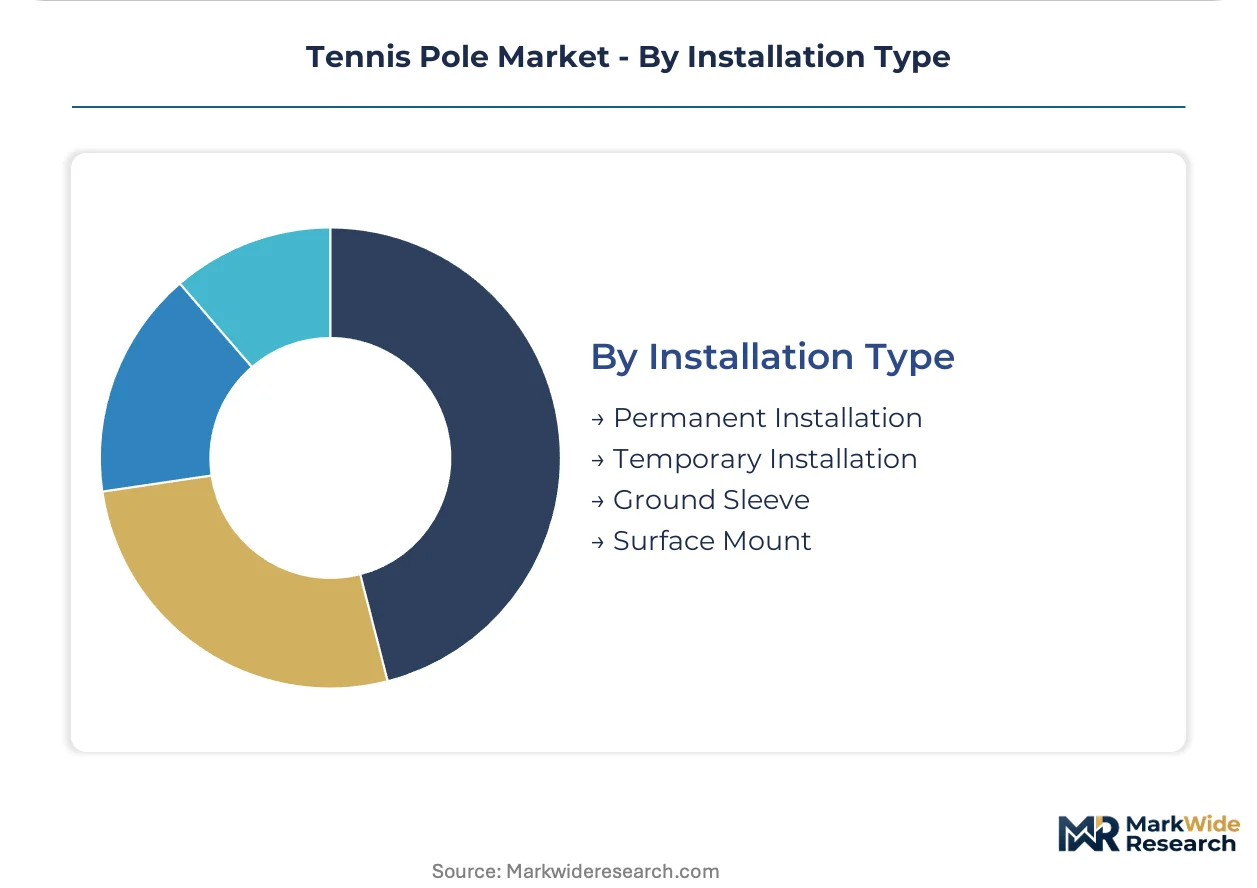
| Segmentation | Product Type: Standard Poles, Portable Poles, Adjustable Poles, Retractable Poles Material: Aluminum, Fiberglass, Steel, Composite End User: Professional Players, Recreational Players, Schools, Clubs Installation Type: Permanent Installation, Temporary Installation, Ground Sleeve, Surface Mount |
| Companies Covered | Wilson Sporting Goods, YONEX Co., Ltd., Babolat VS SAS, HEAD Sport GmbH, Amer Sports Corporation, Tecnifibre SAS, Dunlop Sports, Solinco Sports LLC, ProKennex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tennis Pole Market Evolving Landscape
Digital design tools and embedded sensor systems are compressing traditional specification cycles while enabling predictive maintenance models that alter long-term ownership economics.
Carbon fiber reinforced polymer (CFRP) hybrid poles integrate strain gauges for real-time tension monitoring. University athletic departments in the United States pilot these systems for liability documentation. The technology is virtualizing traditional manual inspection protocols into automated compliance reporting.
REACH SVHC candidate list expansions are forcing reformulation of anti-corrosion surface treatments. European manufacturers accelerate fluoropolymer-free coating development. German tennis club procurement committees now require full material disclosure documentation in tender submissions.
Municipal parks departments consolidate vendor relationships through multi-year framework agreements. Independent regional distributors lose share to direct institutional sales teams. This concentration is most visible in California and Texas public recreation infrastructure budgets.
Tennis Pole Market Segmentation
Tennis pole purchasing decisions hinge on maintenance burden and lifecycle service requirements. Facility operators weigh upfront capital against decades of inspection, tension calibration, and eventual replacement logistics. Segmentation reveals how after-sales intensity varies dramatically across product configurations and user types.
Product Type:
After-sales service intensity diverges sharply across mobility categories, with portable systems demanding seasonal calibration support while permanent installations require decade-spanning structural inspections.
- Standard Poles:Fixed aluminum or steel columns anchored in concrete footings dominate municipal park budgets. German club procurement committees prioritize these for 25-year depreciation schedules, though welding technician scarcity extends installation lead times during peak construction windows.
- Portable Poles:Freestanding weighted bases enable rapid court reconfiguration for multi-use facilities. Tournament operators in the United States drive replacement cycles through seasonal rental programs, creating recurring revenue channels distinct from capital sales.
- Adjustable Poles:Telescoping height mechanisms accommodate junior training programs and wheelchair tennis specifications.
- Retractable Poles:Underground housing systems maximize space flexibility for indoor arena conversions.
By volume, Standard Poles leads. By growth pace, Portable Poles is expanding most quickly.
Material:
Cost tier stratification separates premium corrosion-resistant formulations from budget galvanized steel, with mid-range aluminum capturing institutional procurement frameworks.
- Aluminum:Extruded 6061-T6 alloy delivers strength-to-weight ratios critical for portable applications. YONEX Co., Ltd. maintains in-house extrusion capabilities that control raw material quality and shorten lead times for Japanese municipal buyers facing ITF standardization deadlines.
- Composite:Fiberglass-reinforced polymer formulations eliminate corrosion maintenance cycles entirely. European club procurement committees under EU Green Deal mandates now require embodied carbon documentation, accelerating shifts away from primary aluminum.
- Steel:Galvanized tubular sections retain cost advantage in budget-constrained U.S. school district installations.
- Fiberglass:Pultruded profiles serve coastal markets where salt exposure degrades metal alternatives.
By volume, Aluminum leads. By growth pace, Composite is gaining share fastest.
End User:
Customer type determines specification rigor, with professional venues demanding ITF-certified tension tolerances while recreational buyers prioritize visual uniformity over precision engineering.
- Clubs:Private tennis facilities in Germany sustain replacement order volumes through scheduled renovation cycles. KBA-adjacent sports facility regulators enforce net tension load testing protocols that compress replacement windows and standardize procurement specifications.
- Schools:U.S. district procurement consolidates through multi-year framework agreements, favoring vendors with direct institutional sales teams over regional distributors. Wilson Sporting Goods leverages its established network to capture California and Texas public recreation budgets.
- Professional Players:Tournament operators specify CFRP hybrid poles with embedded strain gauges for liability documentation.
- Recreational Players:Residential backyard installations drive seasonal demand for lightweight portable systems.
By volume, Clubs leads. By growth pace, Schools shows the steepest expansion trajectory.
Installation Type:
Application context dictates anchoring methodology, with ground sleeve systems balancing permanence against future relocation flexibility for leased facility operators.
- Permanent Installation:Concrete-embedded footings with direct burial anchors serve dedicated outdoor courts. OSHA workplace safety directives in the United States mandate installation certification requirements, opening service-attach revenue for qualified contractors performing tension calibration and structural inspections.
- Ground Sleeve:Removable sleeve systems allow pole extraction for seasonal storage or court surface maintenance. Municipal parks departments in Texas favor this configuration for flood-prone regions where equipment must evacuate before severe weather events.
- Temporary Installation:Weighted base plates enable same-day deployment for pop-up tournament infrastructure.
- Surface Mount:Bolt-down flanges attach to existing concrete slabs without excavation, preserving indoor arena flooring.
By volume, Permanent Installation leads. By growth pace, Ground Sleeve is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in tennis pole equipment favor manufacturing economies with integrated aluminum supply chains, while import-dependent markets absorb premium portable systems through tournament infrastructure investments. Trade flows concentrate between East Asian fabrication hubs and European club renovation programs.
United States
Municipal parks departments in California and Texas drive replacement orders through multi-year framework agreements. OSHA workplace safety directives mandate installation certification for permanent anchoring systems. Wilson Sporting Goods leverages direct institutional sales networks to capture school district procurement budgets concentrated in the Southeast and Midwest.
Germany
Club-level tennis participation sustains scheduled renovation cycles with standardized replacement windows. KBA-adjacent sports facility regulators enforce ITF-equivalent net tension load testing protocols. Manufacturing clusters in Bavaria and North Rhine-Westphalia specialize in low-carbon aluminum extrusion for EU Green Deal-compliant tenders.
Japan
METI industrial standards govern sports facility material specifications for public recreation infrastructure. Domestic municipal buyers prioritize corrosion-resistant formulations for coastal humidity exposure. YONEX Co., Ltd. maintains captive extrusion capabilities in industrial zones surrounding Nagoya and Osaka.
Australia
Salt-exposed coastal courts in New South Wales and Queensland drive demand for fiberglass-reinforced polymer alternatives. TGA-aligned building codes regulate structural load requirements for public facility installations. Sydney and Melbourne metropolitan councils consolidate vendor relationships through state-level procurement frameworks.
United Kingdom
Local authority leisure budgets in London and the Southeast prioritize retractable pole systems for multi-use indoor arena conversions. CE marking requirements align with evolving REACH SVHC restrictions on surface treatment chemistries. Manchester and Birmingham club networks sustain mid-market replacement demand through scheduled asset refresh programs.
Tennis Pole Market Competitive Landscape
On the supply side, the industry is tiered between integrated sporting goods conglomerates and specialized court infrastructure fabricators. Equipment leasing channels and municipal rental programs are compressing margins for capital-heavy permanent installation specialists. Three archetypes dominate: vertically integrated aluminum extruders controlling raw material quality, portable system specialists targeting tournament operators, and institutional sales networks capturing public sector framework agreements. Competitive moves center on backward integration into aluminum supply and direct institutional sales team expansion displacing regional distributors.
Within the integrated sporting goods tier, Wilson Sporting Goods and YONEX Co., Ltd. exemplify divergent supply chain strategies. Wilson leverages established North American institutional sales networks to anchor public sector procurement relationships. YONEX represents captive manufacturing depth through in-house aluminum extrusion capabilities. Babolat VS SAS occupies a position among portable system specialists, exemplifying tournament-operator-focused design differentiation. These three anchors illustrate how competitive positioning splits between geographic sales infrastructure control and manufacturing integration depth.
| Leading Market Players |
|---|
| Wilson Sporting Goods |
| YONEX Co., Ltd. |
| Babolat VS SAS |
| HEAD Sport GmbH |
| Amer Sports Corporation |
| Tecnifibre SAS |
| Dunlop Sports |
| Solinco Sports LLC |
| ProKennex |
| Others |
Value Network & Pricing Analysis
Bavarian extrusion clusters in southern Germany concentrate primary aluminum processing capacity, translating upstream energy cost volatility into asymmetric pricing power for permanent installation manufacturers serving EU Green Deal-compliant tenders.
Pricing Analysis
Municipal parks departments anchor three-tier pricing structure across premium, standard, and economy levels, with ITF-certified tension tolerances and REACH-compliant surface treatments commanding 40-60% premiums over galvanized steel alternatives. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because steel substitution threats from corrosion-resistant galvanized formulations pressure aluminum pole margins. Budget-constrained U.S. school districts exhibit highest price sensitivity; professional tournament operators demonstrate lowest sensitivity due to liability documentation requirements.
Supply Chain Analysis
Extended payment terms from Japanese municipal buyers and supply-chain finance facilities from German club procurement committees shape working capital dynamics for fabricators. Manufacturing concentrates in Germany, Japan, and China, with Nagoya-Osaka industrial zones hosting captive extrusion capabilities. Raw material dependencies draw from primary aluminum smelters, fiberglass pultrusion feedstock, and REACH-compliant coating chemistries. Single-source vulnerability in European aluminum supply chains poses structural risk. Distribution runs through direct institutional sales teams displacing independent regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation and embodied carbon mandates are disrupting procurement specifications faster than incumbent supply chains can adapt, compressing margins for manufacturers locked in high-carbon aluminum sourcing.
For Market Incumbents: Insulate core institutional relationships by accelerating low-carbon aluminum qualification and embedding installation certification capabilities to capture OSHA-mandated service-attach revenue. Threat from composite substitution and welding technician scarcity demands backward integration into recyclable polymer formulations and technician training partnerships. For New Entrants and Emerging Players: Establish a beachhead in portable pole rental programs for seasonal U.S. tournament operators, where capital-light recurring revenue models bypass entrenched permanent installation incumbents. White-space exists in CFRP hybrid poles with embedded strain gauges for university athletic departments. Go-to-market through direct digital specification tools that compress traditional procurement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because end-of-life pole recovery programs align with tightening EU Green Deal mandates and create durable competitive moats through reverse logistics capabilities. Acquisition targets should exhibit captive composite recycling infrastructure or established municipal framework agreements. Signal to watch: ITF standardization delays resolving and inventory stranding risk clearing for pre-certified stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminum | Bavarian manufacturers secure EU Green Deal compliance ahead of embodied carbon tender thresholds. |
| Portable System Rental Program Launch | Tournament operators in Texas and California bypass capital constraints through seasonal deployment models. |
| Composite Recycling Infrastructure Buildout | German club networks satisfy circular economy procurement mandates with documented end-of-life recovery. |
| Installation Certification Capability Acquisition | OSHA-compliant contractors capture service-attach revenue from U.S. municipal parks departments. |
| CFRP Hybrid Pole with Embedded Sensors | University athletic departments automate liability documentation through real-time tension monitoring. |
Research Methodology
A spread of perspectives from municipal parks procurement officers, tennis club facility managers, aluminum extrusion plant engineers, and tournament infrastructure operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ITF technical documentation, REACH SVHC regulatory filings, U.S. Consumer Product Safety Commission guidelines, and municipal tender databases. Bottom-up unit economics and top-down market sizing triangulated volume estimates.
Demand-supply balance modeling anchored projections, with segmentation across product mobility categories, material formulations, end-user types, and installation methodologies throughout the forecast period. CAGRs derived from historical replacement cycle analysis, renovation program pipelines, and regulatory-driven acceleration effects. Industry-specific inputs included welding technician capacity constraints and ITF standardization timeline uncertainty.
Stress conditions across primary aluminum price volatility, REACH SVHC list expansion pace, and municipal budget allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on replacement cycle compression and material transition timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Go Kart Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Alpine Ski Equipment Market