
 Europe Artificial Grass Market | 2026-2036
Europe Artificial Grass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Artificial Grass Market Foresight
Modular roll-and-tile configurations is expanding buyer flexibility across municipal and commercial procurement channels. TenCate Grass leverages in-house yarn extrusion to control specification consistency across European football federation tenders. SportGroup anchors its position through integrated installation services that reduce third-party contractor dependency. GreenFields BV differentiates via CoolPlus fiber technology that lowers surface temperatures for southern European climates.
Artificial grass consists of synthetic fiber tufts—typically polyethylene, polypropylene, or nylon—knitted into porous backings and installed over compacted aggregate bases with optional infill layers for shock absorption and vertical fiber support. Polyethylene-based systems dominate the sports field segment due to softer hand-feel and lower abrasion rates for skin contact, while polypropylene surfaces lead in landscaping applications where cost sensitivity outweighs performance premiums. Among installation types, infill systems still occupy the majority share in institutional sports construction, though non-infill modular formats are gaining traction in rooftop garden and residential balcony projects where structural load limits apply.
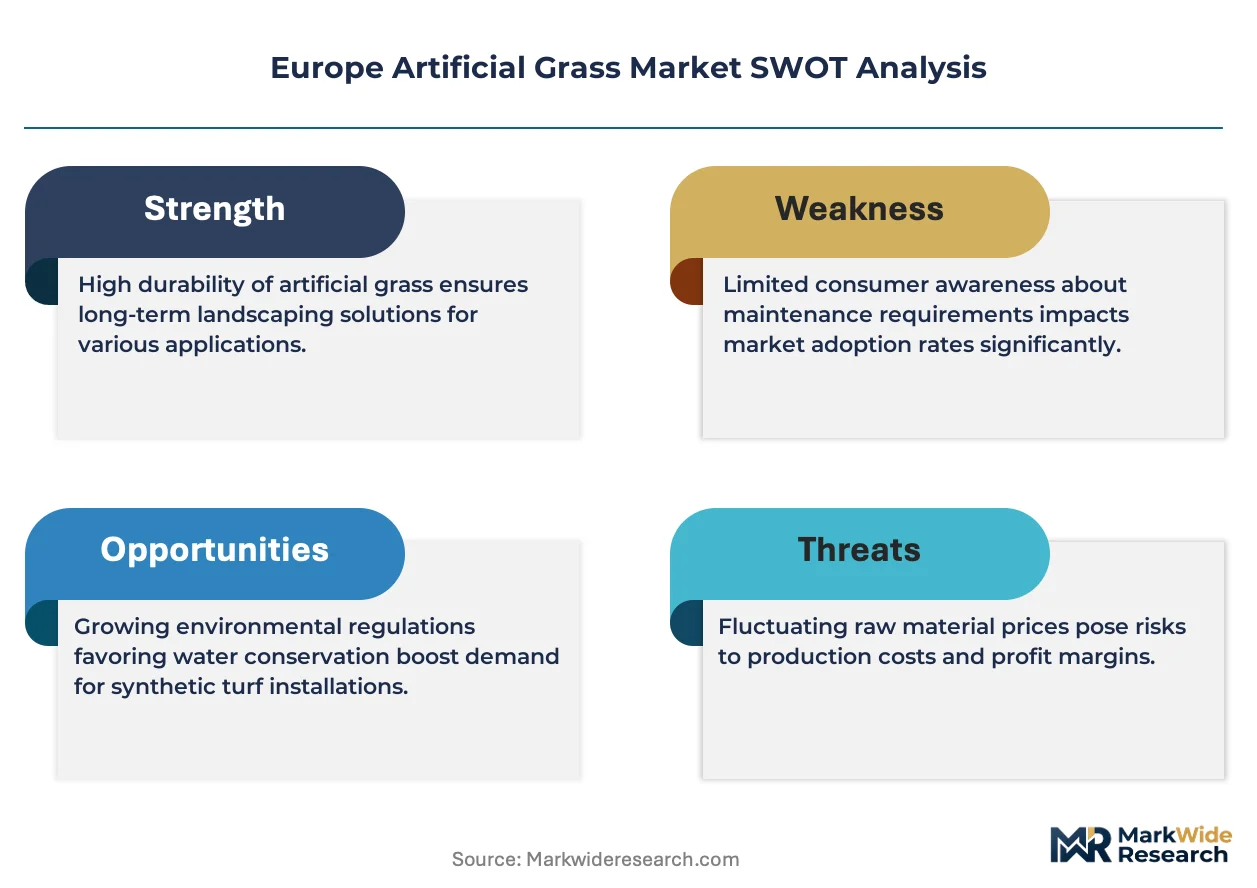
REACH restrictions on crumb rubber infill components and the EU Green Deal circular-economy requirements are forcing reformulation of backing adhesives and filler materials across the supply chain. ECHA substance evaluations now cover zinc and polycyclic aromatic hydrocarbon leaching from legacy synthetic turf systems, creating compliance costs that favor larger manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor pending F-Gas Regulation amendments that could affect yarn cooling processes, plus national building codes in France and Italy that increasingly mandate permeable surfacing for flood-risk zones.
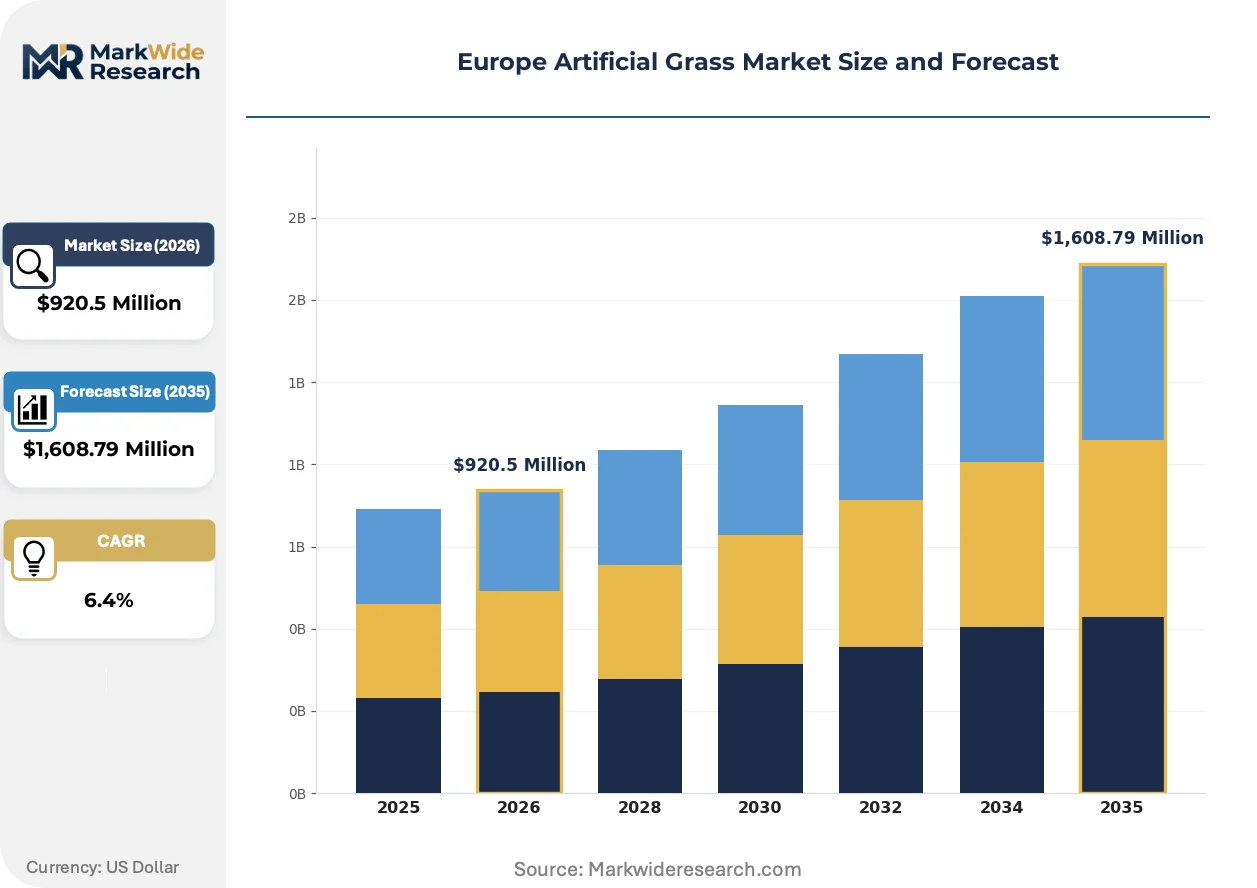
Market Dynamics
Water scarcity mandates and EU Green Deal carbon-footprint thresholds are compressing specification timelines across municipal procurement channels, forcing rapid substitution of legacy natural turf with synthetic alternatives.
Growth Catalysts
- REACH compliance deadlines:ECHA substance evaluations covering zinc and polycyclic aromatic hydrocarbon leaching are accelerating replacement cycles for aging synthetic turf systems in Germany and the Netherlands.
- Football federation tender specifications:Municipal sports authorities across Western Europe are embedding synthetic pitch requirements into multi-year infrastructure renewal programs.
- CoolPlus fiber technology:Surface temperature reduction capabilities are expanding addressable demand into southern European climates previously unsuited to artificial grass deployment.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices expose manufacturers to margin compression without long-term supply agreements.
- Regulatory friction from F-Gas Regulation amendments:Pending restrictions on yarn cooling processes threaten production continuity for extrusion-dependent facilities.
- Natural turf renovation substitutes:Hybrid grass systems and improved natural turf management technologies compete for municipal budget allocation in water-abundant regions.
Strategic Opportunities
- Rooftop garden and residential balcony segments:Non-infill modular formats address structural load constraints in dense urban construction across France and Italy.
- Bio-based infill alternatives:EU Green Deal circular-economy requirements create first-mover advantage for manufacturers with validated organic filler formulations.
- Permeable surfacing mandates:National building codes in flood-risk zones are opening specification pathways for porous backing systems.
Industry Challenges
- Regulatory affairs capability scarcity:Dedicated compliance teams capable of navigating ECHA evaluations and F-Gas amendments concentrate among larger manufacturers.
- Installation workforce certification:Integrated service models require technician training programs that extend deployment timelines in fragmented contractor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Artificial Grass Market |
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Others Application: Sports Fields, Landscaping, Playground, Rooftop Gardens End User: Residential, Commercial, Institutional, Sports Organizations Installation Type: Infills, Non-Infills, Seamless, Modular |
| Companies Covered | SportGroup, Limonta Sport, CCGrass, Victoria PLC, Condor Grass, TenCate Grass, SIS Pitches, GreenFields BV, FieldTurf (Tarkett Group), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Artificial Grass Market Shifts & Advancements
Specification evolution is compressing around temperature performance, circular material flows, and procurement flexibility as buyers demand systems aligned with tightening environmental mandates.
CoolPlus fiber technology is absorbing thermal management requirements for southern European installations. Municipal buyers in Spain and Italy are specifying these systems for youth sports facilities where surface heat previously restricted play hours. The technology is absorbing market share from standard polyethylene formulations in climates exceeding 30°C summer averages.
ECHA substance evaluations under REACH are forcing reformulation of legacy crumb rubber infill across the supply chain. Manufacturers are accelerating bio-based filler development to preempt regulatory prohibitions on zinc and PAH leaching. Sports field installations in Germany and the Netherlands face the most compressed compliance timelines as municipal tenders already exclude non-compliant systems.
Modular roll-and-tile configurations are disrupting traditional infill-dependent procurement patterns. Commercial landscaping buyers and residential developers are specifying these formats for rooftop and balcony projects where structural engineers impose strict load limits. France and Italy show the fastest behavioral shift as urban density increases and permeable surfacing requirements expand.
Europe Artificial Grass Market Segmentation
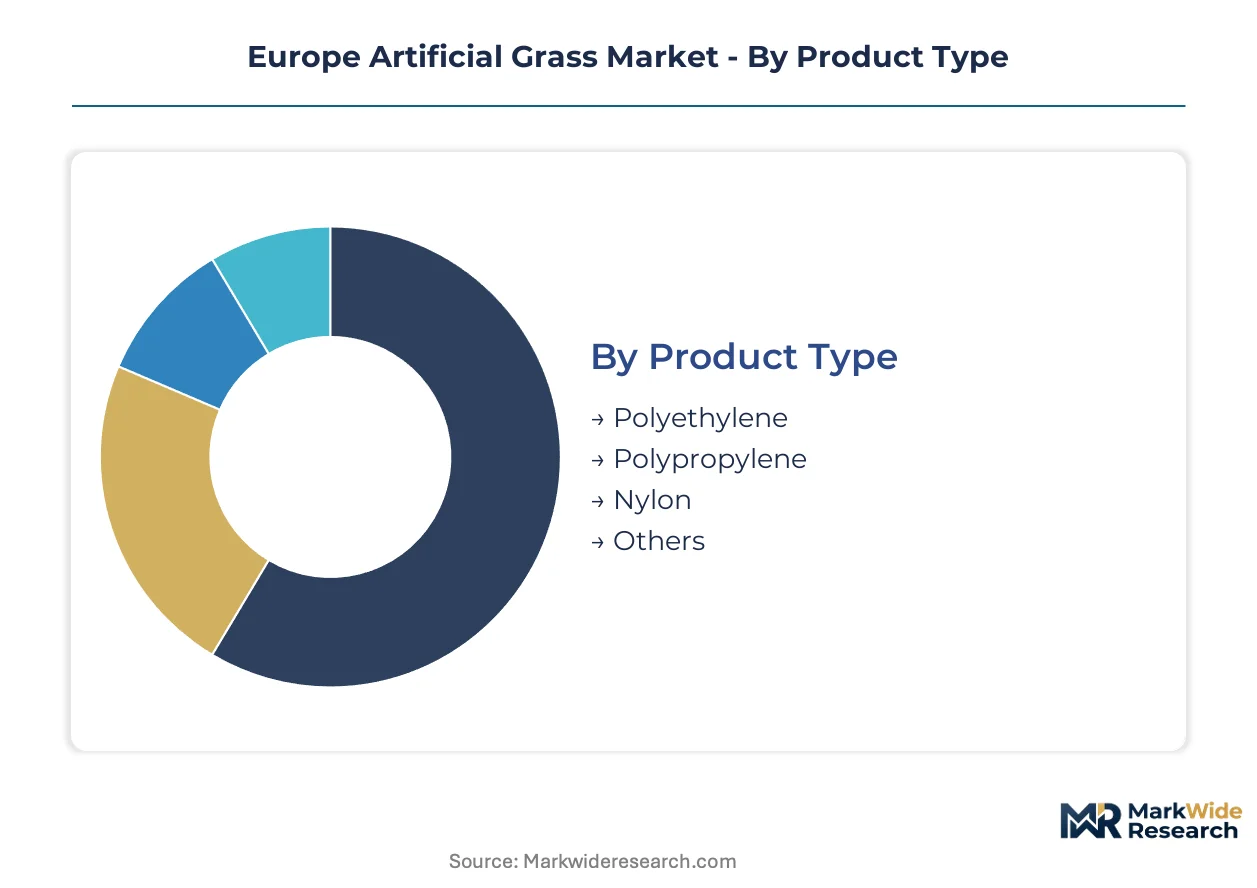
Segmentation in the Europe Artificial Grass Market reflects divergent technical requirements across climate zones, load-bearing constraints, and regulatory compliance timelines. Specification choices cascade from fiber chemistry through installation architecture, with each decision point locking in performance characteristics and lifecycle cost profiles.
Product Type:
Polyethylene formulations operate as standalone surface systems with embedded performance characteristics, while nylon and polypropylene variants embed into multi-layer composite structures.
- Polyethylene:Soft hand-feel and low skin-abrasion rates define this polymer class. German and Dutch municipal football federation tenders specify polyethylene for youth pitches where player contact frequency runs highest. REACH compliance deadlines on legacy rubber infill accelerate specification shifts toward polyethylene systems with bio-based alternatives.
- Polypropylene:Cost-positioned for landscaping deployments where performance premiums face budget pressure. French and Italian residential balcony projects specify polypropylene for structural load compliance without sacrificing aesthetic uniformity.
- Nylon:High-traffic durability drives specification in professional sports venues. Surface resilience under cleat abrasion extends replacement cycles.
- Others:Bio-based polymer trials and hybrid formulations occupy niche pilot installations. ECHA substance evaluations monitor leaching profiles.
Volume placements concentrate in Polyethylene; the faster expansion belongs to bio-based alternatives within the Others category.
Application:
Application segments stratify by structural load requirements and climatic exposure, with rooftop and balcony formats demanding engineered weight reduction.
- Sports Fields:Institutional procurement channels dominate with federation-mandated shock absorption and ball-roll specifications. German municipal authorities embed synthetic pitch requirements into multi-year infrastructure programs.
- Landscaping:Commercial property developers specify for maintenance cost reduction. Water scarcity mandates in southern Europe displace natural turf in hospitality and corporate campus settings.
- Playground:Fall-height certification requirements govern specification. Safety surfacing standards in France and Italy mandate specific pile heights and infill depths.
- Rooftop Gardens:Non-infill modular formats address structural engineer load limits. Urban density increases in Paris and Milan accelerate specification velocity.
Procurement volume tilts toward Sports Fields; rooftop formats climb the fastest as building codes tighten permeability requirements.
End User:
End user categories diverge by procurement sophistication, with institutional buyers commanding specification influence that cascades down to residential segments.
- Residential:Individual homeowners and residential developers drive balcony and garden segment demand. Cost sensitivity favors polypropylene and non-infill formats.
- Commercial:Property management firms and hospitality operators prioritize lifecycle cost over first cost. Maintenance contract structures influence surface selection.
- Institutional:Municipal sports authorities and school districts anchor volume with multi-pitch procurement programs. REACH compliance timelines compress decision cycles in Germany and the Netherlands.
- Sports Organizations:Football federations and rugby unions set technical specifications that manufacturers must certify against. Tender documentation increasingly mandates CoolPlus fiber technology for southern European climates.
Institutional buyers command placement volume; Sports Organizations set the steepest expansion trajectory through specification standardization.
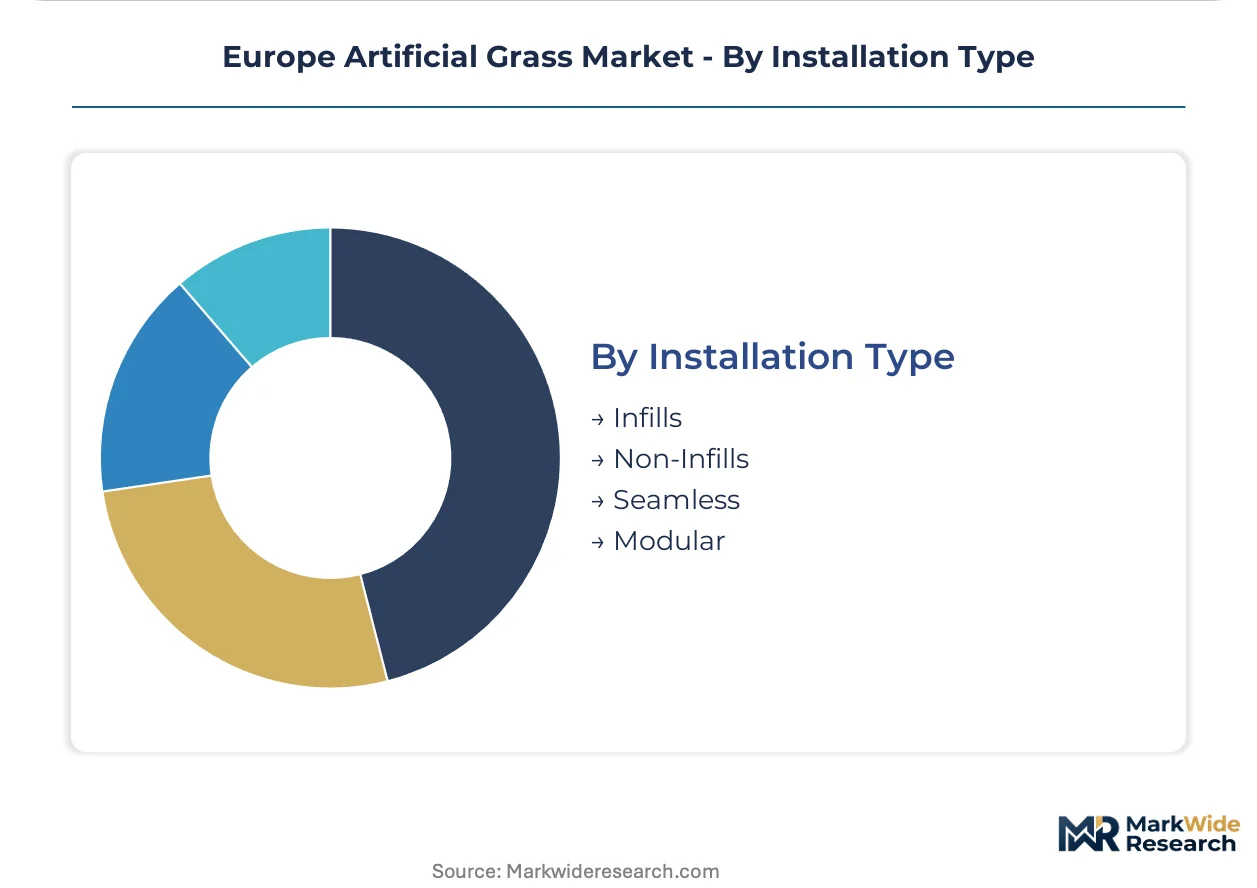
Installation Type:
Installation architecture determines structural integration depth, with infill systems requiring aggregate base preparation versus surface-applied modular alternatives.
- Infills:Sand and rubber granule layers provide shock absorption and fiber support. ECHA evaluations of zinc and PAH leaching force reformulation of legacy crumb rubber across German installations.
- Non-Infills:Dense tufting and specialized backing eliminate granular layers. Weight reduction enables rooftop and balcony deployment where structural limits apply.
- Seamless:In-situ installation creates continuous surfaces without joint lines. Aesthetic requirements in premium landscaping specify this format.
- Modular:Roll-and-tile configurations enable rapid deployment and future relocation. French and Italian flood-risk zone building codes favor permeable modular systems.
Infills retain volume concentration; modular formats gain share fastest as urban construction density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the Netherlands and Germany while consumption spreads across Western and Southern Europe. Water scarcity mandates and municipal procurement programs drive deployment velocity in distinct national patterns.
Germany
Municipal sports authorities in North Rhine-Westphalia and Bavaria embed synthetic pitch requirements into infrastructure renewal programs. REACH compliance deadlines on zinc and PAH leaching accelerate replacement cycles for aging rubber infill systems. The Ruhr industrial cluster hosts extrusion facilities supplying yarn to federation-certified installations across the country.
Netherlands
Water conservation mandates from national environmental agencies compress specification timelines for natural turf replacement. TenCate Grass operates in-house yarn extrusion capacity near Almelo, controlling specification consistency for football federation tenders. The Twente region anchors production gravity for polyethylene-based sports systems exported across the continent.
France
National building codes mandate permeable surfacing for flood-risk zones in Paris and Lyon metropolitan areas. Non-infill modular formats gain specification share for rooftop garden and residential balcony projects where structural engineers impose strict load limits. The Île-de-France region shows fastest behavioral shift toward roll-and-tile configurations.
Italy
Surface temperature concerns previously restricted artificial grass deployment in climates exceeding 30°C summer averages. CoolPlus fiber technology now absorbs thermal management requirements for youth sports facilities in Milan and Rome. Southern Italian hospitality operators specify synthetic landscaping for maintenance cost reduction amid water scarcity pressures.
Spain
Municipal buyers in Madrid and Barcelona specify temperature-reducing fiber systems for extended play hours. EU Green Deal circular-economy requirements push procurement officers toward bio-based infill alternatives in new construction. The Mediterranean coastal corridor concentrates commercial landscaping demand from hotel and resort developers.
Europe Artificial Grass Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive yarn production and dedicated regulatory affairs capabilities. Mid-scale specialists compete through installation service integration and climate-specific fiber technologies. Three archetypes dominate: extrusion-integrated manufacturers controlling specification consistency, service-integrated installers reducing contractor dependency, and technology specialists differentiating via thermal management or bio-based formulations. Capacity expansion and REACH compliance certification represent the dominant competitive moves across the landscape.
Among Netherlands-based extrusion-integrated manufacturers, TenCate Grass and GreenFields BV exemplify the archetype of specification control through in-house yarn production. SportGroup anchors the service-integrated tier with installation capabilities that reduce third-party contractor dependency. These three occupy positions that concentrate regulatory affairs expertise and federation certification relationships.
| Leading Market Players |
|---|
| SportGroup |
| Limonta Sport |
| CCGrass |
| Victoria PLC |
| Condor Grass |
| TenCate Grass |
| SIS Pitches |
| GreenFields BV |
| FieldTurf (Tarkett Group) |
| Others |
Supply & Pricing Matrix
Polyethylene resin price indices cascade through the Europe Artificial Grass Market supply chain, compressing margins at extrusion-integrated manufacturers while amplifying cost-down pressure on procurement-dependent installers. REACH compliance investments and bio-based infill R&D expenditures further stratify pricing tiers between federation-certified systems and uncertified alternatives.
Pricing Analysis
Margin tightening in standard-tier polyethylene systems reflects petrochemical input volatility and compressed municipal procurement timelines. Three-tier pricing structure across premium, standard, and economy levels separates CoolPlus fiber installations from conventional polyethylene and basic polypropylene landscaping grades. Certification against football federation specifications commands measurable premiums over uncertified alternatives. Price differentiation hinges on REACH compliance validation and thermal performance certification. Municipal buyers in Germany and the Netherlands demonstrate lowest price sensitivity due to regulatory mandate urgency, while French residential developers exhibit highest sensitivity to first-cost positioning.
Supply Chain Analysis
Dual-sourcing requirements from municipal tender specifications force yarn procurement across Netherlands and German extrusion facilities, with secondary qualification of Italian and Spanish backing suppliers. Raw material flows draw from Saudi and Qatari polyethylene feedstock, Dutch polypropylene resin, and Portuguese cork-derived bio-infill pilots. Single-source vulnerability concentrates in specialized cooling fiber technology licensed from limited patent holders. Distribution runs through federation-certified installation contractors in institutional segments and direct-to-developer channels for modular rooftop formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Artificial Grass Market sits in a technology-transition phase where CoolPlus fiber systems displace legacy polyethylene formulations in southern European climates. Bio-based infill alternatives are substituting crumb rubber ahead of REACH prohibitions.
For Market Incumbents: Anticipate accelerated specification shifts by securing ECHA pre-registration for organic filler formulations before municipal tender deadlines in Germany and the Netherlands. Deepen backward integration into yarn extrusion to defend margin position against resin price volatility. Prioritize CoolPlus licensing agreements for southern European market access. For New Entrants and Emerging Players: Enter via modular non-infill formats targeting French and Italian rooftop garden segments where structural load constraints exclude incumbent infill systems. White-space exists in bio-based infill validation services for mid-tier manufacturers lacking dedicated regulatory affairs teams. Pursue direct developer relationships in Paris and Milan high-density construction corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor extrusion-integrated specialists in the Netherlands with stranded REACH certification investments and compressed valuation multiples. Long-term viability centers on regulatory affairs capabilities and federation relationship depth. Watch ECHA substance evaluation timelines as inflection signal for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | ECHA pre-registration unlocks German and Dutch municipal tender participation before prohibition deadlines. |
| Bio-Based Infill Development | Organic filler validation addresses EU Green Deal circular-economy mandates and leaching restrictions. |
| CoolPlus Fiber Licensing | Thermal management technology expands addressable demand into Spanish and Italian youth sports facilities. |
| Modular Format Expansion | Roll-and-tile configurations capture French and Italian rooftop segments under permeable surfacing codes. |
| Installation Service Integration | Captive deployment capabilities reduce contractor dependency and accelerate project completion timelines. |
Research Methodology
Document review covered ECHA substance evaluation databases, EU Green Deal implementation guidelines, and football federation tender specifications, complemented by interviews with municipal sports authority procurement officers, artificial grass manufacturer regulatory affairs directors, and commercial landscaping contractor operations managers. Secondary sources included customs trade data for polyethylene and polypropylene resin flows, SEC filings of listed flooring companies, and national building code repositories for France and Italy. Bottom-up volume estimates from installation project databases were cross-referenced against top-down resin consumption figures.
Historical shipment data was cross-referenced against panel input from manufacturer sales directors to establish baseline penetration rates. Segmentation modeling covered fiber chemistry, application type, end-user category, and installation architecture across the projection horizon. CAGRs were derived from trend extrapolation of municipal procurement program commitments and replacement cycle compression under REACH deadlines. Industry-specific inputs included ECHA evaluation timeline assumptions and CoolPlus fiber adoption curves in southern European climates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA prohibition schedules or petrochemical price spike scenarios. Deviation in F-Gas Regulation amendment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Bicycle Tire Market