
 Crampon Market | 2026-2036
Crampon Market Size, Share, and Industry Trends Forecast 2026-2036
Crampon Market Analytics
Modular binding systems bundled with interchangeable front-point configurations is broadening buyer choice across skill levels. Grivel leverages its Italian manufacturing heritage to sustain premium positioning in technical ice climbing lines. Black Diamond anchors North American distribution through direct-to-guide partnerships. Petzl differentiates via integrated headlamp-crampon ecosystem compatibility.
Crampons are traction devices strapped or clipped to footwear, typically constructed from chromoly steel or 7075-T6 aluminum alloy with heat-treated front points rated to specific Rockwell hardness standards, designed to prevent slip-fall incidents on ice and hard snow surfaces. Mountaineering crampons occupy the largest volume tier due to standard three-season alpine use, while carbon composite variants represent the fastest-growing material segment as manufacturers reduce weight for high-altitude applications. Technical crampons command the deepest margin pools because precision front-point geometry requires CNC machining and hand-finishing that commodity general-purpose lines do not.
The EU PPE Regulation and CE marking framework govern market access for crampons sold in Europe, with Category III certification mandating third-party conformity assessment for fall-arrest applications. The US Consumer Product Safety Commission monitors traction-device incident reports, while ISO 24102 outlines testing protocols for mountaineering equipment interoperability. Stakeholders must monitor evolving binding-interface standards as splitboard and ski-mountaineering crossover formats proliferate.
Market Dynamics
Category III certification under the EU PPE Regulation is compressing vendor margins while elevating technical barriers for new entrants. Swiss guide services and military mountaineering units are accelerating replacement cycles for chromoly steel front-point systems.
Growth Catalysts
- EU PPE Regulation Category III mandates:Third-party conformity assessment requirements are filtering out uncertified suppliers and concentrating procurement among validated manufacturers.
- Carbon composite material adoption:High-altitude expedition operators are specifying 7075-T6 aluminum and carbon hybrid constructions to reduce pack weight for 8000-meter objectives.
- Swiss Alps corridor demand concentration:Alpine rescue services and professional guide associations are standardizing on modular binding systems with interchangeable front-point configurations.
Market Restraints
- Chromoly steel price volatility:Heat-treated front-point production depends on alloy steel inputs subject to energy-intensive smelting cost swings.
- Italian manufacturing concentration:Premium technical crampon CNC machining and hand-finishing capabilities cluster in Northern Italian alpine equipment districts.
- CE marking timeline friction:Category III fall-arrest certification requires 6-12 month third-party assessment cycles that delay product launches.
Strategic Opportunities
- Ski-mountaineering crossover formats:Splitboard binding interface standardization is creating demand for hybrid traction systems compatible with touring boots.
- Integrated headlamp-crampon ecosystems:Night climbing safety protocols are driving bundled procurement of illumination and traction equipment.
- Direct-to-guide distribution channels:Professional association purchasing cooperatives are bypassing traditional retail markup structures.
Industry Challenges
- CNC machining talent scarcity:Precision front-point geometry programming requires specialized alpine equipment manufacturing expertise concentrated in legacy European facilities.
- ISO 24102 interoperability testing:Mountaineering equipment standard verification delays product certification and market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crampon Market |
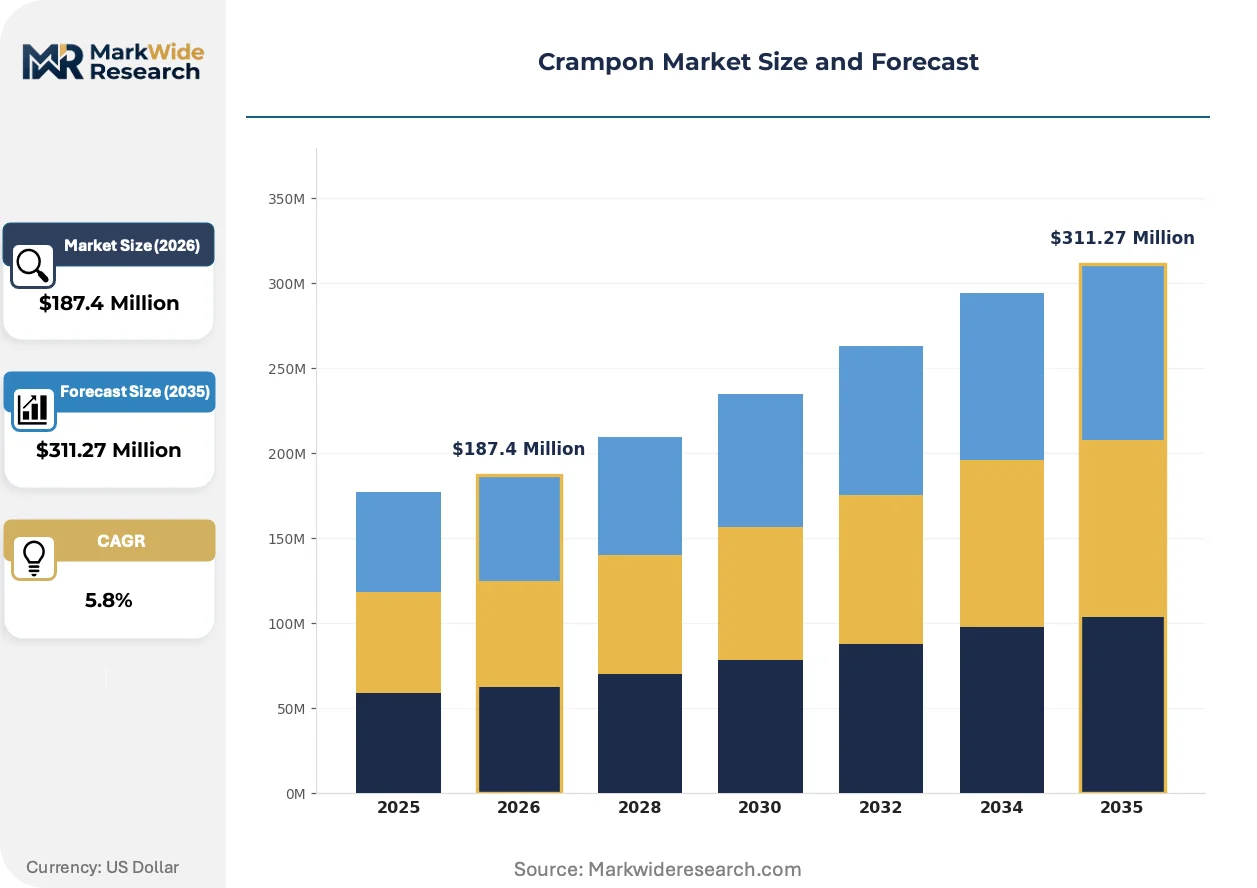
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Crampons, Mountaineering Crampons, Ice Climbing Crampons, General Purpose Crampons Material: Aluminum, Steel, Carbon Composite, Mixed Material Application: Ice Climbing, Glacier Travel, Mixed Terrain, Snow Hiking End User: Athletes, Outdoor Enthusiasts, Adventure Guides, Recreational Climbers |
| Companies Covered | Grivel, Black Diamond, Petzl, CAMP USA, Kahtoola, Salewa, G3 Genuine Guide Gear, Karakoram, Spark R&D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crampon Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing product development cycles while fragmenting buyer segments across skill-specific configurations.
Carbon composite hybrid construction is integrating aerospace-grade fiber layup techniques with traditional aluminum alloy frames to reduce overall system weight by 30-40% without sacrificing Rockwell hardness ratings. Expedition operators above 6000 meters are specifying these variants for oxygen-deprived carrying efficiency. The technology is integrating vertical supply chains as manufacturers bring filament winding and resin transfer molding in-house to protect proprietary layup geometries.
REACH substance restrictions on hexavalent chromium plating processes are forcing migration to trivalent alternatives or ceramic coating deposition for corrosion-resistant front points. Italian and Austrian manufacturers face 18-month transition timelines to reformulate surface treatment lines. Technical ice climbing product categories bear the heaviest compliance burden due to precision tolerances on point geometry.
Rental and guided-service procurement is consolidating individual consumer purchases as alpine tourism operators standardize fleet equipment. Chamonix and Zermatt guide services now specify uniform binding systems to reduce client familiarization time and liability exposure. This behavior concentrates volume among vendors capable of 500-plus unit annual contracts with maintenance and rotation servicing.
Crampon Market Segmentation
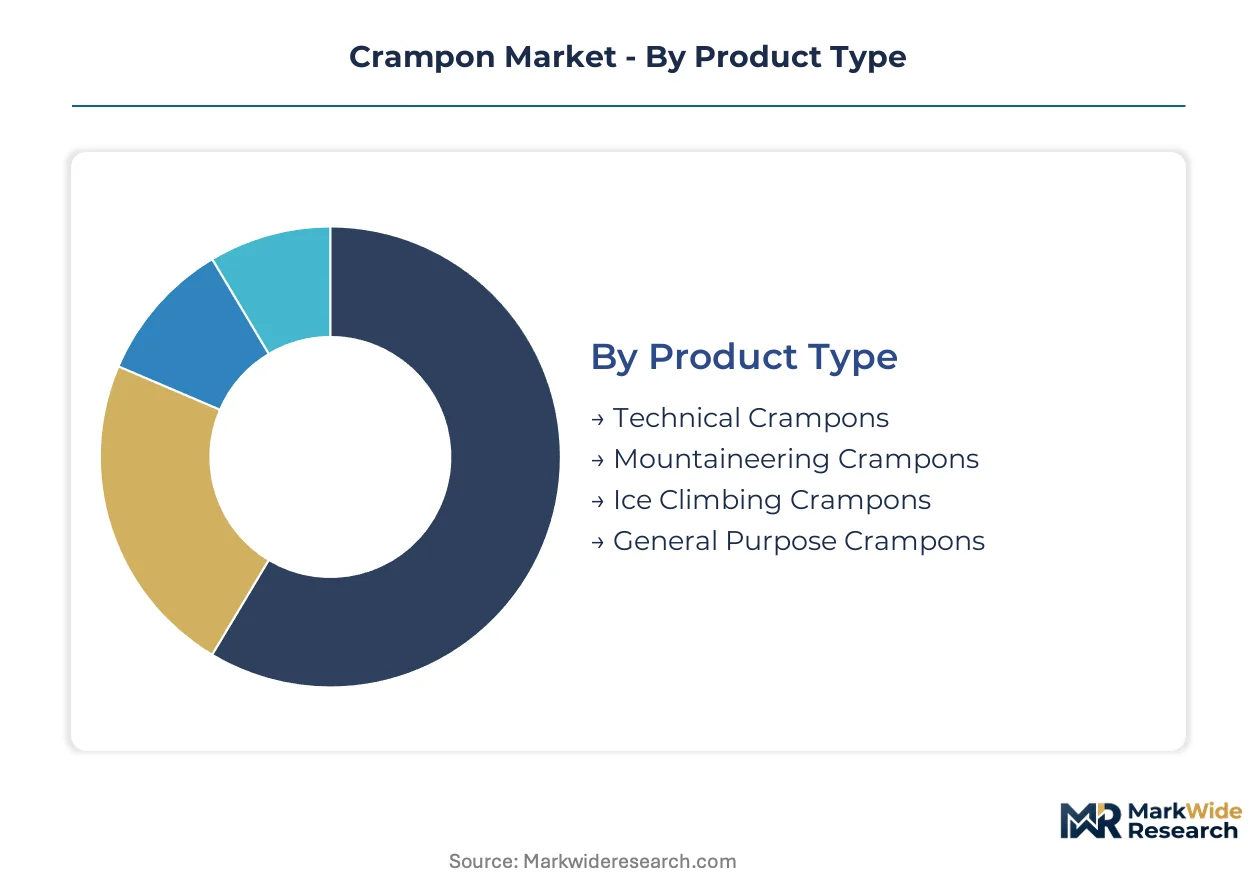
Crampon purchasing decisions pivot on terrain specificity, weight constraints, and certification requirements. Buyers evaluate front-point geometry, binding compatibility, and material durability against objective hazard ratings rather than brand preference alone.
Product Type:
Skill-level differentiation and terrain exposure determine which product tier buyers select.
- Technical Crampons:CNC-machined chromoly steel front points with mono or dual configurations rated for vertical ice and mixed rock-ice terrain. Swiss guide services and alpine rescue units in the Mont Blanc massif specify these for client safety protocols and liability mitigation.
- Mountaineering Crampons:Standard three-season designs with horizontal front points and flexible linking bars for glacier travel and moderate snow slopes. Volume concentrates in the Swiss Alps corridor where military mountaineering units drive replacement cycles for NATO-standard equipment.
- Ice Climbing Crampons:Aggressive front-point geometry optimized for waterfall ice and steep alpine ice routes.
- General Purpose Crampons:Entry-level strap-on systems for occasional snow hiking and non-technical terrain.
Mountaineering Crampons lead on scale; Technical Crampons lead on momentum.
Material:
Weight-to-strength ratios and corrosion resistance shape procurement specifications across altitude bands.
- Steel:Heat-treated chromoly or stainless alloys delivering maximum durability and Rockwell hardness for technical front points. Italian manufacturers in the Premana district dominate precision machining for this segment.
- Carbon Composite:Aerospace-grade fiber layup integrated with aluminum frames reducing system weight 30-40% for 8000-meter expedition use. Demand from Nepal-based operators is climbing the fastest as oxygen-deprived carrying efficiency becomes critical.
- Aluminum:7075-T6 alloy frames balancing weight reduction with adequate strength for glacier travel and moderate terrain.
- Mixed Material:Hybrid constructions combining steel front points with aluminum or composite frames to optimize performance per gram.
Steel dominates current procurement volumes; Carbon Composite shows steepest expansion trajectory.
Application:
Terrain classification and objective hazard levels determine binding system and point configuration requirements.
- Glacier Travel:Horizontal front points and anti-balling plates for crevasse zone safety and efficient flat-footing technique. European alpine clubs standardize these for guided traverse routes.
- Ice Climbing:Vertical front points and rigid construction for steep ice and mixed terrain. Norwegian fjord-region guide services drive specification of modular systems with interchangeable configurations.
- Mixed Terrain:Versatile geometries accommodating rock, ice, and snow transitions on alpine routes.
- Snow Hiking:Lightweight strap-on systems for packed trails and moderate slopes without technical exposure.
Glacier Travel commands the widest user base; Ice Climbing generates the highest equipment expenditure per participant.
End User:
Professional credential requirements and usage frequency create distinct procurement channels and service expectations.
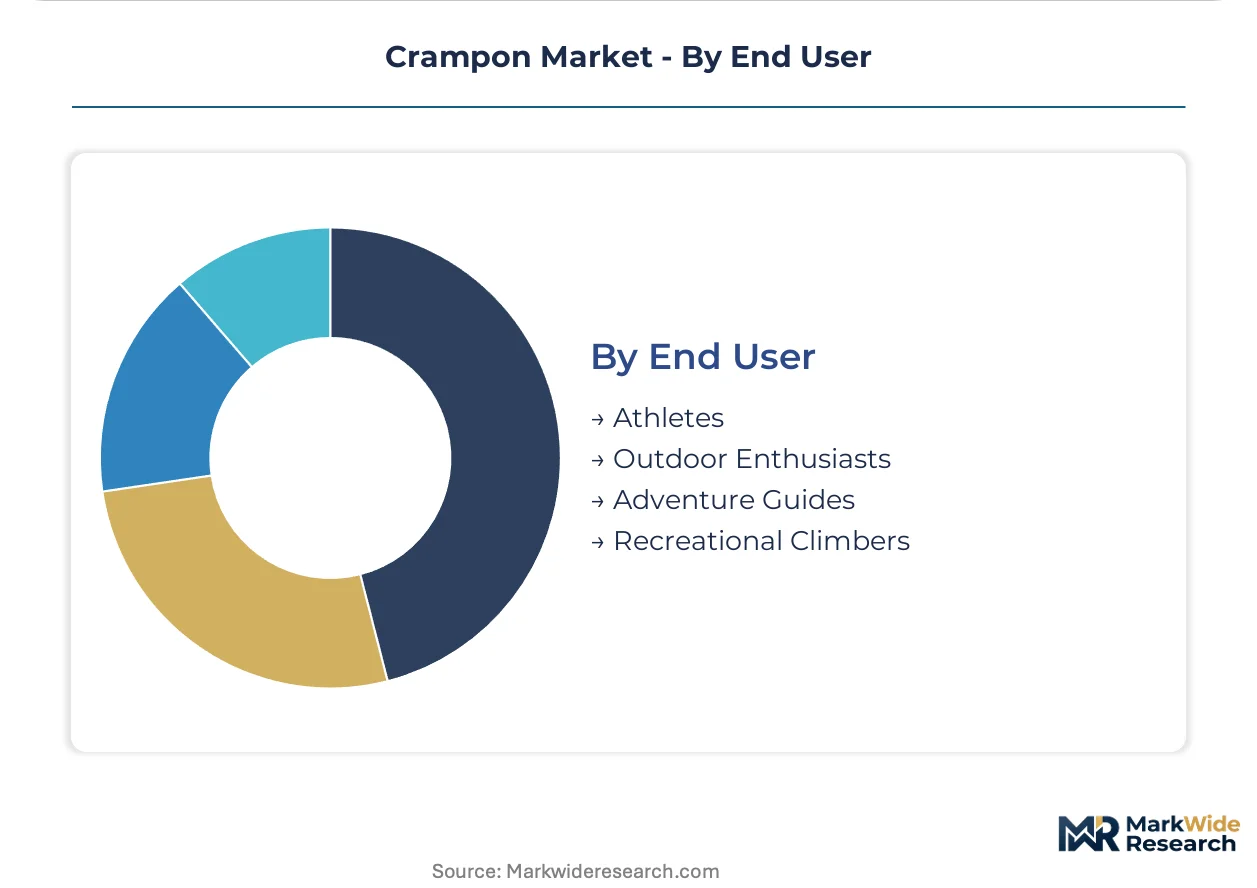
- Adventure Guides:Certified professionals requiring CE-marked Category III equipment with documented inspection histories. IFMGA-affiliated services in Chamonix and Zermatt negotiate fleet contracts with maintenance-included pricing.
- Athletes:Competition and expedition climbers prioritizing weight minimization and technical performance over durability metrics. Sponsored athletes in the UIAA Ice Climbing World Cup circuit influence product development priorities.
- Outdoor Enthusiasts:Self-directed climbers purchasing through specialty retail with emphasis on versatility across multiple trip types.
- Recreational Climbers:Occasional users seeking rental-accessible or entry-level purchase options for guided experiences.
Adventure Guides concentrate procurement volume; Athletes set performance benchmarks that cascade to adjacent tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian alpine equipment districts in Premana established precision crampon manufacturing heritage during the post-war expansion of European mountaineering. Swiss military procurement standards and French guide service specifications subsequently shaped regional demand patterns across the Alpine arc.
Switzerland
Swiss military mountaineering units and IFMGA-affiliated guide services in Zermatt and Chamonix corridor drive replacement cycles for Category III certified equipment. Swissmedic oversees medical device adjacent safety protocols for rescue equipment interoperability. Geneva-based procurement cooperatives negotiate fleet contracts exceeding 500 units annually with integrated maintenance servicing.
Italy
Premana district manufacturers dominate CNC machining and hand-finishing capabilities for technical front-point production. REACH substance restrictions under ECHA jurisdiction mandate 18-month transition timelines away from hexavalent chromium plating processes. Northern Italian alpine equipment clusters are reformulating surface treatment lines toward trivalent alternatives and ceramic coating deposition.
France
Chamonix guide services standardize modular binding systems to reduce client familiarization time and liability exposure. ANSM and CNIL frameworks govern product safety and data handling for rental fleet management systems. Auvergne-Rhône-Alpes region concentrates procurement volume among vendors capable of maintenance-included pricing structures.
United States
Direct-to-guide partnerships anchor North American distribution channels outside traditional retail markup structures. Consumer Product Safety Commission monitors traction-device incident reporting and recall protocols. Pacific Northwest and Rocky Mountain climbing communities generate concentrated demand for hybrid ski-mountaineering crossover formats compatible with splitboard binding interfaces.
Nepal
Expedition operators above 6000 meters specify carbon composite hybrid constructions for oxygen-deprived carrying efficiency on 8000-meter objectives. Kathmandu-based logistics coordinators source lightweight variants through regional distributors serving the Himalaya corridor. Sagarmatha National Park permit regulations increasingly mandate certified equipment inspection histories for commercial guiding operations.
Crampon Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and precision manufacturing capability dimensions. The vendor base stratifies between Italian heritage manufacturers with in-house CNC machining capacity and Asian fabricators serving entry-level strap-on segments. Two dominant archetypes emerge: technical specialists with backward integration into heat-treatment facilities, and scale-oriented assemblers sourcing front points from captive forging networks. Competitive moves concentrate on direct-to-guide distribution partnerships and carbon composite material R&D alliances with aerospace suppliers.
Within the heritage manufacturing tier, Grivel S.p.A. and Petzl S.A. exemplify European alpine equipment specialists with multi-generational production lineage. Black Diamond Equipment anchors North American positioning through Utah-based engineering operations. These three entities occupy positions spanning technical ice climbing innovation and expedition-grade reliability certification, representing distinct geographic anchoring strategies across the Alpine arc and Rocky Mountain corridor.
| Leading Market Players |
|---|
| Grivel |
| Black Diamond |
| Petzl |
| CAMP USA |
| Kahtoola |
| Salewa |
| G3 Genuine Guide Gear |
| Karakoram |
| Spark R&D |
| Others |
Value Network & Pricing Analysis
Category III certification divergence separates premium technical-grade suppliers from commodity-grade competitors, concentrating pricing power among CE-validated manufacturers while compressing margins for uncertified entrants. This bifurcation manifests in procurement structures: Swiss military mountaineering units and IFMGA guide services pay maintenance-included premiums for validated chromoly steel systems, while rental fleets and recreational channels absorb price erosion from Asian-sourced aluminum alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market. Premium tiers command certification-grade markups from CE-validated Italian manufacturers; standard tiers balance weight and durability for three-season alpine use; economy tiers serve occasional snow-hiking demand. Price differentiation rests on Rockwell hardness ratings and binding-system modularity. Pricing pressure stems from REACH compliance costs for hexavalent chromium phase-out. Adventure guides show least price sensitivity; recreational climbers exhibit highest elasticity.
Supply Chain Analysis
Refurbishment flows for chromoly steel front points extend product lifecycles in Swiss and French guide-service fleets, creating secondary supply channels that dampen replacement demand. Manufacturing concentrates in Italy, Switzerland, and Austria. Raw material dependencies include chromoly steel alloy, 7075-T6 aluminum billet, and aerospace-grade carbon fiber prepreg. Single-source vulnerability clusters in Northern Italian CNC machining districts for precision front-point geometry. Distribution runs through direct-to-guide partnerships alongside traditional specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU regulatory compliance costs and Nepalese expedition-operator procurement budgets, where oxygen-deprived carrying efficiency justifies premium carbon composite pricing despite higher unit costs.
For Market Incumbents: Deepen backward integration into heat-treatment facilities to protect proprietary Rockwell hardness protocols from chromoly steel price volatility. Secure long-term CNC machining talent pipelines in Premana district to defend against capability scarcity. Cement direct-to-guide fleet contracts with maintenance-included pricing to lock out emerging competitors. For New Entrants and Emerging Players: Direct-to-guide digital procurement platforms offer the lowest friction entry path. Target Nepal-based 8000-meter expedition logistics coordinators with carbon composite hybrid specifications. Pursue splitboard binding interface certification to capture ski-mountaineering crossover growth. For Investors and Strategic Acquirers: Consolidation pressure builds where CE marking timelines exceed 12 months and certification backlogs strand uncertified inventory. Five-to-ten year viability favors technical specialists with in-house CNC capacity and validated Category III portfolios. Watch for REACH substance restriction enforcement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Composite R&D Alliance | Aerospace fiber partnerships reduce system weight for 8000-meter expedition specifications. |
| Direct-to-Guide Distribution Expansion | Bypassing retail markup structures captures procurement volume from IFMGA-affiliated services. |
| CE Marking Fast-Track Investment | Compressed third-party assessment cycles accelerate product launch timelines against competitors. |
| Integrated Headlamp-Crampon Bundling | Night climbing safety protocols drive bundled procurement from alpine rescue services. |
| Splitboard Interface Certification | Ski-mountaineering crossover compatibility opens touring boot and binding ecosystem integration. |
Research Methodology
Multiple input streams — primary interviews with alpine equipment manufacturers, guide service procurement officers, and military mountaineering quartermasters; secondary validation against CE marking databases, ISO 24102 interoperability protocols, and customs trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed CNC machining operators in Northern Italian districts, expedition logistics coordinators in Kathmandu, and specialty retail buyers in Chamonix and Zermatt.
Data-stream reconciliation across product type, material composition, application terrain, and end-user credential requirements generated volume and value outputs. Segmentation dimensions modeled include technical versus mountaineering versus general-purpose classifications, steel-aluminum-carbon material tiers, and professional guide versus athlete versus recreational user archetypes. CAGRs were derived from replacement cycle analysis and procurement pattern extrapolation across the projection horizon.
Regulatory enforcement acceleration, raw material alloy price spikes, and CNC machining labor scarcity are the dominant revision risks to forecast assumptions. Practitioners should monitor ECHA REACH implementation timelines, chromoly steel smelting energy costs, and Italian alpine equipment district workforce demographics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Golf Bags Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Diving Board Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Figure Skating Equipment Market