
 RTA Furniture Market | 2026-2036
RTA Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
RTA Furniture Market Intelligence
E-commerce distribution is rewriting how RTA furniture reaches end consumers. Inter IKEA Systems B.V. leverages its captive store-and-click infrastructure to control fulfillment costs across multiple continents. Sauder Woodworking Co. anchors its competitiveness through domestic manufacturing scale in Ohio. Dorel Industries Inc. differentiates via vertical control over juvenile and home office RTA lines.
Ready-to-assemble furniture denotes flat-packed products shipped in knockdown form for consumer assembly using cam locks, dowels, or slide-together joints, typically constructed from particleboard, MDF, or engineered wood with laminate or veneer finishes. The category serves cost-conscious residential buyers, commercial fit-out contractors, and institutional procurement officers seeking freight efficiency and warehouse-space savings. Wood-based materials dominate volume shipments while metal-framed RTA seating commands higher per-unit margins in the hospitality channel. Online retail continues to outpace specialty stores in growth velocity though brick-and-mortar locations sustain stronger attachment rates for large-format cabinets and sofas requiring tactile evaluation.
EPA TSCA Title VI governs composite wood formaldehyde emissions in the United States while the EU Ecodesign Directive imposes sustainability disclosure requirements on furniture placed within the European single market. CARB Phase II in California operates as a de facto North American benchmark that most national distributors voluntarily meet to avoid SKU fragmentation. Stakeholders must monitor how extended producer responsibility frameworks in Germany and France reshape packaging and end-of-life obligations before committing capital to new regional distribution hubs.
Market Dynamics
Flat-pack logistics economics are compressing traditional furniture distribution layers as containerized knockdown shipments displace fully assembled inventory flows across ocean and last-mile networks.
Growth Catalysts
- CARB Phase II formaldehyde standards:California's emission benchmarks have become the de facto North American compliance floor, creating uniform SKU viability across US and Canadian distribution channels without regional fragmentation.
- Particleboard cost efficiency:Engineered wood substrates deliver freight density advantages that slash landed costs per unit versus solid wood alternatives for residential buyers.
- Dongguan manufacturing clusters:Guangdong Province's integrated supplier ecosystems compress procurement lead times and tooling costs for export-oriented RTA producers serving European and North American retailers.
Market Restraints
- Resin input volatility:Urea-formaldehyde binder prices fluctuate with natural gas feedstock costs, squeezing margin predictability for particleboard-dependent manufacturers.
- Single-source laminate dependency:Decorative surface paper supply concentrates among Southeast Asian mills, exposing finished goods producers to freight surge vulnerability.
- Dimensional stability limits:MDF swells irreversibly upon moisture exposure, disqualifying RTA bathroom and outdoor applications where solid wood or metal frames prevail.
Strategic Opportunities
- EU Ecodesign Directive disclosure mandates:Sustainability labeling requirements create first-mover advantage for manufacturers with certified recycled-content particleboard and FSC-tracked supply chains.
- India urban residential expansion:Metro apartment dwellers in Mumbai and Bangalore favor space-efficient flat-pack solutions that navigate narrow elevator shafts and stairwells during relocation.
- Augmented reality assembly guidance:Smartphone-based 3D overlay tools reduce customer service burden and return rates for complex cabinet configurations sold through digital channels.
Industry Challenges
- Cam lock tolerance precision:Injection-molded connector quality variance across supplier tiers produces field assembly failures that damage brand equity and drive negative reviews.
- EPA TSCA Title VI certification lag:Third-party laboratory queue times for composite wood emission testing extend product launch windows by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTA Furniture Market |
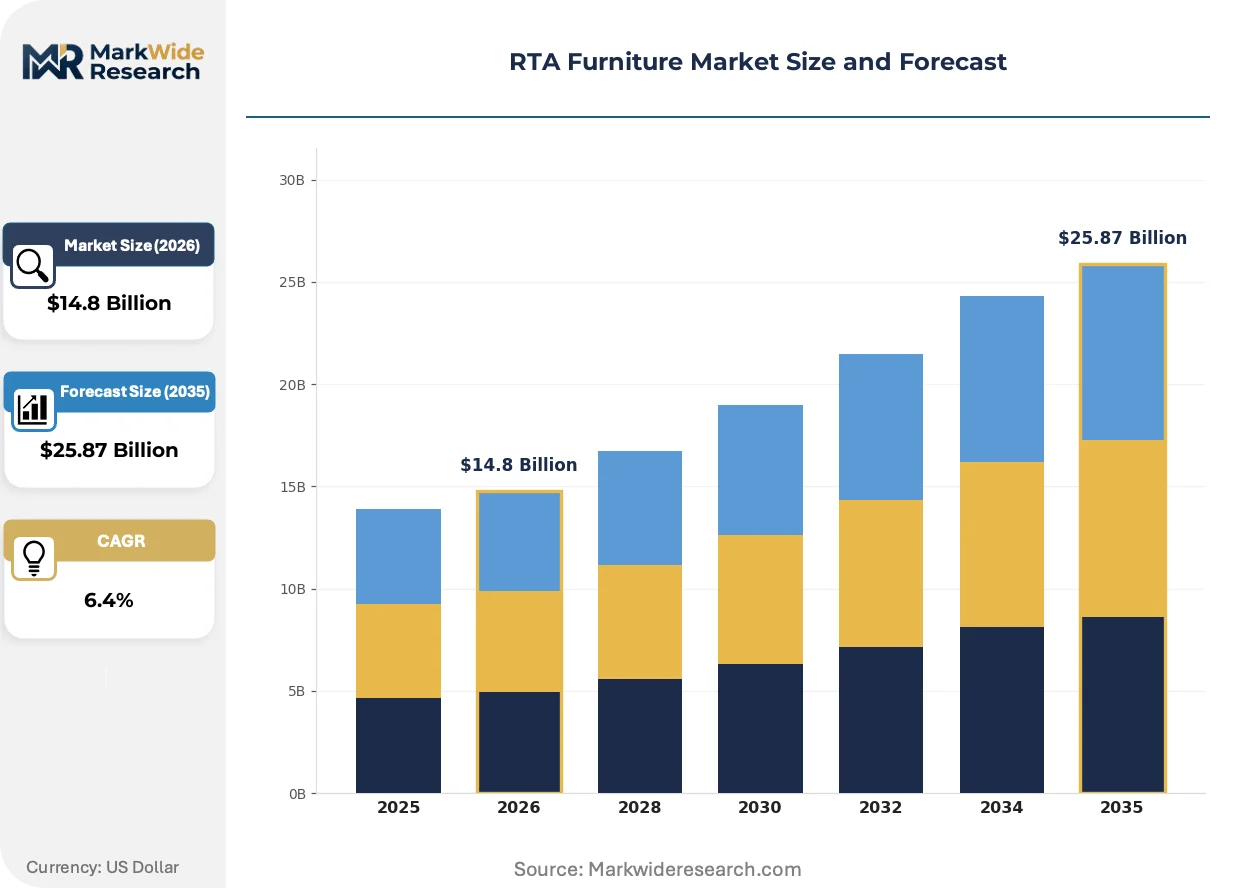
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Chairs, Cabinets, Sofas Material: Wood, Metal, Plastic, Glass End User: Residential, Commercial, Educational, Hospitality Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Steinhoff International, Ashley Furniture Industries, Inter IKEA Systems B.V., BESTAR Inc., Home Reserve LLC, Sauder Woodworking Co., Tvilum A/S, South Shore Industries Ltd., Dorel Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTA Furniture Market Strategic Shifts & Innovations
Digital tools are collapsing the distance between factory floor and living room, reconfiguring how technical specifications travel and how assembly competence gets transferred to end users.
CNC nesting software is virtualizing production planning across contract furniture manufacturers. Hospitality procurement teams specify dimensional constraints through cloud-based configurators that generate machine-ready cut files. This compression of specification-to-fabrication workflow eliminates traditional sampling cycles and reduces engineering overhead for custom batch sizes below fifty units.
REACH SVHC candidate list expansion is forcing laminate suppliers to reformulate melamine resin systems. Decorative surface producers must now document substance-of-very-high-concern absence across adhesive layers and overlay papers. German kitchen retailers are responding by demanding full material passports from RTA cabinet importers, shifting compliance verification upstream to manufacturing origin.
Direct-to-consumer fulfillment is fragmentizing traditional wholesale relationships. Residential buyers now expect unboxing experiences with QR-linked video instructions rather than printed diagrams. This channel bypass is most pronounced in North American metro markets where warehouse-club floor space constraints have pushed bulky furniture categories exclusively online, with tactile evaluation deferred to augmented reality preview tools.
RTA Furniture Market Segmentation
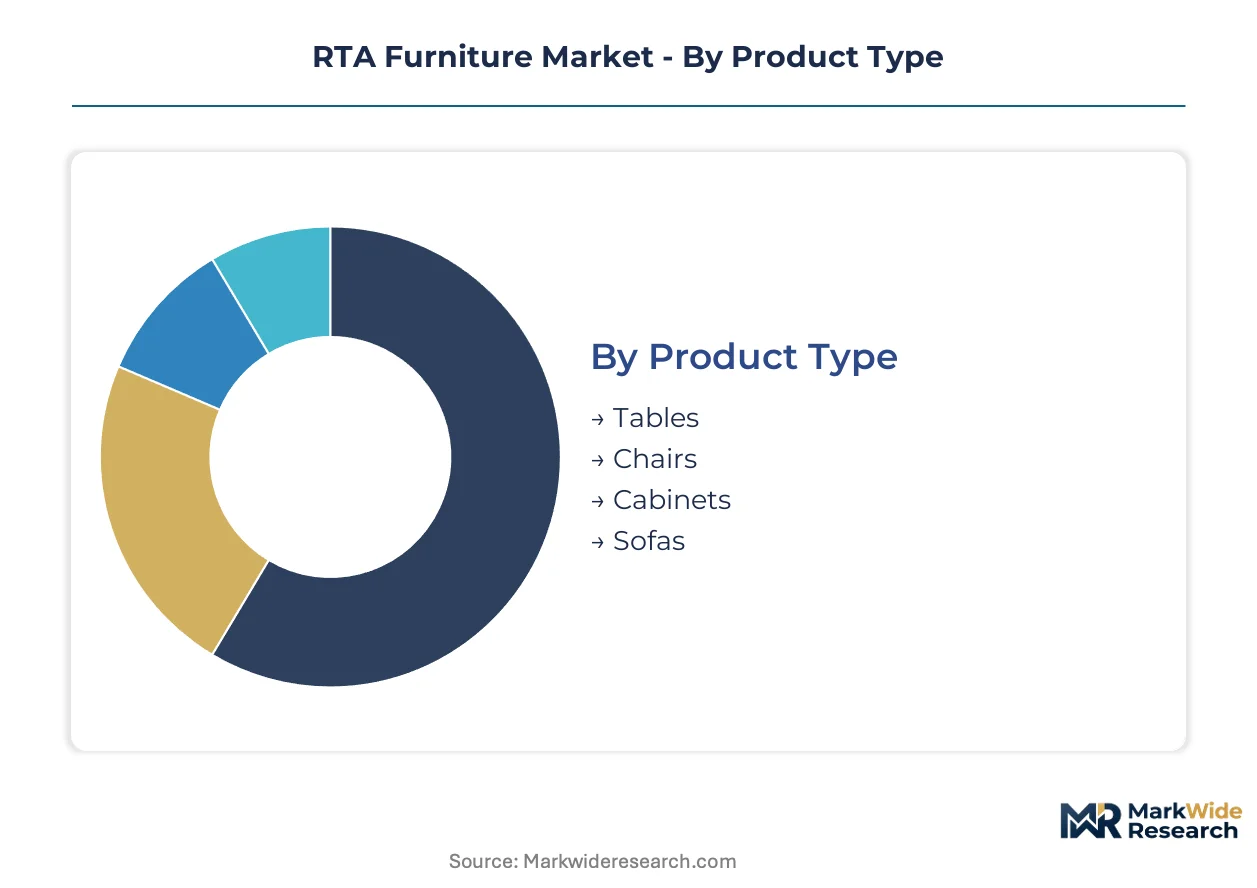
RTA furniture segmentation reveals how flat-pack logistics, material science, and channel economics intersect to serve divergent buyer workflows. Product architecture and substrate selection determine freight density and assembly complexity. End-use context and distribution path shape margin capture and brand positioning.
Product Type:
Use-case spectrum spans compact occasional furniture through large-format storage systems, with dimensional constraints dictating flat-pack viability and last-mile handling protocols.
- Tables:Dining and workspace surfaces utilize honeycomb-core construction to minimize shipping cube while maintaining planar rigidity. Demand concentrates in North American urban apartments where relocation frequency rewards knockdown portability.
- Cabinets:Storage systems employ cam-lock panel joints and adjustable shelf standards, enabling modular height and width configurations. Commercial fit-out contractors in Germany favor certified emission-grade particleboard for office installations subject to workplace air quality audits.
- Chairs:Seating frames ship as disassembled leg-seat-shell kits with hardware pouches, optimizing container stowage density.
- Sofas:Upholstered frames in knockdown form require vacuum-compressed cushion packaging, limiting this segment to premium logistics networks.
Established volume favors cabinets; emerging adoption favors tables.
Material:
Substrate economics separate freight-optimized engineered wood from durability-driven metal and aesthetic-driven glass alternatives.
- Wood:Particleboard and MDF with melamine laminate dominate residential volume shipments due to machinability and cost structure. CARB Phase II certification operates as a de facto North American entry requirement, compressing supplier viability to mills with third-party laboratory relationships.
- Metal:Tubular steel and aluminum extrusions serve hospitality seating and outdoor applications where moisture exposure disqualifies wood substrates. Powder-coat finishing lines in Turkey and Vietnam supply European retailers with REACH-compliant surface treatments.
- Plastic:Injection-molded polypropylene components appear in juvenile furniture and utility shelving where color consistency and impact resistance outweigh surface warmth.
- Glass:Tempered panel inserts in display cabinets and occasional tables require specialized corner protection packaging, constraining this substrate to premium price tiers.
Wood commands shipment volume; metal captures hospitality margins.
End User:
Buyer procurement protocols range from individual online transactions through institutional tender processes with extended qualification cycles.
- Residential:Individual purchasers prioritize freight cost minimization and assembly simplicity, driving demand for sub-50-pound carton weights and QR-linked video instructions.
- Commercial:Corporate procurement officers specify batch consistency and warranty terms for office fit-outs, favoring suppliers with domestic assembly facilities for damage liability containment.
- Educational:School district purchasing cooperatives aggregate volume across multiple institutions, rewarding manufacturers with configurable dimension ranges and extended payment terms.
- Hospitality:Hotel operators source guest room packages through procurement consortia, requiring fire-rated materials and accelerated replacement part availability.
Residential channels drive unit velocity; hospitality contracts yield contract manufacturing stability.
Distribution Channel:
Channel selection determines tactile evaluation access, return logistics burden, and customer acquisition cost structure.
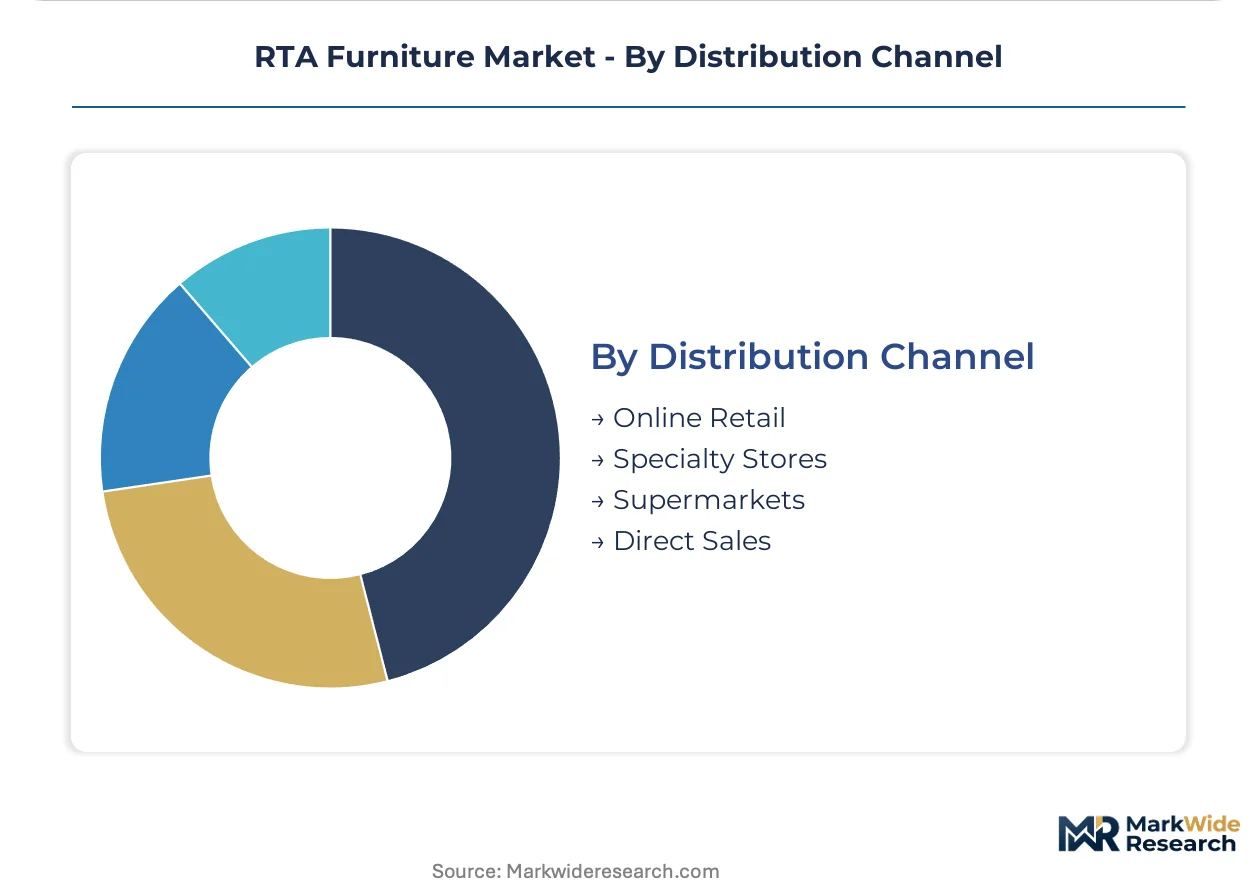
- Online Retail:Digital marketplaces capture urban millennial demand through augmented reality preview tools and compressed delivery windows. Return rates for large-format items exceed specialty store benchmarks, absorbing margin through reverse logistics costs.
- Specialty Stores:Dedicated furniture retailers sustain attachment rates for complex assemblies through floor model evaluation and white-glove delivery upsells.
- Supermarkets:Mass merchants move seasonal RTA collections through high-velocity floor displays, limiting assortment depth to best-selling SKUs with proven assembly completion rates.
- Direct Sales:Manufacturer-owned channels capture full margin but require captive fulfillment infrastructure, viable primarily for vertically integrated producers with regional warehouse density.
Online retail expands fastest; specialty stores defend large-ticket conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's flat-pack import capacity, while China's Ningbo-Zhoushan port complex anchors Asia-Pacific export volumes. These maritime gateways determine freight economics for knockdown furniture distribution.
United States
EPA TSCA Title VI governs composite wood formaldehyde emissions nationwide, creating uniform compliance obligations for domestic and imported RTA products. California's CARB Phase II standards operate as the de facto North American benchmark, with most distributors voluntarily meeting these stricter thresholds to avoid SKU fragmentation. Ohio's manufacturing corridor hosts domestic particleboard production serving midwestern retail distribution networks.
Germany
The EU Ecodesign Directive imposes sustainability disclosure requirements on furniture placed within the European single market, mandating recycled-content documentation. Extended producer responsibility frameworks in France and Germany reshape packaging and end-of-life obligations for RTA importers. The country's furniture retail clusters in North Rhine-Westphalia drive demand for certified low-emission particleboard in commercial fit-out applications.
China
Dongguan's integrated supplier ecosystems compress procurement lead times and tooling costs for export-oriented RTA producers serving European and North American retailers. The country's dual carbon goals pressure manufacturing clusters to decarbonize energy-intensive particleboard pressing operations. Ningbo's port infrastructure and bonded logistics zones facilitate containerized knockdown shipments to trans-Pacific markets.
India
Metro apartment dwellers in Mumbai and Bangalore favor space-efficient flat-pack solutions that navigate narrow elevator shafts and stairwells during relocation. BIS certification requirements for furniture safety standards create compliance entry barriers for imported RTA products. The Delhi-NCR corridor's warehousing expansion supports e-commerce fulfillment infrastructure for online furniture retail.
Vietnam
Powder-coat finishing lines in northern industrial zones supply European retailers with REACH-compliant metal frame treatments for hospitality seating. The country's laminate surface paper mills concentrate decorative supply for regional RTA assembly operations. Ho Chi Minh City's port modernization reduces transit times to European distribution hubs.
RTA Furniture Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying engineered substrates and hardware to branded assemblers. The RTA furniture sector exhibits tiered consolidation, with a handful of vertically integrated retailers controlling premium channel access while numerous regional fabricators compete on cost-engineered particleboard variants. Three archetypes dominate: captive retail platforms with store-and-click infrastructure, contract manufacturers serving hospitality procurement consortia, and domestic-scale woodworkers leveraging proximity for damage liability containment. Competitive intensity centers on M&A-driven geographic expansion and backward integration into particleboard milling to secure emission-grade substrate supply.
Among the named entities in this study, Inter IKEA Systems B.V. and Sauder Woodworking Co. occupy positions reflecting divergent strategic postures. The former exemplifies platform-scale retail integration with captive fulfillment infrastructure spanning multiple continents. The latter represents domestic manufacturing scale anchored in Ohio production facilities. Dorel Industries Inc. sits within a specialized tier focused on juvenile and home office RTA lines, demonstrating vertical control over category-specific product development. These three entities illustrate how competitive positioning in RTA furniture maps to distribution architecture and manufacturing geography rather than singular technology differentiation.
| Leading Market Players |
|---|
| Steinhoff International |
| Ashley Furniture Industries |
| Inter IKEA Systems B.V. |
| BESTAR Inc. |
| Home Reserve LLC |
| Sauder Woodworking Co. |
| Tvilum A/S |
| South Shore Industries Ltd. |
| Dorel Industries Inc. |
| Others |
Cost & Logistics Intelligence
Dongguan's manufacturing cluster capacity dynamics compress tooling costs for export-oriented producers, translating into downstream pricing power for retailers controlling captive fulfillment infrastructure across North American and European markets. CARB Phase II certification requirements fragment supplier viability, allowing certified mills to command margin premiums over uncertified competitors serving price-sensitive residential channels.
Pricing Analysis
Volume-discount tiering structures separate hospitality procurement consortia from individual residential buyers, with contract manufacturers capturing stable margins through multi-year replacement part agreements while direct-to-consumer brands absorb return logistics costs. Price differentiation hinges on emission-grade certification status and domestic assembly proximity, with EPA TSCA Title VI compliance creating tiered entry barriers. Pricing pressure stems from resin input volatility tied to natural gas feedstock costs, compressing particleboard-dependent manufacturers. Commercial fit-out contractors exhibit lowest price sensitivity due to workplace air quality audit requirements, while mass-market residential buyers prioritize sub-50-pound carton weights and freight minimization.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for flat-pack furniture importers, forcing contingency planning around Vietnam and Turkey powder-coat finishing alternatives. Raw material dependencies center on urea-formaldehyde binders, Southeast Asian decorative surface paper mills, and engineered wood substrates from Guangdong Province mills. Single-source laminate concentration exposes finished goods producers to freight surge vulnerability during peak shipping seasons. Distribution runs through containerized knockdown shipments via Ningbo-Zhoushan port complex, with last-mile fragmentation accelerating direct-to-consumer bypass of traditional wholesale layers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified low-emission particleboard supply constrains market entry for new competitors, privileging incumbents with established third-party laboratory relationships and backward integration into substrate milling.
For Market Incumbents: Entrench market position by securing captive supply of CARB Phase II certified particleboard through upstream mill partnerships or in-house production investments, while expanding augmented reality assembly guidance to reduce customer service burden and defend against digital-native entrants. Channel control through store-and-click infrastructure remains the priority lever for margin capture. For New Entrants and Emerging Players: India's metro apartment corridors in Mumbai and Bangalore offer underpenetrated white-space for space-efficient flat-pack solutions navigating narrow elevator shafts, with BIS certification requirements creating defensible moats against low-cost imports. Target educational procurement cooperatives aggregating volume across multiple institutions, leveraging configurable dimension ranges and extended payment terms as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because competitive intensity centers on M&A-driven geographic expansion and backward integration into emission-grade substrate supply, with contract manufacturers serving hospitality procurement consortia representing the most stable cash flow archetype. Monitor EPA TSCA Title VI certification queue times as the inflection indicator for product launch velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Particleboard Milling | Secures CARB Phase II certified substrate supply against emission-grade scarcity. |
| Augmented Reality Assembly Deployment | Reduces return rates for complex cabinet configurations sold through digital channels. |
| Direct-to-Consumer Fulfillment Buildout | Captures full margin bypassing traditional wholesale relationships in North American metros. |
| REACH-Compliant Metal Frame Expansion | Opens hospitality seating contracts requiring European regulatory compliance. |
| Educational Procurement Cooperative Targeting | Aggregates volume across institutions with configurable dimensions and extended terms. |
Research Approach
Desk research of customs trade data, EPA TSCA Title VI certification registries, and EU Ecodesign Directive disclosure frameworks preceded structured interviews with RTA furniture procurement officers at hospitality consortia, plant managers at Guangdong Province manufacturing clusters, and category buyers at North American mass merchants. Primary fieldwork with logistics coordinators at Ningbo-Zhoushan port and laminate suppliers in Southeast Asian mills combined with secondary validation against SEC filings from vertically integrated retailers. Bottom-up shipment volume analysis triangulated against top-down market sizing from trade association aggregates.
Assumptions held fixed include prevailing CARB Phase II and EPA TSCA Title VI emission standards, existing tariff schedules between China and the United States, and continued e-commerce penetration rates across the analysis window. The analytical framework modeled segmentation across product type, material substrate, end-user procurement protocol, and distribution channel. CAGRs derived from regression analysis of historical shipment volumes against macroeconomic indicators. Industry-specific inputs included urea-formaldehyde binder price indices and containerized freight rate volatility from trans-Pacific lanes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Dongguan manufacturing clusters or sudden laminate mill consolidation would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Poland Home Furniture Market
Furniture
Kids Furniture Market
Furniture
Europe Upholstered Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Italy Furniture Market
Furniture
Europe Home Furniture Market
Furniture
Chair Hardware Market
Furniture
UAE Home Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Italy Luxury Furniture Market
Furniture
Children Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Entryway Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Piano Stools Market