
 GCC Luxury Furniture Market | 2026-2036
GCC Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Luxury Furniture Market Foresight
The gap between artisan-crafted luxury furniture and mass-market commodity pieces is repositioning procurement standards across Gulf markets. Luxe Living anchors its competitive stance through captive upholstery workshops in Sharjah. Danube differentiates via its integrated design-to-delivery model spanning Saudi Arabia and the UAE. Al Huzaifa sustains brand equity through three decades of bespoke woodwork heritage centered in Abu Dhabi.
GCC luxury furniture comprises high-specification interior furnishings engineered from premium hardwoods, exotic veneers, hand-finished metals, and full-grain leathers, typically manufactured through CNC-assisted joinery combined with hand-applied finishing techniques to achieve durability ratings exceeding residential-grade standards by substantial margins. Seating and tables command the dominant share of material value given their centrality to spatial design narratives in both residential estates and luxury hotels. Wood and marble configurations attract the strongest margin premiums due to scarcity-driven raw material costs and the labor intensity of hand-polishing and grain-matching processes.
SASO in Saudi Arabia and the UAE's ECAS conformity framework govern product safety, flammability standards, and chemical emissions for imported furnishings, effectively filtering out lower-grade suppliers from European and Asian export bases. Dubai Municipality's green building regulations and Qatar's GSAS certification for hospitality projects increasingly mandate sustainable timber sourcing and low-VOC finishes, reshaping supplier qualification criteria. Stakeholders must monitor evolving conformity timelines across multiple Gulf standardization bodies to avoid customs delays and project slippage.
Market Dynamics
Luxury hospitality fit-outs in Dubai and Riyadh are compressing project timelines and elevating material specifications simultaneously. Hoteliers now mandate bespoke interiors with hand-finished surfaces, forcing suppliers to reconfigure workshop capacity and certification portfolios.
Growth Catalysts
- SASO quality mark:Saudi Arabia's tightening material sourcing standards filter out lower-grade European and Asian suppliers, creating premium positioning for certified manufacturers.
- Dubai Hills and Saadiyat Island clusters:Concentrated premium residential development in the UAE generates sustained procurement volumes for high-specification furnishings.
- CNC-assisted joinery:Precision manufacturing technology enables shorter production cycles for complex woodwork while maintaining hand-applied finishing quality.
Market Restraints
- Exotic veneer scarcity:Rare hardwood sourcing constraints from Southeast Asian and African supply bases inflate raw material costs unpredictably.
- Sharjah workshop concentration:Captive upholstery capacity clusters in a single emirate, creating geographic vulnerability for UAE-based supply chains.
- ECAS conformity timelines:UAE's mandatory product conformity scheme extends customs clearance periods for European imports, delaying project schedules.
Strategic Opportunities
- Qatar GSAS certification:Hospitality projects in Doha mandate sustainable timber sourcing and low-VOC finishes, opening qualification pathways for certified suppliers.
- Riyadh residential estates:Underpenetrated premium housing segments in Saudi Arabia's capital present expansion targets beyond Dubai's saturated clusters.
- Design-to-delivery integration:Consolidated project management models spanning Saudi Arabia and the UAE reduce handoff friction between architects and installers.
Industry Challenges
- Master grain-matching craftsmanship:Hand-polishing and veneer alignment skills face generational transfer gaps as veteran artisans retire from Abu Dhabi workshops.
- Multi-jurisdiction conformity tracking:SASO, ECAS, and GSAS operate on divergent renewal cycles, forcing compliance teams to monitor three separate standardization bodies.
- Legacy finishing chemistry:Traditional solvent-based coatings require reformulation to meet Dubai Municipality's green building regulations without compromising durability ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Luxury Furniture Market |
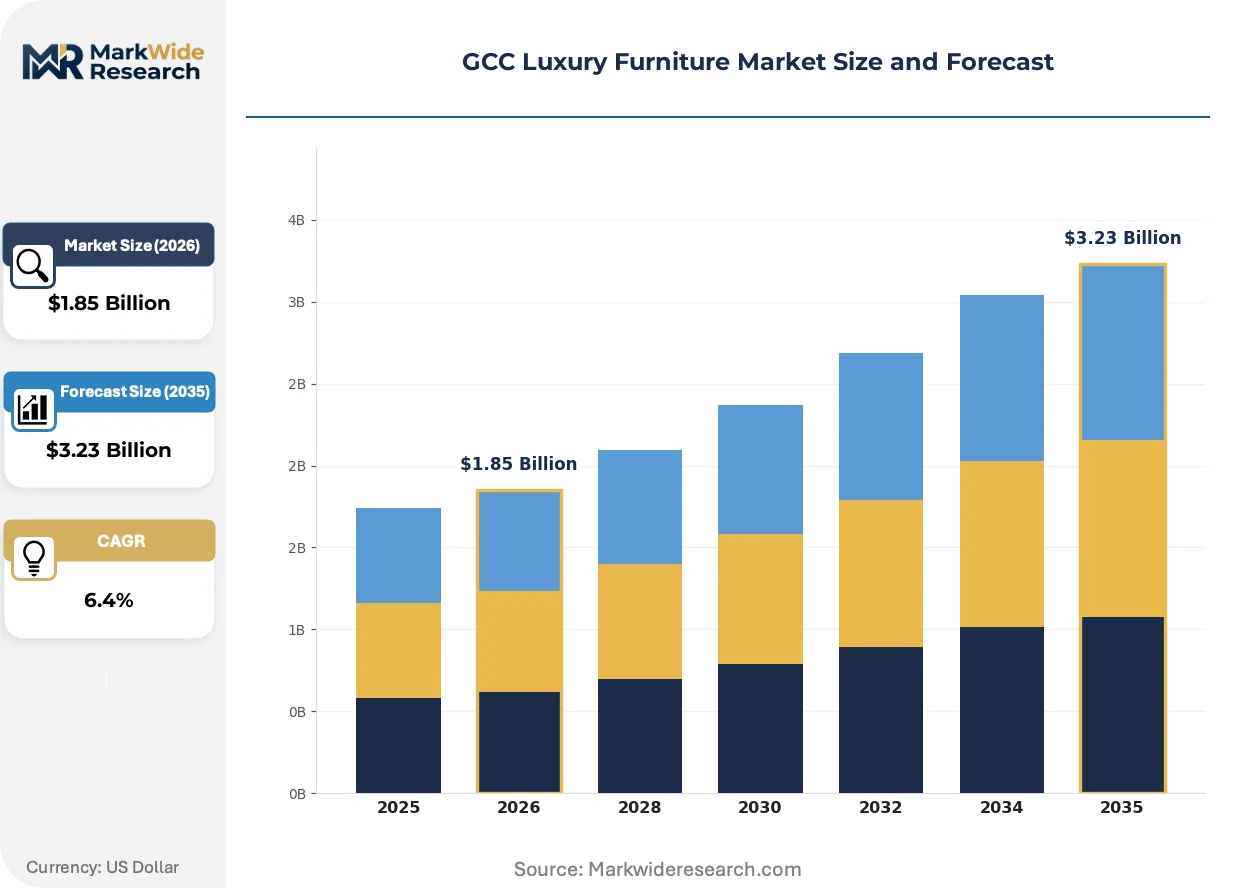
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Storage Units, Beds, Cabinets, Dressers Material: Wood, Metal, Glass, Marble, Leather, Fabric Application: Residential Estates, Luxury Hotels, Executive Offices, High-End Restaurants, Yacht Interiors Customer Type: Property Developers, Interior Designers, Hospitality Chains, Corporate Clients, Private Collectors |
| Companies Covered | Luxe Living, Daze Furniture, PAN Emirates, Next Space, Pan Emirates Home Furnishings, IKEA, Danube, Auraliving, Al Huzaifa, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Luxury Furniture Market Shifts & Advancements
Digital fabrication and sustainability mandates are restructuring how luxury furniture reaches Gulf markets. Suppliers must now reconcile artisan heritage with precision manufacturing and environmental compliance.
Water-based UV-curable coatings are expanding into high-traffic hospitality applications previously reserved for solvent-based systems. Five-star hotel operators in Dubai and Riyadh specify these finishes for lobby and suite furniture to meet GSAS and green building requirements. The technology is expanding into residential segments as developers market wellness-oriented interiors to health-conscious buyers.
Dubai Municipality's green building regulations now mandate chain-of-custody documentation for all timber used in commercial interiors. Project consultants must verify FSC or PEFC certification before furniture installation, adding procurement steps but filtering out uncertified suppliers. Hospitality fit-outs face the strictest enforcement, with municipal inspectors rejecting deliveries lacking proper documentation.
Direct commissioning from design studios is displacing traditional showroom-based purchasing for ultra-high-net-worth residential clients. Architects in Abu Dhabi's Saadiyat Island cluster now specify bespoke pieces through captive workshops rather than retail channels. This pattern concentrates margin capture with integrated manufacturers while reducing distributor roles in the most profitable segment.
GCC Luxury Furniture Market Segmentation
Luxury furniture procurement in the GCC follows distinct patterns across product categories, material specifications, and end-use applications. Understanding these divisions reveals where capital deployment concentrates and which customer segments command premium pricing power.
Product Type:
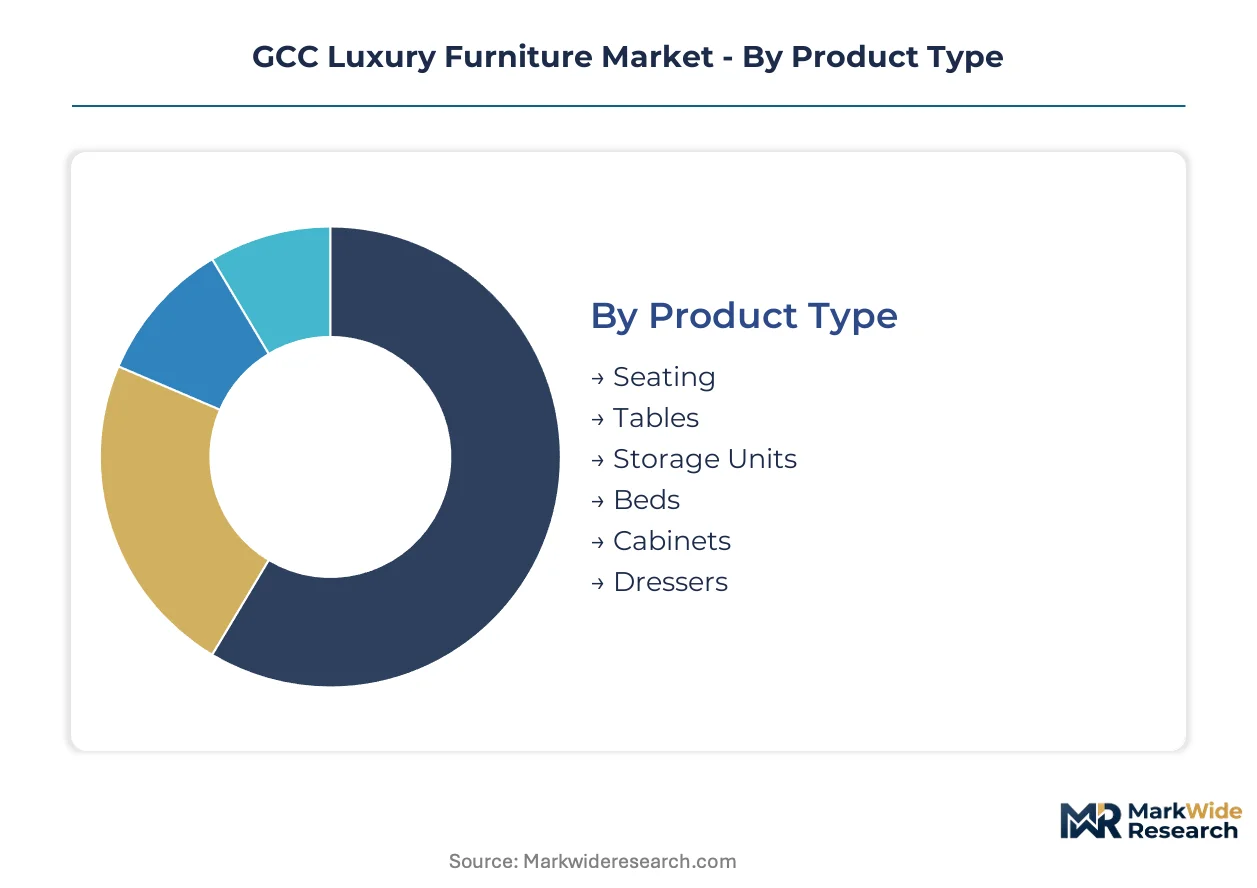
Capital intensity varies sharply across furniture categories, with seating and tables absorbing the largest upfront tooling investments for CNC joinery and hand-finishing workshops.
- Seating:Engineered frames combine kiln-dried hardwoods with multi-density foam cores and full-grain leather or performance fabric upholstery. Demand clusters in Dubai Hills and Saadiyat Island residential estates where developers specify custom sectionals and accent chairs for show villas.
- Tables:Dining and occasional tables require precision-machined substrates with hand-applied veneer matching and catalyzed finish systems. Riyadh's luxury hospitality fit-outs drive procurement of large-format conference and banquet tables with stone inlay surfaces.
- Storage Units:Built-in millwork and freestanding case goods serve residential and commercial installations across the UAE and Saudi Arabia.
- Beds:Upholstered headboards and platform frames target premium residential developments with wellness-oriented positioning.
- Cabinets:Display and bar cabinets concentrate in private collector commissions and executive office fit-outs.
- Dressers:Bedroom storage furniture aligns with boutique hotel procurement cycles in Doha and Riyadh.
Most installed capacity flows through Seating. Expansion is steepest in Tables.
Material:
Raw material sourcing costs determine margin structures, with exotic hardwoods and stone commanding the highest working capital requirements for inventory and quality verification.
- Wood:Premium hardwoods including walnut, oak, and mahogany sourced through FSC-certified supply chains undergo CNC machining and hand-sanding before finishing. Dubai Municipality's chain-of-custody mandates filter out uncertified suppliers for commercial interiors.
- Marble:Calacatta, Statuario, and regional limestone varieties require specialized cutting equipment and moisture-controlled fabrication facilities. Qatar's GSAS certification for hospitality projects specifies low-carbon stone sourcing, reshaping supplier qualification.
- Metal:Brass, bronze, and stainless steel components serve structural and decorative functions across seating and table categories.
- Leather:Full-grain and aniline hides from European tanneries supply upholstery workshops in Sharjah with consistent dye lots.
- Fabric:Performance textiles including mohair, silk blends, and solution-dyed acrylics meet durability ratings for high-traffic hospitality applications.
- Glass:Tempered and laminated glass elements integrate into tabletops and display cases for residential and commercial segments.
Wood commands the largest share of material value. Marble is climbing the fastest as hospitality specifications elevate stone content.
Application:
Project scale and specification intensity create divergent procurement patterns, with hospitality fit-outs demanding the most complex compliance documentation and residential estates offering the longest production timelines.
- Luxury Hotels:Bespoke interiors for five-star properties in Dubai and Riyadh require hand-finished surfaces, custom dimensions, and coordinated installation with MEP contractors. SASO quality mark and ECAS conformity schemes extend procurement lead times but filter competition to certified manufacturers.
- Residential Estates:Ultra-high-net-worth clients in Abu Dhabi's Saadiyat Island cluster commission direct from design studios rather than retail channels, concentrating margin with integrated manufacturers.
- Executive Offices:Corporate headquarters and private family offices in Riyadh and Dubai specify statement pieces with integrated technology and concealed storage.
- High-End Restaurants:F&B operators prioritize durability and rapid turnaround for seating replacement cycles.
- Yacht Interiors:Marine-grade materials and space-optimized dimensions serve superyacht fit-outs in Dubai and Doha shipyards.
Luxury Hotels absorb the majority of certified production capacity. Residential Estates are gaining share fastest through direct commissioning models.
Customer Type:
Buyer sophistication and procurement authority shape pricing power, with hospitality chains and property developers leveraging volume scale against interior designers and private collectors who prioritize exclusivity over unit economics.
- Property Developers:Master developers of premium residential communities in Dubai Hills and Saadiyat Island issue bundled furniture packages for show villas and common areas, driving standardized specifications across multiple units.
- Interior Designers:Independent and studio-based designers in Abu Dhabi and Riyadh specify bespoke pieces through captive workshops, capturing margin that would otherwise flow to distributors.
- Hospitality Chains:International and regional hotel operators mandate global brand standards with local adaptation for GCC properties.
- Corporate Clients:Sovereign wealth funds and family offices commission executive furnishings with extended durability warranties.
- Private Collectors:Individual buyers acquire one-off artisan pieces through direct relationships with Abu Dhabi woodwork heritage workshops.
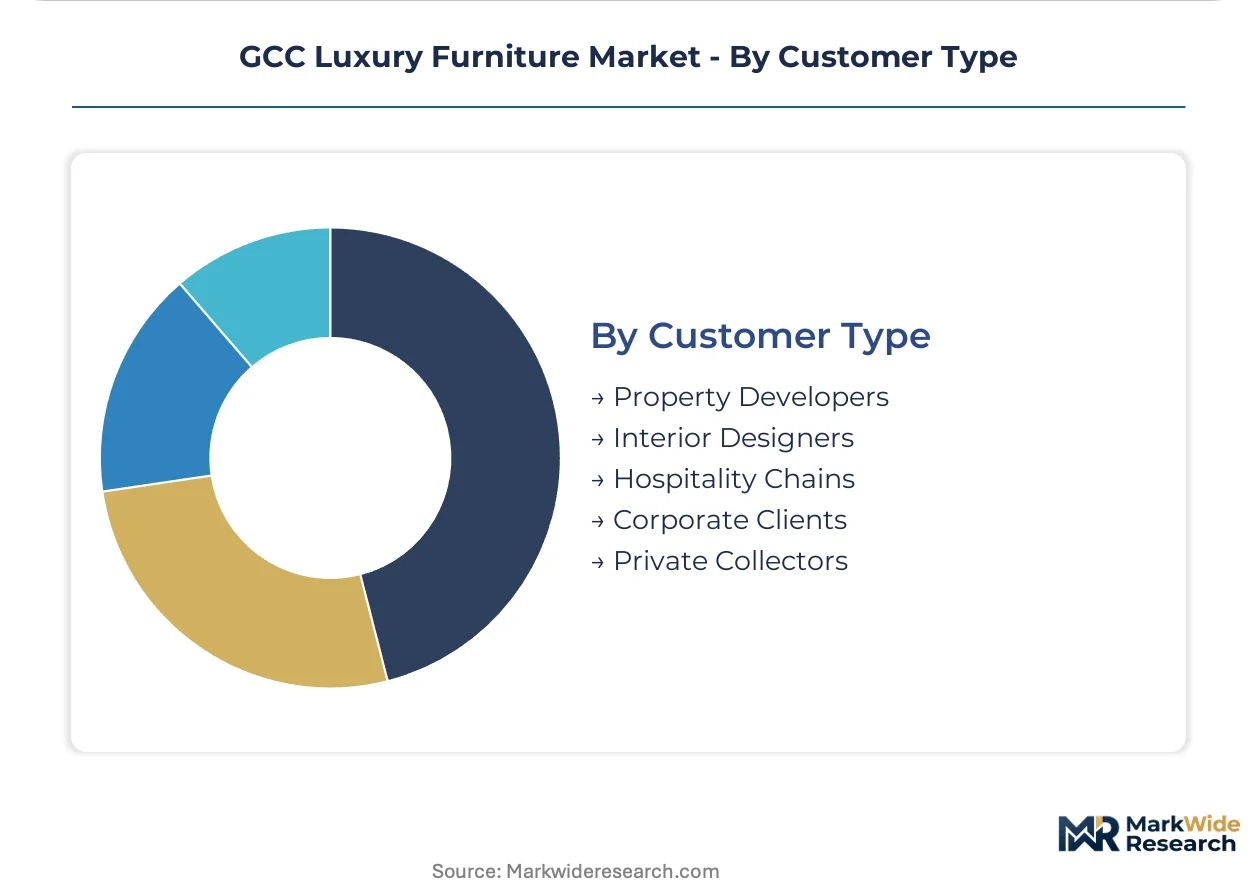
Property Developers channel the largest procurement volumes. Interior Designers are expanding their share fastest as direct commissioning displaces retail purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands larger procurement volumes than the UAE, yet Dubai's concentrated luxury developments sustain higher per-project specification intensity across hospitality and residential segments.
United Arab Emirates
Dubai Hills and Saadiyat Island clusters drive sustained demand for bespoke seating and hand-finished tables. Dubai Municipality's green building regulations mandate FSC-certified timber chain-of-custody documentation for commercial interiors. Sharjah hosts captive upholstery workshops supplying precision-manufactured components to developers across the emirates.
Saudi Arabia
Riyadh's luxury hospitality fit-outs and underpenetrated premium residential estates generate expanding procurement volumes. SASO quality mark requirements filter out uncertified European and Asian suppliers, elevating compliance barriers for market entry. The capital's hotel development pipeline compresses project timelines while mandating bespoke interior specifications.
Qatar
Doha's hospitality sector demands GSAS-certified furnishings with sustainable timber sourcing and low-VOC finishes. The country's national standardization body enforces strict emissions criteria for imported furniture. Municipal inspectors reject deliveries lacking proper environmental documentation, reshaping supplier qualification pathways.
Kuwait
Private residential commissions and executive office fit-outs sustain demand for artisan-crafted woodwork with extended durability warranties. The country's national quality authority maintains product safety standards for imported furnishings. Kuwait City concentrates procurement authority among sovereign wealth funds and family offices commissioning statement pieces.
Bahrain
Boutique hotel developments and high-end restaurant fit-outs prioritize rapid-turnaround seating replacement cycles. The national regulator oversees flammability standards and chemical emissions for hospitality furnishings. Manama's compact geography enables consolidated logistics for suppliers serving cross-border projects from Saudi Arabia and the UAE.
GCC Luxury Furniture Market Competitive Landscape
Top-tier vendors anchor integrated design-to-delivery models, while mid-scale fabricators compete on workshop specialization and geographic proximity to project clusters. The vendor base separates into three functional tiers: heritage woodwork houses with multi-decade track records, precision manufacturers leveraging CNC-assisted production, and diversified home furnishing conglomerates spanning multiple price points. Consolidation pressures favor players with captive upholstery capacity and multi-jurisdiction certification portfolios. Strategic moves center on workshop capacity expansion in Sharjah and Riyadh, plus backward integration into certified timber sourcing.
Among UAE-based heritage specialists, Al Huzaifa exemplifies the artisan-crafted archetype through its Abu Dhabi-centered bespoke woodwork operations. Luxe Living occupies a position within the integrated manufacturing tier, with its Sharjah-based captive upholstery workshops supplying precision-finished components. Danube represents the diversified conglomerate model, spanning Saudi Arabia and the UAE through consolidated project management capabilities. These three players illustrate how competitive positioning stratifies across craftsmanship heritage, manufacturing scale, and geographic reach.
| Leading Market Players |
|---|
| Luxe Living |
| Daze Furniture |
| PAN Emirates |
| Next Space |
| Pan Emirates Home Furnishings |
| IKEA |
| Danube |
| Auraliving |
| Al Huzaifa |
| Others |
Supply & Pricing Matrix
Dubai Municipality's green building regulations gate qualified supply and premium-tier pricing access by mandating FSC-certified timber chain-of-custody documentation for commercial interiors. Certified manufacturers capture margin premiums while uncertified competitors face customs rejection and project disqualification.
Pricing Analysis
Capacity additions in Sharjah are reshaping price floors for upholstered seating components. Three-tier pricing structure across certified artisan, precision-manufactured, and commodity import levels separates buyers by specification intensity. Price differentiation rests on SASO certification status and hand-finishing labor content. Cost compression in standard-grade imports is intensifying because European suppliers face extended ECAS conformity timelines.
Supply Chain Analysis
ECAS and SASO certification requirements filter supplier participation before goods reach Gulf ports. Raw material sourcing draws from Southeast Asian hardwood forests, Italian tanneries for full-grain leather, and Carrara basin quarries for stone inlays. Single-source vulnerability concentrates in Sharjah's captive upholstery workshops. Distribution runs through project-direct channels for hospitality fit-outs and design-studio commissioning for residential estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GCC luxury furniture hinges on certified timber sourcing scale and direct commissioning capture from ultra-high-net-worth residential clients.
For Market Incumbents: Hedge against exotic veneer scarcity by securing multi-year FSC-certified supply agreements with Southeast Asian forest concessions. Expand captive finishing capacity in Riyadh to compress logistics exposure from single-emirate concentration in Sharjah. For New Entrants and Emerging Players: GSAS certification in Qatar opens a window for qualified suppliers to capture hospitality procurement in Doha's hotel development pipeline. Target underpenetrated premium residential estates in Riyadh through architect-direct relationships rather than retail channel buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators with workshop specialization but incomplete certification portfolios. Long-term viability favors integrated design-to-delivery models spanning Saudi Arabia and the UAE. Monitor SASO quality mark renewal timelines as an inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Timber Backward Integration | FSC-certified forest concessions in Southeast Asia secure raw material access for Dubai and Riyadh project pipelines. |
| Multi-Jurisdiction Certification Investment | Simultaneous SASO, ECAS, and GSAS qualification reduces customs friction across Saudi Arabia, UAE, and Qatar. |
| Captive Upholstery Capacity Expansion | Sharjah workshop clusters enable precision-manufactured component supply for Saadiyat Island residential developments. |
| Design-to-Delivery Model Consolidation | Integrated project management spanning Saudi Arabia and UAE reduces architect-to-installer handoff friction. |
| Water-Based UV Coating Transition | Low-VOC finish systems meet Dubai Municipality green building regulations for hospitality lobby specifications. |
Research Methodology
Direct dialogue with furniture manufacturing executives, hospitality procurement directors, interior design studio principals, and municipal building inspectors grounded qualitative findings. Secondary validation drew from Dubai Municipality regulatory filings, SASO technical regulations, GSAS certification databases, and timber trade customs records. Bottom-up project pipeline assessment and top-down spending pattern analysis were triangulated.
Bottom-up modeling tracked hospitality fit-out timelines and residential development completions across the analysis window. Segmentation dimensions included product category, material specification tier, application intensity, and customer procurement authority. CAGRs were derived from installed capacity expansion rates and specification upgrade trajectories. Forecast inputs incorporated CNC joinery adoption curves and artisan workforce demographics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under exotic hardwood export restrictions or accelerated green building mandate enforcement. A model refresh is warranted upon material change in GCC standardization body conformity timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
US School Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Recliner Chair Market
Furniture
Ergonomic Chair for Children Market
Furniture
India Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Lecterns Market
Furniture
GCC Home Furniture Market
Furniture
Brazil Furniture Market
Furniture
Wooden Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Chaises Longue Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Russia Home Furniture Market
Furniture
Spain Furniture Market
Furniture
Asia-Pacific Contract Furniture Market